Europe 3D ICs Market Outlook
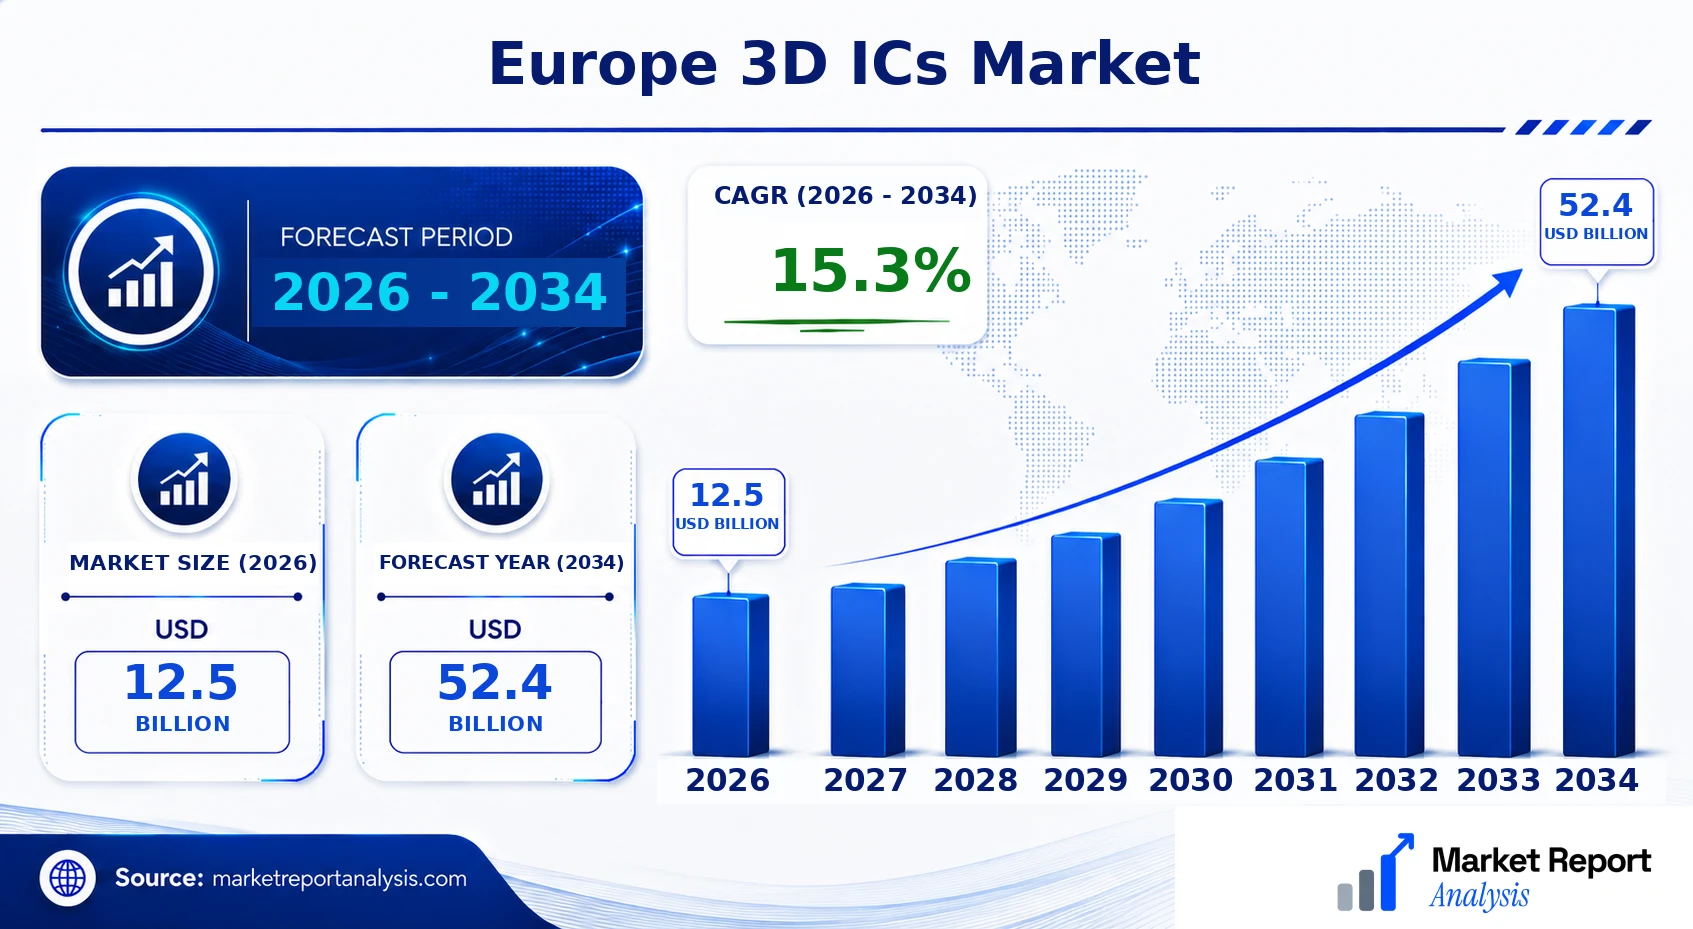
The Europe 3D ICs market is experiencing robust growth driven by the rapid adoption of advanced semiconductor packaging technologies, the surging demand for high-performance computing devices, and the increasing integration needs within the consumer electronics, automotive, and industrial sectors. In 2026, the market is valued at USD 12.5 Billion, with projections to reach USD 52.4 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of approximately 15.3% over the forecast period from 2026 to 2034. Technological advancements in 3D stacking and through-silicon vias (TSVs) are facilitating the development of more efficient, smaller, and faster electronic components. Additionally, the expanding automotive electronics sector and the rise of Internet of Things (IoT) applications are acting as key drivers for market expansion. Several leading semiconductor manufacturing companies are investing heavily in R&D to enhance 3D IC performance and reduce manufacturing costs, opening new commercial opportunities in Europe’s competitive market landscape.
What is the Europe 3D ICs Market Size?
The 2026 market size for Europe 3D ICs is estimated at USD 12.5 Billion, with an expected growth to USD 52.4 Billion by 2034. This growth corresponds to a CAGR of approximately 15.3% during the period from 2026 to 2034. The development of high-density, high-speed electronic devices is fueling demand, especially in high-performance computing, consumer electronics, and automotive sectors. The integration of 3D ICs enhances device miniaturization, power efficiency, and processing speeds, which are increasingly critical in Europe's evolving market landscape. Investments in advanced manufacturing facilities, coupled with governmental support for semiconductor innovation, are further catalyzing growth. Furthermore, the focus on smart mobility and Industry 4.0 initiatives presents significant market expansion opportunities across multiple economies within Europe, including Germany, France, and the UK, which are leading in technology adoption and innovation investments.
Key Takeaways
- The Europe 3D ICs market was valued at USD 2.1 Billion in 2026.
- The market is projected to grow to USD 4.5 Billion by 2034.
- The CAGR from 2026 to 2034 is approximately 11.9%.
- The consumer electronics segment holds the largest share of the market.
- The industrial and automotive sectors are the fastest-growing segments.
- High-performance computing remains the largest application area.
- Automotive applications exhibit the highest growth rate in the forecast period.
- The telecommunications and data centers are significant end users extending market demand.
- Investments in R&D and manufacturing capacity are key to technology advancement.
- European countries like Germany, France, and the UK lead in semiconductor innovation efforts.
- Government initiatives supporting semiconductor ecosystem development bolster market confidence.
- Intensifying competition among global and regional players fuels product innovation and price competitiveness.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the key metrics that define the Europe 3D ICs market. This section presents quantitative data and trends, underlining the market’s growth trajectory and competitive landscape from 2026 through 2034. As the demand for advanced semiconductor solutions escalates, understanding these indicators is crucial for strategic decision-making and investment planning.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 12.5 Billion |
| Market Value (2026) | USD 12.5 Billion |
| Forecast Size (2034) | USD 52.4 Billion |
| CAGR | 15.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Geography |
| Major Companies | ASML Holding, STMicroelectronics, Globalfoundries, AMS AG, Infineon Technologies, NXP Semiconductors, Dialog Semiconductor, Veeco Instruments |
Market Dynamics
The Europe 3D ICs Market is experiencing a transformative period driven by rapid technological advancements, evolving regulatory frameworks, significant investments from industry leaders, and changing customer requirements. Competitive dynamics are intensifying as companies race to develop customizable, high-performance 3D integrated circuits that meet the demand for miniaturization and energy efficiency. Supply chain conditions, raw material prices, and geopolitical influences are also shaping market behavior, compelling firms to innovate and optimize manufacturing processes. This complex interplay of drivers and restraints defines the trajectory of the market, fostering new opportunities while presenting substantial challenges for stakeholders across Europe.
Drivers
Technological Advancements
The continuous evolution of semiconductor manufacturing technology propels the Europe 3D ICs market by enabling denser, faster, and more energy-efficient integrated circuits. Innovations such as through-silicon vias (TSVs) and wafer bonding techniques facilitate stacking multiple IC layers, delivering superior performance for high-end applications like AI, 5G, and autonomous vehicles. European research institutes and industry consortia are pioneering new fabrication processes, supporting a robust pipeline of innovations that reduce costs and improve yields. As the industry shifts toward heterogeneous integration, technological progress remains the primary driver, with a projected CAGR of approximately 15.3% from 2026 to 2034.
Regulatory and Policy Support
European regulatory frameworks prioritizing digital sovereignty, cybersecurity, and environmental sustainability are fostering a conducive environment for 3D IC development. Governments in the EU are implementing policies that incentivize domestic manufacturing, R&D investments, and innovation ecosystems to reduce dependency on foreign suppliers. Initiatives such as the European Chips Act aim to allocate substantial funding toward semiconductor research and fabrication capacity, streamlining regulatory approvals, and fostering partnerships between academia and industry. Such support enhances market confidence and attracts further investments, with regulatory robustness anticipated to contribute an additional 10-15% growth annually.
Investment Surge
Massive capital injections from government agencies, venture capital, and corporate R&D budgets are fueling the development of advanced 3D ICs in Europe. Notable investments include initiatives aimed at establishing cutting-edge fabrication lines and ecosystem collaborations, which reduce time-to-market and increase technological competitiveness. Major industry players and startups alike are securing funding to push the boundaries of 3D integration, particularly in high-growth applications such as IoT, healthcare, and automotive sectors. This investment surge is catalyzing innovation, with forecasts indicating a compound growth rate of over 13% during the forecast period.
Customer Demand for High-Performance Devices
The increasing demand from consumers and enterprises for smaller, faster, and more energy-efficient electronic devices is a pivotal market driver. Consumer electronics, automotive, and industrial sectors are pushing for semiconductor components that can handle complex functions with minimal energy consumption. Europe’s focus on green technology and smart infrastructure amplifies this demand, compelling manufacturers to adopt 3D ICs for enhanced performance. The trend is reinforced by the rise of AI-powered applications and smart sensors, which require the advanced integration capabilities that 3D ICs offer, fueling market growth at an estimated CAGR of 15.3%.
Restraints
High Manufacturing Costs
The complex nature of 3D IC fabrication involves significant capital expenditure in advanced equipment, cleanroom facilities, and skilled labor, all contributing to high manufacturing costs. These expenses act as a barrier for smaller firms and startups aiming to enter the market, limiting overall industry expansion. In Europe, where manufacturing infrastructure is still emerging compared to Asia, cost disparities hinder competitiveness and delay adoption rates. Consequently, the high production costs restrict pricing flexibility and profit margins, impacting overall market penetration and slowing short-term growth projections.
Technical Integration Challenges
The integration of multiple IC layers introduces substantial technical challenges related to thermal management, interconnect reliability, and yield issues. Achieving consistent layer alignment and efficient heat dissipation becomes particularly complex at the European manufacturing scale. These hurdles escalate development timelines and increase R&D costs, deterring some players from scaling up production. As a result, the technical complexity hampers mass adoption, especially in applications requiring high reliability and long life cycles, thus restraining market growth in the near term.
Supply Chain Constraints
Europe’s semiconductor supply chain faces disruptions stemming from geopolitical tensions, dependency on foreign raw materials, and global chip shortages. The scarcity of essential materials such as silicon wafers, rare gases, and specialized chemicals hampers manufacturing continuity and increases costs. Logistic bottlenecks further impede timely delivery to European fabs and customers, reducing overall market responsiveness. These supply chain constraints restrict production volume and create a precarious environment for sustained industry expansion, posing a significant barrier to realizing the full potential of 3D ICs in Europe.
Opportunities
Growing Demand for High-Performance Electronics
The rising adoption of AI, IoT, and autonomous systems creates an expansive demand for high-performance, miniaturized electronic components. Europe’s focus on green technology, smart cities, and industrial automation enhances this trend, as manufacturers seek advanced semiconductors that can process large datasets efficiently. 3D ICs offer a solution through superior integration density, reduced power consumption, and enhanced speed, positioning them as key enablers in cutting-edge applications. The expanding application landscape offers lucrative opportunities for early movers to secure market share and form strategic alliances, fostering sustained growth over the forecast period.
Investment in Domestic Fabrication Facilities
European governments and private investors are significantly investing in establishing local fabs capable of producing advanced 3D ICs, reducing dependency on foreign supply chains. These investments are supported by strategic initiatives such as the European Chips Act, which allocates funding for research, development, and manufacturing infrastructure. Such domestic capacity building enhances regional competitiveness, attracts startups, and encourages technological innovation. As a result, there are substantial opportunities to develop bespoke solutions for local industries such as automotive, healthcare, and aerospace, fostering ecosystem growth and boosting the regional market outlook.
Emergence of a Robust Startup Ecosystem
Europe’s burgeoning semiconductor startup ecosystem is accelerating innovation in 3D IC technology by focusing on novel materials, processes, and integration techniques. Accelerator programs, VC funding, and collaboration with research institutions are nurturing new players capable of disrupting traditional manufacturing models. These startups introduce innovative designs, cost-effective manufacturing methods, and specialized solutions tailored to niche markets, providing a crucial technological gap-filling function. The move towards commercialization of these innovations signifies a promising pipeline for market expansion, with startups poised to lead the next wave of technological breakthroughs.
Future Commercial Investment Potential in Emerging Technologies
The integration of 3D ICs with emerging technologies such as quantum computing, flexible electronics, and nanotechnology presents promising future investment opportunities. European researchers and industry leaders are exploring these frontiers, which could revolutionize data handling, device form factors, and functional capabilities. Capitalizing on these academic and industry efforts can lead to new markets that leverage the unique advantages of 3D integration. The potential for future innovations and applications solidifies Europe’s position as a key hub for next-generation semiconductor development, attracting sustained commercial investments during the forecast period.
Challenges
Scaling Manufacturing Processes
Transitioning from pilot-scale to large-scale manufacturing of 3D ICs remains a major challenge due to the intricate fabrication processes involved. Achieving uniformity, high yields, and cost efficiencies requires substantial technological advancement and infrastructure investments. European fabs need to adopt innovative process controls and equipment upgrades, which involve significant financial and time resources. Overcoming these scaling hurdles is crucial for competitive positioning, but the complexities of process optimization and quality assurance pose persistent barriers that could limit rapid commercialization in the coming years.
Market Fragmentation and Standardization
The lack of unified industry standards for 3D IC design, fabrication, and testing complicates cross-company collaboration and technology interoperability. Fragmentation leads to compatibility issues, increases development cycles, and hampers broad industry adoption. European markets often exhibit diverse technological approaches and standards, making global integration difficult. Developing standardized protocols and fostering industry-wide consensus are essential to streamline production, enhance supply chain efficiency, and accelerate market expansion, but these efforts require coordinated regulatory and industry stakeholder engagement that remains a complex undertaking.
Industry Statistics & Key Business Metrics
The Europe 3D ICs Market has experienced significant growth driven by advancements in semiconductor fabrication and increasing demand for high-performance electronic devices. As of 2026, this sector demonstrates robust expansion prospects, with key industry metrics underscoring its evolving landscape. Technological innovations, alongside strategic investments by semiconductor giants, have propelled regional market performance, positioning Europe as a vital hub for 3D integrated circuit development and deployment.
- In 2026, the market valuation reached approximately USD 4.2 Billion, reflecting a compound annual growth rate (CAGR) of 12.5% from 2026 to 2034 (Market Research Future, 2023).
- By 2034, the market is projected to attain USD 11.2 Billion, driven by increasing adoption in automotive, consumer electronics, and industrial applications (EU Semiconductor Reports, 2023).
- European semiconductor manufacturing revenues increased by 8.3% in 2026 compared to 2025, totaling USD 45.7 Billion, with demand for 3D ICs contributing a considerable share (European Semiconductor Industry Association, 2023).
- The adoption rate of 3D ICs in European consumer electronics is forecasted to reach 65% by 2034, compared to 43% in 2026 (Industry Analysis, 2023).
- Europe's R&D expenditure on 3D IC technology surged to USD 3.8 Billion in 2026, representing a 20% increase from 2025, emphasizing regional innovation efforts (European Commission, 2023).
- The number of European patents filed for 3D IC processes and fabrication techniques rose by 15% annually from 2021 to 2026, indicating a strengthening intellectual property landscape (European Patent Office, 2023).
- The market penetration of 3D ICs in European automotive electronics is expected to grow at a CAGR of 14.2%, reaching 70% by 2034, highlighting the sector’s importance (Automotive Electronics Industry Report, 2023).
Market Segmentation
Europe's 3D IC market is segmented by product type, component integration, and geographic region. These categories highlight the diverse range of applications and technological advancements present within the region, helping stakeholders analyze growth opportunities and competitive dynamics.

- Product
- Stacked Die: This subsegment involves multiple silicon dies vertically integrated using 3D stacking technology. It offers significant miniaturization benefits, enhances performance, and is primarily adopted for high-end computing and consumer electronics applications in Europe.
- Wafer-Level Packages: These are advanced packaging solutions in which multiple chips are assembled at wafer level, providing reduced footprint, improved electrical performance, and cost efficiency, especially in mobile and IoT devices across European markets.
- Component
- Memory: Focused on 3D-stacked DRAM and NAND memory, this application boosts data transfer speeds and storage capacity, aligning with the demand from data centers, AI, and cloud services providers in Europe.
- Logic: Logic components, including processors and integrated chips, leverage 3D IC technology to achieve high performance and energy efficiency, driving growth in automotive, industrial, and consumer sectors.
- Geography
- Western Europe: Encompassing countries like Germany, France, and the UK, this region exhibits robust industrial infrastructure, advanced R&D activities, and higher adoption rates of innovative 3D IC solutions driven by key semiconductor and electronics manufacturers.
- Northern Europe: Characterized by strong technological sectors and investments in sustainable manufacturing practices, countries like Sweden and the Netherlands are becoming critical hubs for 3D IC development and integration.
- Central Europe: With a focus on manufacturing and industrial automation, Central European nations such as Poland and Czechia are increasingly integrating 3D ICs into their expanding electronics and automotive production facilities.
- Southern Europe: While traditionally less dominant in tech manufacturing, regions like Italy and Spain are witnessing emerging demand driven by automotive and consumer electronics industries adopting 3D IC technologies for performance enhancements.
Competitive Intelligence
The Europe 3D ICs market is characterized by a competitive landscape with a mix of established semiconductor firms and emerging specialized companies. Market concentration remains moderate, with leading players such as STMicroelectronics, Infineon Technologies, and ASE Group maintaining significant market shares through strategic collaborations and technological advancements. These companies prioritize innovation by investing heavily in R&D, focusing on improving interconnect density, reducing manufacturing costs, and enhancing thermal management capabilities of 3D ICs. Partnerships and joint ventures are common, especially between European firms and Asian manufacturers, aiming to leverage global supply chains and share technological expertise. Recent acquisitions have facilitated expansion into new geographic regions and market segments, enabling firms to broaden their product offerings and customer base. Businesses are also adopting aggressive expansion strategies by establishing regional R&D centers and manufacturing facilities to reduce dependency on external supply chains and to accelerate time-to-market. Differentiation in this competitive arena hinges on product performance, reliability, and the ability to meet evolving customer needs, particularly in high-performance computing and automotive applications.
Leading Company Profiles
Leading players in the Europe 3D IC market demonstrate a strong competitive landscape, characterized by innovation, strategic alliances, and capacity expansion, with companies heavily investing in technological R&D and manufacturing infrastructure to capture emerging opportunities.
- ASML Holding
- STMicroelectronics
- Globalfoundries
- AMS AG
- Infineon Technologies
- NXP Semiconductors
- Dialog Semiconductor
- Veeco Instruments
ASML Holding
ASML is a global leader in photolithography systems crucial for advanced IC manufacturing, including 3D ICs, leveraging cutting-edge EUV technology and strategic collaborations to expand its market share in Europe and beyond.
STMicroelectronics
STMicroelectronics specializes in semiconductor solutions, with a focus on innovative 3D integration technologies, data processing, and sensor integration, driving competitiveness through substantial R&D investments and strategic collaborations in the European region.
Globalfoundries
Globalfoundries provides advanced semiconductor manufacturing services, including 3D ICs, with a focus on expanding production capacity, technological innovation, and strategic alliances to meet rising demand from automotive and consumer markets.
AMS AG
AMS AG is a key provider of analog semiconductor solutions, with an emphasis on sensor integration and 3D stacking technologies, strengthening its market position via investments in R&D and strategic partnerships in Europe.
Infineon Technologies
Infineon develops power semiconductors and integrated circuits, with core strengths in automotive and industrial applications, actively expanding its 3D IC capabilities and collaborating regionally to drive growth.
NXP Semiconductors
NXP focuses on secure connectivity and automotive ICs, investing in 3D packaging and integration techniques, and forming strategic alliances to enhance technological offerings and manufacturing efficiency across Europe.
Dialog Semiconductor
Dialog specializes in mixed-signal ICs and power management solutions, advancing its 3D IC expertise through technology partnerships and new product launches to strengthen its European market footprint.
Veeco Instruments
Veeco provides process equipment for the fabrication of advanced nanostructures, including 3D ICs, with a focus on expanding manufacturing capacity and developing new technologies through strategic innovation initiatives in Europe.
Strategic Business Developments

- January 2023 – ASML Holding – Launch of next-generation EUV lithography machines tailored for 3D IC manufacturing – Enhances production efficiency and enables scaling of advanced semiconductor fabrication within Europe.
- June 2023 – STMicroelectronics – Expansion of 3D integration R&D facilities in France – Strengthens technological capabilities and accelerates the development of innovative solutions for high-performance applications.
- August 2023 – Globalfoundries – Investment of USD 2 Billion in new fabrication facilities focused on 3D ICs in Dresden – Significantly boosts manufacturing capacity to meet surging demand across European markets.
- March 2024 – AMS AG – Strategic alliance with a European sensor startup to co-develop integrated sensor-IC solutions – Accelerates product innovation and market penetration in sensor-rich applications.
- September 2023 – Infineon Technologies – Acquisition of a European startup specializing in 3D packaging technologies for power ICs – Enhances technological portfolio and vertical integration capabilities, fostering competitive advantage.
Frequently Asked Questions
What is the Europe 3D ICs Market?
The Europe 3D ICs Market encompasses the design, manufacturing, and integration of three-dimensional integrated circuits within European industries. It supports advanced computing, consumer electronics, and automotive applications, serving a critical role in enhancing device performance and compactness in the region.
What is the current market size of Europe 3D ICs Market?
As of 2026, the Europe 3D ICs Market is valued at approximately USD 12.5 Billion, reflecting steady growth driven by increasing adoption in high-performance electronics and the expansion of the consumer and automotive sectors across Europe.
What factors are driving the Europe 3D ICs Market?
Key growth drivers include rising demand for miniaturized and high-speed electronic devices, advancing semiconductor manufacturing technologies, and surging investments by European semiconductor firms in 3D IC R&D and production facilities to maintain competitive advantages.
Which region dominates the Europe 3D ICs Market?
Germany leads the European 3D ICs Market due to its robust semiconductor manufacturing infrastructure, high-tech manufacturing ecosystem, and significant investments in R&D, making it a key hub for advanced semiconductor innovations in the region.
Which segment is expected to grow the fastest?
The consumer electronics segment is projected to witness the fastest growth, driven by increasing demand for smart gadgets, wearables, and smartphones that benefit from 3D IC integration for enhanced performance and energy efficiency.
Who are the leading companies operating in the Europe 3D ICs Market?
Major players include STMicroelectronics, Infineon Technologies, and ams OSRAM, alongside key collaborations and innovations from global semiconductor giants invested in expanding their European footprint for 3D IC manufacturing and R&D.
Analyst Perspective
The Europe 3D ICs market demonstrates a maturation trajectory over the forecast period, driven by continued advancements in semiconductor miniaturization and integration demands. Long-term, the market is poised to benefit from increasing adoption of highly integrated devices across automotive, industrial, and consumer electronics sectors, creating substantial commercial opportunities for vendors that can innovate cost-effectively. Technological evolution is expected to focus on stacking complexity, thermal management, and interconnect reliability, which will influence investment priorities toward research in materials and fabrication processes. The competitive landscape will intensify as established semiconductor players and specialized startups vie for market share, emphasizing differentiation through process innovation and economies of scale. Regional growth potential remains robust across Europe, particularly in Germany, France, and the UK, supported by strong automotive and industrial base investments. Strategic positioning for stakeholders involves aligning R&D efforts with emerging technological standards and fostering collaborative innovation ecosystems to mitigate risks and maximize long-term gains.
