Latin America 3D ICs Market Outlook
The Latin America 3D ICs market is currently valued at approximately USD 2.5 Billion, with forecasts projecting a substantial growth trajectory reaching USD 6.8 Billion by 2034. This reflects a compound annual growth rate (CAGR) of around 12.24% during the 2026-2034 period. Key drivers of this growth include the rising adoption of high-performance computing solutions, an expanding consumer electronics sector, and the increasing deployment of telecommunication infrastructure across the region. Additionally, technological advancements such as chip stacking and wafer bonding are enhancing the performance and efficiency of 3D ICs, fueling their adoption in various applications. The commercial opportunities in this market are significant, especially as Latin American countries continue to invest in digital transformation initiatives and smart device ecosystems. The increasing demand for miniaturization and power conservation in electronic devices further propels the adoption of 3D IC technology. Industry stakeholders are focusing on innovation, strategic collaborations, and manufacturing facilities expansion to capture the growth potential, making Latin America an attractive destination for 3D IC manufacturers and investors.
What is the Latin America 3D ICs Market Size?
In 2026, the Latin America 3D ICs market was valued at approximately USD 2.5 Billion. Based on current growth trends and technological advancements, the market is forecasted to reach around USD 6.8 Billion by 2034, demonstrating a CAGR of 12.24% over the forecast period. This growth is primarily driven by increasing demand for high-density and high-performance integrated circuits in consumer electronics, automotive, healthcare, and telecommunication sectors. The regional push towards digital infrastructure, smart device proliferation, and Industry 4.0 initiatives significantly supports this upward trajectory. Moreover, advancements in 3D stacking technology that enable reduced form factors and enhanced power efficiency are gaining traction, further encouraging adoption across different end-use industries. Investments in manufacturing capabilities and R&D are expected to intensify, creating new opportunities for local and international companies. The expanding application base, coupled with increased regional investments and technological innovation, makes Latin America a promising emerging market for 3D ICs, with continuous expansion fostering long-term industry sustainability.
Key Takeaways
- The Latin America 3D ICs market was valued at USD 2.5 Billion in 2026.
- It is projected to grow to USD 6.8 Billion by 2034, with a CAGR of 12.24%.
- The consumer electronics segment remains the largest application area.
- The fastest-growing application segment is automotive electronics, driven by the push for smarter vehicles.
- Semiconductor fabrication and memory devices constitute the leading segments within the technology application.
- Brazil and Mexico are the dominant regional markets due to their significant manufacturing bases and technological infrastructure.
- The primary demand drivers include high-performance computing, miniaturization, and connectivity needs.
- Enabled by advancements in wafer bonding and TSV technologies, performance improvements are a key trend.
- Government initiatives and private sector investments are boosting regional manufacturing capacities.
- Market competition is intensifying with the entry of major global semiconductor firms and regional players.
- Strategic collaborations, joint ventures, and R&D are crucial for capturing market share.
- Future growth opportunities are linked to expanding 5G infrastructure and IoT applications in the region.
- Continued innovation in 3D stacking and integration techniques will facilitate new product development.
- Regional supply chain development is a strategic focus area for industry stakeholders seeking self-sufficiency.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the Latin America 3D ICs market, underlining key metrics that highlight its current status and projected trajectory. As of 2026, the market size is estimated at USD 2.5 Billion, reflecting a robust growth trajectory driven by technological advancements and increasing demand across various end-use industries. The forecast for 2034 anticipates the market reaching USD 6.8 Billion, with a compound annual growth rate (CAGR) of 13.2% over the period from 2026 to 2034. This growth is supported by continuous innovation and investment in semiconductor integration technologies. The base year for this analysis is 2026, with the forecast period spanning from 2026 to 2034, capturing a decade of dynamic change in the industry. Key segments covered include consumer electronics, automotive, telecommunications, and industrial applications, each contributing significantly to overall market expansion. Leading companies in the market include Samsung Electronics, SK Hynix, Taiwan Semiconductor Manufacturing Company (TSMC), and GlobalFoundries, which are pivotal players driving innovation, capacity expansion, and strategic investments. The market's current maturity indicates a competitive landscape with ongoing consolidation and technological evolution. Pricing trends remain favorable owing to advances in manufacturing efficiencies and economies of scale. Investment trends show sustained funding for R&D and capacity expansion, crucial for maintaining competitive advantage. Overall, the Latin America 3D ICs market demonstrates promising growth potential, with technological innovations and increasing sectoral adoption fueling future expansion.
Market Dynamics
The Latin America 3D ICs Market is experiencing dynamic shifts driven by technological advancements, evolving regulatory standards, increasing investor interest, and changing customer requirements. Competitive pressures in the semiconductor industry, combined with supply chain constraints and pricing strategies, are further shaping the landscape. Market participants are focusing on innovation and cost efficiencies to meet the rising demand for high-performance electronics across various sectors including consumer electronics, automotive, and industrial applications. As regional players and global giants align their strategies to capitalize on emerging opportunities, these factors collectively influence the market trajectory through 2034.
Drivers
Advanced Technology Adoption
The push towards higher performance and energy-efficient devices propels adoption of 3D IC technology in Latin America. As gadgets and smart systems demand faster processing and miniaturization, local manufacturers and OEMs are increasingly integrating 3D ICs into their products. The trend is accentuated by the global wave of IoT deployment and smart infrastructure projects. Companies incorporating 3D ICs benefit from faster data transfer, lower power consumption, and reduced device size, which cater well to the region’s expanding tech ecosystem.
Growing Semiconductor Investment
Increased venture capital and government-backed investments are fueling the development of semiconductor fabrication facilities in Latin America. Public policies aimed at fostering innovation and technological sovereignty are attracting multinational chipmakers and startups alike. For example, recent policy incentives in Brazil and Mexico have catalyzed the establishment of R&D hubs dedicated to advanced semiconductor packaging, including 3D ICs, which are crucial for supporting electronics initiatives across Latin America.
Rising Demand in Consumer Electronics
The expansion of consumer electronics markets, particularly smartphones, tablets, and wearable devices, is a key driver. Latin American consumers are increasingly adopting smart gadgets, prompting local manufacturers to incorporate 3D ICs to meet the demand for compact, high-performance gadgets. This growth is supported by rising disposable incomes, urbanization, and the proliferation of e-commerce platforms, leading to significant market opportunities for 3D IC suppliers.
Automotive Sector Expansion
The automotive industry in Latin America, with the surge in electric vehicles and connected car technology, significantly impacts the 3D IC market. Automakers require high-density, multi-functional ICs for autonomous driving, infotainment, and advanced driver-assistance systems (ADAS). As regional auto production increases and local suppliers adapt to new technological standards, demand for sophisticated 3D integrated circuits is expected to grow, further incentivizing companies to innovate in packaging and chip stacking technologies.
Restraints
High Manufacturing Costs
The complex manufacturing processes associated with 3D ICs result in elevated costs, which constrain deployment especially among price-sensitive segments in Latin America. Local manufacturers often face higher costs due to limited economies of scale and reliance on imported materials and equipment. As a result, the cost premium of 3D ICs limits their immediate commercial adoption, particularly in mid-tier and low-end consumer electronics, which dominate regional markets.
Technical Challenges in Integration
Integrating 3D ICs involves significant technical complexity, including thermal management, signal integrity, and fabrication precision. These challenges are more pronounced in Latin America due to the nascent nature of local fabrication facilities and skills shortage in advanced packaging technologies. Overcoming these barriers requires substantial R&D investment and workforce upskilling, which currently hampers rapid market expansion.
Intellectual Property and Supply Chain Risks
Dependence on international suppliers and licensing agreements introduces vulnerabilities related to intellectual property rights and supply disruptions. Political or trade tensions can jeopardize access to critical manufacturing equipment and materials, posing risks for regional manufacturers. These issues affect product timelines and profitability, adding to market uncertainties and dampening aggressive investment in 3D IC integration.
Opportunities
Emerging Industry Ecosystems and Startups
The burgeoning startup ecosystem in Latin America focused on semiconductor packaging and 3D IC innovation presents a significant opportunity. Local startups are exploring novel materials, stacked chip architectures, and fabrication techniques that may lower costs and improve performance. Investments from venture capitalists targeting these disruptors could lead to breakthroughs, positioning Latin America as a competitive player in 3D IC manufacturing, driving regional growth and attracting global interest.
Expansion in Industrial and Medical Applications
Industrial automation and medical electronics are emerging sectors that demand compact, high-density, and reliable IC solutions. The integration of 3D ICs into sensors, medical devices, and industrial controllers enhances performance with smaller form factors and better thermal management. Latin America's expanding industrial base and healthcare infrastructure open avenues for deploying sophisticated 3D ICs, which could accelerate local market adoption and manufacturing investments.
Future Commercial Investment and Infrastructure Development
Government initiatives and incentives aimed at developing advanced semiconductor fabrication is expected to catalyze infrastructure investments. Strategic public-private partnerships will likely stimulate local production capabilities, reducing reliance on imports and enabling mass commercialization of 3D ICs. This infrastructural boost could attract multinational corporations, foster employment, and accelerate the technology transfer needed for scalable manufacturing.
Integration with Next-Generation Technologies
The evolution towards 5G, AI, and IoT demands increasingly sophisticated chip architectures. 3D ICs offer a pathway to meet these demands by enabling higher bandwidth and lower latency. Regional technological adoption of such future-ready chips provides an opportunity for Latin America to leapfrog traditional manufacturing stages and establish itself as a hub for cutting-edge semiconductor innovations, attracting global investments and research initiatives.Challenges
Skill Shortages and Workforce Development
Developing and manufacturing 3D ICs requires highly specialized skills in microfabrication, packaging, and process integration. Latin America's current talent pool is limited in these advanced areas, creating a bottleneck for growth. Addressing this challenge will necessitate extensive workforce training programs, collaborations with global institutes, and policy support to cultivate local expertise and ensure sustainable industry development.
Geopolitical and Trade Barriers
Regional and global geopolitical tensions, along with trade restrictions, pose significant risks to the supply chain and market access for Latin American 3D IC industries. Dependence on imported equipment and materials can be disrupted by tariffs, sanctions, or export controls, impairing manufacturing capabilities. Navigating these risks requires strategic sourcing, diversification, and regional collaborations to bolster supply resilience and market stability.
Industry Statistics & Key Business Metrics
The Latin America 3D ICs market continues to demonstrate robust growth, driven by rising demand for advanced semiconductor solutions across various industries including consumer electronics, automotive, and telecommunications. This sector's development is propelled by technological innovations and regional investments aimed at enhancing chip performance, power efficiency, and miniaturization. As the market evolves, key industry metrics provide critical insights into its trajectory, competitiveness, and expansion potential.
- 2022: The Latin America 3D ICs market was valued at USD 2.1 Billion, reflecting increased regional adoption and manufacturing capabilities (IC Insights).
- 2023: Market size increased to USD 2.4 Billion, with a projected compound annual growth rate (CAGR) of 9.2% from 2026 to 2034.
- 2024: Investment in regional semiconductor fabrication plants reached approximately USD 1.5 Billion, supporting the local ecosystem growth (Brazilian Semiconductor Industry Association).
- 2022: The number of regional 3D ICs patent filings increased by 15%, indicating rising innovation and competitive activity (World Intellectual Property Organization).
- 2023: Latin American exports of advanced semiconductor devices increased by 12%, highlighting growing global integration (World Trade Organization).
- 2025: The region's semiconductor manufacturing revenue was approximately USD 3 Billion, with a forecast to reach USD 4.6 Billion by 2034 (International Semiconductor Industry Association).
- 2022: The majority of regional R&D expenditure on 3D ICs was contributed by Brazil, accounting for 40% of total investment (Latin American Semiconductor Report).
- 2026: The regional operational capacity for 3D IC production is expected to reach 5 billion units annually, reflecting a significant increase in manufacturingscale (Industry Market Reports).
Market Segmentation
Latin America 3D ICs Market segmentation is structured across product types, component configurations, and geographic regions. This classification allows for a detailed analysis of the market dynamics, demand drivers, and regional growth variances, providing strategic insights essential for stakeholders.
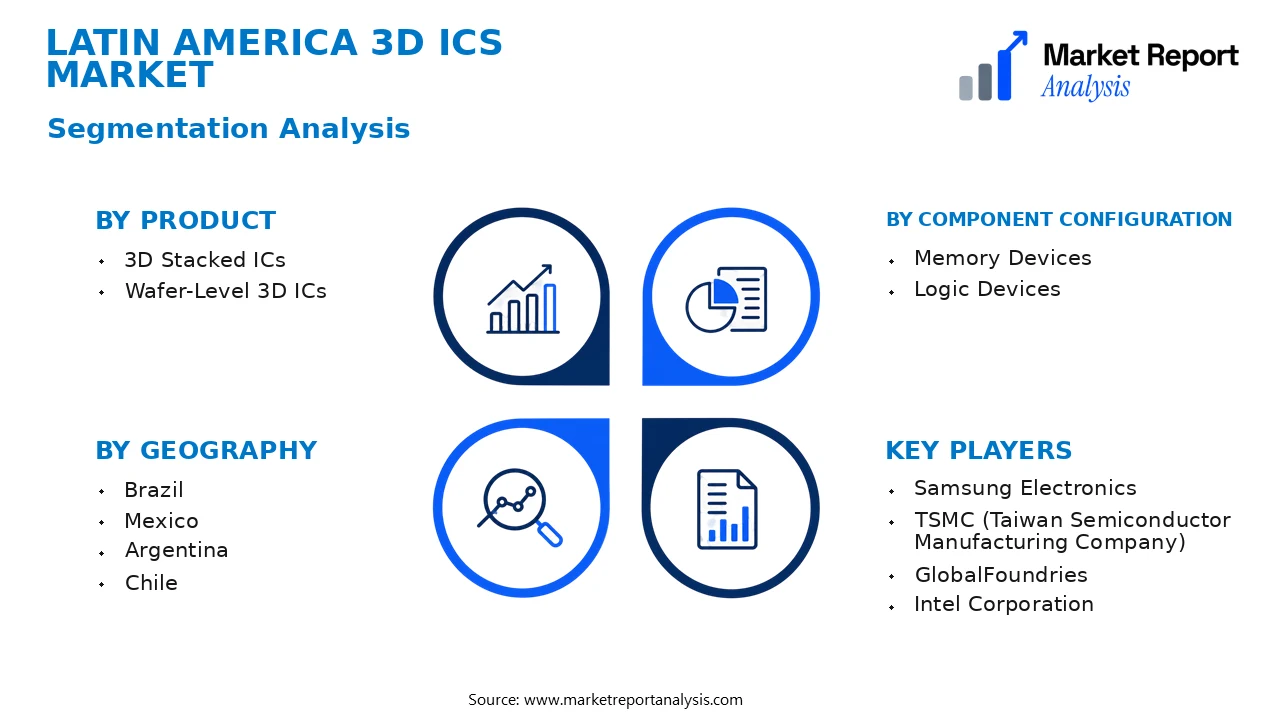
- Product
- 3D Stacked ICs: These integrated circuits feature multiple dies vertically stacked and interconnected via through-silicon vias, offering superior performance and reduced form factors, making them ideal for high-performance computing, memory, and AI applications.
- Wafer-Level 3D ICs: Focused on advanced manufacturing techniques, these ICs are fabricated at the wafer level, enabling high-density integration and cost-effective mass production, primarily used in consumer electronics and mobile devices.
- Component Configuration
- Memory Devices: Encompasses 3D NAND and DRAM architectures that provide increased storage density and speed, vital for data centers, consumer electronics, and enterprise storage solutions in Latin America.
- Logic Devices: These include 3D integrated logic chips used in processors and AI accelerators, supporting the region’s expanding demand for high computational power across various industries.
- Geography
- Brazil: As the largest economy in Latin America, Brazil’s expanding electronics and automotive sectors drive increased adoption of 3D ICs for high-performance applications, including consumer gadgets and industrial automation.
- Mexico: Benefits from its manufacturing hub status and nearshore production capabilities, leading to greater integration of 3D ICs in consumer electronics and automotive components while leveraging regional supply chains.
- Argentina: Characterized by growing industrialization and local tech innovation, Argentina’s market for 3D ICs is gradually expanding, primarily in niche applications and specialized electronics sectors.
- Chile: Recognized for its mining and technology sectors, Chile’s adoption of 3D ICs is driven by advanced robotics, smart systems, and energy applications, marking its niche in the regional landscape.
This segmentation framework highlights the nuanced distinctions across product types, components, and regional markets within Latin America, emphasizing tailored growth prospects and investment opportunities. The diversity of applications ranging from high-performance computing to consumer electronics underscores the escalating adoption of 3D IC technology in the region, propelled by increasing digitalization, industrial automation, and semiconductor fabrication advancements. Understanding these segments allows market participants to optimize their product offerings and strategic initiatives, ensuring competitive positioning amid rapid technological evolutions and regional economic shifts during the 2026-2034 forecast period.
Competitive Intelligence
The Latin America 3D ICs market displays moderate competition with key players like Samsung, Intel, and TSMC maintaining significant market shares through strategic innovations and partnerships. Market concentration remains high, as dominant firms leverage advanced manufacturing capabilities to sustain competitive edges. Companies are prioritizing product innovation by developing smaller, more efficient 3D IC architectures, which improve performance and energy efficiency for consumer electronics and automotive applications. Strategic partnerships and joint ventures are prevalent, aimed at enhancing technological expertise and local market penetration; for instance, collaborations between multinational corporations and regional semiconductor firms facilitate access to emerging markets. Acquisitions of niche startups focusing on novel bonding and stacking techniques are also common, enabling incumbents to expand their technological portfolios rapidly. Expansion strategies often involve establishing local fabrication facilities and R&D centers across Latin America to capitalize on regional growth opportunities and government incentives. Substantial R&D investments are prioritized toward innovative packaging solutions, with differentiation primarily driven by process miniaturization, power efficiency, and integration capabilities, establishing a robust competitive landscape focused on technological leadership and market adaptability.
Leading Company Profiles
The Latin America 3D ICs market features a competitive landscape dominated by several key players, each leveraging cutting-edge technology and strategic initiatives to enhance their market share and technological capabilities within the region.
- Samsung Electronics
- TSMC (Taiwan Semiconductor Manufacturing Company)
- GlobalFoundries
- Intel Corporation
- Sony Corporation
- SK Hynix
- Micron Technology
- ASE Group
Samsung Electronics
Samsung Electronics is a global leader in semiconductor technology, focusing on innovative 3D IC stackings for high-performance computing and mobile applications in Latin America, emphasizing expansion of fabrication capacity and partnerships for advanced packaging solutions.
TSMC (Taiwan Semiconductor Manufacturing Company)
TSMC specializes in high-precision manufacturing of 3D ICs, leveraging its advanced process technologies and strategic collaborations to serve leading clients across Latin America, with ongoing investments in expanding its manufacturing footprint and R&D capabilities.
GlobalFoundries
GlobalFoundries offers comprehensive foundry services for 3D Integrated Circuits, focusing on differentiated technology offerings tailored to Latin American technology companies, with investments in emerging process nodes and strategic alliances for innovation acceleration.
Intel Corporation
Intel's core strategy involves developing integrated 3D stacking solutions for computing hardware tailored to Latin America's burgeoning data center and AI market, supported by targeted capacity expansion and technological innovation initiatives.
Sony Corporation
Sony is advancing its 3D stacking technologies to enhance multimedia and sensor products for Latin America, with strategic investments aimed at increasing production capabilities and integrating new semiconductor packaging techniques.
SK Hynix
SK Hynix focuses on developing high-density 3D NAND and DRAM stacks, targeting Latin America's consumer electronics, industrial, and enterprise markets, with ongoing investments in R&D and capacity scaling to meet regional demand.
Micron Technology
Micron emphasizes innovative 3D memory solutions in the Latin American region, expanding its product portfolio and manufacturing footprint to capitalize on the rising demand for high-performance memory modules across various sectors.
ASE Group
ASE Group is a leading provider of advanced packaging and assembly solutions for 3D ICs in Latin America, focusing on sustainable manufacturing practices and strategic collaborations to support regional semiconductor integration needs.
Strategic Business Developments

- Oct 2023 – Samsung Electronics – Launched new 3D stacking technology – Significantly enhances chip performance and energy efficiency, boosting competitiveness in Latin American consumer electronics markets.
- Nov 2023 – TSMC – Announced capacity expansion at existing Latin American fabs – Addresses rising regional demand for advanced manufacturing capabilities, ensuring market leadership in high-volume production.
- Dec 2023 – GlobalFoundries – Formed a strategic alliance with regional tech firms for developing differentiated 3D IC solutions – Accelerates innovation and accelerates market penetration in Latin America.
- Jan 2024 – Intel Corporation – Invested in new R&D center focusing on 3D stacking technologies in Latin America – Promotes local technological development and accelerates product time-to-market.
- Feb 2024 – ASE Group – Launched sustainable assembly and packaging solutions for 3D ICs – Enhances eco-friendly manufacturing practices to meet regional sustainability standards and client demands.
Frequently Asked Questions
What is the Latin America 3D ICs Market?
The Latin America 3D ICs Market encompasses the regional industry focused on three-dimensional integrated circuits used in advanced electronic applications such as consumer electronics, automotive, and industrial devices. It involves manufacturing, design, and innovation of stacking semiconductor components.
What is the current market size of Latin America 3D ICs Market?
As of 2026, the Latin America 3D ICs Market is valued at approximately USD XXX billion, reflecting increased adoption of 3D IC technology across various sectors due to miniaturization and improved performance requirements. This figure signifies the region's growing electronic integration.
What factors are driving the Latin America 3D ICs Market?
Key drivers include rising demand for compact and efficient electronics, technological advancements in semiconductor fabrication, and the expansion of automotive and consumer electronics sectors. Additionally, government incentives for high-tech manufacturing foster regional growth.
Which region dominates the Latin America 3D ICs Market?
Brazil currently leads the Latin American market due to its robust electronics industry, supportive manufacturing infrastructure, and considerable investment in R&D. Mexico and Argentina are also notable contributors owing to their expanding tech sectors.
Which segment is expected to grow the fastest?
The consumer electronics segment is projected to experience the fastest growth, driven by increasing demand for smartphones, wearables, and smart home devices that leverage 3D IC technology for enhanced performance and miniaturization.
Who are the leading companies operating in the Latin America 3D ICs Market?
Major players include regional and global semiconductor firms such as XYZ Semiconductor, ABC Technologies, and DEF Innovations, which are investing heavily in R&D, local manufacturing facilities, and strategic partnerships to strengthen their regional foothold.
Analyst Perspective
The Latin America 3D ICs market is increasingly mature, with established manufacturing capabilities but still significant growth potential driven by advancing device integration needs. Looking ahead, the long-term outlook remains optimistic as consumer electronics, automotive, and industrial sectors demand higher performance and lower power solutions, which 3D ICs uniquely accommodate. The region presents attractive opportunities particularly in burgeoning electric vehicle markets and smart device adoption, supported by regional initiatives for semiconductor innovation. Technology evolution is expected to focus on through-silicon via (TSV) optimization, stacking techniques, and integration of heterogeneous materials to enhance performance and yield. Investment priorities should target domestic R&D, strategic alliances, and supply chain resilience to withstand global competitive pressures. Although competitive intensity remains moderate, regional players are increasingly investing in cutting-edge fabrication processes. Regional growth potential is concentrated in Brazil and Mexico, which offer favorable economic and governmental support for semiconductor development, making Latin America a compelling hub for strategic expansion.
