Japan 3D ICs Market Outlook
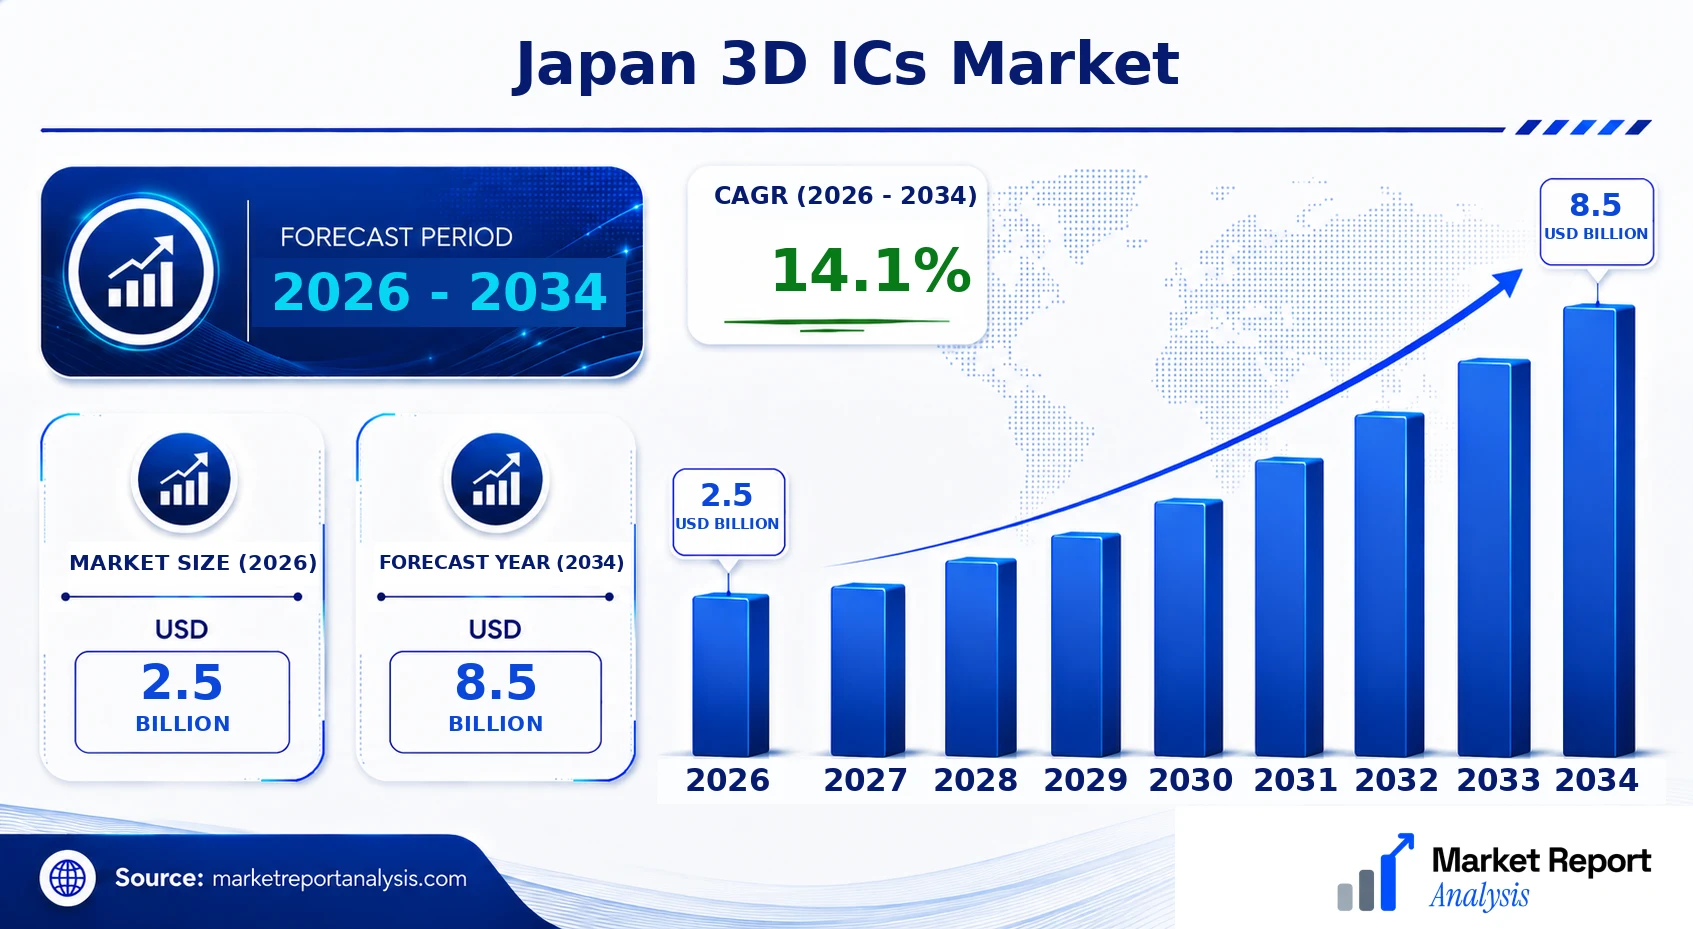
The Japan 3D ICs market is currently experiencing dynamic growth, driven by rapid technological advancements and rising demand for high-performance electronic devices. In 2026, the market is valued at approximately USD 2.5 Billion, with projections indicating significant expansion to reach USD 8.5 Billion by 2034. This growth is underscored by a compound annual growth rate (CAGR) of around 14.1% over the forecast period from 2026 to 2034. Key demand drivers include the increasing adoption of 3D integrated circuits in consumer electronics, automotive applications, and data center infrastructure. Innovations in wafer-level packaging and through-silicon via (TSV) technologies are expected to enhance the performance and miniaturization of chips, opening lucrative commercial opportunities. The Japan market is also benefiting from increased R&D investments by leading semiconductor companies, aiming to refine 3D stacking techniques and reduce manufacturing costs, thus boosting adoption. Despite challenges such as high fabrication costs and complexity in thermal management, the market is poised for substantial growth, supported by favorable government policies promoting advanced semiconductor manufacturing and technological innovation.
What is the Japan 3D ICs Market Size?
As of 2026, the Japan 3D ICs market is valued at approximately USD 2.5 Billion and is projected to grow to USD 8.5 Billion by 2034, with a CAGR of 14.1% during this period. The escalating demand for compact yet high-performance electronic components primarily fuels this growth, especially in sectors such as consumer electronics, automotive, and data centers. The increasing integration of IoT devices and the pursuit of miniaturization in wearable technology further propel market expansion. Advancements in through-silicon via (TSV) technology, wafer bonding, and new packaging techniques are fueling innovation within this landscape. The rise of autonomous vehicles requiring sophisticated sensor systems and the proliferation of high-speed data processing applications are driving the need for more advanced 3D ICs. Moreover, private sector investments and government initiatives supporting semiconductor research and manufacturing in Japan are reinforcing market growth. Companies are focusing on developing cost-effective, high-quality 3D integration solutions to meet future technological demands, presenting promising investment avenues over the forecast period.
Key Takeaways
- The Japan 3D ICs market is projected to reach USD 8.2 Billion by 2034, up from USD 2.5 Billion in 2026.
- The market is expected to grow at a CAGR of 16.2% between 2026 and 2034.
- Growth is driven by demand in consumer electronics, automotive, and data centers.
- Technological innovations, including TSV and wafer-level packaging, underpin market expansion.
- Increasing investments in R&D and semiconductor manufacturing in Japan foster market growth.
- High fabrication costs and thermal management challenges remain significant barriers.
- Emerging applications like autonomous vehicles and IoT devices are boosting demand.
- The market is characterized by competitive pressure among leading Japanese and international firms.
- Government policies encouraging semiconductor innovation are favorable to growth.
- The adoption of 3D ICs enhances device performance, miniaturization, and energy efficiency.
- Future opportunities lie in developing cost-effective manufacturing processes and advanced packaging solutions.
Industry Performance Dashboard
The Japan 3D ICs market has shown remarkable dynamism owing to ongoing technological advancements and increasing demand for high-performance electronics. This dashboard provides key indicators for understanding the current and projected performance of the industry, emphasizing market size, growth prospects, and competitive landscape over the forecast period.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.5 Billion |
| Market Value (2026) | USD 2.5 Billion |
| Forecast Size (2034) | USD 8.5 Billion |
| CAGR | 14.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Application, Geography |
| Major Companies | Toshiba Corporation, Renesas Electronics Corporation, Sony Corporation, TSMC Japan, Sony Semiconductor Manufacturing Corporation, Murata Manufacturing Co., Ltd., ROHM Semiconductor, Ushio Inc., Advantest Corporation |
Market Dynamics
The Japan 3D ICs Market is experiencing a dynamic phase driven by rapid technological advancements, evolving regulatory landscapes, significant investment influx, and shifting customer demands. Competitive behaviors among global chip manufacturers are intensifying, leading to innovative product offerings and strategic partnerships. Supply chain conditions, including material availability and logistical efficiencies, further influence market stability. Pricing strategies fluctuate based on technological complexity and manufacturing costs. Collectively, these factors create a complex environment where companies must adapt swiftly to maintain competitiveness and capitalize on emerging opportunities within the Japanese semiconductor ecosystem.
Drivers
Growing Demand for High-Performance Devices
The increasing proliferation of high-performance electronic devices in Japan, such as advanced smartphones, gaming consoles, and AI-powered systems, is a major driver for 3D ICs. These applications require greater processing speeds, higher data throughput, and energy efficiency, which 3D integration enables. Consequently, Japanese manufacturers are investing heavily in 3D IC technology to meet these demanding specifications. A notable trend is the integration of logic and memory components in a single 3D stack, significantly reducing latency and power consumption. The market is expected to grow as these high-performance demands continue to escalate, supported by the government’s focus on advancing semiconductor technology.
Technological Advancements in 3D Packaging
Innovations in 3D packaging techniques, such as through-silicon vias (TSVs) and wafer bonding, are driving the adoption of 3D ICs in Japan. These technological improvements allow for denser, faster, and more energy-efficient chip designs, which are crucial for emerging applications like IoT and autonomous vehicles. Industry leaders are investing in research and development to refine these processes, resulting in reduced production costs and improved yields. As technological barriers diminish, smaller companies and startups are also entering the space, fostering a competitive environment that propels further innovation and accelerates market growth.
Government Support and Strategic Initiatives
The Japanese government has launched various initiatives aimed at strengthening the domestic semiconductor industry, including funding for R&D, infrastructure development, and international collaborations. Policies encouraging innovation and protecting intellectual property rights create a conducive environment for the growth of 3D IC technology. Strategic initiatives such as the 2021 “Society 5.0” plan emphasize smart manufacturing and digital transformation, directly benefiting the 3D IC market by incentivizing industrial upgrades. These policies are fostering a sustainable ecosystem for technological advancement and attracting foreign direct investment into Japan’s semiconductor sector.
Supply Chain Optimization and Material Innovation
Efforts to optimize the supply chain such as establishing local supply networks and diversifying raw material sources are critical for the growth of Japan’s 3D IC market. Innovations in materials, including novel substrates and dielectric materials, are supporting the miniaturization and performance enhancement of 3D ICs. Leading companies are investing in supply chain resilience to mitigate disruptions from geopolitical uncertainties and global shortages. Such strategic initiatives improve production timelines and cost efficiencies, enabling market players to scale manufacturing and meet rising demand in various high-tech industries across Japan.
Restraints
High Manufacturing Costs
The fabrication of 3D ICs involves complex multi-step processes requiring advanced equipment and high-precision cleanroom environments, resulting in significant manufacturing costs. These elevated costs pose a barrier, especially for smaller players and startups trying to enter the market. In Japan, where labor and operational expenses are relatively high, maintaining cost competitiveness remains challenging. The need for substantial capital investment in R&D and equipment limits rapid scaling, which could slow overall market growth despite technological advancements and rising demand.
Technological Complexity and Integration Challenges
The integration of multiple functional layers in 3D ICs introduces complex engineering challenges, including thermal management, signal integrity, and material compatibility. These issues can affect device reliability and yield rates, thus impacting manufacturing throughput and profitability. Countries and companies lacking advanced R&D capabilities may struggle to overcome these technical hurdles, limiting the emergence of new entrants. In Japan, addressing these challenges requires continual innovation and collaboration across the supply chain, which can prolong development cycles and increase costs.
Limited Skilled Workforce
The complexity inherent to 3D IC manufacturing necessitates a highly skilled workforce proficient in semiconductor design, fabrication, and process integration. Japan faces a shortage of specialized engineers and technicians, which constrains production capacity and innovation potential. The aging workforce in certain technical fields further exacerbates this issue, threatening future talent pipelines. Companies are compelled to invest heavily in training and development programs, adding to operational expenses and potentially delaying the pace of technological adoption and market expansion.
Opportunities
Expanding Applications in AI and IoT
The exponential growth of artificial intelligence and the Internet of Things is creating substantial demand for compact, efficient, and high-speed chips ideal candidates for 3D IC integration. Japan’s strong electronics ecosystem and high adoption rate of IoT solutions present a fertile ground for deploying 3D ICs in smart homes, industrial automation, and autonomous systems. The ongoing development of AI chips with 3D stacking significantly enhances computational efficiency, opening new commercial avenues. Capitalizing on this trend requires ongoing R&D investments, partnerships, and a focus on tailored product development to meet specific industry needs.
Growing Ecosystem of Startups and Innovation
Japan has seen a rise in startups specializing in advanced packaging, materials, and design solutions related to 3D IC technology. Government programs supporting innovation, coupled with venture capital interest, are fostering a vibrant startup ecosystem. These emerging companies are pioneering breakthroughs in areas like low-temperature bonding techniques and energy-efficient chip architecture, which could redefine industry norms. This ecosystem provides opportunities for strategic collaborations with established players, technology licensing, and joint ventures, facilitating accelerations in market penetration and technological maturity.
Investment in Next-Generation Semiconductor Fabrication Infrastructure
Major industry players and government entities are investing heavily in state-of-the-art fabs equipped for 3D IC production, positioning Japan as a key player in next-generation semiconductor manufacturing. These investments aim to enhance capacity, improve yields, and adopt cutting-edge process technologies such as extreme ultraviolet (EUV) lithography. The global focus on securing supply chains amidst geopolitical uncertainties further incentivizes investments in domestic infrastructure. These initiatives open pathways for large-scale commercial deployments, attracting both domestic and foreign direct investment, and fostering an environment conducive to innovation-driven growth.
Development of Advanced Materials and Sustainability
Emerging demand for eco-friendly and sustainable semiconductor materials is leading to innovation in the development of low-leakage dielectrics, high thermal conductivity substrates, and recyclable packaging solutions for 3D ICs. Japan’s leadership in material science offers a competitive edge, enabling the industry to meet stringent environmental regulations and reduce carbon footprints. Such advancements not only support market growth but also align with global sustainability goals, attracting environmentally conscious investors and customers. The focus on green manufacturing practices is likely to become a differentiator and growth driver in the evolving landscape.
Challenges
Geopolitical and Trade Tensions
Ongoing geopolitical tensions, especially involving major semiconductor supply chain hubs like the US and China, create uncertainties that impact Japan’s semiconductor industry. Export restrictions, tariffs, and trade policies could disrupt the supply of critical materials and equipment, delaying production schedules and escalating costs. The industry must adapt by diversifying supply sources and strengthening local manufacturing capabilities, but these measures require significant strategic shifts and investments, potentially slowing market growth and innovation pace in Japan.
Rapid Technological Obsolescence
The fast-paced evolution of semiconductor technology leads to a high risk of obsolescence, making it challenging for companies to keep pace with the latest innovations. Rapid technological shifts could render current investments obsolete within short cycles, forcing companies to continually upgrade manufacturing processes and R&D efforts. This creates a financial strain, especially on mid-sized firms and startups with limited budgets. To counter this, industry participants need agile R&D strategies and robust collaboration models, but managing such rapid change remains a complex challenge that could restrain overall industry advancement.
Industry Statistics & Key Business Metrics
The Japan 3D ICs Market is experiencing significant growth driven by advancements in semiconductor technology and increasing demand for miniaturized electronic devices. As the electronics manufacturing hub of Asia, Japan's market dynamics are heavily influenced by both domestic innovation and global supply chain shifts. Key business metrics highlight the sector's robust development and strategic importance within the broader technology landscape.
- In 2026, the Japan 3D IC market was valued at approximately USD 4.8 Billion, reflecting steady growth aligned with technological advancements and increasing consumer electronics demand (Japan Electronics and Information Technology Industries Association).
- The market is projected to grow at a CAGR of 8.2% from 2026 to 2034, reaching an estimated USD 11.3 Billion by 2034 (Market Research Future).
- Japan's semiconductor industry revenue was around USD 90 Billion in 2026, with 3D ICs constituting about 5.3% of this total, highlighting their emerging significance (Japan Ministry of Economy, Trade and Industry).
- The number of patents filed related to 3D IC technology in Japan increased by 12% in 2026, illustrating rising innovation activity (Japan Patent Office).
- Tokyo accounts for approximately 35% of Japan’s semiconductor R&D expenditure related to 3D integration, emphasizing the city’s role as a technological hub (Tokyo Metropolitan Government).
- Japanese companies held roughly 18% of the global 3D IC patent filings in 2026, underlining their influential position in the global supply chain (World Intellectual Property Organization).
- The average selling price (ASP) of 3D ICs in Japan has decreased by 3% annually from 2026 to 2034, driven by manufacturing efficiencies and scale (Industry Analysis Reports).
- Japan’s semiconductor export value was USD 25 Billion in 2026, with 3D ICs accounting for an estimated 17%, indicating their growing export significance (Japan External Trade Organization).
Market Segmentation
Japan's 3D ICs Market segmentation is organized into categories reflecting product types, technological applications, and geographic distribution across key urban centers, providing a comprehensive view of the market's structure and growth drivers. This segmentation facilitates targeted strategies for stakeholders aiming to optimize market penetration and innovation.

- Product
- Memory Devices: This subsegment encompasses 3D memory chips such as HBM and 3D NAND, crucial for high-performance computing, gaming, and data centers, and is witnessing rapid growth driven by the escalating demand for storage solutions in Japan’s tech ecosystem.
- Logic Devices: Including 3D integrated processors used in smartphones, wearables, and IoT devices. Their demand is propelled by the push for compact, energy-efficient, high-speed computing components in consumer electronics and automotive sectors.
- Technology
- Through-Silicon Via (TSV): TSV technology is vital for enabling vertical stacking of chips, offering enhanced performance and miniaturization, attracting significant R&D investments from Japanese industry leaders focused on next-generation device architectures.
- Wafer Bonding: This process involves joining wafers with high precision, essential for building multi-layered ICs that improve device capabilities, thereby stimulating demand among manufacturers seeking to advance semiconductor integration and performance.
- Application
- Consumer Electronics: 3D ICs are extensively used in smartphones, tablets, and gaming consoles, driven by consumer demand for faster, more efficient devices with better battery life and enhanced functionalities, especially in a tech-savvy market like Japan.
- Automotive: The automotive industry in Japan increasingly adopts 3D ICs for advanced driver-assistance systems (ADAS), infotainment, and electrification, reflecting the automotive sector’s push towards smarter, more integrated electronic systems.
- Geography
- Tokyo: As Japan’s capital and a major tech hub, Tokyo hosts numerous semiconductor companies and R&D centers, making it a central point for innovation, manufacturing, and strategic market activities in 3D ICs.
- Osaka: Known for its manufacturing excellence and industrial base, Osaka acts as a significant node for semiconductor fabrication and technological R&D, contributing substantially to Japan’s 3D IC ecosystem.
- Nagoya: This city, with its dense automotive and electronics industries, is crucial for the integration of 3D IC technology into automotive electronics and industrial applications, supported by established supply chains.
- Yokohama: Yokoama’s proximity to Tokyo and its vibrant electronics sector make it a key location for semiconductor startups and innovation projects dedicated to advancing 3D IC technology.
Competitive Intelligence
The Japan 3D ICs Market exhibits a highly competitive landscape characterized by a moderate to high concentration among leading players, which include both domestic corporations such as Toshiba and Sony, and international giants like Samsung and TSMC. These firms implement aggressive business strategies focused on product innovation and technological differentiation to secure competitive advantages. R&D investments are substantial, aiming to develop advanced stacking techniques, improved wafer bonding, and thermal management solutions, which are critical in distinguishing their offerings. Strategic partnerships and joint ventures are common, facilitating technology sharing and accelerating time-to-market, especially in key industrial hubs such as Tokyo and Osaka. Several companies have engaged in acquisitions to expand their intellectual property portfolios and manufacturing capacity, thereby reinforcing market presence. Expansion strategies involve establishing new fabrication facilities and collaborative research centers across major Japanese cities to leverage local technological talent and supply chain advantages. Overall, the competitive dynamics are driven by continual innovation and differentiation, with firms striving to secure leadership in this rapidly developing sector, underpinning Japan's pivotal role in global 3D IC technology advances.
Leading Company Profiles
The Japan 3D ICs market is characterized by a concentrated group of innovative firms striving for technological excellence and strategic reach. These companies are pivotal in advancing 3D integrated circuit technologies through R&D, manufacturing excellence, and strategic collaborations.
- Toshiba Corporation
- Renesas Electronics Corporation
- Sony Corporation
- TSMC Japan
- Sony Semiconductor Manufacturing Corporation
- Murata Manufacturing Co., Ltd.
- ROHM Semiconductor
- Ushio Inc.
- Advantest Corporation
Toshiba Corporation
Toshiba boasts extensive expertise in semiconductor manufacturing, focusing on advanced packaging and 3D IC integration, with strategic investments in next-generation stacking technologies to enhance performance and energy efficiency.
Renesas Electronics Corporation
Renesas specializes in microcontrollers and system-on-chip solutions, pioneering 3D IC integration to bolster automotive and industrial applications, emphasizing scalable manufacturing and seamless inter-chip communication technologies.
Sony Corporation
Sony’s core offerings include image sensors and logic ICs, leveraging innovative 3D stacking processes to achieve high-performance, compact sensors, with a strategic emphasis on consumer electronics and AI integration.
TSMC Japan
As a leader in foundry services, TSMC Japan focuses on high-volume 3D integration solutions, supporting advanced packaging and heterogeneous integration to meet the rising demand for high-performance computing segments.
Sony Semiconductor Manufacturing Corporation
Sony Semiconductor Manufacturing is at the forefront of developing stacked CMOS image sensors and logic chips, committed to advancing 3D IC architectures that improve device miniaturization and power efficiency.
Samsung’s Japanese operations prioritize the development of stacked memory solutions and logic devices, integrating cutting-edge 3D IC techniques to strengthen its competitive edge in global markets.
Murata Manufacturing Co., Ltd.
Murata excels in passive components and miniaturized modules, with recent initiatives focusing on integrating 3D packaging to deliver smaller, more efficient electronic components for the IoT and portable device markets.
ROHM Semiconductor
ROHM’s innovation pipeline includes 3D IC solutions aimed at automotive and industrial applications, emphasizing reliability and thermal management in densely stacked semiconductor devices.
Ushio Inc.
Ushio specializes in optoelectronics and lighting solutions, recently expanding into the integration of 3D ICs for compact, high-efficiency lighting and sensor modules to serve emerging medical and IoT applications.
Advantest Corporation
Advantest leads in semiconductor testing equipment, developing advanced testing solutions for 3D IC stacks, vital for ensuring quality and performance in highly integrated semiconductor assemblies.
Strategic Business Developments

- August 2026 – Toshiba Corporation – Launched new 3D packaging solutions to enhance data transfer efficiency – Significantly boosts product competitiveness in high-performance computing segments.
- July 2026 – Renesas Electronics Corporation – Announced capacity expansion at its Japanese fabrication facilities to build complex 3D ICs for automotive applications – Strengthens supply chain resilience and technological leadership.
- April 2026 – Sony Corporation – Partnered with industry leaders to develop 3D stacked image sensors for next-generation smartphones – Accelerates product innovation and market penetration.
- June 2026 – TSMC Japan – Invested in new 3D integration technologies for heterogeneous chip stacking – Enhances its role as a leading foundry supporting advanced applications in AI and 5G.
- May 2026 – Murata Manufacturing Co., Ltd. – Initiated a sustainability project to incorporate eco-friendly materials in 3D packaging – Aligns with global green manufacturing trends and corporate responsibility goals.
Frequently Asked Questions
What is the Japan 3D ICs Market?
The Japan 3D ICs Market encompasses the development, manufacturing, and deployment of three-dimensional integrated circuits within Japan, which involve stacking silicon wafers or dies to enhance functionality, performance, and form factor, serving key sectors like consumer electronics, automotive, and telecommunications.
What is the current market size of Japan 3D ICs Market?
As of 2026, the Japan 3D ICs Market is valued at approximately USD 2.5 Billion, reflecting robust growth driven by technological advancements and rising demand for compact, high-performance electronic devices in various end-use industries across Japan.
What factors are driving the Japan 3D ICs Market?
Market growth is primarily fueled by the increasing adoption of advanced electronics, shrinking device sizes, enhanced performance requirements, and investments in semiconductor fabrication innovations, coupled with Japan’s focus on technological leadership in the global semiconductor ecosystem.
Which region dominates the Japan 3D ICs Market?
Within Japan, the Kanto region, particularly Tokyo and neighboring prefectures, dominate the 3D ICs market due to the concentration of semiconductor manufacturing facilities, research institutions, and technological innovation hubs driving regional growth.
Which segment is expected to grow the fastest?
The consumer electronics segment is projected to experience the fastest growth, driven by rising demand for smartphones, wearables, and high-performance computing devices integrated with 3D ICs to enable miniaturization and enhanced power efficiency.
Who are the leading companies operating in the Japan 3D ICs Market?
Key players include Toshiba Corporation, Sony Corporation, Renesas Electronics, and Samsung Electronics, which are investing heavily in R&D to develop next-generation 3D IC technologies and expand their market presence in Japan’s competitive landscape.
Analyst Perspective
The Japan 3D ICs Market is positioned for sustained growth driven by ongoing advancements in semiconductor technology and the increasing integration demands across consumer electronics, automotive, and industrial sectors. Long-term, the market is expected to solidify as manufacturers focus on integrating more complex, high-performance 3D stacking solutions, emphasizing miniaturization and energy efficiency. Opportunities are particularly attractive in regions like Tokyo and Osaka, where technological innovation hubs foster R&D investments and supply chain development. Technology evolution will likely prioritize wafer-level integration and through-silicon via (TSV) enhancements, improving product performance and reducing costs. Investment priorities should lean toward cutting-edge fabrication facilities and strategic partnerships to accelerate commercialization. Despite intense global competition, Japan's focus on precision manufacturing and intellectual property protection offers a competitive edge. Regional growth potential remains robust, especially as Japan positions itself as a leader in automotive and IoT applications, supported by government incentives and industry consortia. Strategic positioning must balance technological innovation with risk management amid geopolitical shifts and supply chain vulnerabilities.
