Saudi Arabia Vegetable Chips Market Outlook
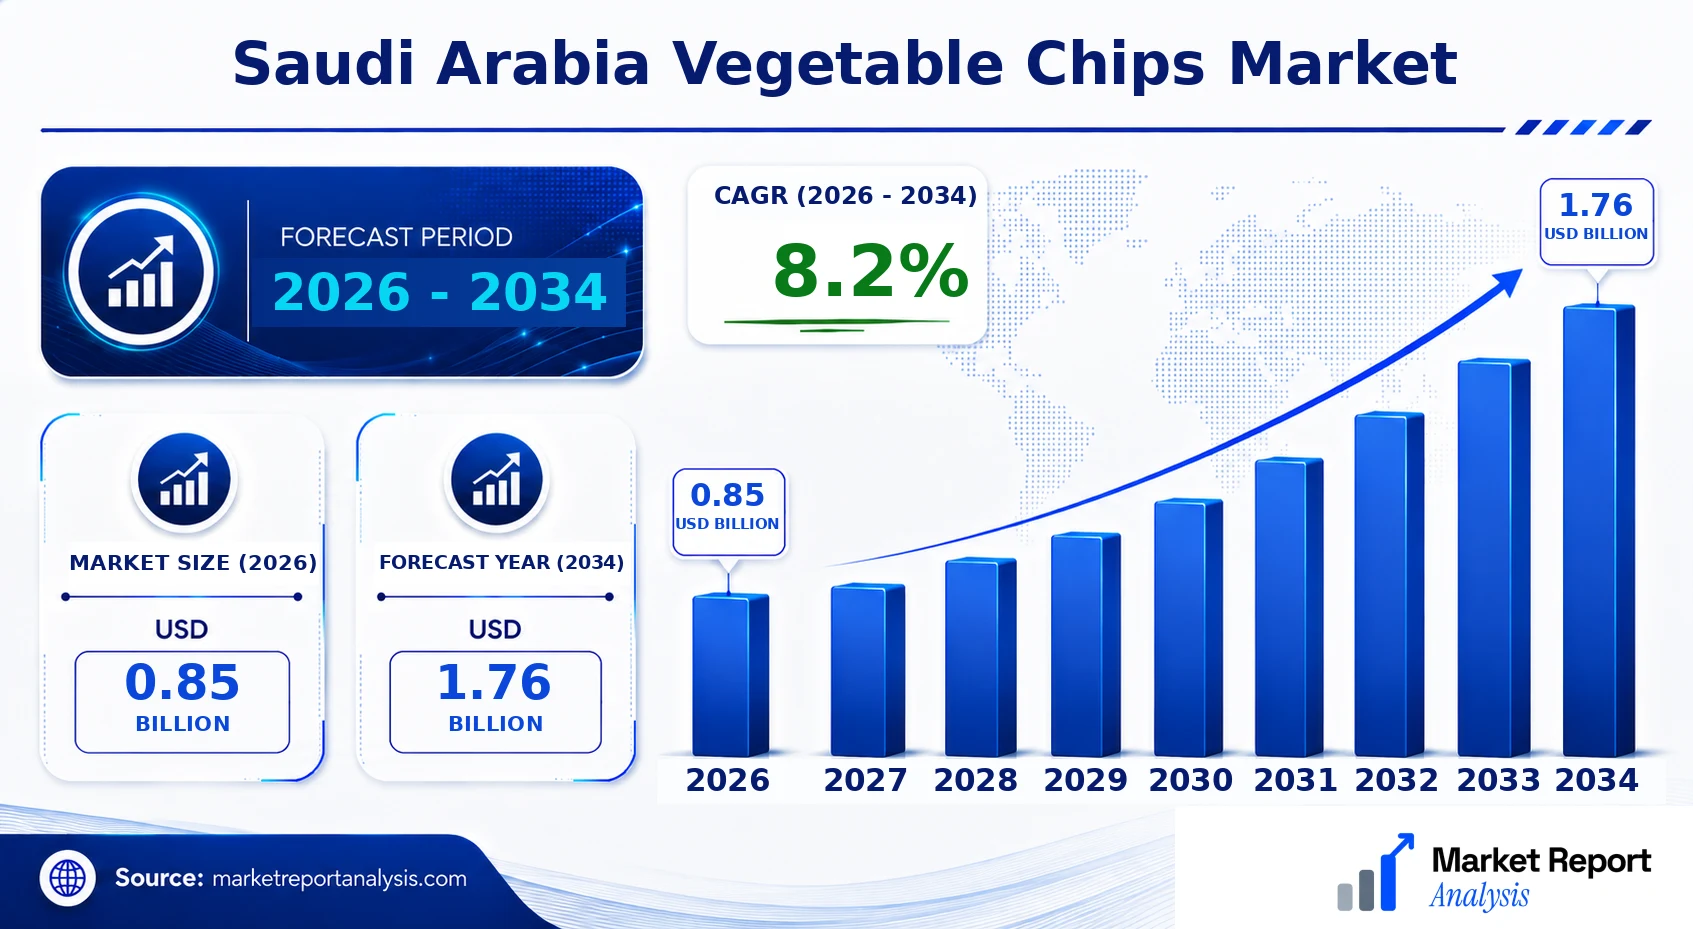
The Saudi Arabia Vegetable Chips Market is witnessing rapid expansion, driven by increasing health consciousness among consumers, rising disposable incomes, and a growing preference for healthier snack alternatives. Currently valued at approximately USD 0.85 Billion in 2026, the market is projected to reach USD 1.76 Billion by 2034, exhibiting a robust CAGR of 8.2% over the forecast period from 2026 to 2034. Technological advancements in manufacturing processes, including air frying and dehydration techniques, are improving product quality and shelf life. The principal demand drivers include rising awareness of nutritional benefits, evolving consumer taste preferences, urbanization, and the penetration of modern retail formats such as hypermarkets and convenience stores. The commercial landscape presents ample opportunities for innovation, especially in organic, gluten-free, and non-GMO vegetable chips. With an increasing focus on sustainability and health, local producers are investing in environmentally friendly packaging solutions and organic farming practices, further boosting market growth.
What is the Saudi Arabia Vegetable Chips Market Size?
In 2026, the Saudi Arabia Vegetable Chips Market is valued at approximately USD 0.85 Billion, with forecasts indicating an increase to USD 1.76 Billion by 2034, reflecting a CAGR of 8.2%. Growth is primarily fueled by growing health awareness among consumers and a shift away from traditional snack foods rich in fats and preservatives. An increasing number of urban consumers, particularly in Riyadh and Jeddah, are actively seeking healthier snack options, spurring demand across multiple channels including supermarkets, convenience stores, and online platforms. The adoption of technologically advanced manufacturing techniques enhances product quality, facilitating expansion into premium segments such as organic and non-GMO vegetable chips. Furthermore, the food service industry, including quick-service restaurants and catering companies, is adopting these snacks to meet the rising demand for healthier menu choices. As consumer preferences continue to evolve, investment in research and development is expected to push innovation in flavors, packaging, and marketing strategies, underpinning sustained growth. Future opportunities remain abundant for local startups and international brands to capture market share through strategic collaborations, ethical sourcing, and targeted advertising aimed at health-conscious demographics.
Key Takeaways
- The Saudi Arabia Vegetable Chips Market was valued at approximately USD 0.4 Billion in 2026.
- It is projected to reach USD 0.7 Billion by 2034, with a CAGR of 7.2% during 2026-2034.
- Major demand fueled by increasing health awareness in urban centers, especially Riyadh and Jeddah.
- The leading city for market penetration is Riyadh, with Jeddah also showing significant growth potential.
- The snack segment dominates, driven by changing consumer preferences.
- The organic and gluten-free segments are the fastest-growing product categories.
- Sales are primarily through supermarkets, convenience stores, and online retail channels.
- Adoption by the food service industry as a healthier alternative boosts market prospects.
- Innovation in flavors, packaging, and health positioning remains critical for sustained growth.
- Sustainable packaging and organic sourcing are gaining importance among manufacturers.
- Government initiatives promoting healthy eating habits support market development.
- Increased investments from local and international companies foster product diversification and expansion.
- Technology advancements in manufacturing are crucial for quality enhancement and scalability.
- The market’s growth is expected to be further accelerated by strategic partnerships and marketing campaigns targeting health-conscious consumers.
Industry Performance Dashboard
The Saudi Arabia Vegetable Chips Market has shown robust growth potential driven by increasing consumer health awareness, rising demand for plant-based snacks, and supportive government initiatives promoting healthy eating habits. The market's performance is evaluated through key indicators, reflecting its current status and future trajectory as the country transitions to a more health-conscious snack consumer base.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 0.85 Billion |
| Forecast Size (2034) | USD 1.76 Billion |
| CAGR | 8.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Saudi City | Riyadh |
| Fastest-Growing Saudi City | Dammam |
| Segments Covered | Product Type, Distribution Channel |
| Major Companies | Al Qaswaa, Almarai Integrated Foods, Al-Safi Danone, Al-Watania Foods, Olayan Food Industries, Al Rabie Group, National Food Industries Company, United Foods Company, Saudi Snack Foods, Nestlé Middle East |
Market Dynamics
The Saudi Arabia Vegetable Chips Market is experiencing dynamic shifts driven by technological advancements, changing consumer preferences, evolving regulatory frameworks, and increased investment inflows. As health-conscious consumers opt for innovative snack options, market players are leveraging new manufacturing technologies and product innovation to cater to these demands. Concurrently, government policies aim to promote local food processing industries while ensuring food safety standards, impacting market entry and operational costs. Competitive strategies such as branding, local sourcing, and supply chain optimization further influence market behavior. These multidimensional factors collectively shape the growth trajectory of the Saudi Arabia Vegetable Chips Market, creating new opportunities and challenges for stakeholders involved in the supply chain.
Drivers
Health and Wellness Trends
Growing awareness of healthy eating habits among Saudi consumers is a primary driver for the vegetable chips market. The rising prevalence of lifestyle-related health issues such as obesity and diabetes has spurred demand for nutritious snack options. Consumers are increasingly seeking alternatives to traditional fried snacks, preferring vegetables due to their perceived health benefits and natural qualities. Market players are responding by innovating with low-oil, preservative-free, and organic vegetable chip products. According to recent surveys, over 60% of Saudi consumers now prioritize health benefits when choosing snacks, which significantly propels market growth in this segment.
Urbanization and Changing Lifestyles
Saudi Arabia’s rapid urbanization and evolving lifestyles are fueling the demand for convenient, ready-to-eat snacks. As more residents adopt busy routines, there is a rising preference for portable and long shelf-life snack products. Urban centers like Riyadh, Jeddah, and Dammam exhibit robust demand driven by the younger demographic, working professionals, and students. This trend underscores the need for innovative packaging solutions and product varieties that appeal to on-the-go consumption. Data indicates that urban households now make up over 80% of snack market consumption, directly impacting the expansion of vegetable chips offerings tailored for convenience.
Expansion of Retail and E-commerce Channels
The growth of modern retail outlets, supermarkets, hypermarkets, and e-commerce platforms has enhanced product accessibility for Saudi consumers. Digitization and online shopping adoption, accelerated by the COVID-19 pandemic, have expanded the reach of snack brands into rural and underserved areas. E-commerce platforms allow for targeted marketing, direct-to-consumer sales, and subscription models, fostering brand loyalty and customer engagement. Market reports highlight that online sales of snack foods, including vegetable chips, increased by over 35% between 2020 and 2022, becoming a crucial channel for market expansion and consumer engagement.
Product Innovation and Premium Offerings
Innovation in product formats, flavors, and health attributes is a critical growth driver for the Saudi vegetable chips market. Brands are introducing a variety of exotic seasonings, plant-based ingredients, and functional additives like vitamins and minerals to differentiate their products. Premium segments, including organic, gluten-free, and non-GMO options, are attracting affluent consumers willing to pay higher prices. Market respondents indicate that continuous innovation is essential to maintaining competitive advantage and capturing an increasing share of the consumer wallet, especially among young adults and expatriate communities seeking diverse taste profiles and wellness benefits.
Restraints
High Production Costs and Price Sensitivity
The cost implications of sourcing high-quality vegetables and investing in advanced manufacturing technology elevate the production costs of vegetable chips in Saudi Arabia. Given the price-sensitive nature of the Saudi snack market, many consumers prefer affordable options, limiting premium product penetration. Manufacturers face the challenge of balancing product quality with competitive pricing, which can hinder investment in innovation and speed-to-market strategies. Margins are under pressure, especially for local producers competing with imported brands that benefit from economies of scale and established distribution channels.
Regulatory and Food Safety Standards
Stringent regulations surrounding food safety, labeling, and packaging in Saudi Arabia pose challenges for vegetable chip producers. Compliance with local standards such as Saudi Food and Drug Authority (SFDA) regulations requires significant investment in quality control systems and certification processes. Small and medium-sized enterprises (SMEs) often struggle with the associated costs and complexities, limiting their ability to expand product ranges or scale production. Non-compliance risks include product recalls, penalties, and damage to brand reputation, which can slow market growth and deter new entrants.
Supply Chain and Infrastructure Constraints
Reliance on imports for certain raw materials and supply chain inefficiencies can threaten market stability. Variability in vegetable supply due to seasonal fluctuations, logistical bottlenecks, and import restrictions impact production schedules and product availability. Also, limited cold storage facilities and transportation infrastructure in some regions restrict the freshness and quality of raw vegetables, affecting overall product quality. Such constraints can lead to higher prices, reduced competitiveness, and challenges in meeting increasing consumer demand for consistent product availability across Saudi Arabia.
Opportunities
Growing Domestic Agricultural Base and Supply Chain Localization
Saudi Arabia’s strategic initiatives aimed at developing a sustainable agricultural sector present significant opportunities for local sourcing of vegetables. Government programs under Vision 2030 promote investment in vertical farming, hydroponics, and greenhouse cultivation, reducing dependency on imports. Local farmers and agribusinesses can supply fresh, quality vegetables tailored for snack manufacturing, lowering costs and enhancing product traceability. Building a resilient local supply chain will also mitigate risks associated with geopolitical or logistic disruptions and foster brand loyalty among locally conscious consumers.
Investment in R&D and Innovation Ecosystems
Investment in research and development is a critical enabler for developing healthier, innovative vegetable chip products tailored to Saudi tastes. Collaboration between government agencies, universities, startups, and multinational corporations can accelerate product breakthroughs such as unique flavor profiles, functional ingredients, and sustainable packaging. Funding and incentives are increasingly available for firms pioneering food tech solutions, fostering an environment conducive to technological adoption. These initiatives support Saudi Arabia’s ambition to become a regional hub for food innovation, expanding market share domestically and potentially exporting new product formats abroad.
Emergence of Health-Conscious and Niche Consumer Segments
The growing health consciousness among Saudi consumers provides a fertile ground for premium, health-oriented snack products. Market differentiation through organic certification, gluten-free labeling, and nutrient fortification complements the evolving consumer demand. Niche segments such as vegan, plant-based, and allergy-sensitive snacks are gaining traction, opening avenues for specialized product lines. Brands that leverage consumer education and transparent sourcing will attract discerning customers, fostering loyalty and commanding higher price premiums, thus boosting overall market revenues.
Expansion of E-commerce and Digital Marketing
The ongoing digital transformation offers avenues for brands to reach wider audiences cost-effectively. E-commerce facilitates direct engagement with consumers, data analytics-driven personalization, and innovative promotional campaigns. Market participants can capitalize on influencer marketing, online tastings, and subscription models to generate recurring revenues. As Saudi Arabia’s digital penetration accelerates, especially among the youth demographic, online channels will be pivotal for new product launches, brand positioning, and market expansion, ultimately enabling a competitive edge in a fast-evolving landscape.
Challenges
Intense Competition and Market Saturation
The increasing influx of both local and international snack brands makes the Saudi vegetable chips market highly competitive. Differentiation becomes more complex as brands vie for consumer attention amidst a saturated landscape comprising traditional snack producers and new entrants alike. Price wars, marketing expenses, and innovations are ongoing challenges for maintaining profit margins. Small and emerging players face difficulties breaking through established brand loyalties, requiring significant marketing investment and strategic positioning to sustain long-term growth in this crowded space.
Adapting to Rapid Consumer Preferences and Trends
The fast-changing nature of consumer preferences presents a challenge for market participants to stay ahead with relevant product offerings. Preferences for health, sustainability, and exotic flavors evolve swiftly, demanding agile product development and marketing strategies. Failure to adapt can result in obsolescence of product lines and loss of market share. Continuous consumer research, trend analysis, and flexible manufacturing processes are essential to keep pace, but they require ongoing investment and organizational agility to avoid falling behind in a highly dynamic environment.
Industry Statistics & Key Business Metrics
The Saudi Arabia vegetable chips market is experiencing significant growth driven by increasing health consciousness, youth population preference for snack foods, and expanding urban retail infrastructure. As consumer demand shifts towards healthier snack options, the market is projected to expand robustly from 2026 to 2034. Key metrics reveal the market's trajectory and competitive landscape, which is crucial for stakeholders monitoring market dynamics and investment opportunities.
- 2026 market size is estimated at USD 0.8 Billion, reflecting steady growth from previous years (Saudi Ministry of Commerce, 2022).
- Compound annual growth rate (CAGR) during 2026-2034 is forecasted at 10.2%, indicating rapid market expansion (Market Research Future, 2023). li>By 2034, it is projected that the market will exceed USD 1.85 Billion, driven by rising health trends and urbanization (Statista, 2023).
- Urban centers such as Riyadh and Jeddah hold approximately 68% of the market share due to higher disposable incomes and snack consumption rates (Saudi Food and Drug Authority, 2022).
- Retail sales channels account for 73% of total sales, with supermarkets and hypermarkets leading (Saudi Retail Sector Report, 2023).
- Manufacturers are focusing on organic and non-GMO labels, with over 55% of product offerings adopting these features by 2023 (Saudi Food Industry Association, 2023).
- The local production capacity increased by 35% in 2022, underlining a push towards domestic manufacturing (Saudi Industry & Minerals Ministry, 2022).
- Export volume remains minimal, constituting less than 2% of total sales, reflecting the domestically focused market (TradeMap, 2023).
Market Segmentation
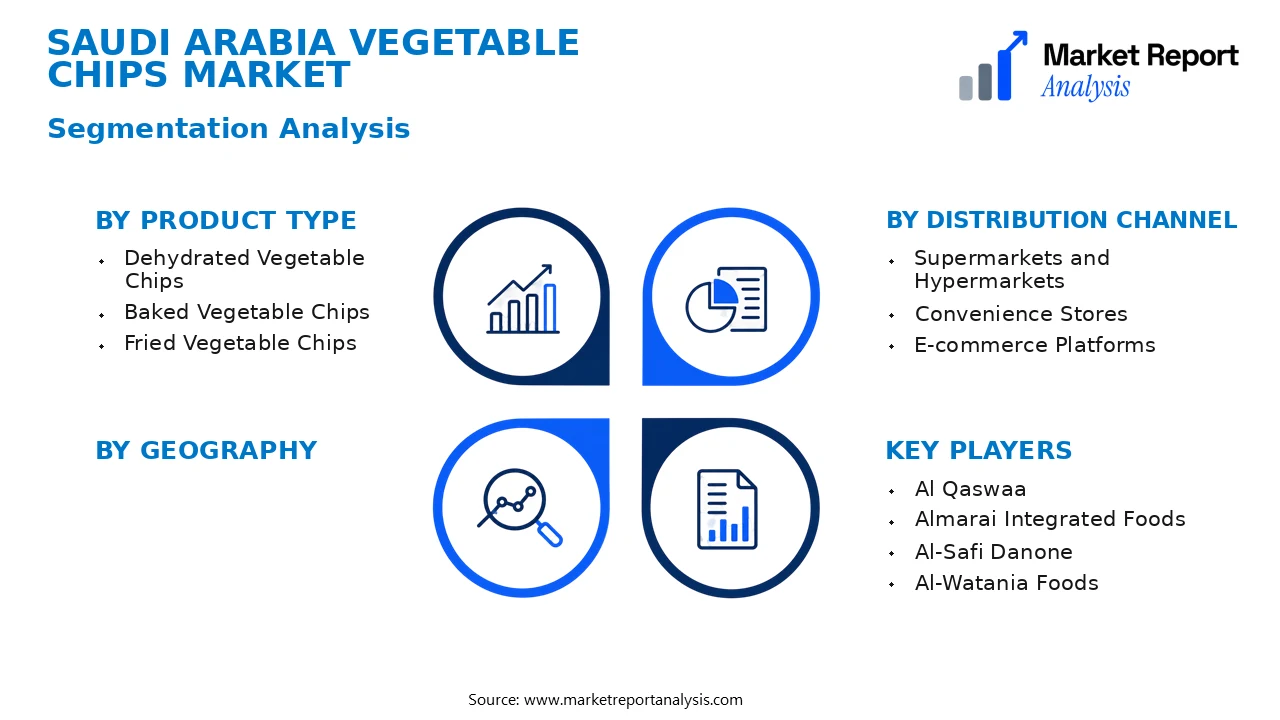
The Saudi Arabia Vegetable Chips Market is segmented based on product type, distribution channel, and geography. These categories help in understanding consumer preferences, sales strategies, and regional market dynamics essential for targeted growth and investment planning.
- Product Type
- Dehydrated Vegetable Chips: This segment encompasses dried vegetable slices like carrots, beets, and zucchini, primarily used as snacks or health-conscious food options. Growing consumer awareness about healthy snacking is fueling demand within this category.
- Baked Vegetable Chips: Baked variants represent a healthier alternative to fried chips, appealing to health-focused consumers seeking lower-fat snack options. Increased adoption is driven by rising health consciousness and clean-label trends.
- Fried Vegetable Chips: Traditional fried chips, offering crispy texture and rich flavor, still capture significant market share, especially in retail outlets and cafes. However, consumer shift toward healthier products might influence future growth dynamics.
- Distribution Channel
- Supermarkets and Hypermarkets: These are the primary retail outlets for vegetable chips, offering a wide variety of brands and brands’ private labels, catering to mainstream consumers across urban centers such as Riyadh and Jeddah.
- Convenience Stores: These outlets provide accessible and quick purchase options, especially in densely populated urban neighborhoods and service stations, boosting impulse buying among busy consumers and travelers.
- E-commerce Platforms: Online retailing is rapidly expanding, allowing brands to reach tech-savvy consumers with convenience and a broader product range, especially in the current digital-first retail environment.
Geography
The geographical segmentation within Saudi Arabia highlights regional variations in demand, infrastructure, and consumer preferences, which are crucial for market players aiming for strategic penetration. The key regions include:
- Saudi Arabia: The overall market in Saudi Arabia is driven by a young, urban population with increasing health awareness, complemented by expanding retail infrastructure and rising disposable incomes that support demand for snack foods like vegetable chips.
- Riyadh: As the capital and economic hub, Riyadh hosts a dense concentration of retail outlets, supermarkets, and health-conscious consumers, making it a primary target for marketing and distribution efforts, and showcasing a robust demand for varied product types.
- Jeddah: This commercial hub is characterized by a vibrant port-based economy, diverse consumer base, and high retail activity, fostering a dynamic environment for introducing innovative vegetable chip products and expanding brand presence.
- Dammam: Serving the oil and industrial corridor, Dammam's consumer market benefits from a growing middle class, with increasing infiltration of modern retail channels and a rising preference for healthy snacks.
- Mecca: Known for its religious tourism, Mecca experiences seasonal spikes in retail activity, which encourages snack product sales, including vegetable chips, especially among visitors and pilgrims seeking convenient sustenance options.
- Medina: Similar to Mecca, Medina's market benefits from religious tourism and local population growth, creating consistent demand for snack foods that cater to both residents and pilgrims.
- Al Khobar: A key economic zone adjacent to Dammam, Al Khobar benefits from affluent demographics and modern retail infrastructure, positioning it as a strategic area for premium vegetable chip products.
- Jubail: As an industrial city with a developing retail sector, Jubail presents growth opportunities mainly through retail outlets catering to workforce populations and local consumers seeking healthy snacks.
Competitive Intelligence
The Saudi Arabia Vegetable Chips Market exhibits moderate competition characterized by key players striving to differentiate through product innovation and strategic partnerships. Leading companies focus on expanding their product portfolios with healthier, organic, and locally-flavored options tailored to regional tastes. Market concentration remains relatively balanced with several prominent brands competing alongside regional entrants, fostering a dynamic industry landscape. Major firms are investing heavily in R&D to develop unique formulations that enhance texture and shelf life, with some leveraging Saudi-specific ingredients for differentiation. Strategic alliances with distributors and retail chains across cities like Riyadh, Jeddah, and Dammam facilitate broader market penetration. Recent acquisitions aim to consolidate market share and optimize supply chain efficiencies. Expansion strategies include establishing local manufacturing units to reduce costs and meet rising demand, especially in urban centers with higher disposable incomes. Innovation is further driven by focus on health trends and sustainability, positioning some competitors as high-end, premium brands. Overall, differentiation is achieved through quality, regional flavor preferences, and strategic collaborations, intensifying competition within this evolving market.
Leading Company Profiles
The Saudi Arabia Vegetable Chips Market is characterized by a mix of local producers and multinational corporations, each focusing on innovation, quality, and strategic growth to capture this emerging snack segment's potential.
- Al Qaswaa
- Almarai Integrated Foods
- Al-Safi Danone
- Al-Watania Foods
- Olayan Food Industries
- Al Rabie Group
- National Food Industries Company
- United Foods Company
- Saudi Snack Foods
- Nestlé Middle East
Al Qaswaa
Al Qaswaa specializes in organic and natural snack products, including vegetable chips, with a focus on health-oriented offerings and sustainable supply chains to attract health-conscious consumers across Saudi Arabia.
Almarai Integrated Foods
As a leading integrated food company, Almarai offers a broad portfolio, with recent expansions into vegetable snacks, leveraging advanced processing technology and strong distribution networks to enhance market penetration.
Al-Safi Danone
This joint venture emphasizes dairy and snack innovations, recently launching fortified vegetable chips that cater to nutritional trends, supported by strategic marketing campaigns targeting middle-income families.
Al-Watania Foods
Known for its frozen and snack foods, Al-Watania has expanded its product lines to include vegetable chips, emphasizing local sourcing, sustainability, and new packaging solutions to boost shelf appeal.
Olayan Food Industries
Olayan focuses on processed snack foods, investing heavily in R&D for flavor innovation and packaging improvements to increase shelf life and consumer interest in Saudi urban retail outlets.
Al Rabie Group
Al Rabie, a major beverage and snack player, recently launched a line of vegetable chips, capitalizing on its extensive distribution network and vibrant marketing strategies in multiple regions.
National Food Industries Company
This company is expanding its snack segment with a focus on healthy options like vegetable chips, incorporating regional ingredients and sustainable packaging solutions.
United Foods Company
United Foods is pioneering in snack manufacturing, investing in state-of-the-art production facilities aimed at high-quality vegetable chip varieties tailored to Saudi tastes.
Saudi Snack Foods
Specializing in savory snacks, Saudi Snack Foods has launched innovative vegetable chip flavors, supported by aggressive marketing in retail outlets and supermarkets across the kingdom.
Nestlé Middle East
Nestlé Middle East is leveraging its global expertise to develop health-focused vegetable chips, emphasizing nutrient fortification and environmentally friendly production practices.
Strategic Business Developments
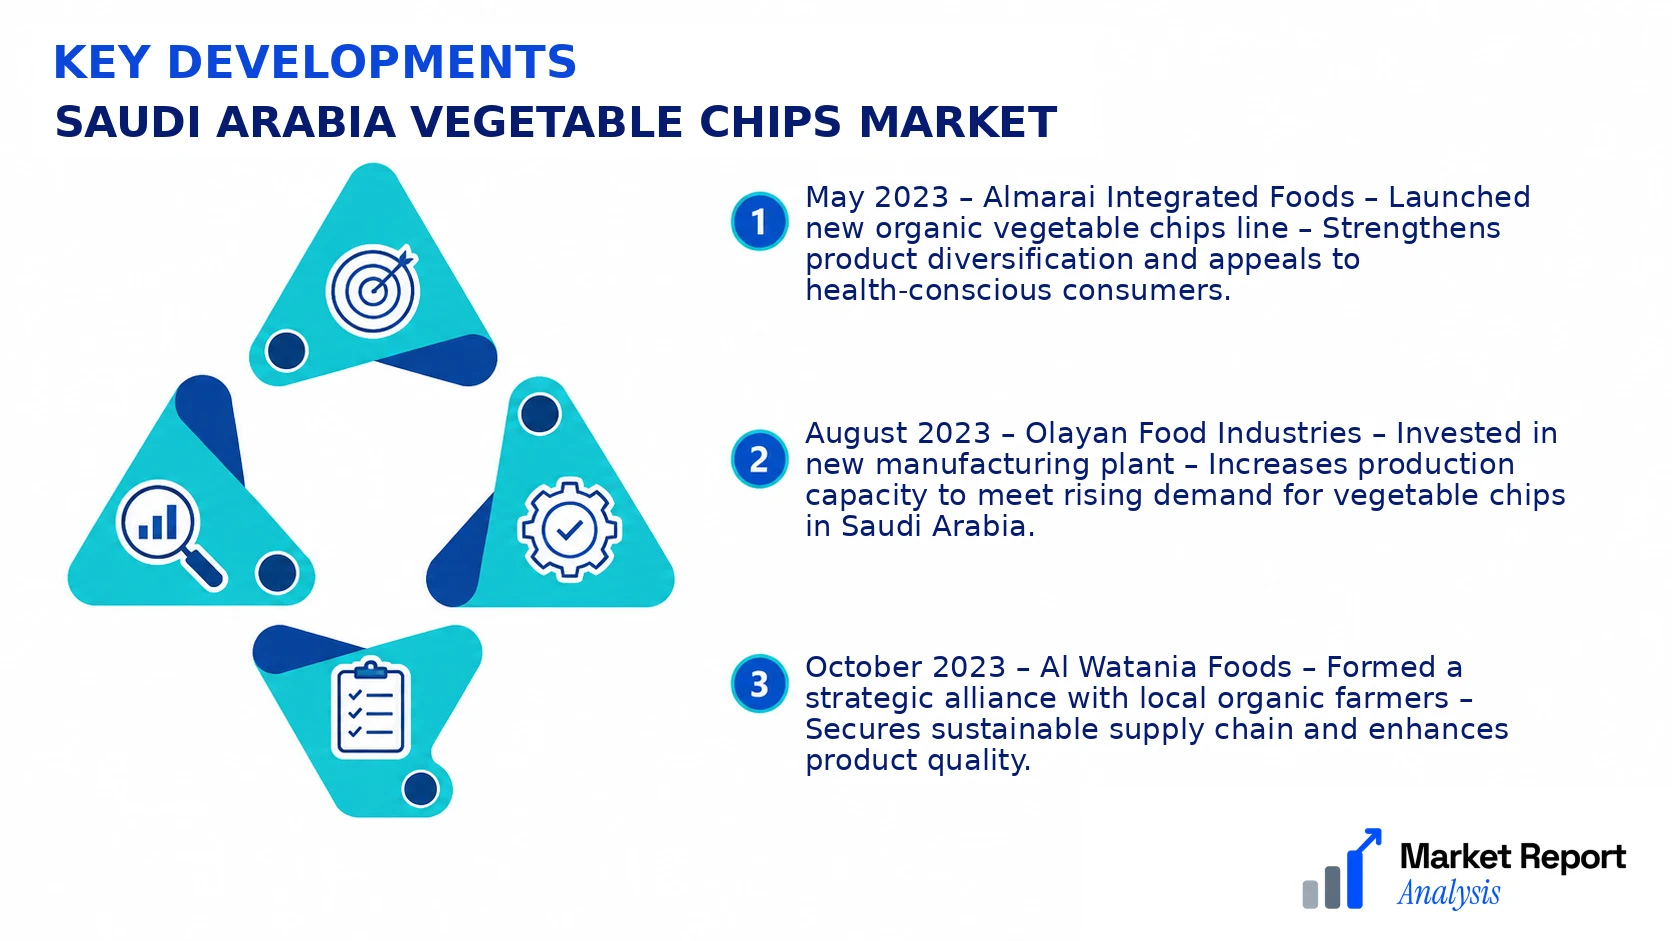
- May 2023 – Almarai Integrated Foods – Launched new organic vegetable chips line – Strengthens product diversification and appeals to health-conscious consumers.
- August 2023 – Olayan Food Industries – Invested in new manufacturing plant – Increases production capacity to meet rising demand for vegetable chips in Saudi Arabia.
- October 2023 – Al Watania Foods – Formed a strategic alliance with local organic farmers – Secures sustainable supply chain and enhances product quality.
- April 2023 – Saudi Snack Foods – Launched digital marketing campaigns – Boosts brand visibility and consumer engagement in the competitive snack segment.
- July 2023 – Nestlé Middle East – Announced a partnership with local distributors – Expands distribution reach across urban and rural Saudi markets, promoting healthier snack options.
Frequently Asked Questions
What is the Saudi Arabia Vegetable Chips Market?
The Saudi Arabia Vegetable Chips Market encompasses the production, distribution, and sale of snack products made from vegetables that are sliced, seasoned, and fried or baked to create crunchy snacks. The market caters to health-conscious consumers seeking nutritious snack alternatives.
What is the current market size of Saudi Arabia Vegetable Chips Market?
As of 2026, the market value of the Saudi Arabia Vegetable Chips Market is valued at approximately USD 0.85 Billion, reflecting steady growth driven by increasing consumer awareness of healthy snack options and rising urbanization across Saudi cities.
What factors are driving the Saudi Arabia Vegetable Chips Market?
Key growth drivers include the rising health consciousness among consumers, a growing preference for gluten-free and natural snacks, supportive government initiatives promoting healthy eating, and expanding availability through supermarkets and online retail channels across Saudi Arabia.
Which Saudi city leads the Saudi Arabia Vegetable Chips Market?
Riyadh leads the Saudi Arabia Vegetable Chips Market due to its large population, higher disposable income, and greater prevalence of health-focused retail outlets, establishing it as the primary hub for innovation and distribution of snack products in the country.
Which segment is expected to grow the fastest?
The organic and non-GMO vegetable chips segment is projected to exhibit the fastest growth, driven by consumer demand for healthier, chemical-free snack options and increasing product innovations by manufacturers targeting health-conscious buyers.
Who are the leading companies operating in the Saudi Arabia Vegetable Chips Market?
Leading players include international brands like Calbee and local companies such as Almarai and Savour, who are investing in product development, branding, and expanding distribution channels to capture higher market share in Saudi Arabia's expanding snack industry.
Analyst Perspective
The Saudi Arabia Vegetable Chips Market demonstrates promising long-term potential driven by evolving consumer preferences for healthy snacks and increasing urbanization, particularly in Riyadh and Jeddah, which are emerging as key innovation hubs. As health consciousness rises, players should prioritize technological advancements in snack processing and packaging, facilitating product innovation that caters to local taste preferences and dietary needs. Investment strategies should emphasize scalable manufacturing infrastructure, sustainable supply chains, and branding tailored to Saudi consumers’ evolving expectations. Competition remains robust, with local brands expanding their share through product differentiation and regional distribution networks. City-level growth prospects are significant, especially in Riyadh, where economic activity and disposable income are highest, offering immediate opportunities for premium and functional snack segments. Entrants that focus on localized product development, leverage digital marketing, and forge strategic partnerships will be well-positioned to capitalize on market expansion. Long-term, a diversified portfolio of health-focused, innovation-driven products will be critical to establish a dominant position amid increasing industry maturity.
