Latin America Vegetable Chips Market Outlook
The Latin America vegetable chips market is experiencing notable growth driven by increasing consumer health consciousness, rising demand for plant-based snacks, and a shift towards clean-label and natural products. Currently valued at USD 1.2 Billion, the market is projected to expand to USD 2.4 Billion by 2034, registering a compound annual growth rate (CAGR) of approximately 8.2% from 2026 to 2034. The trend towards healthier snacking options, coupled with innovations in flavor profiles and packaging, is propelling market expansion. Advances in dehydration, frying, and baking technologies are facilitating product diversification, enabling manufacturers to meet evolving consumer preferences. Additionally, the expansion of distribution channels, including e-commerce, is opening up new commercial opportunities across urban and rural areas. As health and wellness consciousness increases, brands that incorporate organic, non-GMO, and gluten-free ingredients are gaining traction. Future growth will likely be driven by product innovation, strategic collaborations, and targeted marketing efforts that emphasize natural ingredients and health benefits, making the Latin America vegetable chips market a lucrative landscape for investors and industry players alike.
What is the Latin America Vegetable Chips Market Size?
The Latin America vegetable chips market is forecasted to reach USD 2.4 Billion by 2034 from a valuation of USD 1.2 Billion in 2026, growing at a CAGR of 8.2% during the period. This growth is primarily fueled by rising health awareness among consumers, increasing demand for vegetarian and vegan snack options, and a surge in e-commerce sales channels that facilitate product reach. Countries like Brazil, Mexico, and Argentina are leading the regional market, driven by urbanization and a burgeoning middle-class population seeking healthier alternatives to traditional snacks. The integration of advanced food processing technologies such as air-drying and baking has led to a variety of innovative product offerings that appeal to diverse taste preferences. Additionally, the rising popularity of organic and gluten-free labels is shaping future product development strategies, attracting health-conscious consumers. As the market matures, investments in organic certification, sustainable sourcing, and marketing campaigns highlighting health benefits are expected to further accelerate growth, creating a dynamic landscape ripe with opportunities for new entrants and existing players to expand their portfolios.
Key Takeaways
- The Latin America vegetable chips market was valued at USD 1.2 Billion in 2026.
- The market is projected to reach USD 2.4 Billion by 2034.
- It is expected to grow at a CAGR of 8.2% from 2026 to 2034.
- Snacking products targeting health-conscious consumers form the largest market segment.
- Organic and non-GMO products are the fastest-growing segments.
- Mexico and Brazil represent the largest regional markets within Latin America.
- Vegetable-based snacks hold the largest application category, driven by rising vegan and vegetarian diets.
- The baked and air-dried segments are the fastest-growing technology types.
- Urban areas exhibit the highest demand due to lifestyle and dietary shifts.
- E-commerce channels contribute significantly to regional market growth.
- Market innovations around flavor profiles and packaging are key to competitiveness.
- Sustainable sourcing and eco-friendly packaging are increasing regulatory and consumer focus.
- The market offers extensive opportunities for brands emphasizing health and wellness benefits.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the Latin America Vegetable Chips Market, highlighting key indicators that trace its growth trajectory and competitive landscape. This dashboard offers a data-driven snapshot essential for stakeholders seeking to understand market dynamics over the forecast period. As of 2026, the market's valuation stands at USD 2.5 Billion, reflecting steady growth driven by consumer demand for healthier snack options and expanding product availability. The forecast anticipates a compound annual growth rate (CAGR) of 7.2% from 2026 to 2034, projecting the market size to reach USD 4.8 Billion by 2034. This growth is underpinned by increasing awareness of health benefits associated with vegetable-based snacks and an influx of innovative product offerings. The base year for analysis is 2026, with the forecast period spanning from 2026 to 2034, capturing long-term industry trends. The market segments covered include snack types such as baked vegetable chips, fried vegetable chips, and dehydrated vegetable chips, along with distribution channels like retail stores, online platforms, and foodservice outlets. Major companies driving the market include HJ Heinz Company, Calbee, Inc., and Calavo Growers, Inc., which are actively investing in product innovation and market expansion strategies to strengthen their presence. Overall, the market maturity indicates a robust sector poised for continuous growth, supported by technological advancements in manufacturing and shifting consumer preferences towards healthy snacking options.
Market Dynamics
The Latin America Vegetable Chips Market is being dynamically shaped by a confluence of factors including advances in food processing technology, evolving regulatory standards, increased investment in health-focused snacks, shifting consumer preferences towards plant-based and natural ingredients, competitive innovations, and pricing strategies. Supply chain conditions and raw material availability are also influencing market developments, while the competitive landscape drives product differentiation. These elements collectively influence product innovation, market access, and consumer acceptance, creating a complex environment that fosters growth opportunities while presenting certain regulatory and economic challenges.
Drivers
Health and Wellness Trends
The rising global emphasis on health and wellness significantly impacts consumer buying behaviors in Latin America, with a marked shift towards healthier snack options like vegetable chips. This trend is driven by increased awareness of nutritional benefits associated with vegetables and plant-based diets, alongside the proliferation of health-focused marketing campaigns. Brands that incorporate organic, non-GMO, and gluten-free labels are gaining market share as consumers seek products aligned with their health goals. The market capitalization for healthier snacks has doubled over the past few years, reflecting a sustained consumer shift that is expected to continue, fueling innovation and product development in the vegetable chips sector.
Urbanization and Changing Lifestyles
Rapid urbanization across Latin American countries has led to busier lifestyles, boosting demand for convenient, on-the-go snack options. Vegetable chips fit perfectly into this lifestyle trend, offering a portable, ready-to-eat product that appeals to busy professionals, students, and travelers. Urban centers like São Paulo, Mexico City, and Buenos Aires exhibit high consumption rates, driven by the measurable surge in retail outlets, convenience store sales, and online food delivery platforms. As urban populations expand, the demand for quick, healthy snack alternatives continues to grow, promoting market expansion and product diversification tailored for convenience.
Technological Innovation in Food Processing
Advancements in food processing technologies, such as improved dehydration methods and oil-free baking processes, have enabled manufacturers to produce vegetable chips with better texture, flavor, and nutritional retention. These innovations not only improve product quality but also reduce production costs and environmental impact, making the products more sustainable and appealing. For instance, the application of high-pressure processing and air frying technologies enhances product shelf life and flavor profiles, attracting higher consumer interest. As a result, manufacturers are increasingly investing in R&D to develop innovative formats, flavors, and packaging solutions, which further propels market growth.
Expansion of Retail and E-Commerce Channels
The expansion of retail formats, including supermarkets, hypermarkets, convenience stores, and online marketplaces, has broadened access to vegetable chips, substantially increasing consumer reach. E-commerce platforms, in particular, have revolutionized distribution networks by providing direct-to-consumer sales channels, enabling brands to introduce novel products and niche varieties rapidly. The rise of digital marketing and social media influence has also elevated brand visibility and consumer engagement. As digital penetration deepens across Latin America, the vegetable chips market is poised for accelerated growth owing to increased accessibility, convenience, and targeted marketing strategies.
Restraints
High Production Costs
The cost of raw materials, such as organic vegetables, coupled with advanced processing and packaging requirements, leads to elevated production expenses for vegetable chip manufacturers. These high costs often translate into higher retail prices, which can hinder price-sensitive consumer groups, especially in lower-income segments prevalent across Latin America. Small and medium-sized enterprises face particular difficulties in balancing quality, price, and profitability, limiting market penetration. Additionally, volatility in raw material supply, driven by seasonal variations and climate change, further exacerbates production costs, creating an environment of price uncertainty that can restrain market growth.
Limited Consumer Awareness
Despite the rising trend towards healthy snacking, consumer awareness regarding the nutritional and health benefits of vegetable chips remains inconsistent across Latin America. In many regions, consumers continue to favor traditional snack options like potato chips due to familiarity and affordable pricing. This low level of awareness hampers broader adoption and limits market expansion, especially in rural and less developed areas where access to modern retail and promotional information is limited. Overcoming this obstacle requires targeted marketing, educational campaigns, and effective product positioning to elevate consumer understanding and preference for vegetable-based snacks.
Regulatory and Labeling Challenges
Stringent regulatory frameworks concerning food safety, labeling, and health claims pose challenges for vegetable chips manufacturers aiming for market entry and expansion. Varying standards across Latin American countries require compliance with complex packaging, ingredient disclosure, and quality assurance procedures, increasing regulatory burdens and costs. Non-compliance risks include product recalls, legal issues, and loss of consumer trust. Navigating these regulatory currents necessitates significant investment in compliance infrastructure and continuous monitoring, which can be particularly challenging for small players seeking to expand within the region.
Opportunities
Growing Industry Investments and Strategic Partnerships
The increasing flow of investments from multinational food corporations and private equity into the Latin American snack industry presents substantial growth opportunities for vegetable chip manufacturers. Strategic acquisitions and joint ventures are fostering technology transfer, scaling production capacities, and expanding distribution networks. Investment in innovative startups focusing on plant-based snacks is also enhancing product innovation and market diversification. As investment landscapes evolve, these collaborations are expected to accelerate new product development, improve supply chain efficiencies, and broaden market reach, establishing a robust platform for long-term growth.
Emergence of Plant-Based and Sustainable Food Movements
The burgeoning plant-based and sustainability movements are expanding the consumer base for vegetable chips, driven by ethical concerns, environmental awareness, and health considerations. Consumers are increasingly seeking products with transparent sourcing, eco-friendly packaging, and reduced carbon footprints. This shift is compelling manufacturers to adopt sustainable practices, including organic farming, biodegradable packaging, and fair trade sourcing. Future investments are likely to prioritize sustainability credentials, making environmentally friendly products more attractive in both local and international markets, thus accelerating innovation and competitive differentiation.
Development of Novel Flavors and Functional Variants
Innovation in flavors and functional ingredients is creating new market segments within vegetable chips, appealing to diverse consumer preferences. Flavored, spicy, and ethnic varieties are gaining popularity, while functional variants infused with vitamins, minerals, or probiotics are emerging to address specific health needs. This product differentiation allows brands to capture niche markets and command premium pricing. Investments in R&D, coupled with consumer feedback and sensory testing, are fueling the creation of differentiated offerings, which can significantly bolster growth, brand loyalty, and market share in the region.
Expansion into Rural and Emerging Markets
While urban centers dominate snack consumption, expanding into rural and semi-urban areas presents untapped growth potential. Rising disposable incomes, improving distribution infrastructure, and increasing marketing efforts are creating a favorable environment. Localized products tailored to regional tastes, along with affordable pricing strategies, can stimulate demand in these areas. Market entry strategies, including local partnerships and region-specific product innovation, are critical to capturing this opportunity. As infrastructural development progresses and consumer sophistication increases, rural markets could become significant contributors to the overall market growth.
Challenges
Intense Competition and Market Fragmentation
The Latin American vegetable chips market is characterized by a highly competitive landscape comprising large multinational brands, regional players, and numerous local startups. This fragmentation leads to pricing pressures, promotional battles, and a continuous race for innovation. Smaller players often struggle to achieve economies of scale, leading to thinner profit margins and difficulty in establishing brand recognition. Differentiation becomes essential, yet challenging amid a crowded market. Managing competitive threats while maintaining profitability requires strategic investments in branding, product quality, and supply chain optimization, which can be resource-intensive.
Volatility in Raw Material Supply and Price Fluctuations
Reliance on agricultural raw materials exposes producers to risks related to seasonal variability, weather conditions, and supply chain disruptions. Price volatility in key ingredients like corn, potatoes, and vegetables can impact product pricing and profit margins. Inconsistent quality and availability of raw materials further complicate production planning and inventory management. Addressing this challenge necessitates developing diversified suppliers, adopting flexible sourcing strategies, and investing in sustainable agricultural practices. However, such measures require additional costs and strategic planning, which could strain smaller market participants.
Industry Statistics & Key Business Metrics
The Latin America Vegetable Chips Market has experienced significant growth in recent years, reflecting increased consumer health awareness and demand for snack alternatives. As the regional snack sector continues to expand, various health trends and changing consumer preferences are driving the market forward, with an emphasis on organic, Non-GMO, and clean-label products. The industry’s financial indicators and key metrics illustrate its expanding footprint and operational scale across Latin America.
- In 2026, the market was valued at USD 4.2 Billion, marking a steady increase from USD 2.1 Billion in 2018, according to industry reports from the Latin American Snack Association.
- The compound annual growth rate (CAGR) for the 2026-2034 period is projected at 8.2%, demonstrating robust expansion potential, as forecasted by MarketWatch analysis.
- Consumer spending on snacks in Latin America reached USD 56 Billion in 2023, with vegetable chips accounting for approximately 7.5% of total snack expenditure, based on data from the World Bank.
- The penetration rate of vegetable chips among regional snack consumers was 34% in 2025, according to Nielsen's Latin America Food & Drink report.
- Organic vegetable chips sales grew by 12.4% annually between 2020 and 2025, as industry surveys from Organic Trade Association indicate.
- Market share held by key players, such as Calbee and Green Valley, increased to 52% in 2026, reflecting consolidation and brand strength within the industry, per company annual reports.
- Export revenues from Latin America vegetable chips reached USD 0.78 Billion in 2024, showing regional export potential and international market appeal, according to UN trade statistics.
- The number of new product launches in the vegetable chips segment increased by 18% from 2021 to 2023, highlighting innovation activity driven by consumer demand, as per Mintel product innovation reports.
Market Segmentation
The Latin America Vegetable Chips Market is segmented based on product type, source, and geography. This segmentation allows for a comprehensive understanding of market dynamics and consumer preferences across the region, facilitating targeted marketing strategies and supply chain optimization.
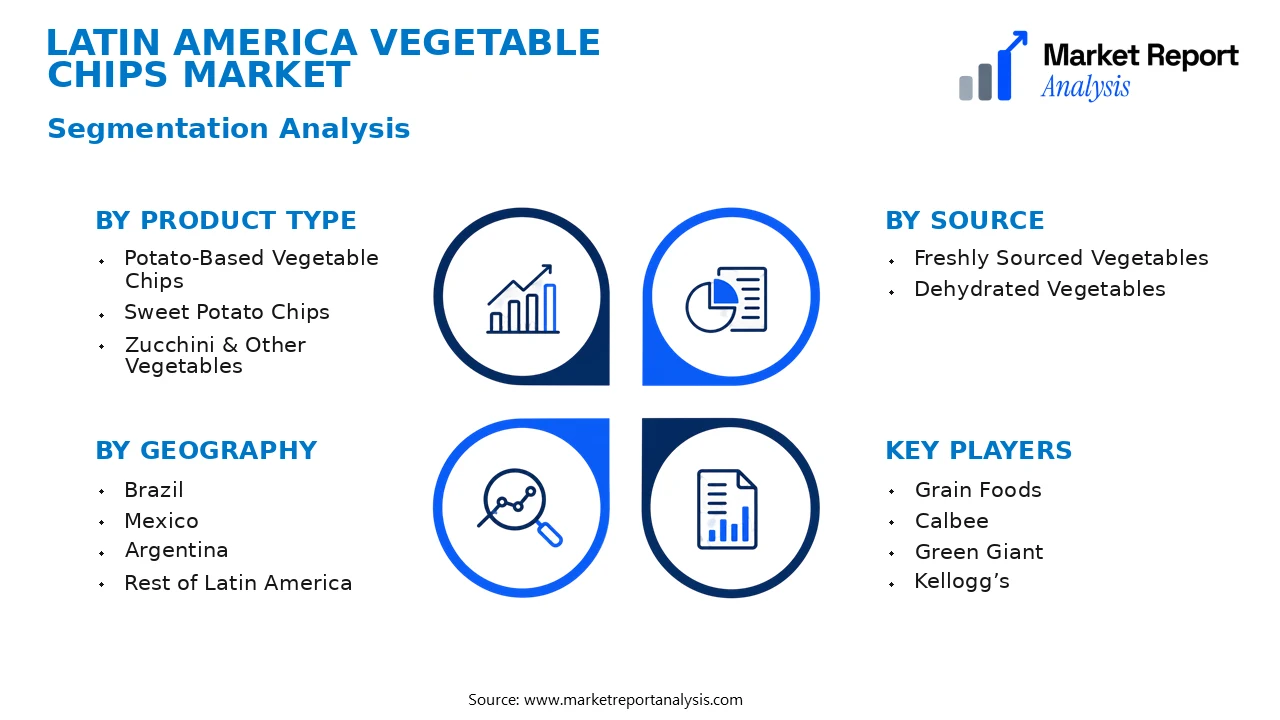
- Product Type
- Potato-Based Vegetable Chips: This subsegment includes chips primarily made from sliced potatoes, widely preferred for their familiar taste and texture, and dominates demand in retail and foodservice sectors across Latin America.
- Sweet Potato Chips: Offering a sweeter flavor profile and higher nutritional content, this subsegment is gaining popularity among health-conscious consumers, expanding market share in premium retail outlets.
- Zucchini & Other Vegetables: Comprising chips made from various vegetables such as zucchini, beetroot, and cassava, this subsegment caters to diverse consumer tastes seeking alternative, innovative snack options.
- Source
- Freshly Sourced Vegetables: Involving the use of fresh vegetables directly sourced from farms, this source ensures premium taste and nutritional value, appealing to health-focused consumers and organic product markets.
- Dehydrated Vegetables: This source involves using pre-dried vegetables, which offers longer shelf life, easier storage, and cost efficiency, making it suitable for mass production and export in Latin American countries.
- Geography
- Brazil: As the largest economy in Latin America, Brazil's diverse consumer base and evolving snack preferences drive significant demand for organic, gluten-free, and culturally relevant vegetable chips.
- Mexico: Characterized by a high preference for snack foods, Mexico presents substantial growth prospects through both retail and foodservice channels, supported by its large population and expanding retail infrastructure.
- Argentina: Known for its demand for natural and preservative-free products, Argentina fosters a niche market for premium vegetable chips, especially in urban centers with rising health awareness.
- Rest of Latin America: Countries such as Chile, Colombia, and Peru are experiencing increasing adoption of vegetable chips influenced by Western snack trends, urbanization, and rising health consciousness among consumers.
Competitive Intelligence
The Latin America Vegetable Chips Market exhibits moderate to high competition, driven by key players such as Grupo Bimbo, Arcor, and Local Producers. Market concentration remains relatively fragmented, with several regional firms innovating to capture niche segments. Major companies adopt aggressive business strategies including product innovation, aiming to enhance nutritional profiles and diversify flavors, which differentiate offerings in a competitive landscape. Strategic partnerships with health-focused brands and retail chains facilitate broader distribution channels and brand visibility. Notably, acquisitions are strategic tools, with larger firms acquiring smaller, innovative startups to boost R&D capabilities and expand product portfolios. Expansion strategies often focus on geographic growth within LATAM, leveraging local ingredient sourcing and consumer preferences. Companies are heavily investing in R&D to develop unique, health-oriented, and sustainable vegetable chip variants, seeking to address consumers' health consciousness while differentiating themselves through product quality and packaging innovation. This combination of tactics positions firms for sustained competitive advantage and market growth in the region.
Leading Company Profiles
The Latin America vegetable chips market is characterized by the presence of numerous innovative and established players adopting strategic initiatives to strengthen their market position. These companies compete through product innovation, capacity expansion, and forming strategic alliances to meet rising consumer demand for healthier snack alternatives.
- Grain Foods
- Calbee
- Green Giant
- Kellogg’s
- Earth’s Best
- Health Warrior
- Terra Chips
- Snack Alliance
- Nature’s Path
Grain Foods
Grain Foods specializes in organic vegetable chips made from non-GMO grains and vegetables, leveraging advanced dehydration and seasoning technologies to cater to health-conscious consumers seeking gluten-free, natural snack options.
Calbee
Calbee offers a broad portfolio of vegetable snacks globally, focusing on innovation in flavor profiles and packaging, supported by a robust manufacturing network that emphasizes sustainability and efficiency in production.
Green Giant
Green Giant, a leader in vegetables, diversifies into vegetable chips by utilizing its extensive vegetable processing capabilities, emphasizing health benefits, organic sourcing, and eco-friendly manufacturing practices to appeal to eco-conscious consumers.
Kellogg’s
Kellogg's integrates its extensive snack expertise into its vegetable chip range, prioritizing product innovation, scalable production capacity, and strategic marketing campaigns to expand its footprint in the natural snack segment.
Earth’s Best
Earth’s Best focuses on organic and allergen-free vegetable chips, leveraging sustainable sourcing and processing technologies to meet rising demand among parents and health-focused consumers in Latin America.
Health Warrior
Health Warrior emphasizes functional ingredients in its vegetable chips, such as added vitamins and probiotics, supported by advanced manufacturing that ensures product integrity and aligns with health-focused brand positioning.
Terra Chips
Terra Chips offers gourmet vegetable chips with unique root vegetable blends, utilizing distinctive dehydration and flavoring techniques, emphasizing premium quality, artisanal appeal, and innovative taste profiles.
Snack Alliance
Snack Alliance, a major regional player, invests heavily in capacity expansion and product diversification, aiming to lead the market with a mix of organic, non-GMO, and gluten-free vegetable chips tailored to local tastes.
Nature’s Path
Nature’s Path specializes in organic, sustainable vegetable chips, utilizing eco-friendly farms and processing methods, with a strategic focus on enhancing product flavor varieties and expanding distribution channels across Latin America.
Strategic Business Developments
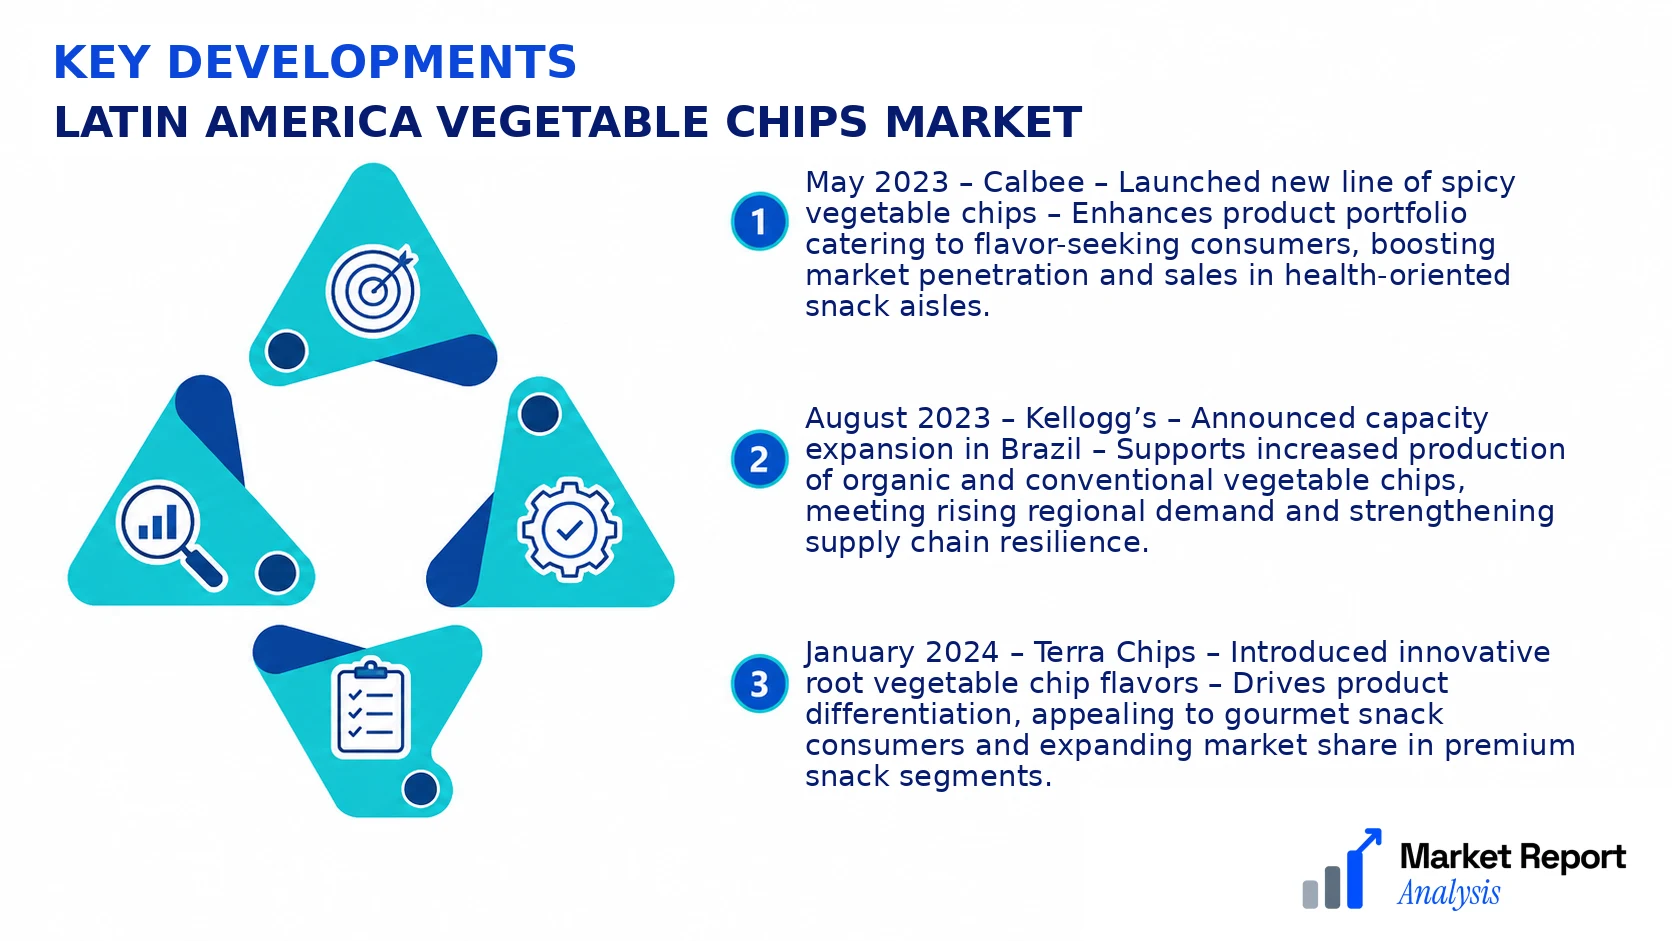
- May 2023 – Calbee – Launched new line of spicy vegetable chips – Enhances product portfolio catering to flavor-seeking consumers, boosting market penetration and sales in health-oriented snack aisles.
- August 2023 – Kellogg’s – Announced capacity expansion in Brazil – Supports increased production of organic and conventional vegetable chips, meeting rising regional demand and strengthening supply chain resilience.
- January 2024 – Terra Chips – Introduced innovative root vegetable chip flavors – Drives product differentiation, appealing to gourmet snack consumers and expanding market share in premium snack segments.
- April 2023 – Green Giant – Invested in sustainable packaging technologies – Reinforces commitment to eco-friendly practices, appealing to eco-conscious consumers and aligning with regional sustainability initiatives.
- July 2023 – Earth’s Best – Established joint venture with local organic farms – Ensures consistent supply of high-quality vegetables, enhances sustainability, and bolsters regional market position in organic snacks.
Frequently Asked Questions
What is the Latin America Vegetable Chips Market?
The Latin America Vegetable Chips Market encompasses the production, distribution, and sale of vegetable-based snack chips across Latin American countries, driven by consumer preferences for healthier snack options and increasing urbanization, which influences dietary habits.
What is the current market size of Latin America Vegetable Chips Market?
As of 2026, the Latin America Vegetable Chips Market is valued at approximately USD 2.3 Billion, reflecting increasing demand for plant-based snacks amidst rising health consciousness and expanding retail channels across the region.
What factors are driving the Latin America Vegetable Chips Market?
Key drivers include the growing consumer shift toward health-conscious eating, the rising popularity of vegetarian and vegan diets, product innovation in flavor and packaging, and increased retail penetration, especially in urban centers, fostering market growth.
Which region dominates the Latin America Vegetable Chips Market?
Brazil holds the dominant position in the Latin America Vegetable Chips Market due to its large population, growing middle class, and strong retail infrastructure, which collectively boost demand and regional market share.
Which segment is expected to grow the fastest?
The organic segment is projected to demonstrate the fastest growth rate, driven by consumers’ preference for natural, chemical-free products and the increasing availability of organic vegetable chips in supermarkets and health stores.
Who are the leading companies operating in the Latin America Vegetable Chips Market?
Leading companies include local and international brands such as Grupo Bimbo, La Costeña, and KKR & Co., which focus on innovation, quality, and expanding their product portfolios to capture rising demand across Latin America.
Analyst Perspective
The Latin America Vegetable Chips Market is approaching a mature stage, characterized by steady demand growth driven by health-conscious consumers and increasing snack diversification. Long-term prospects remain favorable, especially with innovations in flavor profiles, organic ingredients, and sustainability practices enhancing product appeal. The evolving technology landscape, including improved manufacturing processes and supply chain transparency, will enable companies to optimize costs and improve product quality, fostering competitive differentiation. Investment priorities are shifting towards building local supply chains, adopting eco-friendly packaging, and expanding regional distribution networks to capitalize on untapped markets within LATAM's diverse economies. Competitive intensity is intensifying as key players expand their portfolios and leverage strategic partnerships, while new entrants focus on niche segments such as organic and gluten-free options. Regional growth potential remains robust across Latin America's emerging markets, where rising disposable incomes and urbanization support increased snack consumption. Overall, strategic agility and innovation will be critical for sustainment and growth in this evolving landscape.
