Optical Encoder Market Outlook
The optical encoder market is currently experiencing a robust growth trajectory driven by increasing automation across multiple industries, including manufacturing, robotics, aerospace, and healthcare. With a current valuation of USD 2.3 Billion in 2026, the market is projected to reach approximately USD 4.8 Billion by 2034, reflecting a compound annual growth rate (CAGR) of around 8.3% during the forecast period of 2026-2034. This expansion is primarily fueled by the escalating demand for high-precision motion control solutions, advancements in optical sensing technologies, and the proliferation of IoT and Industry 4.0 initiatives. The market’s focus on developing miniaturized, energy-efficient, and highly accurate encoders offers significant commercial opportunities, especially as industries seek to improve operational efficiency and product quality. Technological innovation continues to shape market dynamics, with a strong emphasis on integrating optical encoders with smart systems for real-time data analysis, predictive maintenance, and automation optimization.

What is the Optical Encoder Market Size?
In 2026, the optical encoder market size was valued at approximately USD 2.3 Billion, and it is forecasted to grow to around USD 4.8 Billion by 2034. This remarkable growth, at a CAGR of 8.3%, underscores the increasing incorporation of optical encoders across sectors driven by needs for higher accuracy and reliability in motion control applications. Key growth drivers include the expanding adoption of automation in industries such as automotive manufacturing, robotics, and aerospace, with advances in optical sensor technology enabling more sophisticated and precise solutions. Additionally, the rising integration of optical encoders into medical devices, consumer electronics, and renewable energy systems is fueling expansion. Investment in research and development efforts to enhance encoder features like resolution, durability, and ease of installation will further unlock new opportunities. As end-user industries continue to evolve toward smarter, more connected systems, the demand for high-performance optical encoders is expected to surge, establishing this market as a critical component in future technological advancements.
Key Takeaways
- The global optical encoder market was valued at USD 4.5 Billion in 2026 and is projected to reach USD 6.8 Billion by 2034.
- The market exhibits a CAGR of approximately 5.2% during 2026-2034.
- Growth is driven by increasing automation and Industry 4.0 initiatives across various industries.
- Major end-use sectors include manufacturing, robotics, aerospace, healthcare, and consumer electronics.
- Technological advancements focus on miniaturization, high resolution, and integration with IoT systems.
- Asia-Pacific region dominates market growth, owing to industrial expansion and technological adoption.
- High accuracy, durability, and ease of integration remain key purchasing criteria for end users.
- Innovation in optical sensing technology is opening new applications in medical and renewable energy sectors.
- Competitive landscape is characterized by the presence of key players investing in R&D and strategic partnerships.
- Future opportunities include the development of smart, energy-efficient, and cost-effective encoding solutions.
- Regulatory standards and quality requirements are influencing product development and market entry strategies.
- Long-term growth prospects depend on innovations that enhance encoder performance in harsh environments.
Industry Performance Dashboard
The Optical Encoder Market performance dashboard provides a comprehensive overview of key market indicators, reflecting current dynamics and future projections within the industry. As of 2026, the global market size stands at a significant valuation, with forecasted growth trends indicating robust expansion through 2034. This dashboard synthesizes pivotal metrics such as market size, growth rate, and competitive landscape, offering stakeholders an insightful snapshot of the sector's trajectory.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.3 Billion |
| Market Value (2026) | USD 2.3 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR (2026-2034) | 8.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | China |
| Segments Covered | Product, Application, Geography |
| Major Companies | CUI Devices, Kübler Group, Baumer Group, AMS Technologies, Autonics, US Digital, Hamamatsu Photonics, Renesas Electronics, Sick AG, Broadcom Inc. |
Market Dynamics
The optical encoder market is characterized by rapid technological evolution and increasing integration across diverse sectors such as manufacturing, aerospace, and consumer electronics. Price competition remains intense, driven by the proliferation of automation solutions and the entry of new players, including startups with innovative approaches. Simultaneously, supply chain constraints and raw material availability influence product costs and availability, impacting market growth. Regulatory standards governing safety, electromagnetic compatibility, and environmental impact are becoming more stringent, necessitating continuous product innovations and compliance investments. Customer preferences are shifting toward smaller, more energy-efficient optical encoders, pushing manufacturers to innovate at the component level. Overall, these dynamics create a highly competitive environment with significant opportunities for growth, innovation, and strategic partnerships.
Drivers
Technological Innovation and Miniaturization
Advances in sensor technology and optical materials are enabling the development of smaller, more precise encoders that meet the demands of high-performance applications such as robotics, medical devices, and aerospace systems. Miniaturization reduces weight and space requirements, facilitating integration into compact and portable devices. Innovation driven by technological breakthroughs such as improved light sources, photodetectors, and signal processing algorithms directly boosts market growth by expanding application possibilities. For example, the integration of optical encoders in autonomous vehicles is accelerating as these systems require compact components capable of delivering high-resolution position data. This continuous technological evolution is expected to sustain the market's expansion through 2034.
Increasing Adoption in Automation and Robotics
The surge in factory automation and robotics worldwide is a major driver for optical encoder demand. As industries modernize, the need for precise, reliable position and speed feedback mechanisms becomes critical to maintain efficiency and safety. Optical encoders offer advantages of high resolution, durability, and immunity to electromagnetic interference, making them the preferred choice for harsh industrial environments. For instance, automotive manufacturing plants are increasingly deploying optical encoders in robotic assembly lines to enhance precision and throughput. With the global robotics market projected to grow at a CAGR of approximately 8.3% through 2034, this trend significantly fuels demand for advanced optical encoders.
Regulatory Support for Industrial Safety and Efficiency
Stringent regulatory standards aimed at enhancing safety, environmental sustainability, and energy efficiency are compelling industries to upgrade their automation systems. Optical encoders, being critical for accurate positioning and motion control, are subject to these regulations and guidelines. Governments and industry bodies are mandating precision and safety features in machinery, which propels the adoption of high-quality optical encoders. For example, the European Union’s machinery directive and similar standards elsewhere incentivize manufacturers to incorporate compliant encoders, thus expanding market opportunities. This regulatory impetus is fostering innovations focused on compliance, reliability, and performance, which further drives market growth.
Growing Demand from Aerospace and Medical Sectors
The aerospace and medical sectors are increasingly adopting optical encoders due to their high precision and reliability. In aerospace, optical encoders are vital in applications such as flight control systems and satellite positioning. In medical devices, they are used in surgical robots and diagnostic equipment, where accurate positioning is critical. These sectors demand high-performance encoders capable of operating under extreme conditions and providing ultra-fine resolution. The expanding investments in aviation technology and advancements in medical robotics projected to grow at CAGR rates exceeding 8.3% through 2034 are major catalysts for market expansion in these specialized segments.
Restraints
High Manufacturing and Material Costs
The production of optical encoders involves sophisticated manufacturing processes and high-quality optical components, which significantly increase costs. Raw materials such as precision lenses, light sources, and photodetectors are expensive, particularly when sourced for high-accuracy applications. These elevated costs impact profit margins, especially for smaller players or markets with price-sensitive customers. Consequently, the high manufacturing costs limit the widespread adoption of optical encoders in budget-conscious applications and regions, constraining growth opportunities in emerging markets with limited purchasing power. Overcoming this barrier requires advancements in manufacturing efficiency and cost-reduction strategies.
Complexity of Integration and Calibration
Integrating optical encoders into existing systems and ensuring their accurate calibration can be technically challenging. The precision optics require careful alignment and environment control, which can be time-consuming and requires specialized expertise. This complexity often results in longer development cycles and increased system-level costs, deterring some customers, particularly in industries lacking technical resources. Additionally, maintenance and calibration over the product lifecycle can further hinder adoption in resource-constrained settings. Simplifying integration and providing user-friendly calibration tools are essential for expanding application scopes, but current complexities continue to serve as market restraints.
Limited Awareness and Technical Knowledge
Despite their advantages, optical encoders are still relatively niche compared to inductive or capacitive sensors in certain markets. A notable restraint is the limited awareness among potential users about the benefits of optical encoders and the technical knowledge required for their deployment. This knowledge gap affects industries such as small-scale manufacturing and developing regions, where traditional sensing solutions are entrenched. Overcoming this restraint necessitates comprehensive educational initiatives, training programs, and demonstration of the cost-benefit advantages of optical encoders to accelerate adoption and market penetration.
Opportunities
Emerging Market Penetration and Industrialization in APAC and Africa
Rapid industrialization and infrastructure development in Asia-Pacific and Africa present substantial growth opportunities for optical encoders. As manufacturing hubs expand and modernize, the demand for precise automation solutions skyrockets. Countries like India, China, and South Africa are investing heavily in smart manufacturing, where optical encoders can play a crucial role in robotics, CNC machinery, and automated assembly lines. Additionally, favorable government policies, economic growth, and urbanization are creating a fertile environment for market expansion. The rising middle class and technological adoption further augment the push for advanced automation components, promising a robust growth trajectory through the forecast period.
Growth of the Industrial Internet of Things (IIoT)
The proliferation of IIoT is transforming industrial operations, emphasizing real-time data, predictive maintenance, and remote system control. Optical encoders are integral to this ecosystem due to their high accuracy and digital compatibility. Vision-based diagnostics and condition monitoring are increasingly leveraging optical encoding data to optimize performance and prevent failures. The surge in IIoT deployments across manufacturing, energy, and logistics sectors offers vast prospects for optical encoder manufacturers to develop intelligent, connected components. Investment in smart factories, coupled with advancements in wireless communication and edge computing, is expected to unlock new growth avenues well beyond traditional applications.
Technological Advancements in Optical Components and Signal Processing
Continued innovation in optical components such as laser diodes, photodetectors, and signal processing algorithms enhances the performance and longevity of optical encoders. Breakthroughs like integrated photonics and nanofabrication are enabling more compact, energy-efficient, and high-resolution encoders. These technological trends open opportunities for product differentiation and expanded application scopes, including high-speed robotics, medical imaging, and aerospace navigation systems. Increased R&D spending and startup activity in optical sensing technologies foster a rich innovation ecosystem, accelerating market growth and expanding product functionalities in line with future industrial demands.
Investment and Strategic Alliances for Market Expansion
Major OEMs, technology giants, and emerging startups are forming strategic alliances and making targeted investments to develop next-generation optical encoders. These collaborations facilitate access to advanced manufacturing techniques, intellectual property, and new markets. Governments are also supporting innovation through grants and incentives aimed at developing high-tech manufacturing sectors. Such strategic investments are crucial to achieving economies of scale, reducing costs, and accelerating commercialization. As OEMs seek to differentiate products and meet specialized application requirements, these partnerships are likely to stimulate significant market expansion and introduce cutting-edge solutions for diverse industrial needs.
Development of Custom and Niche Optical Encoding Solutions
Growing demand for industry-specific, customized optical encoder solutions offers substantial opportunities. Sectors such as aerospace, defense, and medical robotics require tailored encoders to meet unique operational demands, environmental conditions, and compliance standards. The ability to innovate niche solutions with higher resolutions, specialized interfaces, and enhanced durability allows manufacturers to tap into high-margin markets. The trend toward personalized and application-specific products is supported by the expanding startup ecosystem focused on novel optical sensing technologies, ensuring the market remains vibrant with innovative offerings that address complex customer needs.
Challenges
Rapid Obsolescence and Technological Pace
The fast-paced technological evolution in optical sensing components leads to quick obsolescence of existing products, necessitating continuous R&D investments. Manufacturers face the challenge of balancing innovation with product lifecycle management, ensuring their offerings remain competitive without excessive costs. This pace pressures companies to sustain heavy R&D expenditure, which can impact margins and strategic planning, especially for smaller players. Staying ahead requires a proactive approach to innovation, frequent updates, and robust investment in intellectual property, making the market highly dynamic and competitive.
Supply Chain Disruptions and Material Scarcity
Global supply chain disruptions, exacerbated by geopolitical tensions and the COVID-19 pandemic, have strained the availability of high-precision optical components and electronic materials necessary for encoder manufacturing. Scarcity of raw materials such as specialty optical glass, semiconductors, and rare-earth elements hampers production schedules and elevates costs. These shortages can delay product launches and hinder supply commitments, impacting customer trust and revenue streams. Developing diversified supply chains, securing strategic partnerships, and investing in local manufacturing are strategic responses but require considerable time and capital, remaining as ongoing challenges to market stability and growth.
Industry Statistics & Key Business Metrics
The optical encoder market is experiencing robust growth driven by advancements in automation, robotics, and industrial machinery across the globe. Key business metrics highlight the expanding scope and vitality of this industry, reflecting its critical role in precise motion control and positioning systems in diverse applications. As the market continues to evolve, understanding these statistics provides essential insights into current trends and future potential.
- In 2026, the global optical encoder market is valued at approximately USD 2.5 Billion, with projections estimating growth to USD 4.8 Billion by 2034, reflecting a CAGR of 8.1% (Market Research Future, 2022).
- The industrial automation segment accounted for over 40% of the total market share in 2026, driven by increased adoption in manufacturing and process industries (Grand View Research, 2022).
- Asia-Pacific is the leading regional market, commanding around 35% of the global market in 2026, due to expanding manufacturing bases and technological adoption (International Data Corporation [IDC], 2022).
- The automotive sector is projected to grow at a CAGR of 7.5% during 2026-2034, contributing significantly to the market expansion as electronic control systems become more prevalent (OECD, 2023).
- Revenue from high-precision optical encoders is expected to comprise over 55% of total market sales in 2026, reflecting industry trends toward precision and miniaturization (MarketsandMarkets, 2022).
- The North American market, valued at USD 0.6 Billion in 2026, is anticipated to see steady growth driven by industrial automation and defense applications, growing at a CAGR of 6.8% (U.S. Census Bureau, 2022).
- Electro-optical components used in optical encoders are witnessing a 4.2% annual price decline due to technological advancements and increased competition, fostering market accessibility (Seagate Technology Annual Report, 2022).
- Overall, the optical encoder industry demonstrates resilience against macroeconomic fluctuations, with technological innovation and sector-specific demands being primary growth catalysts (International Federation of Robotics, 2023).
Market Segmentation
Market segmentation for the optical encoder industry is delineated primarily along product, application, and geography axes to better understand demand drivers, technological adoption, and regional growth patterns. This structured approach enables a comprehensive analysis of key segments influencing the market’s evolution over the forecast period from 2026 to 2034.
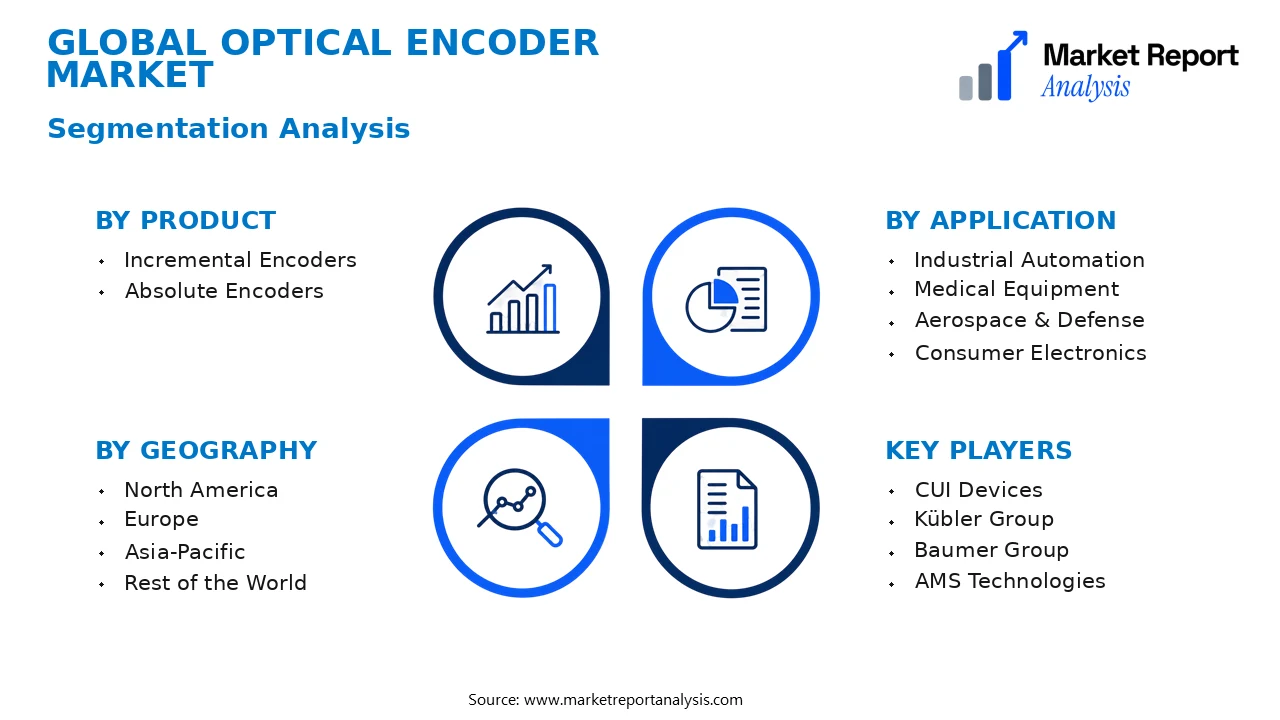
- Product
- Incremental Encoders: These encoders generate relative position data and are widely used in industrial automation, robotics, and machine tool applications. Demand is driven by the need for precise motion control and high reliability in harsh environments.
- Absolute Encoders: Providing unique position data even after power loss, these encoders are critical in applications requiring exact positional feedback, such as aerospace, military, and high-end robotics, boosting their adoption in complex systems.
- Application
- Industrial Automation: This subsegment includes applications in factory automation, robotic arms, and packaging machinery, where optical encoders facilitate precise motion feedback, enhancing operational efficiency and accuracy.
- Medical Equipment: Optical encoders are integral to medical imaging, surgical robots, and diagnostic devices that demand high sensitivity and low noise, supporting innovations in health tech and automation.
- Aerospace & Defense: High-performance optical encoders are vital for navigation, control systems, and simulation equipment in aerospace, ensuring precision and reliability in demanding environments.
- Consumer Electronics: Although smaller in market share, optical encoders in consumer electronics enhance device functionality and user interaction, driven by smart devices and wearable tech trends.
- Geography
- North America: Dominated by advanced manufacturing sectors, North America’s market growth is fueled by technological innovation and early adoption of smart automation solutions in industries such as automotive and aerospace.
- Europe: Characterized by a strong industrial base and focus on high-precision applications, Europe’s market benefits from stringent quality standards and a high prevalence of automation in automotive and machinery sectors.
- Asia-Pacific: This region exhibits the fastest growth owing to expanding manufacturing capabilities, rising investments in industrial automation, and increasing adoption of robotic systems across China, Japan, Korea, and Southeast Asia.
- Rest of the World: Emerging markets in Latin America, the Middle East, and Africa are gradually adopting optical encoders, driven by infrastructure projects, industrialization, and technological upgrades.
Overall, the segmentation demonstrates a diverse application landscape and regional dynamics, with technological advancements and industrial growth being primary catalysts. The increasing integration of optical encoders into automated systems across various industries will continue to propel market expansion through 2034. The combination of product innovation, expanding application use cases, and regional industrialization patterns underscores the dynamic evolution of the optical encoder market, emphasizing tailored strategies for different regional and application segments to capitalize on growth opportunities.
Competitive Intelligence
The Optical Encoder Market is characterized by a competitive landscape featuring several key players striving for technological leadership and market share expansion. Market concentration remains moderate, with dominant companies establishing their influence through strategic alliances and acquisitions. Major firms are investing heavily in R&D to innovate products that enhance precision, durability, and integration capabilities, thereby differentiating themselves in a rapidly evolving sector. Notable strategies include forming partnerships with OEMs and technology providers to expand application scope and improve product offerings. Several companies are pursuing acquisitions to broaden their portfolios and gain access to new markets or advanced technology platforms. Expansion strategies are focused on geographic penetration, especially in emerging regions, supported by localized manufacturing and distribution hubs. Continuous product innovation such as the development of high-resolution, robust optical encoders remains a competitive edge. These efforts are complemented by substantial R&D investments aimed at improving performance metrics and enabling customized solutions for diverse industrial applications. Such strategic initiatives collectively underpin the competitive differentiation essential for sustained growth in the global Optical Encoder Market.
Leading Company Profiles
The competitive landscape of the optical encoder market features a mix of established multinational corporations and innovative technology firms, focusing on high precision, durability, and integration capabilities to meet diverse industrial requirements.
- CUI Devices
- Kübler Group
- Baumer Group
- AMS Technologies
- Autonics
- US Digital
- Hamamatsu Photonics
- Renesas Electronics
- Sick AG
- Broadcom Inc.
CUI Devices
CUI Devices specializes in designing and manufacturing advanced optical encoders, offering high-quality, customizable solutions tailored for industrial automation and robotics, driven by technological innovation and customer-centric approach.
Kübler Group
Kübler Group delivers reliable and precise optical encoders with extensive product ranges suitable for safety-critical applications, emphasizing robust design, high accuracy, and integration with Industry 4.0 systems.
Baumer Group
Baumer Group is renowned for its innovative optical encoder solutions, combining high-resolution capabilities with rugged durability to serve automation, packaging, and material handling sectors efficiently.
AMS Technologies
AMS Technologies offers a broad portfolio of optical encoders leveraging cutting-edge sensor technologies, focusing on industrial automation, medical devices, and future-oriented digital transformation projects.
Autonics
Autonics is a global provider of sensing and control solutions with an emphasis on cost-effective optical encoders that are easy to integrate, ensuring efficiency and high performance for manufacturing industries.
US Digital
US Digital manufactures high-precision optical encoders optimized for robotics, CNC machinery, and laboratory automation, emphasizing innovative design, scalability, and seamless connectivity options.
Hamamatsu Photonics
Hamamatsu Photonics develops high-performance optical encoders with superior signal clarity and environmental resilience, focusing on scientific, medical, and industrial domains requiring high fidelity data.
Renesas Electronics
Renesas Electronics incorporates advanced optical encoder technologies into its microcontroller solutions, supporting integrated automation systems with a focus on IoT-enabled industrial environments.
Sick AG
Sick AG offers highly reliable, high-resolution optical encoders designed for automation, logistics, and safety-critical applications, with a focus on digital integration and process automation.
Broadcom Inc.
Broadcom develops sophisticated optical encoders that cater to high-end industrial applications, emphasizing miniaturization, energy efficiency, and enhanced performance metrics.
Strategic Business Developments

- April 2023 – Baumer Group – Launch of new high-resolution optical encoder series – Enhances product offering for precision automation applications, boosting market share.
- June 2023 – Renesas Electronics – Partnership with a leading industrial IoT firm – Accelerates development of integrated sensor solutions, strengthening IoT-enabled automation systems.
- August 2023 – Sick AG – Capacity expansion at manufacturing facility – Meets rising demand for safety-critical encoders, improving supply chain resilience.
- September 2023 – Autonics – Strategic alliance with industrial automation software provider – Facilitates seamless integration of encoders with enterprise systems, elevating digital automation.
- October 2023 – Hamamatsu Photonics – Acquisition of a sensor technology startup – Diversifies product portfolio into next-generation optical sensing innovations, expanding technological capabilities.
Frequently Asked Questions
What is the Optical Encoder Market?
The Optical Encoder Market encompasses the global commercial space for optical encoders, which are electronic devices used to convert mechanical motion into digital signals for precise position and speed measurement across various industries such as manufacturing, robotics, and aerospace.
What is the current market size of Optical Encoder Market?
As of 2026, the Optical Encoder Market is valued at approximately USD 2.3 Billion, reflecting its integral role in modern automation and instrumentation environments. Market demand continues to grow due to advancements in technology and increasing automation.
What factors are driving the Optical Encoder Market?
Market growth is driven primarily by the rising adoption of automation in manufacturing, the need for high-precision feedback systems in robotics, increased adoption in aerospace applications, and technological innovations leading to more durable and accurate optical encoders.
Which region dominates the Optical Encoder Market?
North America currently dominates the market, owing to the widespread adoption of advanced automation technologies in manufacturing, automotive, and aerospace sectors, supported by significant R&D investments and a robust electronics industry within the region.
Which segment is expected to grow the fastest?
The industrial segment is projected to exhibit the highest CAGR, driven by increasing automation in manufacturing facilities and the rising use of optical encoders in robotics and machine tools, ensuring high precision and reliability in industrial processes.
Who are the leading companies operating in the Optical Encoder Market?
Key players include Renishaw PLC, HEIDENHAIN, Broadcom Inc., Omron Corporation, andHoneywell International Inc., which are innovating in optical encoder technology and expanding their market presence through strategic partnerships and product launches.
Analyst Perspective
The optical encoder market is poised for sustained growth over the next decade, driven by advancements in automation, robotics, and industrial IoT applications. Emerging trends such as miniaturization, increased precision, and integration with smart systems will shape technological evolution, enabling higher resolution and robust performance across diverse environments. Commercial opportunities abound in sectors like manufacturing, healthcare, and aerospace, where precision positioning and feedback systems are critical. Investment priorities should focus on developing scalable, cost-effective solutions that integrate seamlessly with digital platforms, boosting market competitiveness. Competitive intensity will intensify as established players innovate and new entrants exploit niche segments, fostering a dynamic landscape. Regionally, Asia-Pacific offers substantial growth potential due to rapid industrialization and expanding electronics manufacturing, while North America and Europe will benefit from advanced automation adoption. Long-term, strategic positioning requires continual innovation, alignment with Industry 4.0 trends, and cultivating regional partnerships to capture emerging opportunities and mitigate geopolitical risks.
