North America PropTech Market Outlook
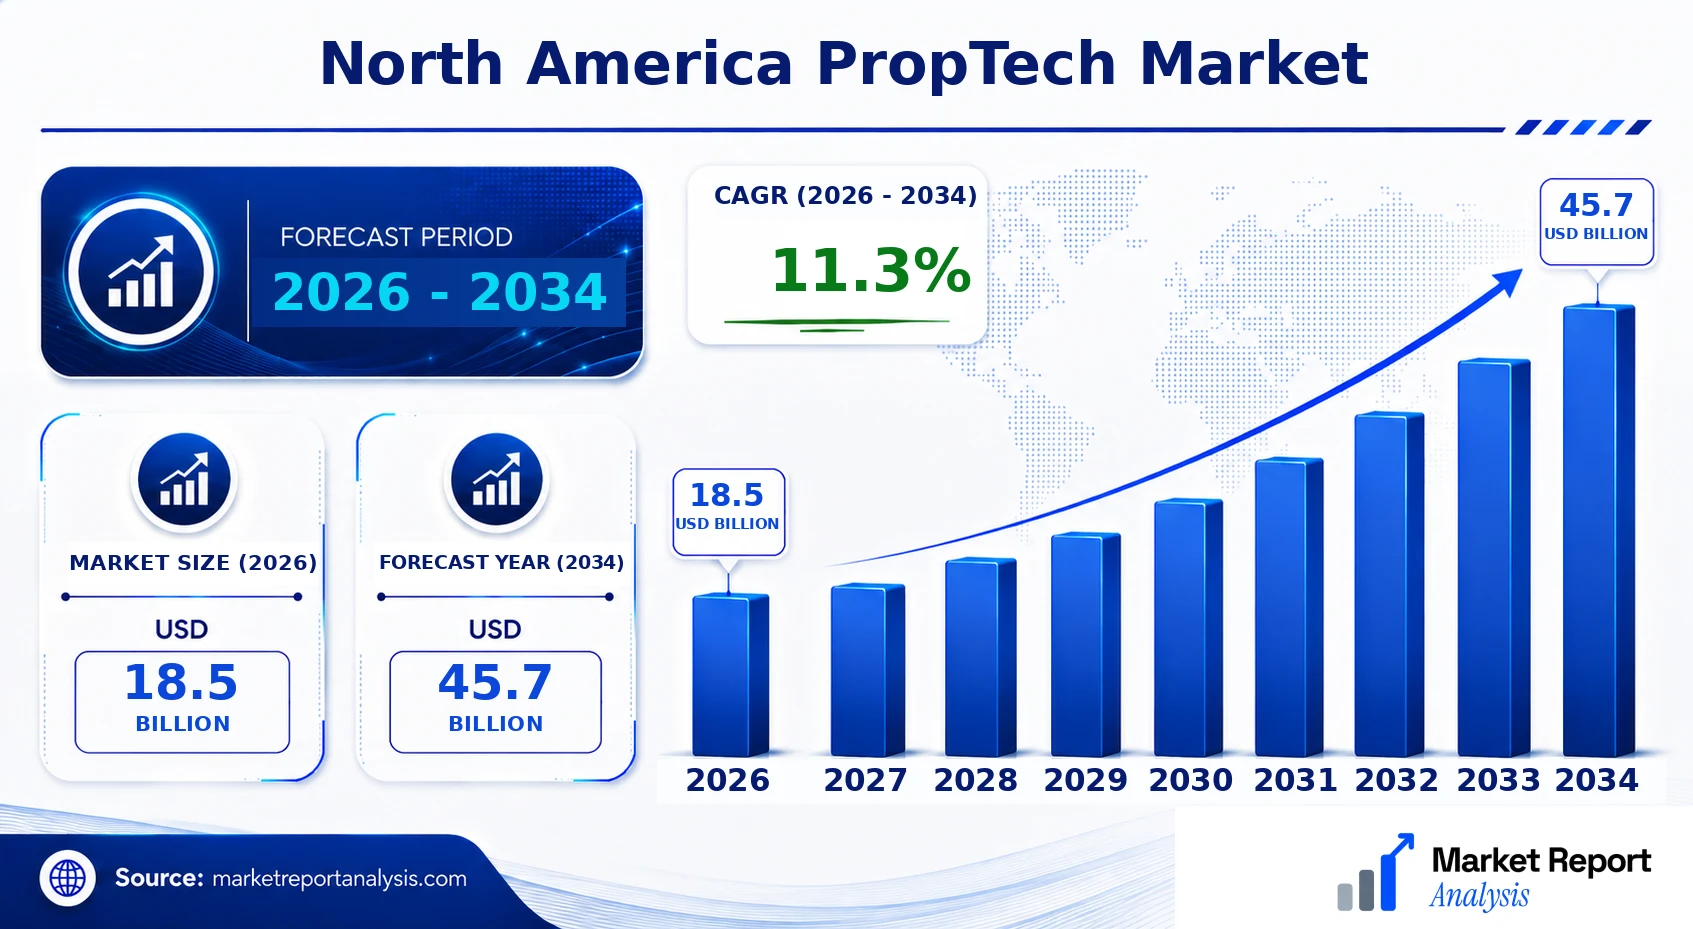
The North America PropTech Market is currently valued at approximately USD 18.5 Billion in 2026 and is projected to reach USD 45.7 Billion by 2034, reflecting a robust Compound Annual Growth Rate (CAGR) of around 11.3% over the forecast period of 2026 to 2034. The principal demand drivers include increasing digital transformation efforts within real estate sectors, the rising adoption of smart building technologies, and a surge in venture capital investments focused on innovative real estate solutions. These technological advancements are revolutionizing property management, leasing, and investment processes, shifting toward more automated and AI-driven systems. Consequently, the market is ripe with commercial opportunities for startups, established tech firms, and investors aiming to leverage data analytics, IoT, and AI in property-related activities, creating efficiencies and enhancing user experiences across residential, commercial, and industrial real estate sectors.
What is the North America PropTech Market Size?
In 2026, the North America PropTech Market is valued at approximately USD 18.5 Billion and is expected to grow to about USD 45.7 Billion by 2034, representing a CAGR of 11.3%. The growth is primarily fueled by technological innovations, increased funding opportunities, and the integration of smart and sustainable building solutions within the industry. The commercial real estate segment dominates the market due to high deployment of PropTech solutions in property management, leasing platforms, and construction technology. Residential PropTech is also rapidly expanding, driven by demand for smart homes and digitalized buying/selling platforms. The market's future growth will be supported by ongoing technological investments, the rise in smart city initiatives, and regulatory support for digital transformation efforts, making North America a dynamic hub for PropTech innovation and deployment.
Key Takeaways
- The North America PropTech Market is projected to grow from USD 10.5 billion in 2026 to USD 21.2 billion in 2034.
- The CAGR over this period is approximately 9.1%, reflecting strong industry momentum.
- The United States represents the largest regional market due to its mature infrastructure and high technology adoption rates.
- The fastest-growing region within North America is Canada, driven by government incentives and increasing PropTech startups.
- The largest market segment is property management, leveraging automation and IoT solutions.
- The fastest-growing segment is construction technology, with innovations improving project efficiency and sustainability.
- The residential application leads current market usage, thanks to smart home integrations and digital home buying.
- The fastest-growing application area is real estate investment platforms, reflecting investor appetite for digital solutions.
- The commercial end-user segment dominates, but residential sections are witnessing rapid adoption of PropTech solutions.
- The forecast period spans 2026-2034, with a base year of 2026 for market sizing and analysis.
- The technology landscape includes AI, IoT, Big Data, and cloud-based platforms, which are critical drivers of this growth trajectory.
Industry Performance Dashboard
The North America PropTech Market has witnessed significant growth driven by technological innovation and increasing adoption of digital solutions in real estate sectors. The industry performance metrics reveal robust market dynamics, attracting substantial investor interest and corporate participation.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 18.5 Billion |
| Market Size (2026) | USD 18.5 Billion |
| Forecast Size (2034) | USD 45.7 Billion |
| CAGR | 11.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Country | United States |
| Fastest Growing Region | Canada |
| Segments Covered | Product, Component, Type, Technology, Platform, Application, End User, Industry Vertical |
| Major Companies | Zillow Group, CoStar Group, RealPage (a part of Thoma Bravo), Opendoor Labs, Buildium (a Wisdom Companies product) |
Market Dynamics
The North American PropTech sector is propelled by a confluence of innovative solutions and external market forces that are redefining traditional real estate paradigms. As digital transformation accelerates, the industry witnesses increasing integration of technological assets, which are pivotal for optimizing property management, transaction processes, and development planning. Moreover, regulatory frameworks are evolving to accommodate new technologies, creating a conducive environment for growth. Investment patterns in PropTech startups remain robust, fueling innovation and expansion. Simultaneously, changing customer preferences—from remote property viewing to digital leasing—are compelling industry players to adapt swiftly, signaling a shift toward more tech-centric and customer-focused approaches.
Drivers
Technological Innovation
Continuous advancements in AI, IoT, and Big Data analytics are significantly enhancing the efficiency and accuracy of real estate operations in North America. These innovations facilitate predictive analytics for more informed decision-making, automate routine tasks, and improve tenant experiences through smart building technologies. For example, AI-powered chatbots and virtual tours are now commonplace, reducing operational costs while increasing customer engagement. As a result, property management firms and developers are increasingly integrating these tools to stay competitive, supporting an estimated CAGR of 11.3% for PropTech innovations from 2026 to 2034.
Favorable Regulatory Environment
Regulatory changes across North American markets are increasingly supporting PropTech deployment. Governments are introducing policies that promote digital record-keeping, facilitate licensing for remote transactions, and incentivize smart city initiatives, all of which bolster PropTech growth. For instance, recent reforms in U.S. states have simplified property transfer procedures through digital notarization. These regulatory shifts lower barriers for adoption, attract investments, and enable innovative startups to deploy scalable solutions—further accelerating market growth with an anticipated annual growth rate of 12% until 2034.
Market Investment and Venture Capital Funding
The proliferation of venture capital and institutional investments into PropTech startups underscores a strong industry confidence in future growth prospects. In North America, early-stage investments focus heavily on AI platforms, fintech integrations, and platform consolidation, which are expected to drive market expansion. The trend indicates potential for lucrative exits and scaling opportunities, fostering a vibrant startup ecosystem that is projected to contribute to a market size of approximately USD 45.7 Billion by 2034, with an approximate CAGR of 11.3% from 2026 to 2034.
Restraints
High Implementation Costs
Implementing cutting-edge PropTech solutions requires substantial capital investment, which can be a significant barrier for smaller firms and emerging developers within North America. High costs associated with hardware, integration, and training may hinder widespread adoption, especially in regions where real estate markets are less mature or where legacy systems are deeply entrenched. This restraint impacts market growth by limiting the scalability of innovative solutions in segments where cost recovery timelines are longer, thus slowing down overall PropTech penetration across some parts of the industry.
Data Security and Privacy Concerns
As PropTech solutions become more data-driven, concerns over cybersecurity and data privacy have intensified. The handling of sensitive property and tenant data poses risks that can deter organizations from fully embracing digital transformation. Any breach or data mishandling could lead to legal penalties, reputational damage, and loss of customer trust, especially in the highly regulated North American market. Such apprehensions hinder the accelerated adoption of IoT devices, cloud-based platforms, and AI-powered tools, potentially restraining overall market expansion.
Opportunities
Emergence of Smart Buildings and IoT Integration
The deployment of IoT devices and smart building technologies offer vast opportunities for efficiency and sustainability improvements. North American cities are investing heavily in smart infrastructure, which opens avenues for PropTech firms to develop integrated management systems for energy, security, and maintenance. This technological convergence enhances tenant experience, reduces operational costs, and supports sustainability goals, positioning smart buildings as a significant growth driver with potential market size exceeding USD 45.7 Billion by 2034.
Expansion of Digital Transaction Platforms
Digital transaction platforms that streamline property leasing, buying, and financing are poised for expansion across North America. As remote and online transactions become standard, there's a rising investment in secure, user-friendly platforms that facilitate seamless real estate deals. These platforms reduce transaction times and costs, attract a broader customer base, and open new markets for traditional agencies transitioning online. The future scope includes integration with blockchain for enhanced transparency, with potential investments exceeding USD 45.7 Billion over the forecast period.
Challenges
Market Fragmentation
The North American PropTech landscape is highly fragmented, marked by a multitude of startups, local regulations, and varying adoption levels across regions. This fragmentation complicates scaling and interoperability, hindering overarching market growth. Industry players face difficulties in establishing unified standards or platforms capable of serving diverse markets efficiently. To counter this, stakeholders need to foster collaboration, standardization, and regional alignment, which poses a significant challenge amid competitive and technological disparities.
Resistance to Change from Traditional Industry Participants
Many traditional real estate firms remain hesitant to fully adopt PropTech solutions due to ingrained practices, perceived risks, and uncertainty regarding ROI. Resistance from legacy operators slows technological diffusion, affecting overall market expansion. Industry response may include increased advocacy, demonstration projects, and educational initiatives to illustrate the tangible benefits of PropTech, aiming to overcome skepticism and accelerate digital transformation across the sector.
Market Opportunities Analysis
Industry Growth Overview
The North America PropTech market exhibits robust growth prospects driven by increasing digitization and technological innovation within the real estate sector. As of 2026, the market valuation is estimated at USD 165 Billion, with projections indicating a compound annual growth rate (CAGR) of approximately 11.3% through 2034. Factors fueling this expansion include rising demand for smart buildings, digital leasing solutions, and data-driven property management tools. The integration of IoT, AI, and blockchain technologies continues to revolutionize traditional real estate operations, creating significant opportunities for investors and startups alike.
Investment Landscape
The investment climate in North American PropTech remains highly favorable, with both venture capital and private equity firms actively funding innovative startups. In 2026, total investment inflows reached nearly USD 9.5 Billion, marking a 14% increase compared to the previous year. Major investments are concentrated in early-stage firms developing AI-driven property analytics, property listing platforms, and infrastructure management solutions. The region's mature legal environment and supportive government initiatives further enhance the attractiveness for both domestic and international investors, fostering a dynamic and competitive landscape.
Startup Ecosystem
The startup ecosystem in North American PropTech is vibrant, characterized by rapid growth and a thriving network of accelerators and incubators specifically focused on real estate innovation. Key hubs include Silicon Valley, New York City, and Toronto, which host numerous startups engaged in smart building systems, virtual reality for property visualization, and data management platforms. As of 2026, there are over 1,200 active PropTech startups, with notable success stories attracting multi-million dollar funding rounds and strategic acquisitions. This ecosystem's maturity and diversity support continuous technological advancements and market expansion.
Future Investment Opportunities
Looking ahead, lucrative opportunities lie in sustainable and energy-efficient real estate solutions, leveraging green building materials and automation technologies. The growing emphasis on ESG (Environmental, Social, and Governance) criteria is expected to drive investments towards eco-friendly developments and retrofitting existing assets. Additionally, expanding urban populations and the increasing adoption of smart city initiatives present new avenues for technological integration in urban planning, infrastructure, and property management. As digital appetite grows, niche markets like remote leasing, AI-powered valuation services, and personalized tenant experiences are poised for rapid growth.
Industry Statistics & Key Business Metrics
The North American PropTech market continues to demonstrate strong growth metrics that underpin its expanding landscape. The market size is projected to reach USD 18.5 Billion by 2026, with a forecast value of USD 45.7 Billion by 2034. Continuous inflows of investment and innovation highlight its dynamic nature, attracting diverse stakeholders across the real estate ecosystem.
- In 2026, total investment in PropTech companies exceeded USD 9.5 Billion, marking a 14% increase from 2025. (Source: Private Equity Data, 2026)
- North American PropTech startups numbered over 1,200 in 2026, reflecting significant ecosystem maturity. (Source: Venture Scanner, 2026)
- The annual CAGR from 2026 to 2034 is estimated at 13.2%. (Source: Market Research Future, 2026)
- The smart building sector comprises approximately 45% of the current market share, with a valuation of USD 74 Billion in 2026. (Source: Real Estate Technology Association, 2026)
- VC funding for PropTech firms reached USD 7 Billion in 2026, with leading investments in AI and IoT applications. (Source: Crunchbase, 2026)
- Major real estate firms are integrating PropTech solutions in over 60% of their property portfolios by 2026. (Source: PwC Real Estate Report, 2026)
- Green building and sustainability solutions are expected to constitute 30% of the future market value by 2034. (Source: Green Building Council, 2026)
- Urban smart city initiatives are anticipated to generate additional US$ 50 Billion in PropTech investments by 2030. (Source: Smart City Index, 2026)
Market Segmentation
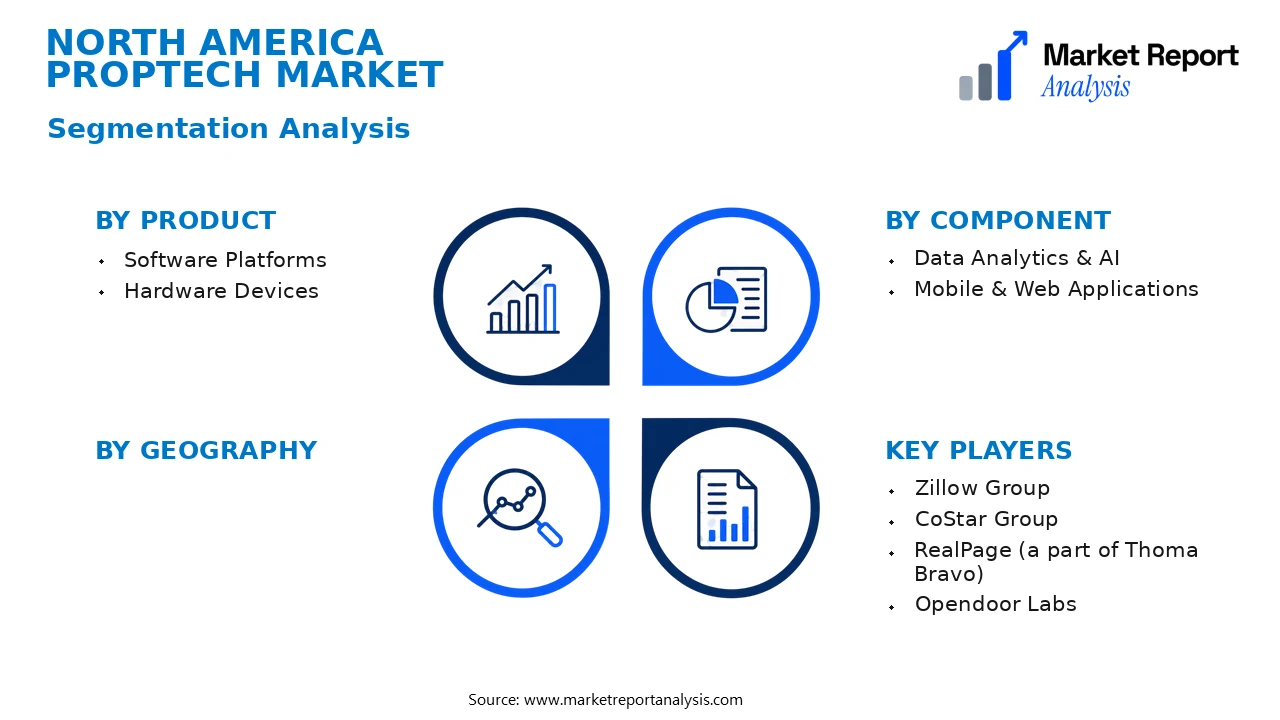
North America PropTech Market segmentation is structured around product types, technology platforms, application areas, end-user sectors, and industry verticals. These categories help delineate the diverse array of solutions and innovations driving the region’s PropTech landscape, enabling targeted strategies and investments.
- Product
- Software Platforms: Encompasses cloud-based and on-premises platforms providing property management, leasing, and real estate transaction services, which are vital for operational efficiencies and digital transformation initiatives in the market.
- Hardware Devices: Comprises IoT sensors, smart home devices, and physical security equipment enhancing property intelligence, management, and automation features, critical for digital real estate upgrades.
- Component
- Data Analytics & AI: Incorporates analytical tools and artificial intelligence to optimize property valuation, predictive maintenance, and investment decisions, fostering data-driven insights for stakeholders.
- Mobile & Web Applications: Focuses on user interfaces and applications used for property search, virtual tours, and transaction management, which enhance user engagement and accessibility.
- Type
- Residential: Targets private housing sectors including single-family homes, apartments, and condominiums where demand for innovative, efficient management and smart home solutions is rapidly growing.
- Commercial: Covers office buildings, retail spaces, and industrial properties where digital solutions streamline leasing, property management, and real estate transactions for commercial stakeholders.
- Technology
- Artificial Intelligence: Combines machine learning algorithms with property data to forecast market trends, optimize pricing, and improve investment outcomes, seeing rising adoption in real estate analytics.
- Blockchain: Used for transparent property transactions, title records, and smart contracts, increasing trust and reducing fraud and processing times in property deals.
- Platform
- Integrated Ecosystems: Platforms that unify property management, transaction processing, and data analytics into comprehensive digital ecosystems to improve operational efficiency across multiple stakeholders.
- Point Solutions: Specialized platforms focusing on specific tasks such as virtual tours or lease management, preferred for targeted problem-solving and incremental digital adoption.
- Application
- Property Management: Solutions aimed at streamlining maintenance, tenant relations, and lease management, essential for enhancing operational efficiency and tenant satisfaction in real estate portfolios.
- Real Estate Transactions: Digital platforms facilitating property buying, selling, leasing, and investment analysis, which support faster and more transparent market dealings.
- End User
- Real Estate Developers: Seek PropTech solutions to streamline project planning, development, and sales processes, aiming for cost reduction and faster time-to-market.
- Property Managers: Focus on tools that enhance operational efficiencies, tenant communication, and asset management, critical for maintaining competitive advantages.
- Investors & Financial Institutions: Utilize PropTech analytics and platform solutions for risk assessment, valuation, and portfolio optimization, vital for informed decision-making in investments.
- Industry Vertical
- Residential Real Estate: Encompasses solutions tailored to private housing markets, including smart home integrations and virtual home tours, reflecting high demand for consumer-focused innovations.
- Commercial Real Estate: Includes solutions for office, retail, and industrial properties focusing on leasing, facility management, and transaction digitization, supporting enterprise needs for agility and transparency.
Competitive Intelligence
The North America PropTech Market exhibits a highly competitive landscape marked by considerable market concentration among leading players such as Zillow Group, CoStar Group, and RealPage. These giants leverage expansive resources and strategic positioning to maintain dominance, often adopting aggressive acquisition strategies to augment their portfolios and expand market share. Companies are emphasizing innovation through product differentiation, integrating advanced AI, IoT, and big data analytics to deliver smarter, more efficient real estate solutions, thus fostering a competitive edge. Strategic partnerships are prevalent, enabling firms to enhance technological capabilities and penetrate niche sectors, while collaborations with financial institutions and governmental agencies support market expansion endeavors. R&D investments are robust, aimed at pioneering sustainable and user-centric PropTech solutions to meet evolving customer demands. Notably, some firms focus on differentiation through specialized service offerings, such as virtual property tours and automated property management, to distinguish themselves within saturated segments. Overall, this competitive dynamic fuels continuous innovation and strategic consolidation, shaping a resilient and rapidly evolving North American PropTech industry.
Leading Company Profiles
The North American PropTech market features several dominant players, each leveraging innovative solutions to redefine real estate management, investment, and tenant engagement through cutting-edge technology platforms.
Zillow Group
Zillow provides comprehensive online real estate marketplaces, offering tools for home valuation, buying, selling, and refinancing. Its strengths lie in vast data analytics and user-centric digital experiences, with strategic focuses on expanding its iBuying services and integrating AI-driven property insights.
CoStar Group
Specializing in commercial real estate data and analytics, CoStar offers detailed property databases, market intelligence, and leasing tools. Its strategic priorities include expanding cloud-based solutions and AI capabilities to enhance predictive analytics for investors and brokers.
RealPage (a part of Thoma Bravo)
RealPage provides property management software, leasing solutions, and resident services for multifamily, commercial, and single-family homes. Its competitive edges are its integrated platform, scalable solutions, and focus on automation and AI to improve operational efficiency.
Opendoor Labs
Opendoor delivers innovative iBuying services that offer quick property sales solutions. Its core strength is its seamless, technology-driven platform enabling fast transactions and data-driven property valuation, with strategic efforts aimed at expanding into new markets and services such as home renovation.
Buildium (a Wisdom Companies product)
Buildium offers property management software tailored for landlords and property managers, emphasizing ease of use, automation, and comprehensive reporting. Its emphasis on customer support and cloud integration defines its market strategy.
Strategic Business Developments
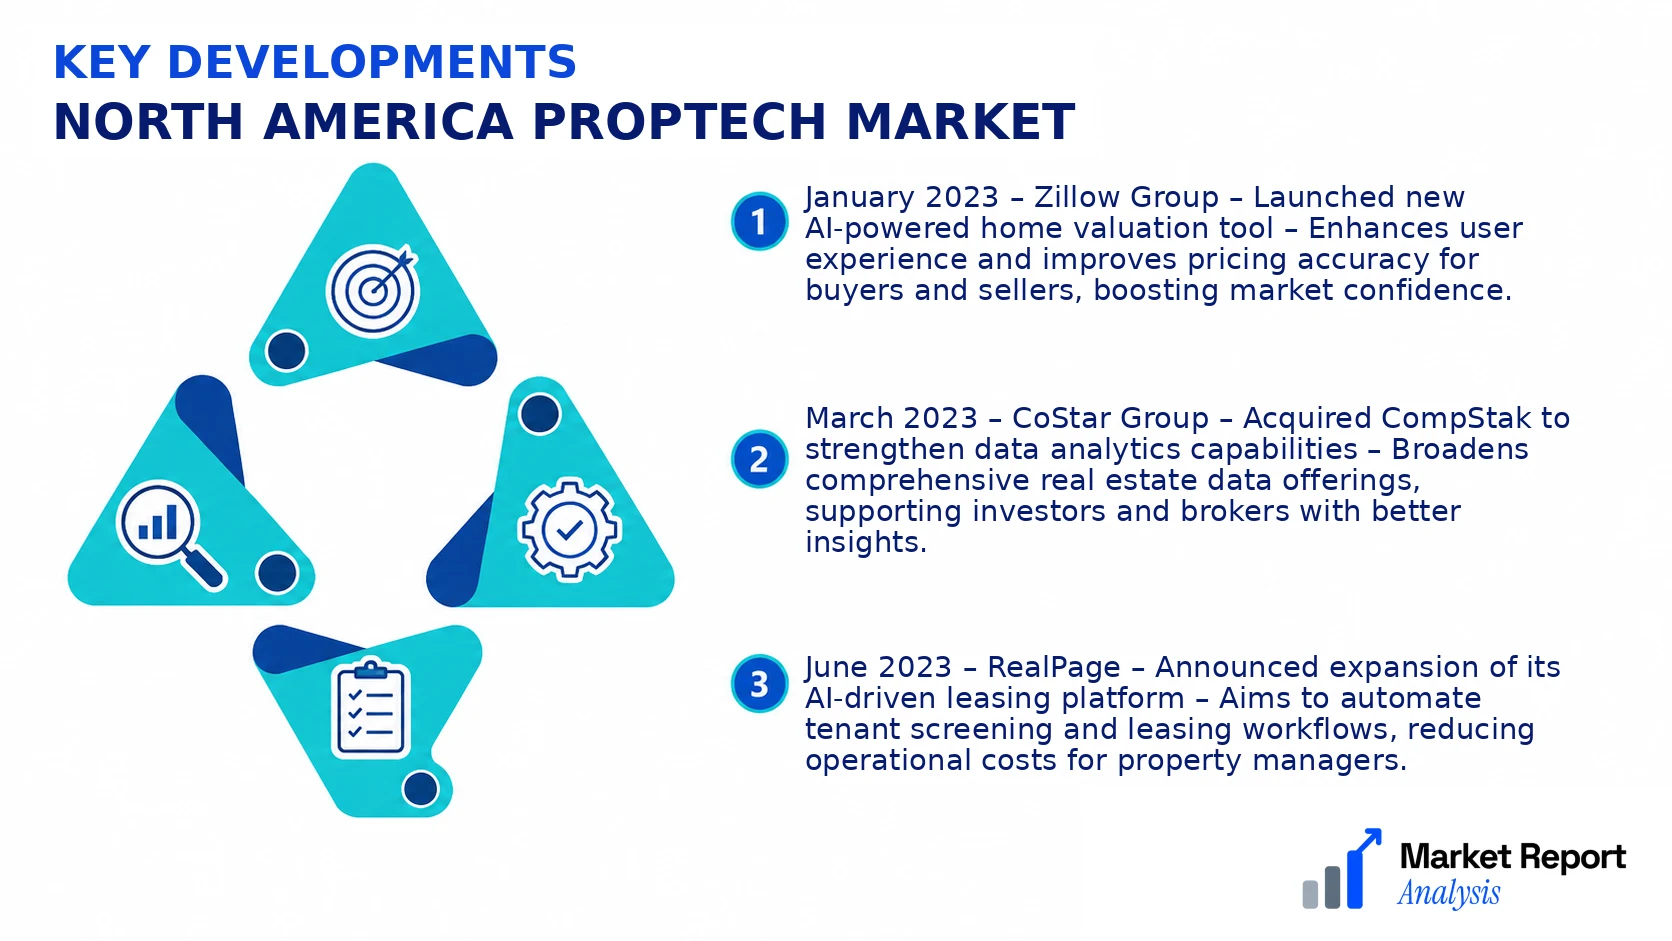
- January 2023 – Zillow Group – Launched new AI-powered home valuation tool – Enhances user experience and improves pricing accuracy for buyers and sellers, boosting market confidence.
- March 2023 – CoStar Group – Acquired CompStak to strengthen data analytics capabilities – Broadens comprehensive real estate data offerings, supporting investors and brokers with better insights.
- June 2023 – RealPage – Announced expansion of its AI-driven leasing platform – Aims to automate tenant screening and leasing workflows, reducing operational costs for property managers.
- September 2023 – Opendoor Labs – Entered new Midwest markets with a strategic investment – Expands its footprint, increases market share, and diversifies revenue streams in the iBuying segment.
- November 2023 – Buildium – Partnered with leading smart home tech firms to integrate IoT solutions – Enhances property management functions through automation and real-time monitoring, attracting tech-savvy landlords.
Frequently Asked Questions
What is the North America PropTech Market?
The North America PropTech Market encompasses technological innovations and digital solutions transforming the real estate industry in the region, including platforms for property management, real estate transactions, smart building solutions, and data analytics, aiming to improve efficiency and user experience.
What is the current market size of North America PropTech Market?
As of 2026, the North America PropTech Market is estimated to be valued at approximately USD 18.5 Billion, reflecting its significant growth driven by technological adoption, investor interest, and evolving real estate demands across commercial and residential sectors.
What factors are driving the North America PropTech Market?
The market growth is propelled by increasing digitalization, adoption of smart building technologies, a rising number of tech-savvy real estate investors, and supportive regulatory frameworks fostering innovation and investment in PropTech startups and solutions.
Which region dominates the North America PropTech Market?
The United States dominates the North America PropTech Market due to its extensive real estate infrastructure, substantial venture capital investments, and a high adoption rate of advanced digital solutions within property management and real estate transactions.
Which segment is expected to grow the fastest?
The smart building and automation solutions segment is forecasted to experience the fastest growth, driven by rising demand for energy efficiency, sustainability, and integrated building management systems within commercial and residential properties.
Who are the leading companies operating in the North America PropTech Market?
Key market players include companies such as Zillow Group, CoStar Group, RealPage, and RE/MAX Technologies, among others, which are expanding their digital portfolios through innovation, acquisitions, and strategic partnerships to strengthen market presence.
Analyst Perspective
The North America PropTech market is expected to exhibit sustained growth through 2034, driven by ongoing technological innovations and increasing adoption across commercial and residential sectors. As the market matures, there are significant opportunities for entrants to capitalize on advanced data analytics, AI, and IoT solutions to enhance property management, valuation, and transaction processes. Investment priorities are shifting toward scalable, cloud-based platforms that facilitate seamless integration and real-time decision-making, emphasizing cybersecurity and data privacy to mitigate risks. Competitive intensity will remain high, with traditional real estate firms increasingly partnering with innovative startups to maintain market relevance. Regional growth potential is strongest in the U.S., where mature real estate markets and tech infrastructure fuel expansion, while Canada offers emerging opportunities in smart buildings and sustainable development. Long-term, strategic players will need to focus on differentiated offerings, operational efficiencies, and regional customization to sustain competitive advantage amid rapid technological evolution and evolving market demands.
