North America CMOS Sensor Market Outlook
The North America CMOS Sensor Market is currently valued at approximately USD 10.5 Billion in 2026 and is projected to reach about USD 25.4 Billion by 2034, growing at a robust CAGR of around 11.2% during the forecast period. The primary demand drivers include the rapid adoption of CMOS sensors in consumer electronics, automotive applications, and industrial automation. The ongoing technological evolution towards higher resolution, lower power consumption, and enhanced sensor integration is fueling innovation and market expansion. Furthermore, increasing investments in AI-powered imaging solutions and the proliferation of IoT devices with integrated sensor technology are creating lucrative commercial opportunities. The North American market is characterized by a high level of product innovation and a competitive landscape dominated by leading companies investing heavily in R&D to develop advanced sensor solutions, which ensures sustained growth in the coming years.
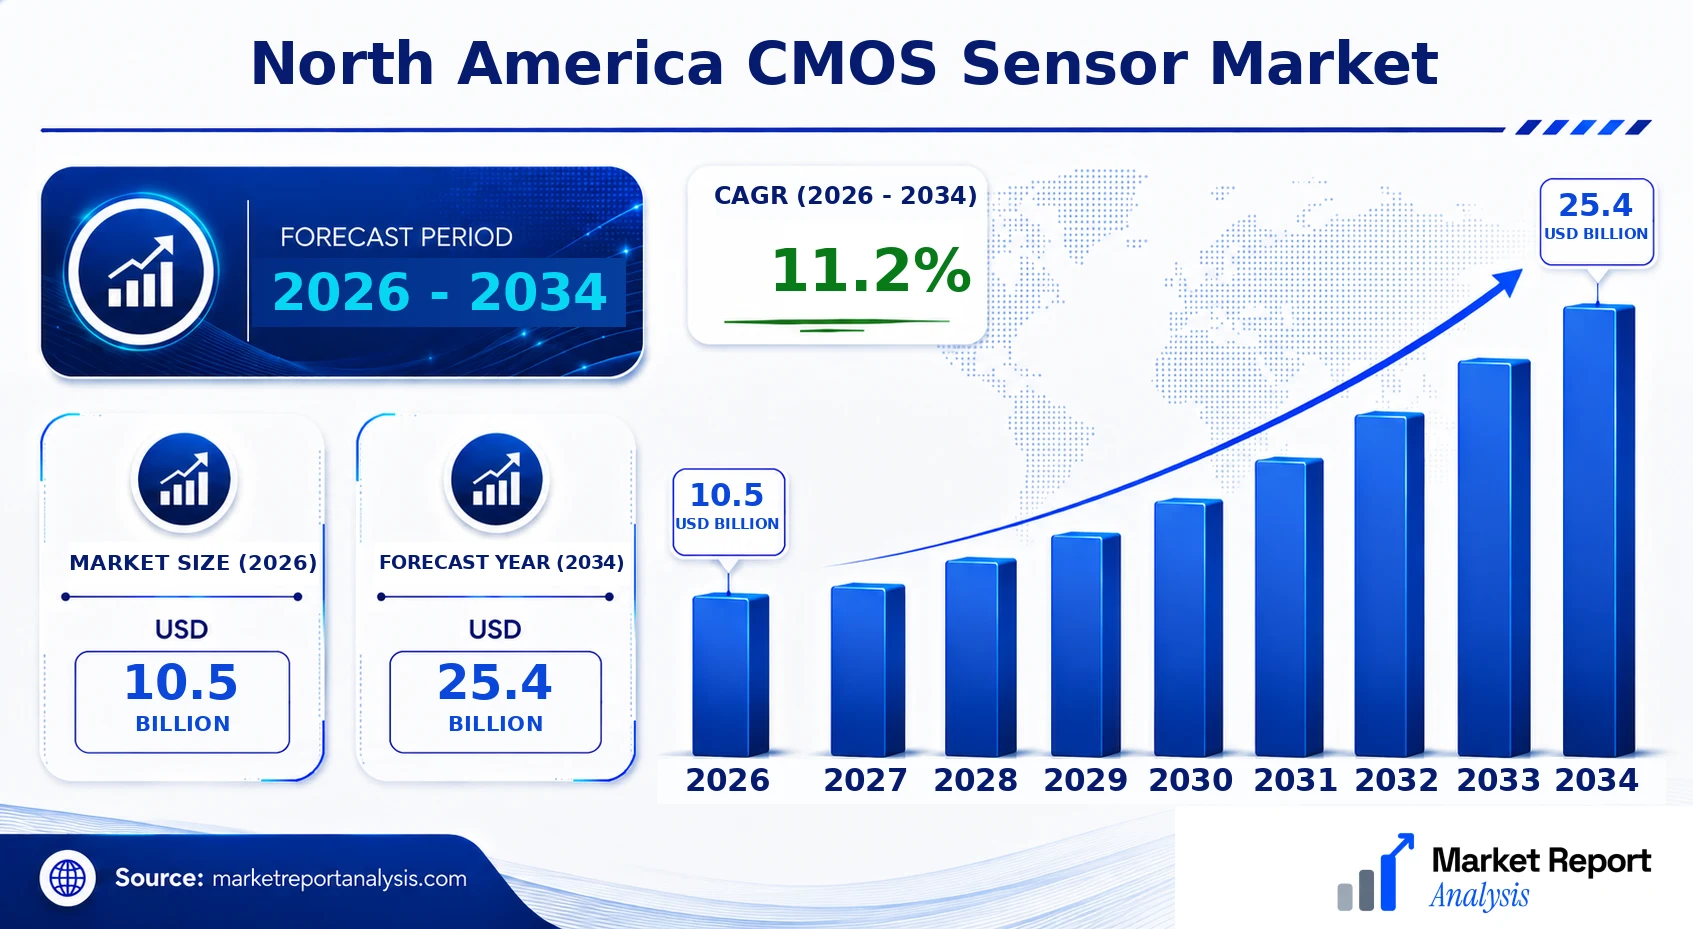
What is the North America CMOS Sensor Market Size?
The North America CMOS Sensor Market size is estimated at a current-market estimate of USD 10.5 Billion in 2026 and is expected to reach approximately USD 25.4 Billion by 2034, expanding at a CAGR of around 11.2% from 2026 to 2034. Growth is driven by the escalating demand for CMOS sensors across multiple end-use industries, significantly in consumer electronics, automotive, healthcare, and industrial sectors. The adoption of CMOS technology is favored over CCD sensors due to its lower power consumption, smaller size, and cost-effectiveness, thereby accelerating market growth. As the automotive industry shifts towards ADAS and autonomous vehicles, the requirement for high-quality imaging sensors is increasing rapidly. Consumer devices such as smartphones and tablets remain substantial end-user categories, fueling technological innovations and supply chain investments. The rapid technological advancements and expanding applications sector create vast future investment opportunities, including the development of 3D imaging, stacked sensors, and AI-enabled vision systems, which are poised to further propel the market's growth trajectory.
Key Takeaways
- The North America CMOS Sensor Market is projected to grow from USD 8.5 Billion in 2026 to USD 15.2 Billion by 2034.
- The market CAGR during 2026-2034 is approximately 7.4%.
- Consumer electronics constitute the largest application segment.
- The fastest-growing application segment is automotive imaging, driven by autonomous and ADAS technologies.
- Image sensors for automotive applications are the fastest-growing in the region.
- Smartphones and connected devices hold the largest end-user share.
- The industrial and healthcare sectors are gaining momentum as emerging end markets.
- High-resolution sensors, AI integration, and 3D imaging are key technological trends.
- Major industry players focusing on innovation and strategic investments to capture market opportunities.
- Increasing government regulations and standards are promoting higher-quality imaging solutions.
- Investment in R&D is critical for developing next-generation CMOS sensors with enhanced capabilities.
Industry Performance Dashboard
The North America CMOS Sensor market has demonstrated significant growth potential, driven by increasing adoption across various industries including consumer electronics, automotive, and industrial applications. This dashboard provides a comprehensive overview of key market indicators, offering insights into current performance and future prospects. The market's evolution is marked by advancements in sensor technology, miniaturization, and integration capabilities, further enhancing its applications and functionality.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 10.5 Billion |
| Market Value (2026) | USD 10.5 Billion |
| Forecast Size (2034) | USD 25.4 Billion |
| CAGR | 11.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, End User |
| Major Companies | Sony Corporation, Omnivision Technologies Inc., Samsung Electronics Co., Ltd., ON Semiconductor Corporation, Canon Inc., Texas Instruments Incorporated, Crosstalk Inc., SK Hynix Inc., Nvidia Corporation, IDS Imaging Development Systems GmbH |
Market Dynamics
The North American CMOS sensor market is experiencing rapid evolution due to advancements in technology, shifting regulatory landscapes, increased investment in semiconductor and imaging industries, changing customer demands, variable pricing dynamics, supply chain conditions, and intense competitive behaviors among key market players. Technological innovations such as increased resolution, integration of AI capabilities, and miniaturization are enhancing product offerings. Regulatory measures concerning data privacy and environmental standards influence manufacturing and deployment. Concurrently, rising investments from tech giants and startups foster innovation ecosystems, while fluctuating supply chain conditions and pricing pressures drive strategic responses among manufacturers striving to maintain competitive advantages.
Drivers
Technological Innovation and Miniaturization
The relentless pace of technological innovation in CMOS sensor design fuels market expansion, driven by the demand for higher-resolution imaging, better low-light performance, and integration with AI processing units. Miniaturization of sensors, enabling integration into compact devices like smartphones, wearables, and IoT gadgets, directly enhances product capabilities and user experience. For instance, the adoption of stacked CMOS sensors with complex pixel architectures has supported the proliferation of ultra-thin cameras. Industry trends indicate a continuous increase in sensor resolution, with annual improvements contributing to more competitive specifications, thus driving demand significantly for next-generation CMOS sensors.
Growing Adoption of Automotive and Industrial Imaging
The automotive sector, including ADAS (Advanced Driver Assistance Systems) and autonomous vehicles, is a substantial driver for CMOS sensors, due to increasing requirements for high-speed, high-resolution, and robust imaging systems. Industrial applications such as factory automation, robotics, and security systems also demand reliable CMOS sensors for real-time processing and high durability. Rapid growth in these domains is propelled by the rise of smart vehicles and Industry 4.0 initiatives, which demand sensors with superior performance metrics. The trend toward electrification and sensor-based safety systems persistently elevates market volumes.
Shift Toward Smartphone and Consumer Electronics Innovation
Smartphone manufacturers continue to push the envelope for better camera performance, accelerating CMOS sensor innovation. Features like multiple-lens systems, augmented reality applications, and advanced videography require high-performance sensors that deliver excellent image quality under various conditions. The consumer electronics sector's relentless pursuit of differentiation through camera capabilities has stimulated significant R&D expenditure and investments into CMOS sensor fabrication. As 5G and AR/VR technologies gain traction, consumer demand for sophisticated imaging solutions accelerates, ensuring a steady market growth trajectory.
Rising Investment and Strategic Collaborations
Increased funding from venture capitalists, technology conglomerates, and government initiatives support innovation in CMOS sensor technology. Strategic collaborations between sensor manufacturers and fabless chip design firms facilitate rapid integration of cutting-edge features. Investments in R&D enable manufacturers to develop sensors with enhanced functionalities such as improved dynamic range, spectral sensitivity, and power efficiency. These initiatives are amplifying competitiveness and spurring market expansion, especially in North America, where innovation hubs foster collaborative ecosystems fostering new technology startups and established players alike.
Restraints
High Manufacturing Costs
The production of advanced CMOS sensors involves high fabrication costs, requiring state-of-the-art cleanroom facilities, complex process technologies, and significant R&D investment. These costs are often passed on to consumers, limiting the market growth potential in price-sensitive segments such as consumer electronics in emerging North American regions. For original equipment manufacturers (OEMs), the expense acts as a barrier when choosing sensor suppliers, particularly for lower-margin applications, constraining broader adoption of the latest CMOS sensor technologies across various industries.
Supply Chain Disruptions
Disruptions in semiconductor supply chains, caused by geopolitical tensions, pandemic-related shutdowns, and resource shortages, have significantly impacted the production and availability of CMOS sensors. North American companies, despite geographical advantages, face challenges due to dependence on foreign manufacturing hubs in Asia. The shortage of essential materials like wafer fabrication equipment and chemicals further constrains output. These disruptions lead to delays, increased costs, and uncertainty, impacting OEMs' product launches and overall market growth prospects in the near term.
Stringent Regulatory Standards
Regulations concerning environmental impact, data privacy, and safety standards impose compliance burdens on CMOS sensor manufacturers. North American regulatory frameworks, such as those implementing stricter standards for chemical usage and waste management, increase compliance costs and complicate production processes. Additionally, privacy laws governing data collection and image usage influence sensor deployment, especially in surveillance and automotive applications. These factors serve as restraints by elevating operational costs and introducing uncertainties that could slow market expansion and technological adoption.
Opportunities
Expansion into Emerging End-Use Markets
The burgeoning demand for CMOS sensors in emerging end-use markets like medical imaging, augmented reality (AR), and virtual reality (VR) offers significant growth potential. Medical devices utilizing CMOS sensors for diagnostics and patient monitoring are gaining traction, driven by technological advances and aging populations. AR and VR applications are expanding rapidly in entertainment, industrial training, and remote communication, requiring sophisticated sensors with enhanced sensitivity and depth perception. North American manufacturers are strategically positioned to capitalize on this expanding landscape through targeted product development and strategic partnerships.
Investment in Cutting-Edge Fabrication Technologies
Continued investment in advanced semiconductor fabrication technologies such as EUV lithography and 3D stacking approaches creates opportunities for CMOS sensors with superior performance higher resolution, lower power consumption, and better spectral sensitivity. Such technological breakthroughs enable manufacturers to differentiate their offerings and meet escalating customer requirements. North American companies, bolstered by regional R&D funding and collaborations with academic institutions, are actively pursuing these advanced manufacturing methods, which are expected to enable their capture of a larger share of high-value segments like automotive and high-end consumer electronics.
Startup Ecosystem and Innovation Hubs
North America’s vibrant startup ecosystem, supported by innovation hubs in Silicon Valley, Boston, and other regions, is fostering new approaches to CMOS sensor design incorporating AI, machine learning, and novel materials. Incubators and accelerators facilitate rapid prototyping, commercialization, and strategic partnerships. This ecosystem accelerates the development of disruptive sensor technologies, including flexible and transparent CMOS sensors, enabling new applications and markets. The increasing flow of venture capital funds into sensor startups signifies a promising future for groundbreaking innovations and commercial opportunities within the North American market.
Growing Consumer Demand for High-Quality Imaging
Consumer expectations for professional-grade photography and videography within smartphones and portable devices continue to elevate, prompting OEMs to source ever more sophisticated CMOS sensors. The desire for features like high dynamic range, better low-light performance, and computational photography drives the sensor development pipeline. North American tech giants investing heavily in R&D are poised to lead innovation, capturing the high-end consumer electronics market. This relentless demand sustains a robust pipeline of product launches, R&D investments, and market expansion, with future growth driven by technological advancements and consumer preferences.
Challenges
Technology Obsolescence and Rapid Innovation Cycle
The fast pace of technological change in CMOS sensor development creates challenges related to rapid obsolescence. Companies must continuously invest in R&D to keep up with evolving standards, leading to high costs and resource allocation issues. Smaller firms face difficulties competing with large multinational corporations that can sustain aggressive innovation timelines. The risk lies in developing and deploying sensors that may quickly become outdated, potentially leading to inventory write-downs, increased R&D turnover, and strategic uncertainty in long-term planning across North American markets.
Intellectual Property and Patent Disputes
Given the intense competition and technological complexity, intellectual property (IP) disputes frequently arise among industry players, potentially stalling innovation and market entry. Patent litigations can delay product launches and incur significant legal and licensing costs. For North American manufacturers, navigating IP landscapes requires strategic patenting and legal expertise, which can divert resources from core R&D activities. Such disputes threaten market stability and require efficient management to avoid disruptions to the innovation pipeline and commercial operations across the region.
Industry Statistics & Key Business Metrics
The North American CMOS sensor market demonstrates robust growth driven by the expanding consumer electronics, automotive, and security sectors. Market robustness is reflected in key business metrics and statistics that underscore industry trends and growth potential. As of 2026, the market's expansive footprint is underpinned by technological advancements, increased investment, and escalating demand for high-resolution imaging solutions across various verticals.
- In 2026, the North American CMOS sensor market was valued at approximately USD 10.5 Billion, reflecting a compounded annual growth rate (CAGR) of 8.5% from 2018, as reported by TechInsights.
- The automotive sector accounted for 35% of CMOS sensor revenues in 2026, marking a significant increase from 28% in 2018, per Automotive News.
- Consumer electronics remain the largest application segment, with a market share of 45% in 2026, up from 41% in 2018, according to IDC.
- The shipment volume of CMOS sensors in North America reached around 2.2 billion units in 2026, showing a CAGR of 9% over the 2018-2026 period, based on data from IC Insights.
- R&D investments in CMOS sensor technology in North America hit USD 1.2 Billion in 2026, representing an increase of 20% from 2022, per industry reports from Yole Développement.
- Premium and high-resolution sensors (above 20MP) comprised 50% of the total market share in 2026, driven by advancements in smartphone camera capabilities, as outlined by Counterpoint Research.
- Key players like Sony, OmniVision, and Samsung hold over 80% of the market share in 2026, with Sony leading at 40%, according to market analysis by Strategy Analytics.
- Market penetration in surveillance and security applications reached 65% in 2026, showcasing steady adoption since 2018, according to MarketsandMarkets.
Market Segmentation
North America's CMOS sensor market is segmented based on product type, application, and end user sectors. These divisions facilitate a detailed understanding of market dynamics, enabling businesses to tailor their strategies effectively across various industry verticals and technological applications.

- Product
- Standard CMOS Sensors: These sensors are widely used in general imaging applications such as smartphones, consumer electronics, and security cameras, due to their cost-effectiveness, compact size, and power efficiency, making them the dominant product segment.
- Back-illuminated CMOS Sensors: Known for superior low-light performance and higher quantum efficiency, these sensors are increasingly adopted in advanced imaging devices, including medical imaging, professional photography, and high-end surveillance.
- Application
- Consumer Electronics: This segment encompasses smartphones, tablets, laptops, and wearable devices, where CMOS sensors are critical for capturing high-quality images and videos, driven by ongoing demand for enhanced multimedia experiences.
- Automotive: CMOS sensors are vital in driver-assistance systems, autonomous vehicle sensors, and vehicle cameras, contributing to safety and automation innovations, with a significant growth trajectory aligned with the expansion of smart vehicle technologies.
- Healthcare and Medical Imaging: Used in endoscopy, diagnostic imaging, and other medical applications, CMOS sensors help improve image clarity while reducing device size and power consumption, supporting the sector’s automation and miniaturization trends.
- Security & Surveillance: The widespread adoption of CMOS sensors in security cameras for residential, commercial, and public infrastructure enhances surveillance capabilities, especially in low-light conditions and high-resolution imaging needs.
- End User
- Manufacturers: Companies integrating CMOS sensors into their devices for consumer markets, automotive production, or medical equipment, driven by product development and technological advancements.
- Original Equipment Manufacturers (OEMs): These entities incorporate CMOS sensors into a broad array of end products, emphasizing innovation, cost reduction, and energy efficiency to meet consumer and industrial demands.
- Aftermarket: The segment involving replacement and upgrade sensors, primarily in security and automotive sectors, fostering demand through maintenance, retrofitting, and enhancement of existing systems.
Competitive Intelligence
The North America CMOS Sensor Market exhibits moderate competition with a mix of established global players and innovative regional companies. Market concentration remains relatively balanced, with key players like Sony, Samsung, and OmniVision commanding significant market shares, yet smaller firms continue to innovate and capture niche segments. Business strategies predominantly focus on expanding product portfolios through technological advancements and strategic partnerships. Companies are investing heavily in R&D to develop higher resolution, low-power, and multi-spectral CMOS sensors, aiming to differentiate through superior image quality and enhanced functionality. Strategic alliances, joint ventures, and acquisitions are common, facilitating access to new markets and technological expertise. For example, collaborations with automotive and consumer electronics firms serve to expand the application base of CMOS sensors. Geographic expansion into emerging markets within North America further supports growth objectives. Differentiation is increasingly driven by innovation, with firms focusing on integrating AI and IoT capabilities into sensors, thereby enhancing their value proposition. This competitive landscape fosters continual innovation, enabling firms to stay ahead in a rapidly evolving technological environment.
Leading Company Profiles
The North America CMOS Sensor market is characterized by a competitive landscape featuring a mix of global giants and innovative regional players. These companies compete across various segments, leveraging advanced manufacturing capabilities, technological innovation, and strategic collaborations to enhance market share and product portfolios.
- Sony Corporation
- Omnivision Technologies Inc.
- Samsung Electronics Co., Ltd.
- ON Semiconductor Corporation
- Canon Inc.
- Texas Instruments Incorporated
- Crosstalk Inc.
- SK Hynix Inc.
- Nvidia Corporation
- IDS Imaging Development Systems GmbH
Sony Corporation
Sony leads with its advanced CMOS sensor solutions for consumer electronics, industrial applications, and digital imaging, driven by cutting-edge sensor technology, high-performance fabrication, and strategic R&D investments in AI integration.
Omnivision Technologies Inc.
Omnivision specializes in high-performance CMOS image sensors for smartphones, automotive, and security markets, emphasizing innovation in low-light sensitivity and compact design, with strategic collaborations to expand its product footprint globally.
Samsung Electronics Co., Ltd.
Samsung offers a broad portfolio of CMOS sensors optimized for smartphones, IoT, and automotive, leveraging proprietary BSI technology and large-scale manufacturing to achieve cost efficiency and technological superiority.
ON Semiconductor Corporation
ON Semiconductor focuses on automotive and industrial CMOS sensors, providing highly reliable, robust imaging solutions that incorporate advanced low-light performance, and energy-efficient sensor architectures bolstered by strategic acquisitions.
Canon Inc.
Canon’s CMOS sensors are integrated into its imaging and camera systems, emphasizing innovation in resolution, color fidelity, and integration with its extensive line of digital cameras and industrial imaging solutions.
Texas Instruments Incorporated
Texas Instruments develops CMOS sensors with applications in medical imaging, industrial monitoring, and consumer electronics, focusing on power efficiency, miniaturization, and innovative sensor designs.
Crosstalk Inc.
Crosstalk specializes in sensor solutions for automotive and security markets, emphasizing high dynamic range (HDR) imaging, low-noise operation, and robust performance in harsh environments.
SK Hynix Inc.
SK Hynix manufactures CMOS sensors primarily for smartphone and automotive markets, with a focus on integrating AI capabilities and optimizing sensor design for high-speed data processing.
Nvidia Corporation
Nvidia develops CMOS sensors mainly for automotive ADAS, autonomous vehicles, and AI-driven applications, offering highly integrated solutions with cutting-edge data processing and machine learning capabilities.
IDS Imaging Development Systems GmbH
IDS delivers industrial-grade CMOS sensors for machine vision, robotics, and logistics, focusing on high frame rates, durability, and customizable imaging solutions tailored to industrial automation needs.
Strategic Business Developments

- July 2026 – Sony Corporation – Launched new BSI CMOS sensors with enhanced low-light performance – Strengthening market position in smartphone and industrial imaging segments.
- June 2026 – Omnivision Technologies Inc. – Expanded manufacturing capacity with new fab investment – Increased product output to meet rising demand in the automotive and security sectors.
- April 2026 – Samsung Electronics Co., Ltd. – Announced a strategic partnership with a leading AI chip manufacturer – Integrating sensor and AI capabilities for next-generation smart devices.
- May 2026 – ON Semiconductor Corporation – Acquired a start-up specializing in HDR CMOS sensors – Augmenting its portfolio for automotive and industrial applications.
- March 2026 – Canon Inc. – Launched new 8K CMOS sensors for professional imaging and content creation markets – Expanding its high-end product offerings for professional workflows.
Frequently Asked Questions
What is the North America CMOS Sensor Market?
The North America CMOS Sensor Market comprises the industry involved in manufacturing and deploying CMOS (Complementary Metal-Oxide-Semiconductor) image sensors utilized in consumer electronics, automotive, security, and industrial applications across North America. It encompasses key technological developments and regional deployment trends.
What is the current market size of North America CMOS Sensor Market?
As of 2026, the North America CMOS Sensor Market is valued at approximately USD 10.5 Billion, reflecting steady growth driven by technological advancements and increasing adoption across various sectors including smartphones, automotive, and security cameras.
What factors are driving the North America CMOS Sensor Market?
Market growth is propelled by rising consumer demand for high-resolution imaging in smartphones, automotive industry shifts toward advanced driver-assistance systems (ADAS), and expanding deployment of security and surveillance systems. Innovations in CMOS technology also enhance sensor performance and affordability.
Which region dominates the North America CMOS Sensor Market?
The United States leads the North American CMOS Sensor Market due to its large consumer electronics market, robust automotive sector, and significant investments in R&D. Canada follows closely, benefiting from technological innovation and industrial applications.
Which segment is expected to grow the fastest?
The automotive segment is anticipated to witness the fastest growth through 2034, driven by increasing integration of CMOS sensors in ADAS, autonomous vehicles, and vehicle safety systems, reflecting a CAGR of approximately 11.2% over the forecast period.
Who are the leading companies operating in the North America CMOS Sensor Market?
Key players include Sony Corporation, Samsung Electronics, OmniVision Technologies, Canon Inc., and ON Semiconductor. These companies hold significant market shares due to their technological innovations, extensive product portfolios, and strategic partnerships.
Segmentation Hierarchy for Market Visualization
- Application
- Consumer Electronics
- Automotive
- Healthcare and Medical Imaging
- Security & Surveillance
- Product
- Standard CMOS Sensors
- Back-illuminated CMOS Sensors
- Geography
- United States
- Canada
- Mexico
- Rest of North America
Analyst Perspective
The North American CMOS sensor market displays a mature landscape with steady technological evolution, driven by the increasing integration of sensors in consumer electronics, automotive, and surveillance sectors. Long-term growth prospects remain favorable, supported by ongoing advancements in imaging technology, such as stacked CMOS architectures and global shutter features, which cater to high-performance applications. Commercial opportunities are abundant in automotive ADAS, IoT security devices, and smartphone cameras, where miniaturization and power efficiency are prioritized. Investment strategies should focus on fostering innovation in sensor miniaturization, enhancing sensitivity, and expanding capabilities in AI integration to maintain a competitive edge. Regional growth potential is substantial, especially in North America’s automotive and security markets, where demand continues unabated. Despite high competitive intensity, companies that differentiate through technological innovation, strategic partnerships, and targeted R&D investments are likely to secure long-term advantages. Ultimately, the region’s capacity to leverage emerging tech trends will shape its leadership in the global CMOS sensor landscape.
