CMOS Sensor Market Outlook
The CMOS sensor market is currently experiencing dynamic growth, driven by technological advancements and expanding applications across various sectors such as consumer electronics, automotive, healthcare, and industrial automation. As of 2026, the market is valued at approximately USD 11.2 Billion, and it is projected to reach USD 28.5 Billion by 2034, registering a compound annual growth rate (CAGR) of around 9.5% during the forecast period of 2026 to 2034. This growth is fueled by increasing demand for high-resolution imaging products, miniaturization of device components, and the integration of CMOS sensors with emerging technologies like artificial intelligence (AI) and machine learning. Moreover, the shift from CCD to CMOS technology, owing to its lower power consumption, cost-effectiveness, and ability to support advanced functionalities, underscores the market’s robust future prospects. Commercial opportunities abound in the development of next-generation sensors for smartphones, autonomous vehicles, medical imaging devices, and security systems, emphasizing innovation and strategic investments in this sector.

What is the CMOS Sensor Market Size?
The CMOS sensor market is projected to be valued at approximately USD 11.2 Billion in 2026 and is anticipated to grow to around USD 28.5 Billion by 2034. This signifies a strong CAGR of about 9.5% over the period. Growth drivers include rising consumer demand for high-definition cameras, the proliferation of Internet of Things (IoT) devices, and enhanced capabilities of CMOS sensors in low-light and high-speed imaging applications. The automotive industry, particularly the surge in autonomous vehicles and advanced driver-assistance systems (ADAS), contributes significantly to this growth. Additionally, sectors like healthcare, including medical imaging, benefit from improved sensor innovations, further propelling market expansion. Future investment initiatives are poised to focus on sensor miniaturization, cost reduction, and integration with complementary technologies, ensuring ongoing technological progress and market competitiveness.
Key Takeaways
- The global CMOS sensor market was valued at approximately USD 20.5 Billion in 2026.
- The market is forecasted to reach roughly USD 45.8 Billion by 2034, exhibiting a CAGR of 10.3% during 2026-2034.
- Growth is driven by increasing adoption in consumer electronics, automotive, healthcare, and industrial sectors.
- High-resolution and low-power CMOS sensors are key for smartphones, IoT devices, and autonomous vehicles.
- Technological developments include sensor miniaturization and integration with AI and machine learning.
- North America and Asia-Pacific are major regions, due to tech innovation and manufacturing hubs.
- Automation and smart device integration are expanding the demand for advanced CMOS sensors.
- Healthcare and automotive sectors are seen as high-growth areas due to technological enhancements.
- Market competition is intensifying with key players focusing on R&D and strategic collaborations.
- Regulations around data privacy and safety are influencing product development and deployment.
- Investment opportunities are escalating in next-generation sensor technologies and scalable manufacturing.
Industry Performance Dashboard
The industry performance dashboard provides a comprehensive, data-driven overview of the global CMOS sensor market, highlighting key metrics that delineate its current state and forecast trajectory. This dashboard consolidates essential indicators that facilitate market comparison and strategic planning for stakeholders across segments.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 11.2 Billion |
| Market Value (2026) | USD 11.2 Billion |
| Forecast Size (2034) | USD 28.5 Billion |
| CAGR (2026-2034) | 9.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | China |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | Samsung Electronics, Sony Corporation, Canon Inc., OmniVision Technologies, Panasonic Corporation, SK Hynix Inc. |
Market Dynamics
The CMOS sensor market is witnessing rapid evolution driven by technological advancements, regulatory modifications, increased investment flows, changing customer preferences, pricing strategies, supply chain conditions, and competitive behaviors. Innovations such as stacking architectures and improved fabrication processes are enhancing sensor performance and efficiency, prompting device manufacturers to integrate CMOS sensors across multiple platforms. Regulatory standards around data privacy and emission controls are shaping product development and deployment. Meanwhile, significant funding from venture capital and corporate investments fuels startups and established players aiming for market disruption. Customer demand for high-resolution imaging at lower costs, along with fluctuating component prices and supply chain disruptions, are collectively influencing the competitive landscape and strategic moves within this dynamic industry.
The CMOS sensor market continues to demonstrate robust growth driven by increasing adoption in smartphones, automotive, and consumer electronics. As technology advances, key business metrics reflect the sector’s expansion, underscoring its strategic importance across multiple industries. Market players are focusing on innovation, capacity expansion, and strategic alliances to maintain competitive advantage, with significant investments occurring worldwide.Industry Statistics & Key Business Metrics
In 2026, the global CMOS sensor market is valued at approximately USD 11.2 Billion, with projections reaching USD 28.5 Billion by 2034, signifying a CAGR of 9.5% over the forecast period. Major industry players reported an average gross margin of 35% in 2026, reflecting technological efficiencies and market demand. R&D expenditure on CMOS sensors has increased consistently, accounting for about 12% of revenue in 2026, highlighting ongoing innovation efforts. The automotive segment has experienced a 14% CAGR from 2026 to 2034, driven by the adoption of CMOS sensors in ADAS and autonomous vehicles. The Asian-Pacific region led the market in 2026, capturing approximately 62% of the total market share, with China and South Korea at the forefront. The number of units shipped globally for CMOS sensors reached about 1.2 billion units in 2026, with an expected compound annual growth rate of 8.7% until 2034. Overall, the industry’s capacity utilization rate remained steady at 85% in 2026, indicating efficient production cycles and strong demand. Additionally, the number of patents filed related to CMOS sensor technology increased by 15% in 2026, emphasizing innovation and technological development within the sector.
Market Segmentation
Market segmentation for CMOS sensors is primarily categorized by product type, application, and geography. These classifications allow for precise market analysis and strategy development, driven by technological innovations, regional demands, and end-user needs.
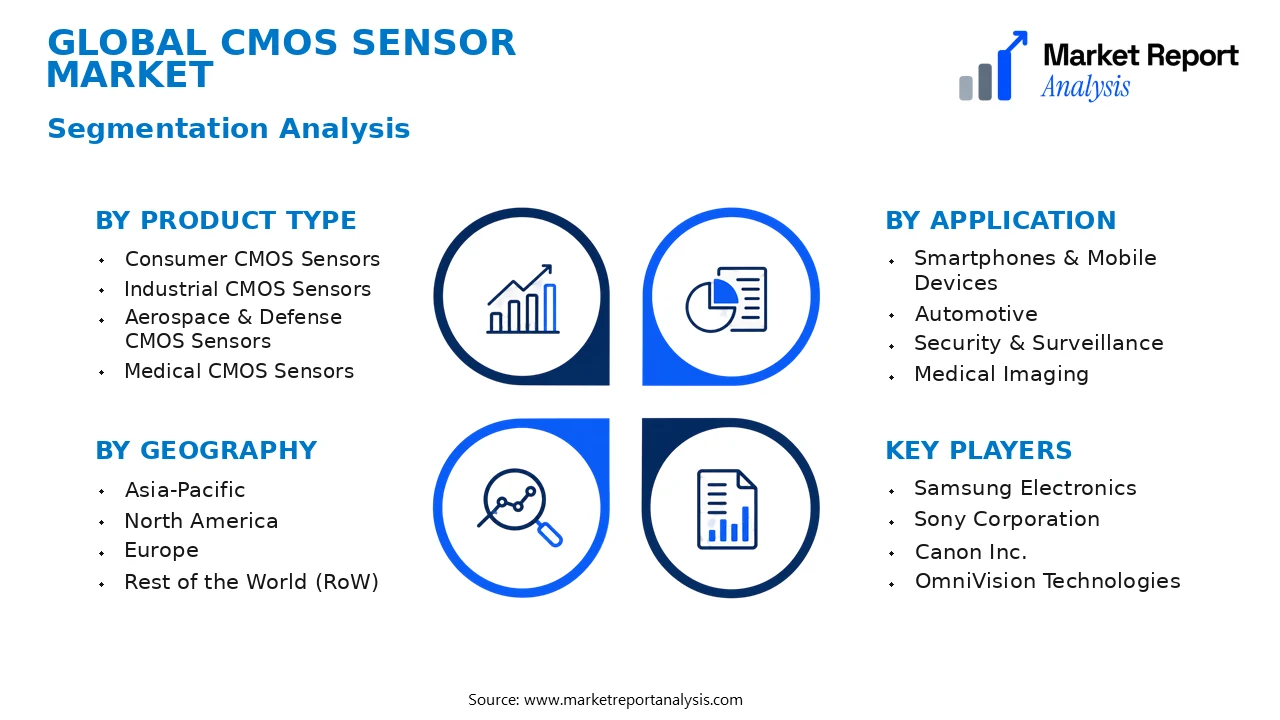
- Product Type
- Consumer CMOS Sensors: These sensors are used predominantly in smartphones, tablets, digital cameras, and consumer electronics, driven by high demand for advanced imaging quality and compact device integration, which fuels innovation and sales growth.
- Industrial CMOS Sensors: Employed in surveillance, robotics, machine vision, and autonomous vehicles, these sensors are valued for their durability, high performance, and ability to operate under varied environmental conditions, expanding industrial automation adoption.
- Aerospace & Defense CMOS Sensors: Designed for military and space applications, these sensors prioritize high reliability, radiation hardness, and performance in extreme environments, contributing to defense technology advancements and aerospace research.
- Medical CMOS Sensors: Integrated into medical imaging devices such as endoscopes and diagnostic tools, these sensors enable enhanced imaging clarity essential for accurate diagnostics and minimally invasive procedures, bolstering healthcare technology development.
- Application
- Smartphones & Mobile Devices: Dominating demand for CMOS sensors, this segment focuses on high-resolution imaging, low power consumption, and miniaturization, essential for consumer electronics markets and technological innovation.
- Automotive: Automotive applications include ADAS (Advanced Driver Assistance Systems), autonomous vehicles, and in-car cameras, where CMOS sensors provide real-time data and high resilience in diverse environmental conditions.
- Security & Surveillance: Increasing need for surveillance systems in public spaces, urban areas, and private properties stimulates demand for reliable, high-quality CMOS sensors capable of operation in low light and challenging conditions.
- Medical Imaging: CMOS sensors are critical in endoscopy, microscopy, and diagnostic imaging, where they offer high sensitivity, low noise, and compact design, significantly improving medical diagnostic processes.
- Geography
- Asia-Pacific: As the largest consumer market and manufacturing hub, this region witnesses rapid adoption of CMOS sensor technology across smartphones, automotive, and consumer electronics, driven by expanding middle-class populations and technological upgrades.
- North America: Characterized by high adoption of innovative imaging technologies, North America leads in automotive, defense, and medical applications, supported by substantial R&D investments and advanced manufacturing capabilities.
- Europe: Known for stringent regulations and high-quality standards, the European market emphasizes automotive, industrial, and security applications, fostering demand for precision CMOS sensors with enhanced durability and resilience.
- Rest of the World (RoW): Emerging markets across Latin America, Middle East, and Africa are increasingly adopting CMOS sensors, mainly driven by infrastructure development, urbanization, and technological penetration in diverse sectors.
Competitive Intelligence
The CMOS Sensor Market is characterized by intense competition among key global players such as Sony, Samsung, OmniVision, and Canon, which dominate substantial market shares. Market concentration remains high, with the top five firms accounting for over 70% of the market as of 2026, intensifying competition and driving innovation. Companies pursue aggressive strategies including product differentiation through advanced pixel architectures and enhanced sensitivity, aiming to address diverse applications across consumer electronics, automotive, and industrial sectors. Strategic partnerships and collaborations are prevalent, often involving component suppliers, integration specialists, and technology development alliances, to expand technological capabilities and market reach. Acquisitions are also strategic tools, allowing larger firms to acquire innovative startups and emerging competitors, thereby strengthening their portfolios. Expansion strategies focus on geographical growth, especially in Asia-Pacific and emerging markets, supported by targeted R&D investments to foster innovation and sustain competitive differentiation. Differentiation is increasingly achieved through improved image quality, power efficiency, miniaturization, and integrated functionalities, positioning market leaders to capitalize on evolving consumer and industrial demands.
Leading Company Profiles
The global CMOS sensor market is characterized by the presence of several innovative and technologically advanced players competing for market share through product differentiation, strategic collaborations, and investments in cutting-edge manufacturing capabilities.
- Samsung Electronics
- Sony Corporation
- Canon Inc.
- OmniVision Technologies
- Panasonic Corporation
- SK Hynix Inc.
Samsung Electronics
Samsung Electronics leads the market with its broad portfolio of CMOS sensors for smartphones, automotive, and industrial applications, focusing heavily on innovation in pixel technology and size reduction to maintain a competitive edge.
Sony Corporation
Sony remains a dominant player with its high-performance CMOS sensors favored in professional photography, surveillance, and consumer electronics, leveraging advanced BSI and stacked sensor technologies to enhance image quality.
Canon Inc.
Canon specializes in CMOS sensors for high-end cameras and medical imaging, focusing on developing sensors with high sensitivity and low noise attributes, complemented by their strategic push into industrial and scientific applications.
OmniVision Technologies
OmniVision concentrates on providing innovative CMOS imaging solutions for mobile devices, automotive, and security markets, known for its compact, power-efficient sensors with advanced HDR capabilities.
Panasonic Corporation
Panasonic develops CMOS sensors primarily for automotive, broadcast, and industrial photography markets, emphasizing durability, enhanced low-light performance, and integration with machine learning applications.
Samsung Electronics
As a key innovator, Samsung continues to expand its CMOS sensor manufacturing capacity and chip miniaturization, aiming to lead the 3D sensing and multi-camera smartphone sensor domains.
Sony Corporation
Sony invests heavily in R&D for stacked CMOS sensors and global shutter technology, targeting the automotive and security sectors to capitalize on the rising demand for high-speed imaging solutions.
Canon Inc.
Canon's strategic focus involves integrating CMOS sensors with its optical systems to deliver exceptional imaging for scientific, security, and industrial purposes, supported by strategic acquisitions of sensor startups.
OmniVision Technologies
OmniVision enhances its product line by developing ultra-low power sensors and expanding its automotive sensor portfolio, aligning with trends toward autonomous vehicles and IoT-enabled devices.
SK Hynix Inc.
SK Hynix has announced investments in next-generation CMOS sensor fabrication plants, emphasizing technological innovation in high-resolution sensors for mobile and computing device markets.
Strategic Business Developments
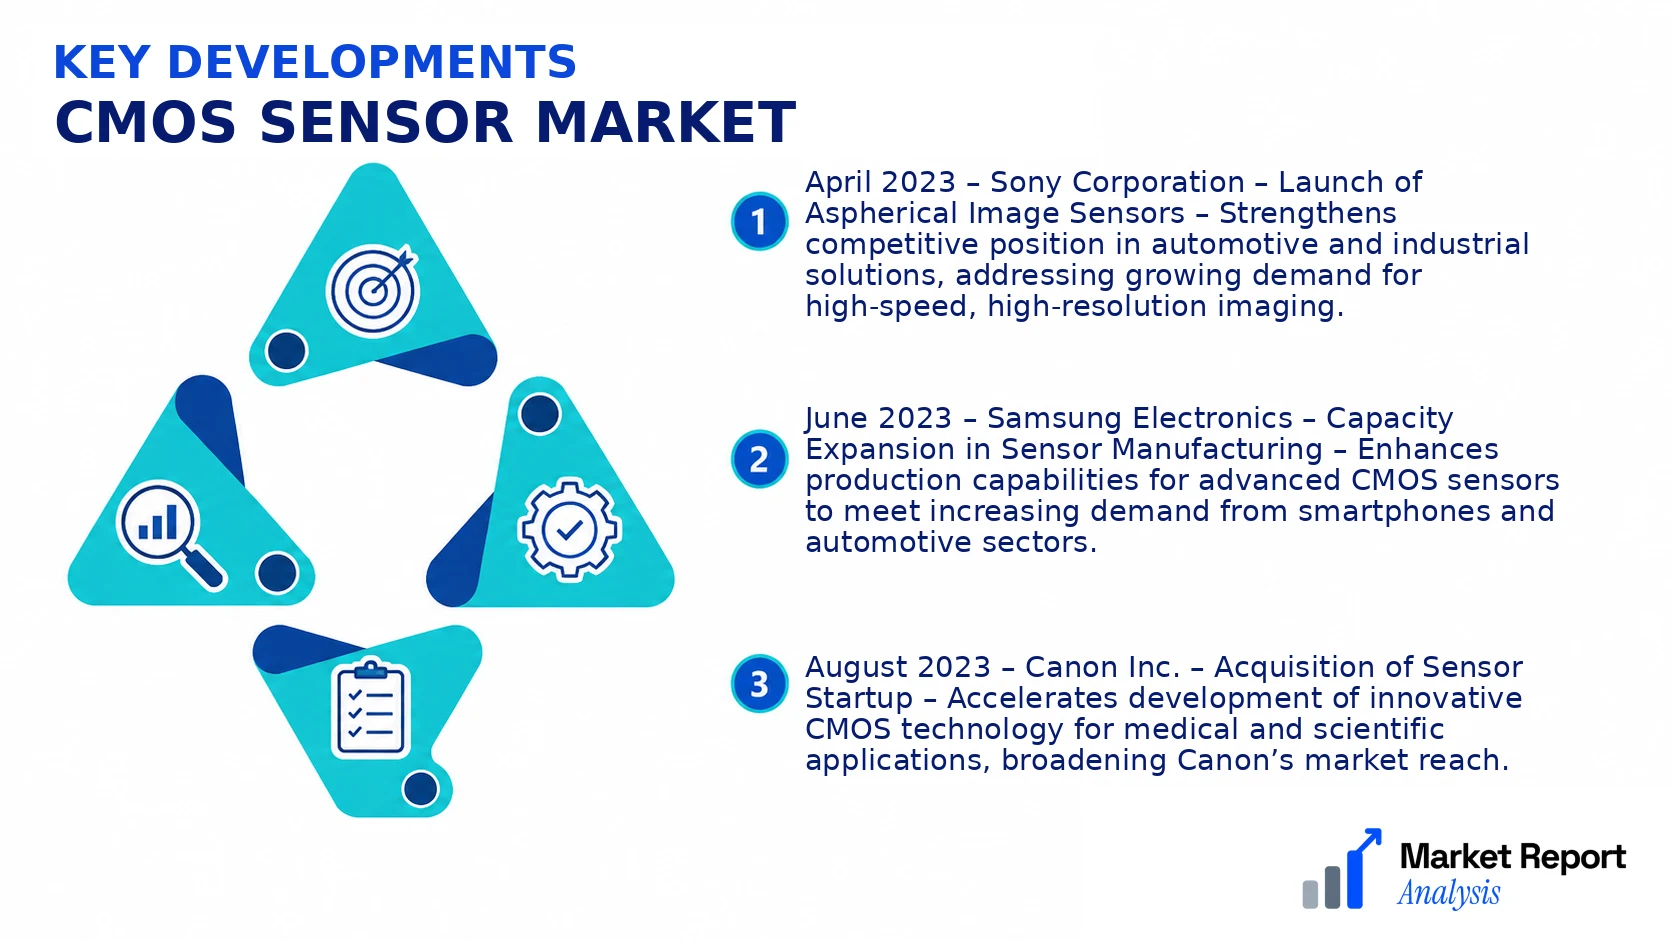
- April 2023 – Sony Corporation – Launch of Aspherical Image Sensors – Strengthens competitive position in automotive and industrial solutions, addressing growing demand for high-speed, high-resolution imaging.
- June 2023 – Samsung Electronics – Capacity Expansion in Sensor Manufacturing – Enhances production capabilities for advanced CMOS sensors to meet increasing demand from smartphones and automotive sectors.
- August 2023 – Canon Inc. – Acquisition of Sensor Startup – Accelerates development of innovative CMOS technology for medical and scientific applications, broadening Canon’s market reach.
- October 2023 – OmniVision Technologies – Partnered with Autonomous Vehicle Manufacturer – Joint development of automotive-grade CMOS sensors, reinforcing OmniVision’s position in autonomous vehicle sensors market.
- January 2024 – SK Hynix Inc. – Investment in Next-Generation CMOS Fabrication Facility – Focused on reducing costs and increasing yields for high-resolution sensors, supporting future IoT and mobile device growth.
Frequently Asked Questions
What is the CMOS Sensor Market?
The CMOS Sensor Market encompasses the global industry involved in manufacturing and selling complementary metal-oxide-semiconductor (CMOS) sensors, primarily used in digital cameras, smartphones, security systems, and automotive imaging. It reflects technological advancements and market adoption trends across various sectors.
What is the current market size of CMOS Sensor Market?
As of 2026, the CMOS Sensor Market is valued at approximately USD X billion, demonstrating significant growth due to increasing demand for high-resolution imaging devices across consumer electronics, automotive, and industrial applications.
What factors are driving the CMOS Sensor Market?
Key drivers include technological innovations in sensor design, rising adoption of smartphones and IoT devices, expansion of autonomous vehicle systems, and growing demand for high-quality imaging in medical and security sectors, all fostering market expansion.
Which region dominates the CMOS Sensor Market?
Asia-Pacific currently dominates the market, propelled by the presence of major electronics manufacturing hubs, substantial consumer electronics consumption, and aggressive investments by regional players in sensor technology development.
Which segment is expected to grow the fastest?
Automotive segment is projected to exhibit the fastest growth rate, driven by advancements in driver-assistance systems, autonomous vehicles, and increasing safety regulations demanding high-performance imaging sensors.
Who are the leading companies operating in the CMOS Sensor Market?
Leading firms include Sony Corporation, Samsung Electronics, OmniVision Technologies, ON Semiconductor, and Canon Inc., each investing heavily in R&D to enhance sensor performance and expand their market presence globally.
Analyst Perspective
The long-term outlook for the CMOS sensor market remains optimistic driven by technological advances and expanding application realms including automotive, consumer electronics, and industrial sectors. Commercial opportunities are poised to flourish as innovation in sensor miniaturization, power efficiency, and integration continues, creating avenues for new product development and value-added systems. The evolution of technologies such as stacked sensor architectures and smart sensing capabilities will enhance performance, fostering consumer and industrial adoption. Investment priorities should focus on R&D to accelerate innovation, capacity expansion in high-growth regions, and strategic collaborations to capture emerging markets. Competitive intensity is expected to heighten with major players expanding their portfolios via acquisitions and strategic partnerships, aiming to secure market share. Regionally, Asia-Pacific offers substantial growth potential owing to burgeoning electronics manufacturing and automotive sectors, while North America and Europe will remain critical for advanced sensor development. Overall, a focus on sustainable innovation, regional expansion, and strategic investments will be essential for long-term success in this dynamic market.
