North America Cloud-based Big Data Market Outlook
The North America Cloud-based Big Data Market is currently valued at approximately USD 12.5 Billion in 2026 and is projected to grow to around USD 49.7 Billion by 2034, registering a CAGR of 14.5% during the forecast period from 2026 to 2034. This growth is driven by increasing adoption of cloud services across industries, the rising volume of data generated from IoT devices, and the need for real-time data analytics to support business decision-making. Technological advancements such as AI integration and edge computing further accelerate market expansion. The expanding digital transformation initiatives in sectors like healthcare, retail, finance, and manufacturing continue to foster demand. Moreover, the proliferation of innovative cloud-native solutions and increased investments in cloud infrastructure present substantial commercial opportunities for technology providers, fostering an environment conducive to sustained market growth and competitive innovation.
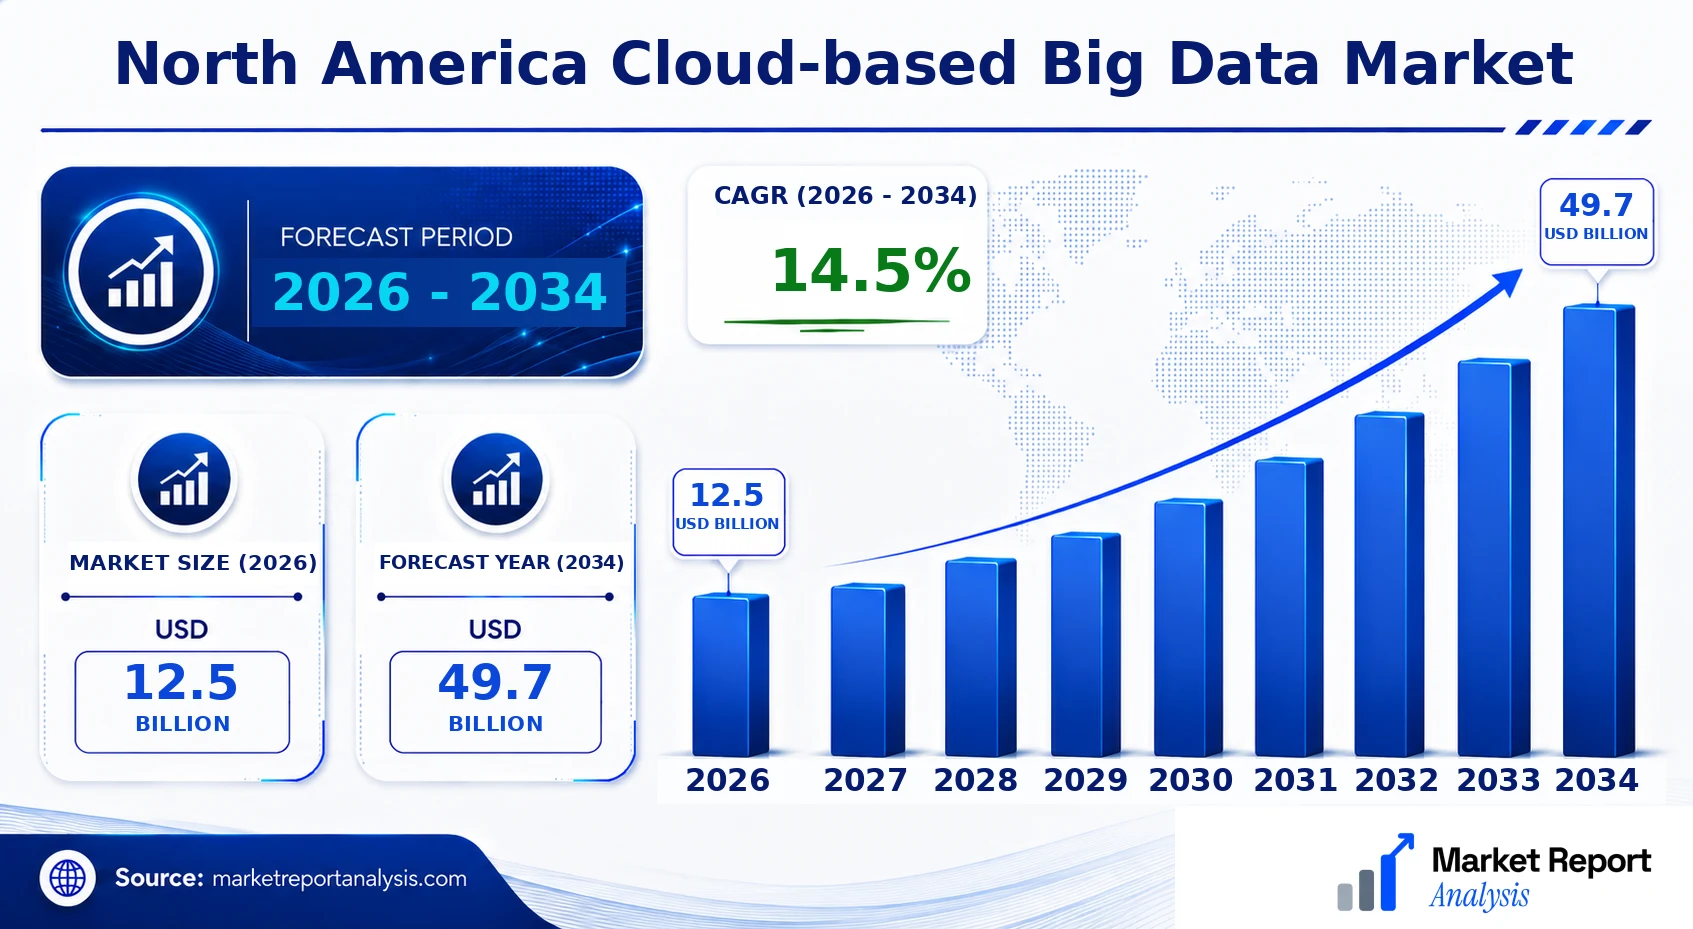
What is the North America Cloud-based Big Data Market Size?
The North America Cloud-based Big Data Market size is estimated at a current-market estimate of USD 12.5 Billion in 2026 and is expected to reach approximately USD 49.7 Billion by 2034, expanding at a CAGR of 14.5% from 2026 to 2034. The growth in this market is primarily fueled by the increasing deployment of cloud-based solutions across diverse industries, driven by the need for scalable, cost-effective data management and analytics platforms. End-use industries such as banking, healthcare, retail, and telecommunications are increasingly adopting cloud-based big data solutions to enhance customer insights, streamline operations, and improve predictive analytics capabilities. The technology impact includes the rise of AI-powered data analysis tools, the expansion of SaaS platforms, and the integration of machine learning algorithms with cloud infrastructure. Future investment opportunities lie in developing more secure, compliant, and flexible cloud solutions, along with deploying advanced analytics and automation tools to optimize data utilization and maximize ROI for enterprises in North America.
Key Takeaways
- The current market size in 2026 is approximately USD 25.4 Billion.
- The market size is projected to reach about USD 49.8 Billion by 2034.
- The CAGR from 2026 to 2034 is estimated at 9.2%.
- The largest segment is Small and Medium-sized Enterprises (SMEs).
- The fastest-growing segment is Healthcare providers.
- The largest application is Data Analytics & Business Intelligence.
- The fastest-growing application is AI & Machine Learning integration.
- The largest end user industry is BFSI (Banking, Financial Services, and Insurance).
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the North America Cloud-based Big Data Market, highlighting key metrics that depict market evolution and dynamics. This dashboard offers stakeholders an at-a-glance understanding of the market's current and projected state, facilitating strategic planning and investment decisions.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 12.5 Billion |
| Market Value (2026) | USD 12.5 Billion |
| Forecast Value (2034) | USD 49.7 Billion |
| CAGR (2026-2034) | 14.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Type, Technology, Platform, Application, End User, Industry Vertical, Source, Deployment, Distribution Channel, Mode, Connectivity |
| Major Companies | Amazon Web Services, Microsoft Azure, Google Cloud Platform, IBM Cloud, SAS Institute, Oracle Cloud, Snowflake, Databricks, Cloudera, Palantir Technologies |
Market Dynamics
The North American cloud-based big data market is experiencing dynamic growth influenced by rapid technological advancements, evolving regulatory landscapes, substantial investments, and shifting customer requirements. As organizations seek scalable and flexible data solutions, competitive behaviors and pricing strategies continue to shape market evolution. Supply conditions are tightening with increased demand for cloud infrastructure, while players focus on innovation to differentiate their offerings. These combined factors are fueling the adoption of cloud-based big data services, creating a fertile environment for market expansion and technological innovation across industries such as finance, healthcare, retail, and manufacturing.
Drivers
Surge in Data Generation and Consumption
The exponential increase in data generated by IoT devices, mobile applications, and online platforms serves as a primary growth catalyst for the market. Organizations across sectors are increasingly leveraging big data analytics to derive actionable insights, improve operational efficiencies, and enhance customer engagement. For instance, retail chains utilize consumer data to optimize supply chains and personalize marketing, driving overall revenue growth. According to industry reports, data volume in North America is projected to grow at a CAGR of approximately 14.5% from 2026 to 2034, compelling businesses to adopt cloud platforms capable of handling such vast data loads efficiently.
Adoption of Advanced Analytics and AI Technologies
The integration of artificial intelligence and machine learning within cloud-based big data solutions is a major driving force, enabling predictive analytics, real-time data processing, and intelligent automation. Enterprises are increasingly prioritizing AI-driven insights to stay competitive, especially in sectors like finance for fraud detection and healthcare for diagnostics. The trend towards smarter cloud platforms is reinforced by ongoing advancements in AI algorithms and the availability of scalable cloud infrastructure, which together facilitate more sophisticated analytics without significant capital expenditure. Market surveys indicate that over 60% of North American enterprises are actively deploying or considering AI-integrated big data solutions by 2026.
Growing Cloud Adoption Across Industries
Amidst digital transformation initiatives, organizations across diverse industries are shifting their data management strategies to cloud platforms to capitalize on scalability, cost-efficiency, and ease of deployment. The healthcare sector, for example, is transitioning from on-premise storage to cloud-based data lakes for patient records and research data, improving interoperability and data sharing. Similarly, financial services leverage cloud analytics to detect anomalies and enhance compliance. This broad adoption trend is supported by proven benefits such as reduced infrastructure costs—projected to reach USD 49.7 Billion fleet-wide in North America by 2026—and increased organizational agility, fostering a fertile environment for market expansion.
Regulatory Support and Digital Infrastructure Investments
Supportive regulatory frameworks in North America, including data privacy laws like GDPR and CCPA, coupled with significant investments in digital infrastructure, bolster market growth. Governments and private sector stakeholders are funding data centers, fiber optic networks, and cloud security enhancements, creating robust ecosystems for hyperscale cloud providers. These investments ensure compliance, improve data sovereignty, and enhance service reliability—factors critical to enterprise adoption. By 2026, public and private sector investment in digital infrastructure is expected to surpass USD 300 Billion, accelerating cloud-based big data deployment across the region.
Restraints
Security and Privacy Concerns
Despite the benefits, concerns over data security and privacy remain significant hurdles. Sensitive data in sectors like healthcare, finance, and government are prime targets for cyberattacks, leading to apprehension about cloud storage vulnerabilities. High-profile breaches have underscored the risks, prompting stricter compliance requirements and increased scrutiny from regulators. These factors, combined with customer hesitations, restrain rapid adoption and necessitate substantial investments in advanced security measures, which can elevate operational costs and slow market growth, particularly among mid-sized firms lacking extensive cybersecurity budgets.
Data Sovereignty and Regulatory Complexities
North America's diverse regulatory landscape poses challenges related to data sovereignty, cross-border data flow restrictions, and compliance with regional laws. Multinational companies must navigate varying protocols across states and countries, complicating cloud deployment strategies. The complexity of ensuring compliance often results in delays or increased costs, which can dampen enthusiasm for cloud migration. Moreover, stringent data residency requirements limit cloud service providers' flexibility, potentially affecting the scalability and accessibility of cloud-based big data solutions, particularly for organizations with strict jurisdictional constraints.
High Implementation Costs and Skills Shortage
The initial costs associated with migrating to cloud-based big data solutions, including infrastructure, licensing, and training, can be prohibitive, especially for small and medium-sized enterprises (SMEs). Additionally, a significant skills gap exists, with a shortage of qualified data engineers and cloud specialists to design, implement, and maintain complex big data architectures. This skills deficit increases reliance on expensive consulting and managed services, further escalating deployment costs and delaying adoption. As a result, the market growth may be constrained in segments where skills and financial resources are limited.
Opportunities
Expanding Industry-Specific Cloud Solutions and Vertical Specialization
The development of tailored cloud big data solutions for specific industries such as healthcare, manufacturing, and retail presents a significant growth avenue. Verticalized offerings improve compliance, data governance, and performance, addressing unique industry needs. For instance, healthcare-focused cloud analytics enable better patient outcomes through real-time data insights, while manufacturing solutions optimize supply chains and predictive maintenance. Vendors investing in industry-specific platforms can capitalize on client needs for specialized functions, driving incremental revenue streams while strengthening market presence and customer loyalty.
Investment in AI-Driven and Edge Analytics Technologies
Innovation in AI and edge computing opens new frontiers for cloud-based big data, especially in latency-sensitive applications. Investment in AI algorithms and the integration of edge devices allow organizations to process data closer to sources, reducing latency and bandwidth usage. This shift supports real-time analytics in autonomous vehicles, industrial IoT, and smart cities, enabling smarter decision-making and operational efficiencies. North American startups and tech giants are actively funding R&D, positioning the region as a global leader in next-generation big data analytics, which promises substantial commercial returns and market expansion opportunities.
Rising Venture Capital and Startup Ecosystem
The vibrant startup ecosystem and increased venture capital (VC) funding targeting cloud big data innovations further propel market growth. Key players are developing advanced analytics tools, SaaS platforms, and security solutions, fostering a competitive landscape rich with innovation. VC investments are predominantly flowing into AI-enhanced analytics, data governance, and specialized industry applications, which accelerates technology adoption. This influx of capital fuels the commercialization of novel solutions and supports startups to capture niche markets, creating a continuous pipeline of innovation that benefits the broader ecosystem and expanding market footprint.
Public-Private Partnerships and Digital Transformation Initiatives
Government-led initiatives focusing on digital transformation and smart city projects offer considerable growth prospects. Public-private partnerships (PPPs) facilitate deployment of cloud infrastructures, data-sharing platforms, and cyberinfrastructure projects, which directly support enterprise migration and analytics deployment. These programs often come with grants, subsidies, and policy incentives, reducing barriers for adoption. The focus on building resilient, scalable digital ecosystems in North America provides a strategic foundation for long-term market growth, fostering an environment conducive to innovation and commercial expansion in cloud-based big data services.
Challenges
Rapid Technological Obsolescence and Integration Complexity
The fast pace of technological evolution in cloud computing and big data analytics presents considerable challenges. Keeping up with new platform features, security protocols, and integration standards requires ongoing investments and workforce training. As new tools and frameworks emerge, legacy systems may become obsolete, complicating migration efforts and creating interoperability issues. Enterprises often face high switching costs and operational disruptions during upgrades, hampering swift adaptation and impeding overall market growth. Vendors must provide seamless integration and upgrade paths to mitigate this challenge and foster customer confidence.
Market Fragmentation and Vendor Lock-In Risks
The market's fragmentation, with numerous cloud service providers and offerings, leads to vendor lock-in risks and interoperability concerns. Organizations may become overly dependent on specific platforms, limiting flexibility and negotiating leverage. This fragmentation also complicates vendor comparisons and decision-making processes, slowing down adoption rates. Furthermore, customers worry about losing data control or facing high exit costs if they switch providers. Such concerns necessitate developing open standards and multi-cloud strategies, yet these solutions are still evolving, posing a significant challenge to rapid, broad-based adoption of cloud-based big data solutions across North America.
Industry Statistics & Key Business Metrics
The North American cloud-based big data market is witnessing rapid growth driven by increasing adoption across diverse industries such as healthcare, retail, finance, and manufacturing. The expanding use of cloud technologies, the proliferation of IoT devices, and data-driven decision-making are fueling this expansion. The market's trajectory indicates escalating revenue streams and technological innovation, with stakeholders emphasizing scalability, security, and compliance.
- 2026: The market size reached approximately USD 45.2 Billion, according to industry analysts.
- 2034: Projected to grow to around USD 112.8 Billion, demonstrating a substantial Compound Annual Growth Rate (CAGR) of approximately 12.4% from 2026 to 2034.
- 2023: North America dominated the cloud-based big data market, accounting for 52% of the global revenue share, per market research firms.
- 2025: The healthcare sector's adoption of cloud-based big data solutions increased by 35% compared to 2023, reflecting accelerated digital transformation efforts.
- 2024: Around 68% of North American enterprises reported implementing multi-cloud strategies, enhancing data management flexibility (Gartner).
- 2022: Big data-driven analytics contributed an estimated USD 2.5 Billion to North America's GDP, highlighting the economic impact (OECD).
- 2023: The number of active cloud data warehouses in North America surpassed 1500, a 20% increase from 2022 (IDC).
- 2024: Cybersecurity investments in cloud big data platforms increased by 25% year-over-year, emphasizing the significance of data protection (Forrester Research).
Market Segmentation
North America's Cloud-based Big Data Market is segmented based on Product, Component, Type, Technology, Platform, Application, End User, Industry Vertical, Source, Deployment, Distribution Channel, Mode, Connectivity, and Geography. This comprehensive segmentation facilitates targeted analysis and strategic planning for stakeholders across various sectors within the region. Each category reflects specific market characteristics, adoption patterns, and growth drivers essential for understanding the overall landscape.
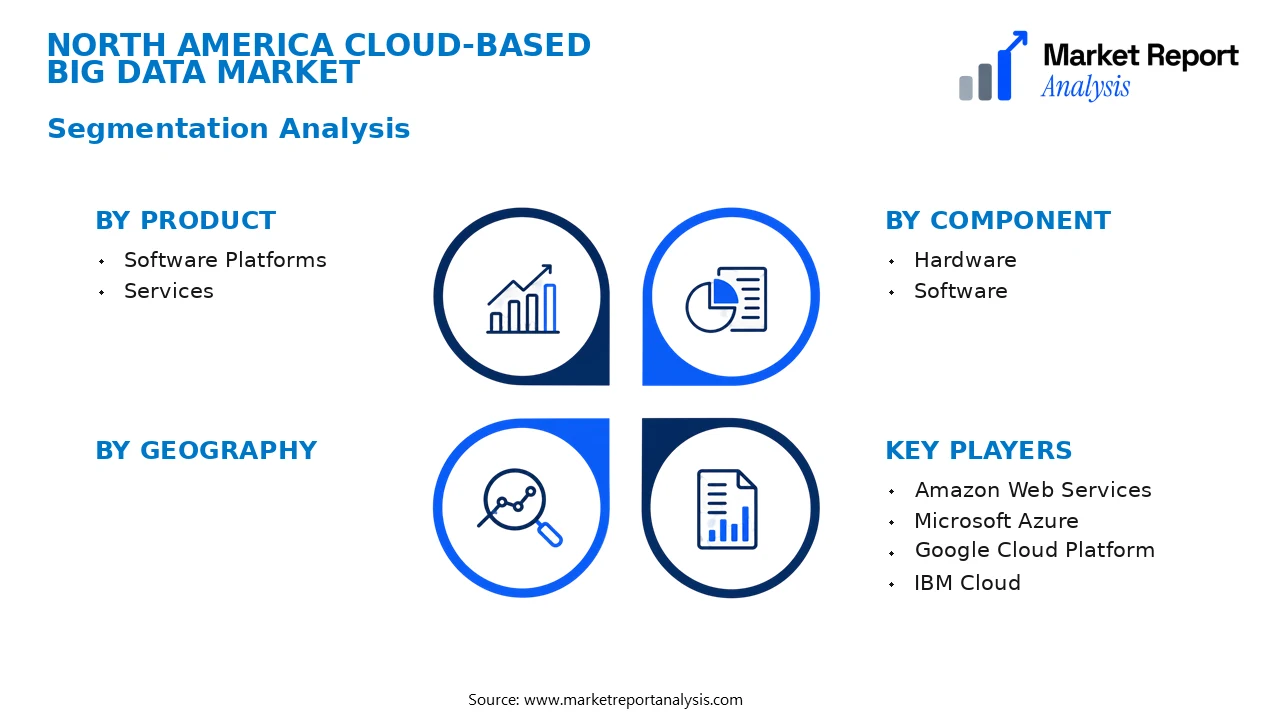
- Product
- Software Platforms: These encompass data analytics, data management, and data visualization tools that serve as the backbone of cloud-based big data solutions, facilitating data processing, analysis, and business intelligence.
- Services: Encompassing consulting, integration, and managed services, these support the deployment, customization, and maintenance of big data solutions in the cloud, accelerating adoption and operational efficiency.
- Component
- Hardware: Includes servers, storage devices, and networking equipment critical for infrastructure setup within cloud-based big data environments, supporting scalable and high-performance data processing.
- Software: The core computational tools facilitating data storage, processing, and analytics tasks, often integrated into cloud offerings for enhanced performance and ease of deployment.
- Type
- Public Cloud: These services are offered over the public internet, providing scalable, flexible, and cost-efficient big data solutions accessible to organizations without substantial infrastructure investments.
- Private Cloud: Dedicated cloud environments tailored for organizations with strict data security and compliance requirements, offering greater control over sensitive data and workloads.
- Hybrid Cloud: Combines public and private cloud elements, enabling organizations to optimize deployment based on workload sensitivity, cost, and performance criteria, thus enhancing flexibility.
- Technology
- Machine Learning & AI: Integrates advanced algorithms with big data platforms to derive predictive insights and automate decision-making processes, significantly boosting analytical capabilities in the cloud.
- Distributed Processing: Utilizes frameworks like Hadoop and Spark to manage large-scale data processing tasks efficiently, supporting real-time analytics and data-intensive applications.
- Platform
- Data Analytics Platforms: Offer comprehensive environments for data mining, statistical analysis, and visualization, empowering organizations to extract actionable insights from cloud-stored data.
- Data Management Platforms: Focus on organizing, storing, and maintaining vast data repositories, ensuring data integrity, security, and accessibility across multiple cloud environments.
- Application
- Customer Analytics: Utilized by enterprises to understand customer behaviors, preferences, and trends, thereby enabling personalized marketing and improved customer experience.
- Operational Analytics: Supports real-time monitoring of business processes, supply chains, and operational efficiencies to enhance productivity and decision-making.
- Fraud Detection & Compliance: Employs big data analytics to identify anomalies, ensure regulatory compliance, and mitigate risks in financial, healthcare, and government sectors.
- End User
- Large Enterprises: Major users due to their substantial data volumes and need for robust analytics, driving significant demand for cloud-based big data solutions.
- SMEs: Increasing adoption among small and medium-sized enterprises seeking cost-effective, scalable analytics solutions to improve competitiveness.
- Industry Vertical
- BFSI: Banking, financial services, and insurance sectors leverage big data for customer insights, risk management, and fraud detection, representing a key growth area.
- Healthcare: Utilizes big data for patient data management, predictive analytics, and personalized medicine, with rapid adoption driven by digital health initiatives.
- Retail & E-Commerce: Focuses on customer behavior analysis, inventory management, and targeted marketing, fueling demand for cloud-based big data solutions.
- Manufacturing: Deploys big data for predictive maintenance, supply chain optimization, and quality control, enhancing operational efficiencies.
- Source
- Structured Data: Data organized in defined formats such as databases and spreadsheets, forming the core data type processed within cloud platforms for analytics and reporting.
- Unstructured Data: Includes multimedia files, social media content, and sensor data, which require advanced processing capabilities to extract meaningful insights.
- Deployment
- Cloud-Service Providers: Major players offering hosted cloud environments with scalable infrastructure, essential for deploying big data solutions at scale.
- In-House Deployment: Private cloud or on-premise infrastructure used by organizations with high data security needs, supporting control over data and compliance.
- Distribution Channel
- Direct Sales: Vendors sell directly to large enterprises and government agencies, enabling tailored solutions and dedicated support services.
- Channel Partners: Resellers and integrators amplify market reach, providing local deployment, customization, and ongoing support for smaller enterprises.
- Mode
- On-Premise: Deployment within organizational infrastructure, primarily used by sectors with strict data governance, despite higher costs and maintenance requirements.
- Cloud-Based: Deployment over cloud platforms offering scalability, flexibility, and cost advantages, driving the majority of market growth in North America.
- Connectivity
- High-Speed Internet: Critical for seamless data transfer, real-time analytics, and remote collaborations across cloud platforms in North America.
- VPN & Dedicated Links: Ensure secure, reliable connectivity for sensitive data processing and compliance with industry regulations.
Competitive Intelligence
The North American cloud-based big data market is characterized by a highly competitive landscape with a mix of global tech giants and regional players vying for dominance. Market concentration remains moderate, with leading companies such as Amazon Web Services, Microsoft Azure, and Google Cloud holding significant market shares, while innovative startups are rapidly emerging. Major players focus on strategic partnerships with technology providers and enterprises to expand their service portfolios and enhance integration capabilities. Recent acquisitions have aimed to strengthen domain-specific offerings and data management solutions, fostering a more comprehensive ecosystem. Business strategies emphasize product innovation, integrating advanced analytics, AI, and machine learning capabilities to differentiate offerings in a crowded marketplace. Heavy R&D investments are directed toward developing scalable, secure, and cost-efficient cloud solutions that meet diverse industry needs, including healthcare, finance, and retail. This competitive dynamic encourages continuous innovation and service differentiation, fueling market growth and pushing providers to stay at the forefront through technological advancements and strategic collaborations.
Leading Company Profiles
The North American cloud-based big data market is characterized by a competitive landscape comprising several globally recognized tech giants and innovative startups. These companies are at the forefront of developing cutting-edge cloud and big data solutions, leveraging advanced analytics, artificial intelligence, and machine learning to serve diverse industries, including finance, healthcare, retail, and manufacturing. Their strategic initiatives focus on expanding cloud infrastructure, enhancing data management capabilities, and forming strategic alliances to solidify their market positions.
- Amazon Web Services
- Microsoft Azure
- Google Cloud Platform
- IBM Cloud
- SAS Institute
- Oracle Cloud
- Snowflake
- Databricks
- Cloudera
- Palantir Technologies
Amazon Web Services
Amazon Web Services (AWS) offers extensive cloud-based analytics and big data services, focusing on scalable storage, computing, and analytic solutions, with strategic initiatives aimed at expanding global infrastructure and integrating AI-driven analytics.
Microsoft Azure
Microsoft Azure provides integrated cloud solutions emphasizing enterprise data management, machine learning, and AI capabilities, with a strategic priority on hybrid cloud environments and strong partnership ecosystems to enhance big data analytics.
Google Cloud Platform
Google Cloud specializes in data analytics and AI-driven solutions, leveraging its expertise in machine learning to deliver real-time analytics, cloud storage, and data infrastructure for enterprises aiming to optimize big data operations.
IBM Cloud
IBM Cloud combines cloud infrastructure with advanced AI and analytics offerings, focusing on data security, hybrid cloud deployment, and strategic alliances with industry leaders to drive innovation in big data analytics solutions.
SAS Institute
SAS Institute offers comprehensive analytics software, emphasizing advanced statistical analysis, AI, and machine learning, with a strategic focus on delivering customizable analytics solutions to corporate and government clients.
Oracle Cloud
Oracle Cloud delivers integrated big data and analytics solutions, emphasizing database management, cloud infrastructure, and strategic acquisitions aimed at strengthening its cloud and big data portfolio for enterprise use.
Snowflake
Snowflake provides cloud data platform services with a focus on data sharing, scalability, and cross-cloud compatibility, enabling enterprises to efficiently manage and analyze large-scale datasets across multiple cloud environments.
Databricks
Databricks offers Unified Data Analytics platforms combining data engineering, data science, and analytics, emphasizing high-performance processing and AI integration to accelerate big data initiatives for enterprise clients.
Cloudera
Cloudera specializes in enterprise data cloud solutions, with a focus on hybrid cloud deployment, data security, and governance, supporting organizations in managing complex big data architectures efficiently.
Palantir Technologies
Palantir focuses on large-scale data integration and analytics, delivering tailored solutions for government and enterprise clients, emphasizing data security, visualization, and AI-powered insights.
Strategic Business Developments
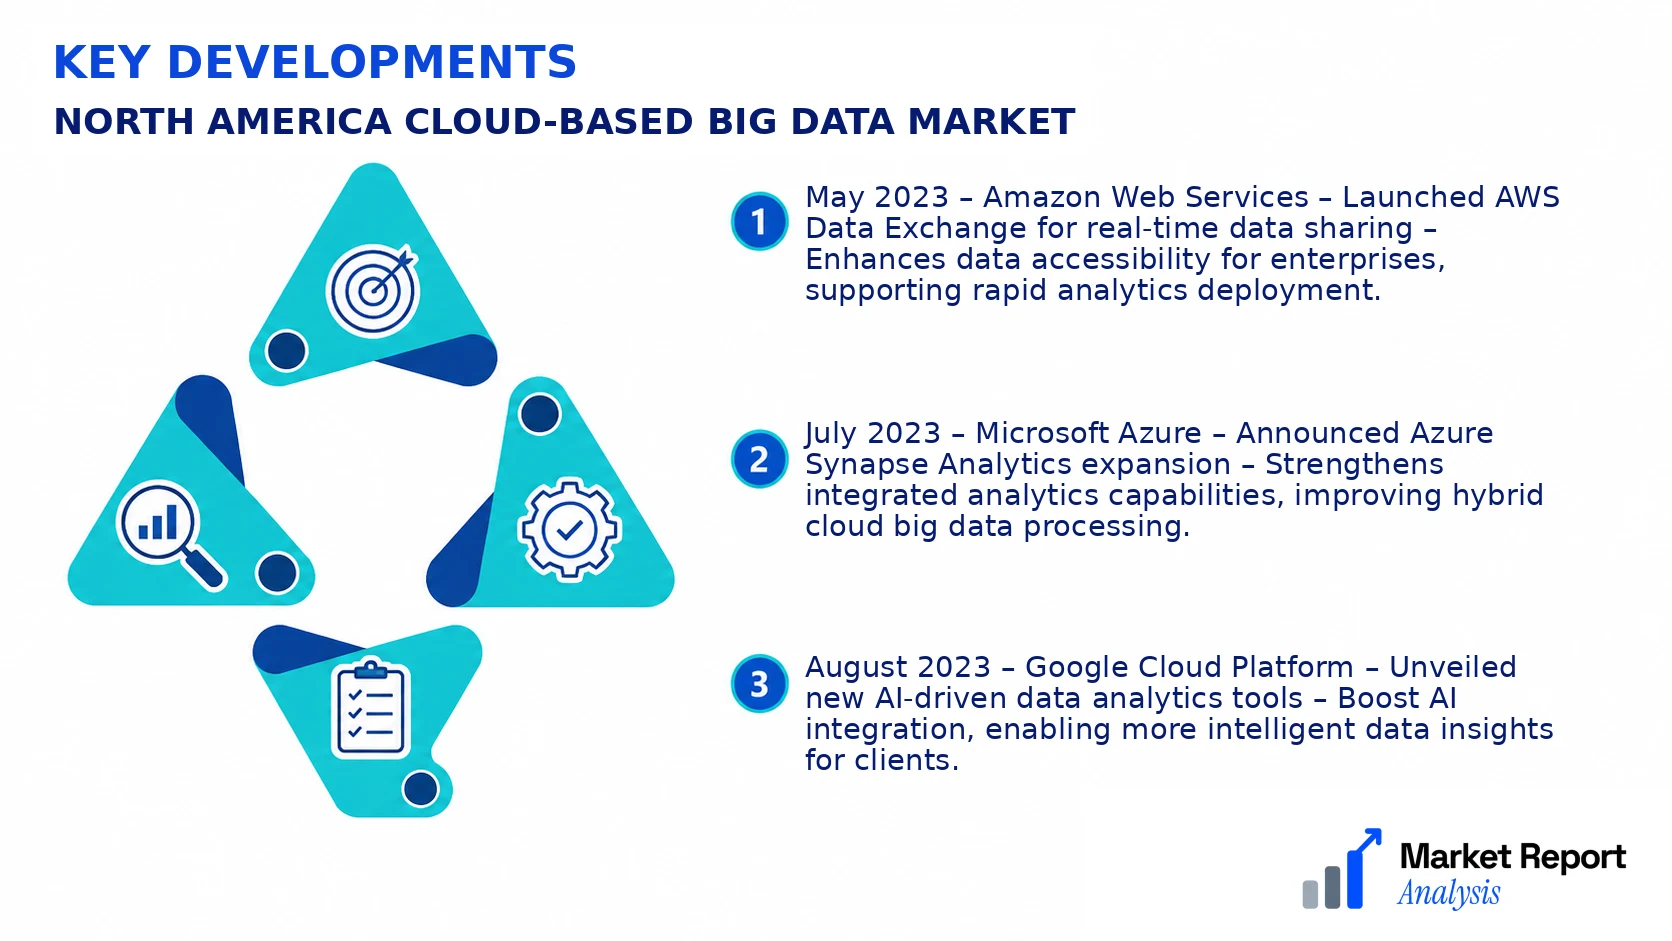
- May 2023 – Amazon Web Services – Launched AWS Data Exchange for real-time data sharing – Enhances data accessibility for enterprises, supporting rapid analytics deployment.
- July 2023 – Microsoft Azure – Announced Azure Synapse Analytics expansion – Strengthens integrated analytics capabilities, improving hybrid cloud big data processing.
- August 2023 – Google Cloud Platform – Unveiled new AI-driven data analytics tools – Boost AI integration, enabling more intelligent data insights for clients.
- June 2023 – Snowflake – Acquired Data Marketplace startup – Expands data sharing ecosystem, increasing interoperability across multiple cloud platforms.
- April 2023 – Palantir Technologies – Formed alliance with North American healthcare providers – Accelerates data integration and analytics in health sector, emphasizing secure data management.
Frequently Asked Questions
What is the North America Cloud-based Big Data Market?
The North America Cloud-based Big Data Market encompasses cloud solutions and services that facilitate big data analytics, storage, and processing within North America. It involves various industries leveraging cloud infrastructure to derive insights from vast data sets efficiently.
What is the current market size of North America Cloud-based Big Data Market?
As of 2026, the market size is valued at approximately USD 12.5 Billion, reflecting significant growth driven by increased adoption of cloud services across diverse sectors such as healthcare, retail, and finance within North America.
What factors are driving the North America Cloud-based Big Data Market?
Key drivers include the proliferation of big data, rising demand for advanced analytics, cost efficiency of cloud solutions, the expansion of IoT devices, and the need for real-time data processing, all contributing to accelerated adoption in North American enterprises.
Which region dominates the North America Cloud-based Big Data Market?
The United States leads the North American market, accounting for the majority share due to its advanced technological infrastructure, high cloud service adoption rates, and the presence of major cloud service providers supporting big data initiatives.
Which segment is expected to grow the fastest?
The SaaS (Software-as-a-Service) segment is projected to experience the fastest growth, driven by its flexibility, scalability, and cost-effectiveness, making it preferable for organizations aiming to implement scalable big data analytics solutions.
Who are the leading companies operating in the North America Cloud-based Big Data Market?
Major players include Amazon Web Services, Microsoft Azure, Google Cloud Platform, IBM Cloud, and Oracle Cloud, all actively expanding their cloud big data offerings and maintaining competitive advantages through innovation and strategic partnerships.
Analyst Perspective
The long-term outlook for the North America Cloud-based Big Data Market remains highly promising, driven by continuous technological innovation and growing enterprise reliance on data-driven decision-making. As organizations increasingly adopt advanced analytics and AI capabilities, demand for scalable, flexible cloud solutions will amplify, creating significant commercial opportunities across sectors such as healthcare, financial services, and retail. Technological evolution is expected to prioritize integrated data management tools, enhanced security protocols, and edge computing integration to support real-time insights. Investment priorities should focus on robust infrastructure, strategic partnerships, and cybersecurity enhancements to sustain growth amid rising competition. The market's competitive landscape is intensifying, with established cloud giants and agile startups vying for market share through innovation and aggressive pricing. Regional growth potential is concentrated in underserved areas, with U.S. and Canadian enterprises leading adoption, though burgeoning innovation hubs in Mexico could diversify the landscape. Strategic positioning will be crucial to capitalize on emerging opportunities and mitigate risks associated with evolving regulatory environments and technological disruptions.
