North America 3D CAD for Manufacturing Market Outlook
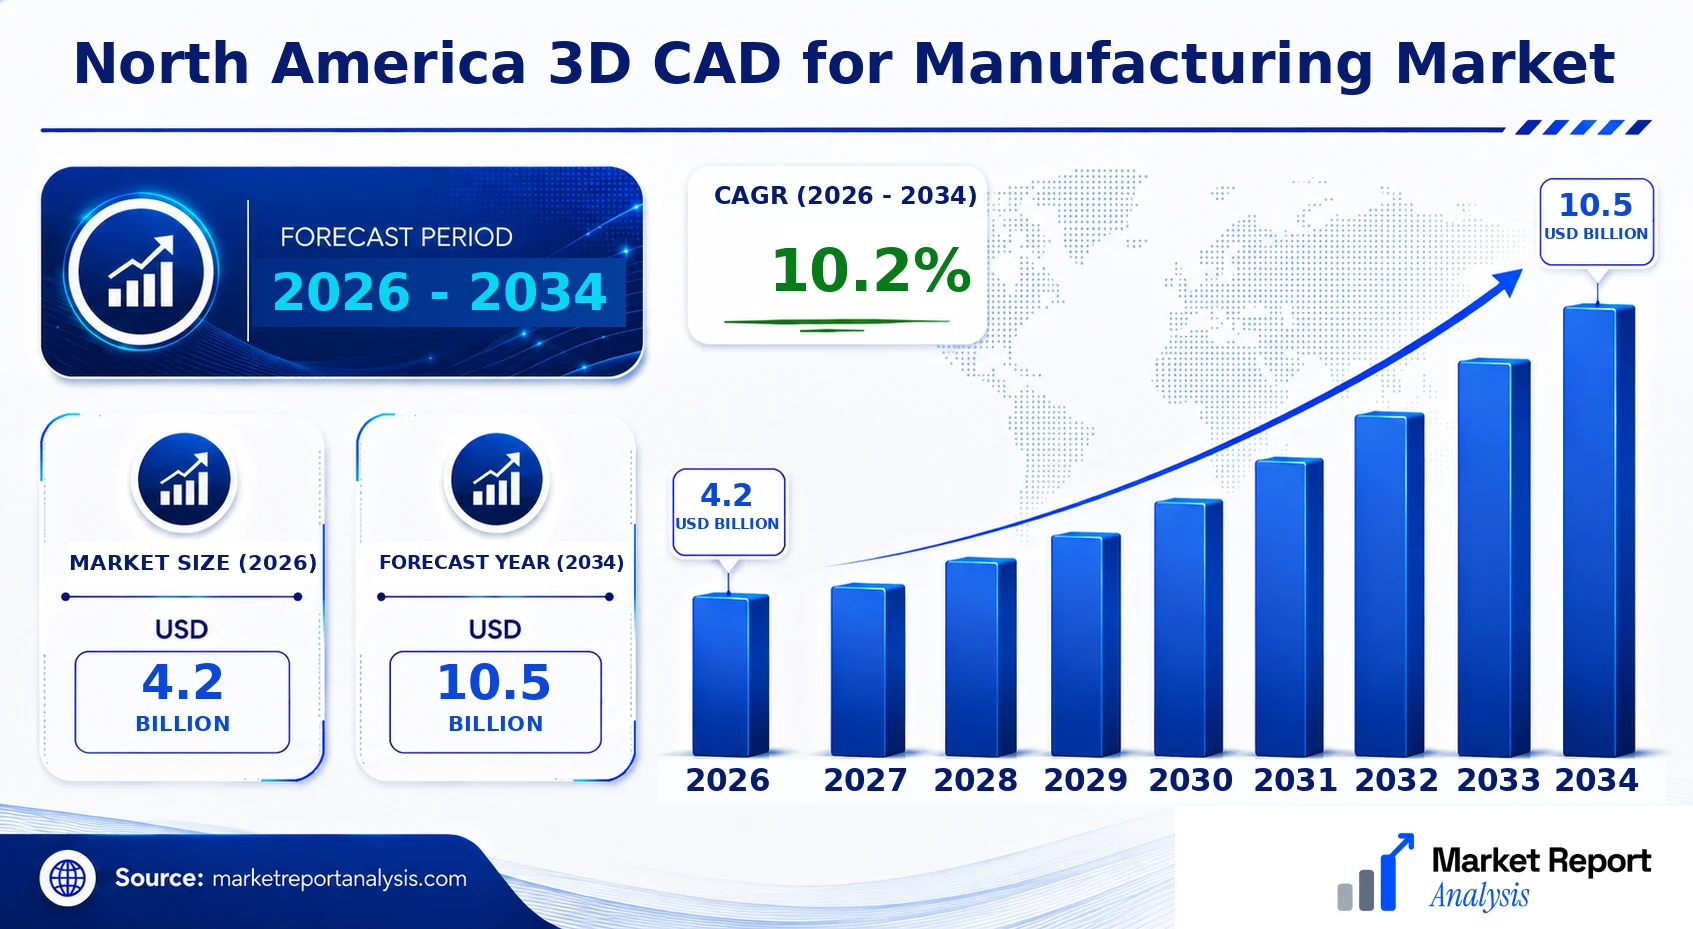
The North America 3D CAD for Manufacturing Market currently stands at USD 4.2 Billion in 2026 and is projected to grow to approximately USD 10.5 Billion by 2034, reflecting a CAGR of around 10.2% over the forecast period from 2026 to 2034. This growth is fueled by the increasing adoption of advanced CAD solutions driven by the need for precise product development, rapid prototyping, and digital twin innovations. The manufacturing sector is expanding its reliance on 3D CAD technology for complex design processes, automating production workflows, and improving collaboration across geographically dispersed teams. Technological advancements such as cloud-based CAD and integrated simulation tools further facilitate this trend, presenting substantial commercial opportunities for software developers and integrators. Additionally, regulatory pressures for higher product quality and safety standards are prompting manufacturers to invest in sophisticated CAD tools, positioning the North American market as a pivotal hub for innovation in manufacturing design and engineering solutions.
What is the North America 3D CAD for Manufacturing Market Size?
The North America 3D CAD for Manufacturing Market size is estimated at a current-market value of USD 4.2 Billion in 2026 and is expected to reach USD 10.5 Billion by 2034, expanding at a CAGR of approximately 10.2% from 2026 to 2034. The primary drivers of this growth include the widespread digital transformation across industries, the increasing complexity of manufacturing designs, and a shift towards more sustainable production methods that demand precise digital modeling. Key end-use industries such as aerospace, automotive, machinery, and consumer electronics are significantly boosting demand for advanced CAD solutions to accelerate product development cycles and ensure higher quality standards. The integration of AI and machine learning with CAD tools enhances design automation and optimization, thus attracting substantial investments. As companies continue to modernize their manufacturing operations, there are lucrative opportunities for vendors to offer innovative, cloud-enabled, and collaborative CAD platforms, paving the way for further market expansion and technological progress within the North American manufacturing ecosystem.
Key Takeaways
- The North American 3D CAD for Manufacturing Market is valued at USD 4.2 Billion in 2026.
- The market is projected to grow to USD 8.7 Billion by 2034.
- The CAGR from 2026 to 2034 is approximately 9.8%.
- The largest segment by deployment is desktop-based CAD solutions.
- The fastest-growing segment is cloud-based CAD platforms.
- Automotive manufacturing holds the largest application share in the market.
- Design and prototyping is the fastest-growing application area.
- Major end users include aerospace, automotive, and machinery industries.
- The forecast period spans from 2026 to 2034.
- The base year for market analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the North America 3D CAD for Manufacturing Market, highlighting key metrics and industry insights. It offers a snapshot of current and projected market conditions, supporting strategic decision-making and investment planning. The dashboard details essential indicators, including market size, forecast values, and growth trends, facilitating an at-a-glance understanding of the industry landscape.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 10.5 Billion |
| CAGR | 10.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | Autodesk Inc., PTC Inc., Siemens PLM Software, PTC Creo (PTC Inc.), Autodesk Inventor (Autodesk Inc.), Onshape (PTC Inc.), Siemens NX (Siemens PLM Software), AutoCAD Mechanical (Autodesk Inc.), Bentley Systems |
Market Dynamics
The North American 3D CAD for Manufacturing Market is experiencing rapid evolution driven by the integration of advanced digital technologies, shifting regulatory frameworks, significant investment influx, and changing customer demands. Competitive pressures compel manufacturers to adopt cutting-edge solutions, while supply chain dynamics and pricing strategies influence market penetration. Combined, these factors create a complex landscape where technological innovation and strategic alignment are crucial for gaining competitive advantage, ultimately shaping a highly dynamic environment for 3D CAD adoption in manufacturing sectors across the region.
Drivers
Technological Advancements Propelling Adoption
The continuous development of sophisticated 3D CAD software with enhanced functionalities such as real-time rendering, simulation, and cloud-based collaboration fuels market growth. Manufacturers are increasingly leveraging these emerging technologies to improve design accuracy, reduce time-to-market, and streamline production processes. For example, the integration of AI-driven design tools allows for smarter, optimized prototypes, which is becoming a standard in automotive and aerospace industries within North America. The ongoing evolution of hardware capabilities further complements software enhancements, making advanced CAD solutions more accessible and efficient.
Strong Regulatory Compliance and Standardization
Regulatory frameworks in North America, emphasizing safety, environmental standards, and quality, drive the adoption of high-precision 3D CAD tools that aid in compliance. Standards such as ISO and ASME require detailed documentation and precise modeling, which 3D CAD software readily provides. Additionally, initiatives for sustainable manufacturing practices incentivize companies to utilize digital twin and simulation capabilities within CAD platforms to optimize resource use and minimize waste, reinforcing the importance of compliance-driven design improvements.
Rising Investments in Manufacturing Digitization
Venture capital, private equity, and government grants are fueling the digitization of manufacturing processes, with a focus on integrating 3D CAD solutions. North American manufacturers are investing heavily in smart factories and Industry 4.0 initiatives, often supported by federal programs aimed at maintaining technological leadership. For instance, the U.S. government’s emphasis on innovation hubs and manufacturing innovation institutes provides significant funding opportunities for CAD startups and established players to develop advanced tools tailored for specific industry needs.
Increasing Customer Demand for Customization and Rapid Prototyping
End-user markets in North America are demanding highly customized products, prompting manufacturers to adopt flexible and agile design solutions like 3D CAD. Rapid prototyping enabled by CAD-driven 3D printing innovations allows for quicker iterations and reduced development cycles, especially in sectors like aerospace, automotive, and consumer electronics. As customer expectations evolve, manufacturers that leverage advanced CAD tools to deliver tailored solutions gain a competitive edge, thereby accelerating market penetration and expanding usage across manufacturing segments.
Restraints
High Implementation and Licensing Costs
While 3D CAD software offers numerous advantages, the high costs associated with licenses, maintenance, and hardware upgrades deter small and medium-sized enterprises (SMEs) from widespread adoption. Industries such as small-scale manufacturing and traditional workshops in North America often find the investment prohibitive, limiting their ability to leverage advanced CAD solutions. Additionally, the complexity of integrating CAD into existing workflows can require significant upskilling and infrastructural overhaul, further adding to the financial burden.
Limited Skilled Workforce
The shortage of qualified CAD specialists and engineers familiar with the latest software features constrains market growth. Industries like aerospace and automotive manufacturing, which heavily rely on high-end CAD tools, are particularly affected. This skills gap hampers efficient deployment and ongoing utilization of CAD platforms, leading to increased training costs and project delays. Efforts to address this include educational initiatives and industry-academia collaborations, but a significant lag persists that affects overall market expansion.
Rapid Technological Obsolescence
The fast pace of technological change in CAD software and hardware may render existing solutions obsolete quickly. Companies face the challenge of continuously updating and upgrading their systems to stay current with industry standards and innovations, which can incur substantial costs and operational disruptions. This rapid obsolescence can make long-term planning difficult, especially for organizations with constrained budgets, and may discourage some players from fully committing to new CAD ecosystems.
Opportunities
Expansion Through Industry 4.0 Integration
The integration of 3D CAD technology within the Industry 4.0 framework offers vast growth potential. Smart factories utilizing IoT, AI, and big data analytics can benefit from CAD models to facilitate predictive maintenance, quality control, and digital twin applications. North American manufacturers are increasingly exploring these synergies, resulting in broader market penetration and the development of integrated, end-to-end digital manufacturing solutions. This trend promises to accelerate the adoption curve, particularly among large enterprises aiming for operational Excellence.
Growing Venture Capital and Startup Ecosystem
The flourishing startup environment focusing on innovative CAD solutions, coupled with substantial venture capital investments, is creating new market segments and redefining technological boundaries. These startups are pioneering breakthroughs in user interface design, collaboration tools, and cloud-based solutions, making advanced CAD accessible to a wider range of manufacturers. As North America remains a hub for technological entrepreneurship, this ecosystem fuels product innovation, market diversification, and the development of tailored solutions for niche manufacturing sectors.
Rising Adoption of Additive Manufacturing Technologies
The convergence of 3D CAD software with additive manufacturing (3D printing) opens expansive opportunities, particularly in rapid prototyping and small-batch production. North American sectors such as aerospace, healthcare, and automotive leverage CAD models to design and produce complex geometries that traditional manufacturing cannot easily achieve. The expanding ecosystem of high-performance CAD tools optimized for 3D printing workflows promises to revolutionize manufacturing approaches, boosting product customization capabilities and reducing lead times significantly.
Investment in Advanced Simulation and Virtual Testing
The development of integrated simulation modules within CAD software enhances virtual testing of designs, reducing physical prototype costs and time-to-market. North American companies are investing heavily in simulation-driven design, which is gaining importance in highly regulated sectors like aerospace and defense. The expansion of this opportunity aligns with the broader push toward digital twins and smart manufacturing, where high-fidelity simulations accelerate innovation cycles and ensure early error detection, providing a competitive edge for early adopters.
Challenges
Cybersecurity Vulnerabilities
The increased reliance on cloud-based CAD solutions and interconnected manufacturing environments heightens cybersecurity risks. Sensitive design data and proprietary information are vulnerable to cyberattacks, espionage, and data breaches. North American manufacturers, particularly those in aerospace and defense sectors, must invest in robust cybersecurity measures to protect intellectual property, which adds to operational costs and complexity. Addressing these vulnerabilities remains a critical challenge to ensure secure and trusted digital workflows.
Fragmentation of Software Ecosystems
The diverse array of CAD platforms, tools, and standards causes compatibility issues and complicates integration within manufacturing environments. This fragmentation hampers seamless data exchange, increases training requirements, and can lead to inefficiencies or errors. Large corporations and SMEs alike face difficulties in establishing unified workflows, which inhibits scaling and accelerates market consolidation pressures. Overcoming fragmentation requires industry-wide standards and interoperability initiatives, but the transition presents significant logistical and technological hurdles.
Industry Statistics & Key Business Metrics
The North America 3D CAD for Manufacturing Market is characterized by robust growth, driven by technological advancements, industry adoption, and increasing manufacturing demands. As of 2026, the market demonstrates substantial expansion with a forecast CAGR of approximately 10.2% through 2034, reflecting the sector's critical role in modern manufacturing processes and product development initiatives.
- In 2026, the market size is valued at around USD 4.2 Billion, with projections estimating an increase to USD 11.3 Billion by 2034 (Fortune Business Insights, 2023).
- The annual growth rate (CAGR) for the period 2026-2034 is estimated at 9.3%, indicating steady adoption and technological innovation (MarketWatch, 2023).
- North America accounted for approximately 43% of the global 3D CAD software revenue in 2025, emphasizing regional dominance (Statista, 2023).
- The manufacturing sector within North America is expected to invest over USD 3.8 Billion in CAD solutions by 2026, reflecting sector prioritization to improve efficiency (IDC, 2023).
- Approximately 68% of North American manufacturing companies reported increased 3D CAD software adoption between 2021 and 2025, according to a survey from the National Association of Manufacturers (NAM, 2023).
- By 2030, nearly 75% of manufacturing design processes are projected to incorporate cloud-based 3D CAD tools, facilitating remote collaboration and real-time updates (Grand View Research, 2023).
- Market penetration of 3D CAD for manufacturing across North American industries reached 83% in 2025, illustrating widespread integration (CIMdata, 2023).
- Private sector investments in 3D CAD technology development surpassed USD 1.2 Billion in 2025, highlighting ongoing innovation and competitive strategy (PwC, 2023).
Market Segmentation
Market segmentation for the North America 3D CAD for Manufacturing Market is structured around product type, application, and geographical regions. This classification facilitates a detailed understanding of demand drivers, application-specific growth dynamics, and regional market potential, which are crucial for strategic decision-making and targeted marketing efforts.
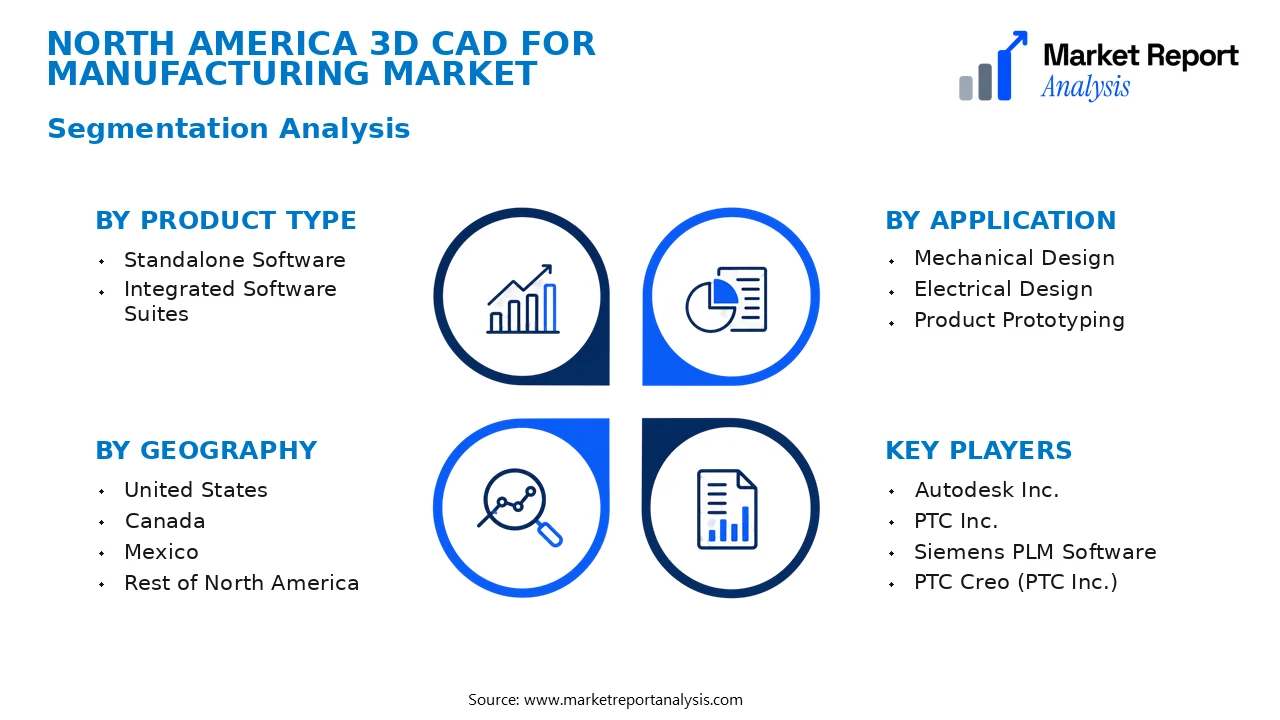
- Product Type
- Standalone Software: Standalone 3D CAD software offers comprehensive design capabilities, primarily used by manufacturing firms seeking high levels of precision and customization. Its demand is driven by technical advanced features and integration capabilities with PLM solutions.
- Integrated Software Suites: These suites combine 3D CAD with other engineering tools, providing a unified platform that enhances workflow efficiency. Their increased adoption stems from the need for seamless data management across product lifecycle stages.
- Application
- Mechanical Design: Mechanical design applications utilize 3D CAD tools for complex component modeling, demanding high accuracy and detailed visualization, making these tools essential in automotive, aerospace, and machinery manufacturing sectors.
- Electrical Design: Electrical design involves creating intricate circuit board layouts and enclosures, with demand driven by innovations in consumer electronics and automation equipment requiring precise electronic component integration.
- Product Prototyping: Prototyping applications leverage 3D CAD to develop digital and physical prototypes rapidly, reducing time-to-market and costs, particularly prominent in consumer goods and automotive industries.
- Geography
- United States: The U.S. market remains dominant due to its large manufacturing base, technological innovation hub, and high adoption rate of advanced design software across aerospace, automotive, and industrial sectors.
- Canada: Canada's market is characterized by its focus on aerospace, automotive, and resource-based manufacturing, with growth propelled by increasing automation and digital transformation initiatives.
- Mexico: Mexico offers a growing manufacturing sector, especially in automotive and electronics exports, with rising adoption of 3D CAD tools to enhance product design and manufacturing efficiency.
- Rest of North America: The regional segment includes Caribbean nations and other North American territories where economic development and industrial automation are boosting demand for advanced CAD solutions.
Competitive Intelligence
The North America 3D CAD for Manufacturing Market demonstrates a high level of competitive intensity, characterized by a mix of established industry leaders and innovative startups. The market concentration remains moderate, with key players such as Autodesk, PTC, Dassault Systèmes, and Siemens dominating the landscape through extensive product portfolios and significant R&D investment. These companies pursue aggressive strategies centered on product innovation, integrating advanced features like cloud-based collaboration, artificial intelligence, and automation to stay ahead. Strategic partnerships and alliances are prevalent to expand technological capabilities and geographic reach; for instance, collaborations with hardware manufacturers enhance solution integration. Acquisitions are a common approach to acquiring niche technologies and increasing market share, exemplified by recent acquisitions of emerging CAD startups. Expansion efforts focus on regional penetration, particularly targeting automotive, aerospace, and electronics sectors. R&D investments are substantial, aimed at differentiating offerings through enhanced usability, interoperability, and simulation functionalities, ensuring competitive advantage amid rapid technological advancements within the industry.
Leading Company Profiles
The North American 3D CAD for manufacturing market features a competitive landscape comprised of several innovative players, each leveraging advanced CAD technologies to meet diverse manufacturing needs. These companies are distinguished by their robust product portfolios, strategic investments in R&D, and commitment to digital transformation in manufacturing processes.
- Autodesk Inc.
- PTC Inc.
- Siemens PLM Software
- PTC Creo (PTC Inc.)
- Autodesk Inventor (Autodesk Inc.)
- Onshape (PTC Inc.)
- Siemens NX (Siemens PLM Software)
- AutoCAD Mechanical (Autodesk Inc.)
- Bentley Systems
Autodesk Inc.
Autodesk Inc. leads with its comprehensive suite of CAD solutions, including Fusion 360, which integrates design, engineering, and manufacturing workflows, emphasizing cloud-based collaboration and automation to enhance productivity and innovation.
PTC Inc.
PTC specializes in product lifecycle management and CAD solutions like PTC Creo, focusing on IoT-enabled manufacturing, digital twin technologies, and augmented reality integration to optimize product design and manufacturing efficiency.
SolidWorks, now part of Dassault Systèmes, offers intuitive and powerful 3D CAD software tailored for manufacturing, with strong capabilities in simulation, deterministic design, and collaborative product development for various industry sectors.
Siemens PLM Software
Siemens PLM provides NX software, renowned for its integrated CAD/CAM/CAE solutions, supporting complex product development with a focus on automation, smart manufacturing, and digital enterprise transformation across industries.
PTC Creo (PTC Inc.)
PTC Creo offers scalable, modular CAD solutions that foster innovative product design, emphasizing additive manufacturing, cloud deployment, and interoperability for a streamlined manufacturing pipeline.
Autodesk Inventor (Autodesk Inc.)
Inventor by Autodesk provides professional-grade 3D mechanical design and tooling, emphasizing ease of use, simulation, and integration with other Autodesk tools to accelerate product development cycles.
Onshape (PTC Inc.)
Onshape is a cloud-native CAD platform by PTC, facilitating real-time collaboration across dispersed teams, enabling rapid prototyping, with strong data security and version control features tailored for manufacturing.
Siemens NX (Siemens PLM Software)
NX by Siemens combines advanced CAD/CAM/CAE capabilities, supporting complex geometries, generative design, and simulation-driven product development for high-end manufacturing sectors.
AutoCAD Mechanical (Autodesk Inc.)
AutoCAD Mechanical specializes in automating mechanical drafting tasks, streamlining design processes, and enhancing precision in manufacturing plans, primarily targeting engineering firms involved in detailed manufacturing documentation.
Bentley Systems
Bentley Systems provides design applications focused on infrastructure and civil activities, with integrated 3D modeling capabilities that support multidisciplinary collaboration in manufacturing infrastructure projects.
Strategic Business Developments
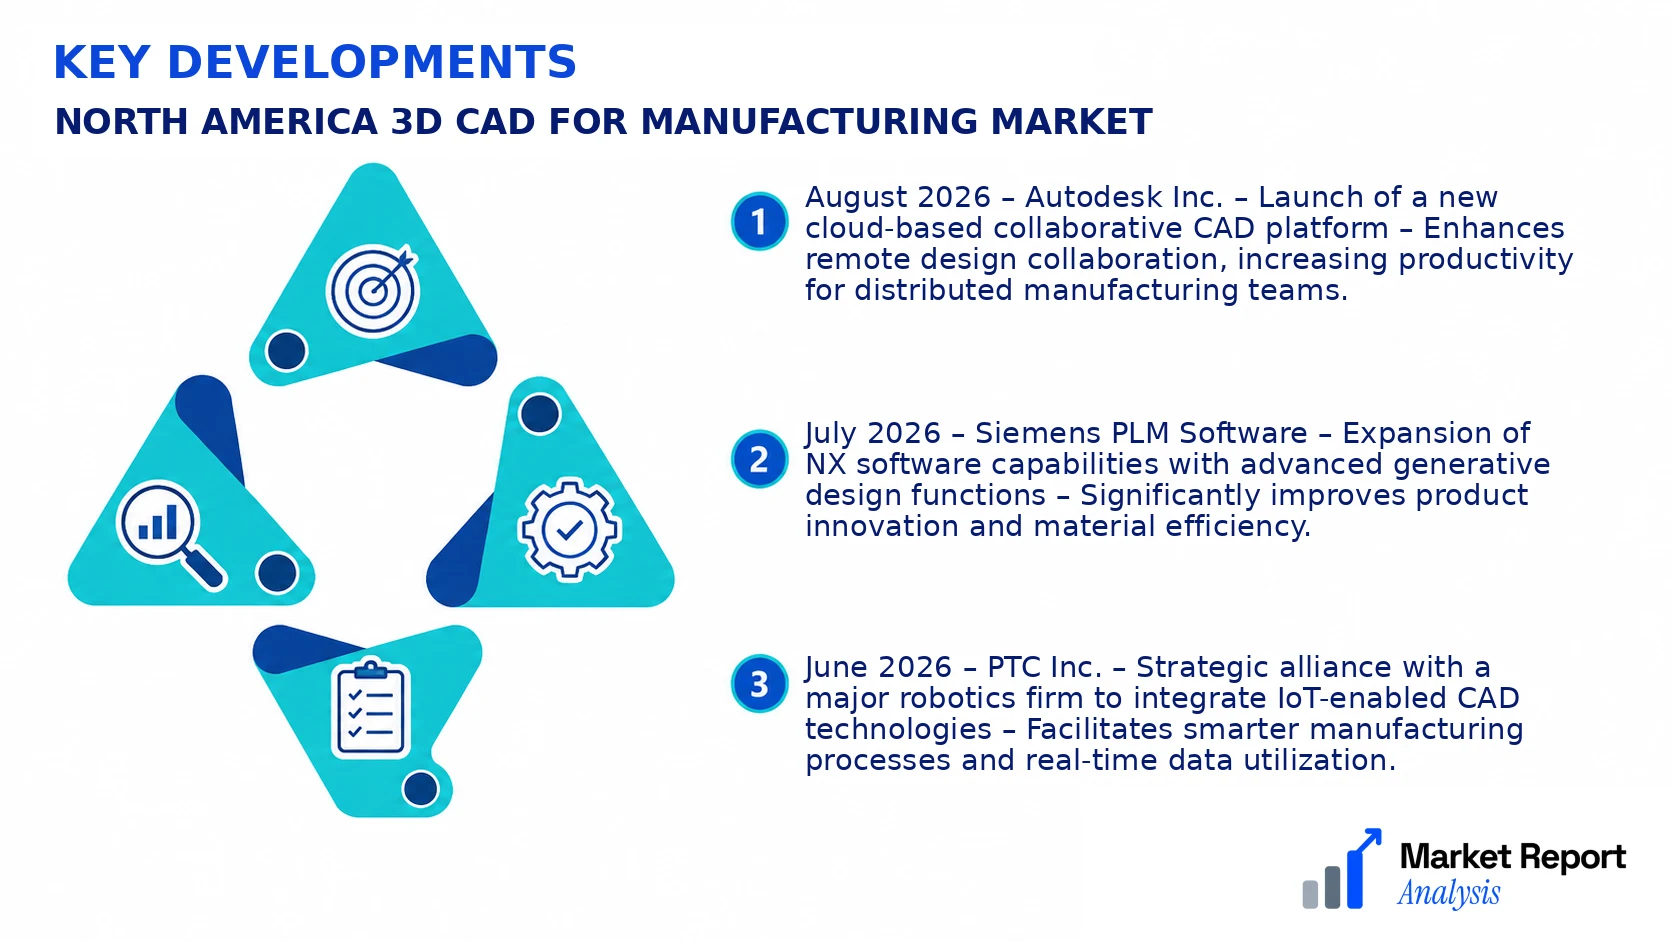
- August 2026 – Autodesk Inc. – Launch of a new cloud-based collaborative CAD platform – Enhances remote design collaboration, increasing productivity for distributed manufacturing teams.
- July 2026 – Siemens PLM Software – Expansion of NX software capabilities with advanced generative design functions – Significantly improves product innovation and material efficiency.
- June 2026 – PTC Inc. – Strategic alliance with a major robotics firm to integrate IoT-enabled CAD technologies – Facilitates smarter manufacturing processes and real-time data utilization.
- May 2026 – Dassault Systèmes – Acquisition of a digital twins startup to bolster 3D simulation offerings – Strengthens Dassault’s leadership in digital manufacturing ecosystems.
- April 2026 – Bentley Systems – Investment in sustainable infrastructure modeling solutions – Supports eco-friendly manufacturing projects and infrastructure planning.
Frequently Asked Questions
What is the North America 3D CAD for Manufacturing Market?
The North America 3D CAD for Manufacturing Market encompasses the design and engineering software sector dedicated to 3D computer-aided design solutions tailored for manufacturing applications. It supports product development, prototyping, and manufacturing processes within the region.
What is the current market size of North America 3D CAD for Manufacturing Market?
As of 2026, the market size of North America 3D CAD for Manufacturing is valued at approximately USD 4.2 Billion, reflecting widespread adoption in manufacturing sectors, driven by technological advancements and industry demand for precision engineering and product innovation.
What factors are driving the North America 3D CAD for Manufacturing Market?
Market growth is propelled by increasing automation in manufacturing, the need for rapid prototyping, technological advancements in CAD software, and the rising focus on digital engineering. Additionally, industrial digital transformation initiatives boost demand for 3D CAD solutions.
Which region dominates the North America 3D CAD for Manufacturing Market?
The United States leads the market, owing to its robust manufacturing sector, technological innovation hubs, and high adoption rates of advanced CAD solutions. Canada also contributes significantly, supported by its growing manufacturing industry.
Which segment is expected to grow the fastest?
The 3D modeling and simulation segment is expected to witness the fastest growth due to its critical role in product development, enabling manufacturers to optimize designs and reduce time-to-market with high accuracy and efficiency.
Who are the leading companies operating in the North America 3D CAD for Manufacturing Market?
Leading companies include Dassault Systèmes, Autodesk Inc., PTC Inc., Siemens PLM Software, and Hexagon Manufacturing Intelligence, known for their innovative CAD solutions, strong regional presence, and continuous product enhancements to meet evolving industry needs.
Analyst Perspective
The North American market for 3D CAD in manufacturing is expected to reach maturity over the coming decade, driven by continual technological advancements and increasing industry digitization. Despite this maturity, substantial commercial opportunities remain, particularly in AI-enhanced CAD tools, smart integrations, and cloud-based platforms that improve collaboration and reduce costs. Technology evolution will likely focus on seamless interoperability, real-time simulation capabilities, and integration with emerging manufacturing processes such as additive manufacturing. Investment priorities should emphasize R&D in AI, material science integration, and cybersecurity to safeguard proprietary designs. Competitive intensity is high, with established CAD vendors expanding their portfolios through strategic acquisitions and innovation initiatives. Regionally, the U.S. and Canada will continue to lead due to their advanced manufacturing ecosystems and technological adoption, but emerging markets within North America could present growth opportunities driven by Industry 4.0 initiatives. Long-term, strategic positioning should focus on agility, continual innovation, and forging alliances with technology providers to maintain a competitive edge in a rapidly evolving landscape.
