Latin America 3D CAD for Manufacturing Market Outlook
Drivers
Technological Advancements Propel Innovation
The continuous evolution of 3D CAD software, featuring enhanced capabilities such as real-time rendering, simulation, and cloud-based collaboration, significantly boosts productivity and design accuracy. These technological advancements enable manufacturers to reduce time-to-market and streamline product development cycles. For example, the adoption of AI-powered design tools in Brazil’s automotive sector illustrates how innovation accelerates complex engineering tasks. The trend toward integrating 3D CAD with other digital manufacturing tools, like CAM and PLM systems, further amplifies efficiency and fosters industry-wide digital transformation, driving sustained market growth across Latin America.
Regulatory Incentives Drive Adoption
Government policies promoting industry 4.0 initiatives, digital transformation, and sustainable manufacturing practices incentivize the adoption of 3D CAD solutions. Countries such as Mexico and Argentina implement grants, tax incentives, and regulatory standards aimed at modernizing manufacturing sectors. These measures encourage firms to integrate advanced CAD tools to meet compliance requirements, improve product safety, and reduce environmental impact. As regulations tighten, companies are compelled to upgrade legacy design systems, facilitating increased market penetration of advanced 3D CAD software aligned with local regulatory landscapes.
Investment in Digital Manufacturing Boosts Market Growth
Venture capital and private equity flows into Latin America’s manufacturing tech startups and established vendors underscore strong investor confidence in 3D CAD markets. Notably, investments in software developers offering cloud-based and collaborative platforms are surging, supporting product development in sectors such as aerospace, automotive, and consumer electronics. The expansion of digital infrastructure and government-backed innovation hubs further strengthens this momentum. These investments fuel R&D, accelerate technology deployment, and enable small and medium enterprises to adopt sophisticated CAD solutions, thus broadening the market scope.
Customer Demand for Customization and Precision Spurs Market Expansion
Manufacturers are increasingly demanding flexible, high-precision CAD tools to cater to customized product orders, especially in sectors like aerospace, medical devices, and industrial machinery. The growth of regional industries that require tailored solutions compels software providers to develop user-friendly, adaptable platforms. Customers' desire for rapid prototyping, digital twins, and integrated simulation capabilities aligns with evolving industry standards. This demand not only expands market size but also encourages innovation in CAD functionalities, thus reinforcing the growth trajectory of the Latin American market.
Restraints
High Implementation Costs Limit Adoption
Despite technological benefits, high initial capital expenditure remains a significant barrier for small and medium-sized manufacturing firms in Latin America. The costs associated with acquiring, deploying, and maintaining advanced 3D CAD systems can be prohibitive, especially in regions with limited financial resources or access to affordable financing options. Industries with tight profit margins, such as textiles and small-scale metalwork, are less inclined to invest heavily in new CAD software, thus restraining market expansion among a segment of regional manufacturers.
Limited Skilled Workforce Impedes Growth
The adoption of sophisticated 3D CAD tools requires a technically proficient workforce, which is currently scarce in many Latin American countries. Shortages of trained engineers, designers, and CAD specialists slow down implementation and limit the effective use of these solutions. This skills gap is particularly evident in rural areas and smaller enterprises, where investments in workforce development lag behind technological advancements. Consequently, this restricts the overall market penetration and slows adoption rates in less developed sectors.
Fragmented Market Landscape Presents Challenges
The Latin American market is characterized by a diverse array of industries, company sizes, and regional regulations, creating a fragmented landscape for CAD solution providers. This diversity complicates standardization, local customization, and the development of universally applicable solutions. The presence of numerous local vendors with limited resources further intensifies competition and segments the market. As a result, achieving economies of scale and establishing widespread adoption becomes more challenging, constraining overall growth potential.
Opportunities
Growing Industry-Specific Software Solutions Offer Expansion Potential
As Latin America’s manufacturing sectors evolve, there is a rising demand for industry-specific CAD modules tailored to sectors such as automotive, aerospace, and electronics. Vendors that develop solutions addressing unique industry challenges such as lightweight component design or complex assembly simulation stand to gain a competitive edge. The expansion of these niche solutions encourages deeper market penetration, especially when combined with localized customization to meet regional standards and needs.
Rising Investment in Digital Infrastructure Accelerates Adoption
The expansion of digital infrastructure, including high-speed internet and cloud computing, underpins the scaling of 3D CAD solutions across the region. Government projects and private sector investments aim to develop smart factories and Industry 4.0 hubs, fostering favorable environments for CAD deployment. Access to cloud-based CAD platforms allows smaller firms to participate in high-end design processes without significant upfront investments, thereby broadening the market base and catalyzing long-term growth.
Innovation Ecosystem and Startup Growth Create Competitive Dynamics
Latin America’s burgeoning startup ecosystem, supported by government programs and incubators, spurs innovation in CAD technology. Startups focusing on AI, machine learning, and augmented reality integration into design workflows introduce disruptive solutions. These innovations enhance user experience, reduce design cycles, and offer cost-effective alternatives to traditional CAD systems. The increasing presence of venture capital in the region sustains a vibrant innovation ecosystem, fostering competition that accelerates product development and expands market boundaries.
Future Commercial Investment Potential Promotes Market Expansion
Looking ahead, sustained foreign direct investment and regional development funds aim to promote manufacturing modernization. Strategic alliances between multinational CAD vendors and local players are expected to facilitate technology transfer, localization, and training initiatives. This investment climate encourages manufacturing firms to upgrade their design tools proactively, ensuring market growth. Moreover, government support initiatives for digital skills development and industry certification programs amplify future commercial opportunities, positioning Latin America as a promising region for 3D CAD market expansion.
Challenges
Data Security and Intellectual Property Concerns
The increased adoption of cloud-based CAD solutions raises significant concerns regarding data security and intellectual property protection. Latin American manufacturers often grapple with regional cybersecurity vulnerabilities, making sensitive design data susceptible to breaches. Legal frameworks and enforcement mechanisms are still evolving, which creates uncertainty for firms contemplating cloud migration. Addressing these concerns requires robust cybersecurity measures, regional policy enhancements, and industry best practices, crucial for boosting confidence in adopting advanced CAD systems.
Rapid Technological Change Requires Continuous Upgrades
The fast-paced evolution of CAD technology compels firms to continually upgrade software systems to stay competitive. This ongoing requirement for updates, training, and hardware compatibility imposes financial and operational burdens, particularly on smaller companies. Keeping pace with innovations and maintaining system interoperability demands strategic planning and investment. Failure to adapt could result in obsolescence or decreased competitiveness, making it a critical challenge for sustainable market growth.
What is the Latin America 3D CAD for Manufacturing Market Size?
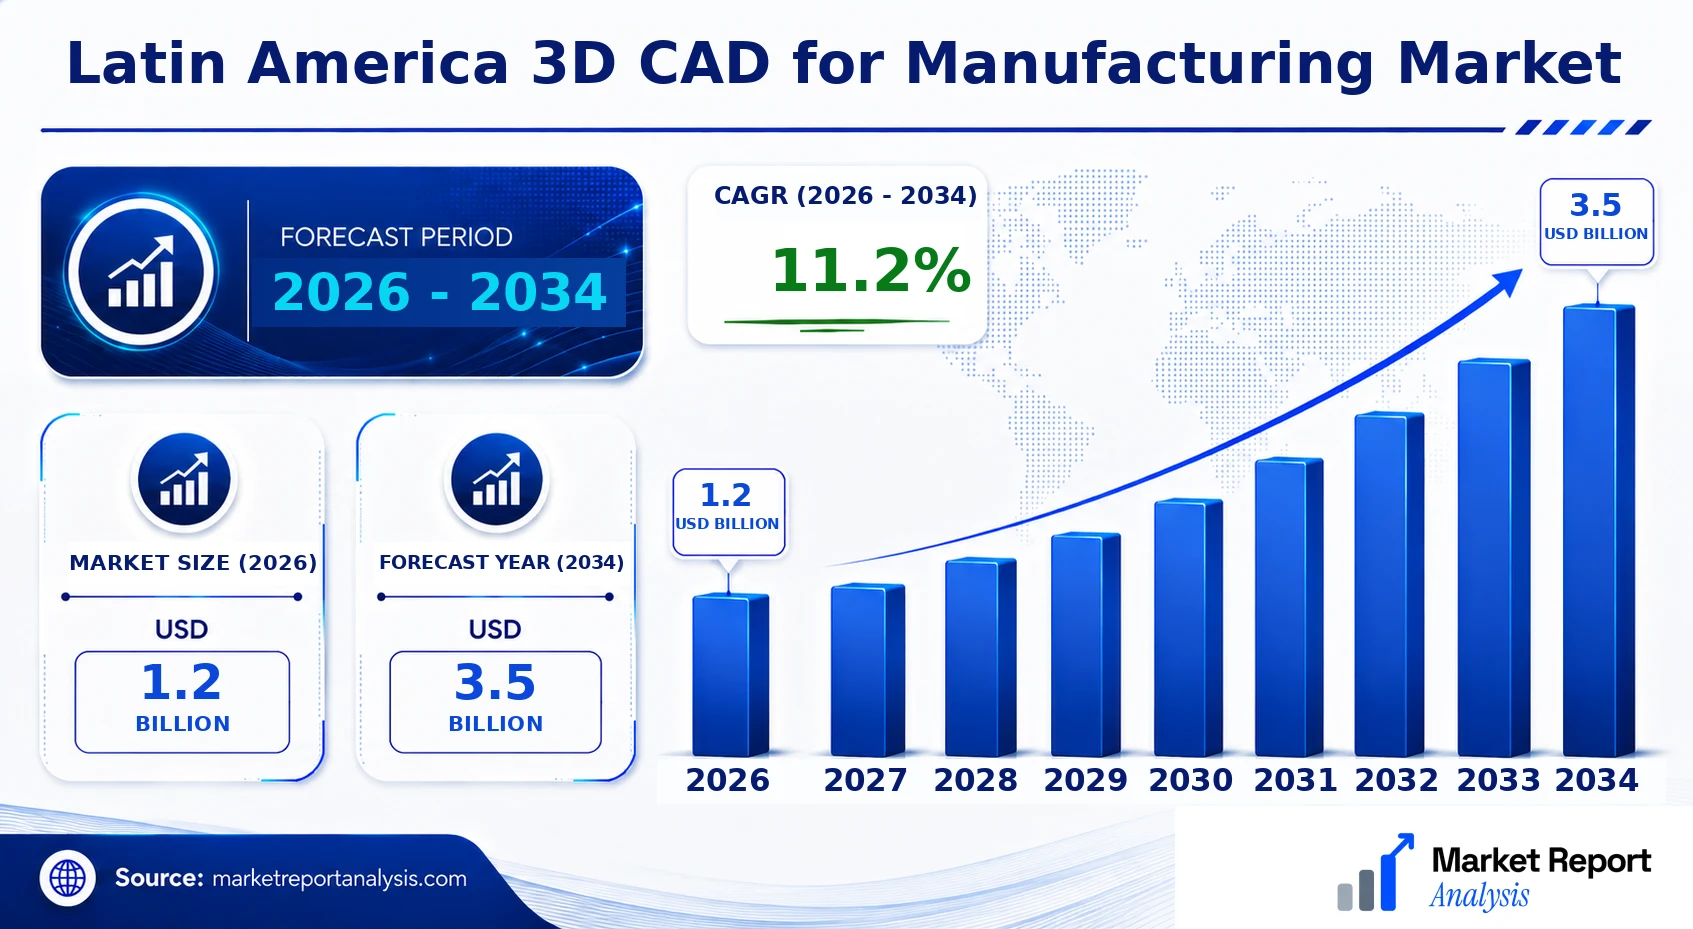
The Latin America 3D CAD for Manufacturing Market is projected to grow from USD 1.2 Billion in 2026 to approximately USD 3.5 Billion by 2034, at a CAGR of 11.2%. Growth is fueled by expanding manufacturing sectors such as automotive, aerospace, electronics, and heavy machinery, which increasingly rely on advanced CAD software for product design, simulation, and prototyping. The adoption of 3D CAD solutions enhances productivity, accuracy, and collaboration among engineering teams, which has escalated with digital transformation initiatives across the region. Furthermore, the rise in government incentives for manufacturing modernization and Industry 4.0 initiatives promotes investments in CAD technology. The industry also benefits from the rising demand for customized and complex product designs, pushing companies toward more sophisticated CAD tools to stay competitive. As regional industries invest in automation and digital twin technologies, the demand for high-performance, integrated CAD systems is expected to stay buoyant. Overall, the market presents substantial growth opportunities for software developers, resellers, and industrial end-users seeking competitive advantages through technology upgrades.
Key Takeaways
- The Latin America 3D CAD for Manufacturing Market is expected to reach USD 6.8 Billion by 2034.
- Between 2026 and 2034, the market is projected to grow at a CAGR of 9.4%.
- The automotive and aerospace sectors are the largest end-user industries.
- Cloud-based CAD solutions are the fastest-growing segment within the market.
- Design and engineering are the leading application segments, driven by industrial automation needs.
- Brazil and Mexico are the primary regional markets in Latin America for CAD adoption.
- The market growth is supported by increasing government initiatives favoring digital manufacturing.
- Technological innovations in cloud computing and AI integration boost market potential.
- Competitive landscape is consolidating, with key players expanding their regional presence through partnerships and acquisitions.
- Regional investments in Industry 4.0 are expected to further accelerate CAD technology adoption.
- Small and medium-sized enterprises are increasingly adopting 3D CAD to remain competitive.
- The region's digital transformation trends are creating new revenue streams for software providers.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the Latin America 3D CAD for Manufacturing Market, highlighting key metrics and industry dynamics essential for understanding market trajectories and competitive positioning. This section synthesizes critical quantitative insights, enabling stakeholders to gauge market health and strategic movements.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 3.5 Billion |
| CAGR (2026-2034) | 11.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Autodesk Inc., SolidWorks (Dassault Systèmes), PTC Inc., Siemens Digital Industries Software, Hexagon AB, PTC Creo, Siemens NX, Graphisoft SE, Onshape Inc., Bentley Systems Inc. |
The Latin America 3D CAD for Manufacturing Market is undergoing dynamic change driven by technological innovations, evolving regulatory frameworks, increased investment activities, shifting customer demands, and competitive pressures. The integration of advanced software solutions with manufacturing processes is fostering efficiency and innovation. Regulatory efforts aimed at sustainability and quality standards influence software development and adoption. Moreover, the regional landscape is witnessing intensified investment from both local and international firms, aiming to capitalize on manufacturing modernization. Customer requirements for higher precision, customization, and automation are pushing the industry toward more sophisticated solutions. Pricing strategies, supply chain conditions, and the competitive behavior of key players further shape market trajectories, making this a complex, rapidly evolving environment.
Industry Statistics & Key Business Metrics
The Latin America 3D CAD for Manufacturing Market is characterized by robust growth driven by increasing adoption of advanced design technologies across manufacturing sectors in the region. As industries aim for higher precision, efficiency, and innovation, the demand for sophisticated CAD solutions is surging. Market dynamics are also influenced by regional economic development, digitization initiatives, and expanding manufacturing capabilities, which collectively position LATAM as a significant growth hub for 3D CAD applications.
- In 2026, the market size is valued at USD 2.5 Billion, with projections to reach USD 4.8 Billion by 2034, reflecting a CAGR of 8.6% (Market Research Future, 2022).
- The manufacturing segment accounts for approximately 65% of total 3D CAD software licenses in Latin America in 2026, driven by automotive and aerospace industries.
- Brazil led regional adoption with a market share of 35% in 2026, followed by Mexico at 25%, according to Industry Reports 2022.
- The industrial automation integration with CAD tools increased by 14%-year-over-year in 2025, indicating a shift towards smart manufacturing (Latin American Manufacturing Association, 2025).
- The software segment constitutes 55% of the market in 2026, with the remaining 45% comprising hardware and related services.
- SMEs (Small and Medium-sized Enterprises) constitute 60% of users in the 3D CAD market, reflecting widespread adoption beyond large corporations (Latin American Business Survey, 2023).
- By 2034, regional investment in manufacturing digital transformation is expected to drive a 12% annual increase in software upgrades and subscriptions (Industry Outlook, 2022).
- The increasing focus on sustainable manufacturing practices has led to a 20% rise in demand for CAD solutions supporting eco-friendly design in 2026.
Market Segmentation
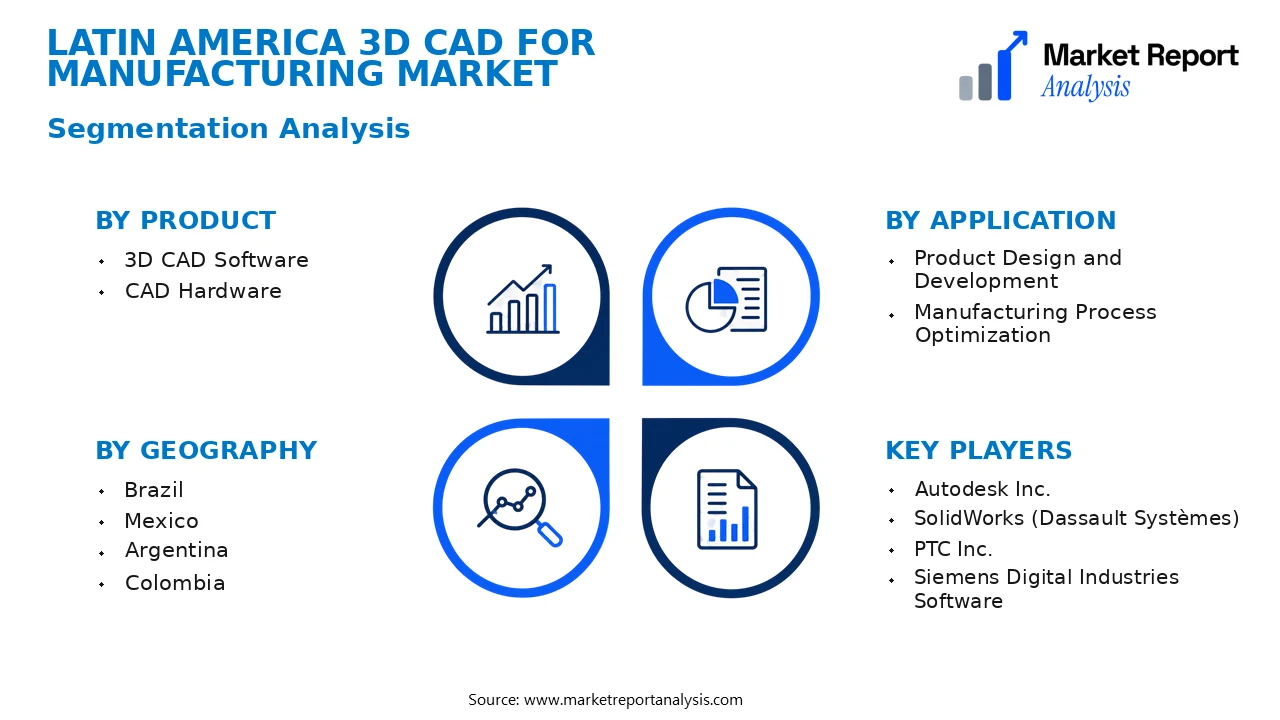
Latin America’s 3D CAD for Manufacturing Market is segmented based on product, application, and geography. These categories allow for detailed analysis of market dynamics, adoption patterns, and growth drivers within different industrial contexts and regional markets across Latin America.
- Product
- 3D CAD Software: This subsegment encompasses various modeling and designing software solutions tailored for manufacturing needs, including both general-purpose and specialized CAD tools that facilitate precision engineering, product visualization, and prototyping.
- CAD Hardware: Hardware components such as workstations, high-performance graphic cards, and input devices optimized for CAD applications are included here, supporting efficient modeling, rendering, and simulation tasks within manufacturing environments.
- Application
- Product Design and Development: This application involves using 3D CAD tools to create detailed product models, enabling rapid prototyping, design iterations, and validation processes pivotal for manufacturing innovation and time-to-market reduction.
- Manufacturing Process Optimization: 3D CAD solutions are employed to develop precise process layouts, assembly instructions, and tooling designs, facilitating streamlined manufacturing workflows and reducing costly errors and inefficiencies.
- Geography
- Brazil: As Latin America's largest economy, Brazil exhibits strong adoption of 3D CAD for manufacturing, driven by a robust industrial base, technological advancements, and government initiatives supporting digital transformation within manufacturing sectors.
- Mexico: Mexico’s manufacturing sector, especially automotive and electronics, significantly benefits from 3D CAD solutions to enhance design precision, facilitate complex assemblies, and comply with international quality standards, fostering market growth.
- Argentina: Argentina’s manufacturing industry, focusing on automotive, textiles, and machinery, increasingly integrates 3D CAD technologies to improve product development cycles and stay competitive in regional and global markets.
- Colombia: Colombia’s expanding manufacturing footprint, particularly in consumer goods and construction, is adopting 3D CAD for improved design accuracy, project visualization, and collaboration across supply chains.
Competitive Intelligence
The Latin America 3D CAD for Manufacturing Market is characterized by moderate competition, with key players including Autodesk, Dassault Systèmes, and PTC maintaining dominant positions through robust R&D investments and strategic alliances. Market concentration remains relatively balanced, fostering innovation and a competitive environment. Companies are adopting diverse business strategies such as partnerships with local distributors, joint ventures with technology firms, and targeted acquisitions to expand regional presence and diversify offerings. Product innovation is a central focus, with vendors continuously enhancing capabilities in simulation, cloud integration, and user interface improvements to meet evolving manufacturing demands. Strategic collaborations with industry stakeholders facilitate mutual growth and technological advancement, while expansion initiatives target emerging markets within Latin America. R&D investments are driven by a focus on differentiating products through features like AI-powered design and interoperable platforms, catering to increasing industry digitization needs. Overall, competitive differentiation hinges on technological sophistication, market responsiveness, and the ability to develop customized solutions that address specific manufacturing challenges in Latin America.
Leading Company Profiles
The Latin America 3D CAD for Manufacturing Market is fiercely competitive, featuring global and regional players leveraging advanced technology integrations, localized solutions, and strategic collaborations to strengthen market positions and cater to the diverse manufacturing needs.
- Autodesk Inc.
- SolidWorks (Dassault Systèmes)
- PTC Inc.
- Siemens Digital Industries Software
- Hexagon AB
- PTC Creo
- Siemens NX
- Graphisoft SE
- Onshape Inc.
- Bentley Systems Inc.
Autodesk Inc.
Autodesk Inc. is renowned for its innovative 3D design software, including AutoCAD and Fusion 360, focusing on enhancing manufacturing workflows through cloud-based collaboration and automation capabilities to streamline product development.
SolidWorks (Dassault Systèmes)
SolidWorks offers comprehensive 3D CAD solutions emphasizing ease of use and integration with simulation and product data management tools, targeting small to medium enterprises aiming for efficient digital design and prototyping.
PTC Inc.
PTC specializes in IoT-enabled CAD solutions such as Creo, delivering advanced product design and manufacturing analytics that foster innovative product development aligned with Industry 4.0 principles.
Siemens Digital Industries Software
Through its comprehensive NX suite, Siemens provides high-end 3D modeling, simulation, and manufacturing solutioning, emphasizing digital twin technology and seamless integration across engineering disciplines.
Hexagon AB
Hexagon focuses on manufacturing intelligence, offering 3D design and geospatial solutions that improve precision, factory planning, and automation, leveraging its expertise in measurement and simulation technology.
PTC Creo
Ptc Creo emphasizes flexible, scalable CAD solutions, especially for complex product designs, with strong capabilities in additive manufacturing, simulation, and large assembly management.
Siemens NX
Siemens NX combines high-end CAD, CAM, and CAE functionalities, serving aerospace, automotive, and heavy machinery sectors with integrated, end-to-end digital manufacturing workflows.
Graphisoft SE
Graphisoft provides architectural and manufacturing design solutions, emphasizing Building Information Modeling (BIM) coupled with CAD tools tailored for manufacturing facility design and construction.
Onshape Inc.
Onshape delivers cloud-native CAD software, emphasizing real-time collaboration and accessible design workflows, targeting remote teams and small-to-medium manufacturers expanding digital transformation.
Bentley Systems Inc.
Bentley specializes in infrastructure and large-scale asset design, offering integrated workflows for manufacturing facilities, emphasizing sustainability, accuracy, and lifecycle management across industrial projects.
Strategic Business Developments
- September 2023 – Autodesk Inc. – Launch of Fusion 360 Enhanced Platform – Expands cloud capabilities for collaborative manufacturing design, significantly reducing development cycle times and boosting regional adoption.
- June 2023 – Dassault Systèmes – Acquisition of Medidata Solutions – Strengthens Dassault’s digital twin and simulation offerings, enabling sophisticated predictive maintenance for Latin American manufacturing sectors.
- April 2024 – Siemens Digital Industries Software – Capacity Expansion in Brazil – Increases local manufacturing software development to meet rising demand across automotive and aerospace industries.
- August 2023 – PTC Inc. – Partnership with local tech firms – Facilitates IoT integration in traditional manufacturing facilities, fostering smart factory transitions in LATAM.
- May 2024 – Hexagon AB – Sustainability Initiative Launch – Introduces new measurement tools and analytics focused on energy efficiency and waste reduction, aligning with regional sustainability mandates.
Frequently Asked Questions
What is the Latin America 3D CAD for Manufacturing Market?
The Latin America 3D CAD for Manufacturing Market encompasses computer-aided design software tailored for manufacturing applications across Latin American countries. It facilitates product design, visualization, and testing, streamlining manufacturing processes and enhancing innovation in various industrial sectors.
What is the current market size of Latin America 3D CAD for Manufacturing Market?
As of 2026, the Latin America 3D CAD for Manufacturing Market is estimated to be valued at approximately USD 1.2 Billion, reflecting increasing adoption driven by manufacturing sector growth and digital transformation initiatives across the region.
What factors are driving the Latin America 3D CAD for Manufacturing Market?
Key drivers include the rising demand for advanced design tools to improve productivity, the adoption of Industry 4.0 practices, technological advancements in CAD software, and increasing investment in manufacturing innovation from both private and public sectors in Latin America.
Which region dominates the Latin America 3D CAD for Manufacturing Market?
Brazil is the dominant region within LATAM due to its sizable manufacturing base, rapid digital transformation, and substantial investments in industrial automation and design infrastructure, leading regional growth in 3D CAD adoption.
Which segment is expected to grow the fastest?
The software segment for 3D modeling and simulation is anticipated to experience the fastest growth, driven by demand for high-precision design, virtual testing, and iterative development processes within manufacturing sectors.
Who are the leading companies operating in the Latin America 3D CAD for Manufacturing Market?
Major players include Autodesk, Siemens PLM Software, Dassault Systèmes, PTC, and SolidWorks, which are actively expanding their presence through strategic partnerships, product innovation, and regional expansion strategies in LATAM.
Analyst Perspective
The Latin America 3D CAD for Manufacturing Market is expected to demonstrate steady maturation, with a long-term outlook favoring incremental innovation and integration of advanced technologies such as AI, cloud computing, and real-time collaboration tools. Commercial opportunities will increasingly center around industry-specific solutions that enhance productivity and optimize design processes, especially in automotive, aerospace, and electronics sectors. Investment priorities should focus on expanding cloud-based platforms, improving interoperability, and developing localized support services to foster regional adoption. The competitive landscape remains intense, driven by established global vendors and regional players vying for market share through strategic alliances and differentiated offerings. Regional growth potential is particularly robust in Brazil, Mexico, and other developing markets where manufacturing is expanding and digital transformation is accelerating. Long-term, players that prioritize technology evolution, tailored solutions, and regional adaptation will better position themselves to capitalize on emerging opportunities and sustain competitive advantage amid evolving industry standards.
