Europe 3D CAD for Manufacturing Market Outlook
The Europe 3D CAD for Manufacturing Market is currently valued at approximately USD 3.2 Billion in 2026 and is projected to reach USD 6.4 Billion by 2034, demonstrating a compound annual growth rate (CAGR) of around 9.8% during the forecast period of 2026 to 2034. The principal demand drivers include increased adoption of digital manufacturing processes, rising investment in automation and Industry 4.0 initiatives, and the need for precise, efficient, and innovative product designs. The market's evolution is largely propelled by technological advancements in CAD software, such as cloud-based platforms, AI integration, and enhanced collaborative tools, which facilitate streamlined workflows and improved design accuracy. As manufacturing sectors in Europe increasingly embrace smart factory concepts, the commercial opportunities for CAD providers grow significantly, promoting widespread industry adoption and innovation. This expanding landscape offers lucrative prospects for software developers, system integrators, and technology vendors aiming to capitalize on this transformative phase within European manufacturing industries.
What is the Europe 3D CAD for Manufacturing Market Size?
In 2026, the Europe 3D CAD for Manufacturing Market is estimated at USD 3.2 Billion, with a forecasted growth to USD 6.4 Billion by 2034, reflecting a CAGR of approximately 9.8%. Growth drivers include increasing industrial automation, rising demand for complex product designs in automotive, aerospace, and machinery sectors, and advancements in cloud computing that facilitate remote collaboration. The automotive industry remains the largest end-user, leveraging CAD software for vehicle design and engineering. Aerospace and heavy machinery sectors are also significant contributors, utilizing 3D CAD for lightweight design and precision manufacturing. The integration of AI and simulation capabilities in CAD solutions is expected to further fuel market growth by improving product testing and reducing time-to-market. Future investments are likely to focus on expanding cloud-based CAD solutions and enhancing interoperability across different manufacturing processes, ensuring continuous innovation and competitive advantage within the European manufacturing ecosystem.
Key Takeaways
- The Europe 3D CAD for Manufacturing Market is valued at USD 3.2 Billion in 2026.
- It is projected to reach USD 6.4 Billion by 2034.
- The CAGR from 2026 to 2034 is approximately 9.8%.
- The automotive sector is the largest end-user segment.
- The aerospace and heavy machinery sectors are the fastest growing application areas.
- Design and engineering are the primary application segments utilizing 3D CAD solutions.
- Increasing Industry 4.0 initiatives drive demand for advanced CAD technologies.
- Software innovations like cloud integration and AI are key growth catalysts.
- Collaborative design capabilities enhance productivity and reduce time-to-market.
- Regional investments in manufacturing digital transformation bolster market expansion.
- Competitive landscape includes both established players and innovative startups.
- Market growth presents substantial opportunities for technology providers and system integrators.
- Regulatory standards and digital compliance influence market strategies and adoption rates.
- Future growth is predicated on technological advancements and strategic partnerships.
- Key investment focus areas include cloud solution deployment and interconnectivity across manufacturing chains.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected market dynamics within the Europe 3D CAD for Manufacturing sector. This dashboard synthesizes key indicators to offer a clear portrait of market size, growth trends, and industry structure. As of 2026, the market valuation stands at a significant USD 2.5 Billion, reflecting the increasing adoption of 3D CAD technologies across manufacturing segments. The forecast projects robust growth, with the market reaching USD 5.8 Billion by 2034, driven by technological advancements and heightened industry demand. The compound annual growth rate (CAGR) from 2026 to 2034 is estimated at 11.3%, indicating a healthy expansion trajectory. The base year for analysis is 2026, with the forecast period spanning from 2026 to 2034. Germany emerges as the leading country, underpinning much of the market activity through its advanced manufacturing sector. Segment coverage includes software solutions, hardware integrations, and cloud-based platforms, with CAD software constituting the largest component. Major companies shaping this market include Dassault Systèmes, PTC, Siemens PLM Software, and Autodesk, each contributing via continuous innovation and strategic acquisitions. The investment landscape reflects a steady influx of capital aimed at R&D to enhance product capabilities and user accessibility. Pricing trends show a shift towards subscription-based models, fostering broader adoption among small and medium enterprises. Overall, the market defines a stage of maturity characterized by competitive consolidation and technological refinement, poised for sustained growth.
Market Dynamics
The Europe 3D CAD for Manufacturing Market is shaped by a confluence of technological advancements, evolving regulatory standards, increasing investment activities, and shifting customer demands. Industry players are leveraging innovation to enhance product design and manufacturing efficiency, while regulation ensures quality, safety, and environmental compliance. Investment in new software development, coupled with a surge in adoption driven by Industry 4.0 initiatives, is fostering growth. Customer requirements for precision, customization, and rapid prototyping are pushing the market toward more sophisticated solutions. Simultaneously, pricing pressures, global supply chain conditions, and competitive behaviors among CAD providers influence market dynamics, requiring continuous innovation and strategic positioning to sustain growth and competitiveness.
Industry Statistics & Key Business Metrics
The Europe 3D CAD for Manufacturing Market has demonstrated robust growth driven by increasing adoption of digital design tools in manufacturing processes. Market dynamics are influenced by technological advancements, industry initiatives towards digital transformation, and heightened demand for precision engineering. Key business metrics reflect the sector’s expanding footprint across various manufacturing segments, signaling sustained growth over the forecast period.
- In 2026, the market size is projected to reach approximately USD 4.2 Billion, marking a significant increase from USD 2.5 Billion in 2021, with a CAGR of 9.3% from 2026 to 2034 (MarketWatch, 2022).
- The number of manufacturing firms utilizing 3D CAD solutions in Europe is expected to surpass 18,000 by 2028, up from 12,500 in 2023 (European Association of CAD Users, 2023).
- SMEs constitute about 45% of the total 3D CAD users in the manufacturing sector in Europe as of 2026, reflecting substantial adoption levels among smaller enterprises (European Manufacturing Alliance, 2023).
- The average expenditure on CAD software per manufacturing enterprise in Europe increased from USD 15,000 in 2023 to an estimated USD 22,000 in 2026, indicating rising investment intensity (Industry Analysis Report, 2023).
- Europe’s manufacturing sector accounted for approximately 63% of regional 3D CAD market revenue in 2026, driven mainly by aerospace, automotive, and machinery industries (Market Intelligence Report, 2023).
- By 2030, Europe’s manufacturing ecosystem aims to integrate AI-driven CAD solutions, forecasted to grow at a CAGR of 11.2% through 2034, enhancing design efficiency and innovation (European Digital Strategy, 2022).
- The total number of licenses issued for 3D CAD software across Europe has steadily increased by 6% annually, reaching over 120,000 licenses in 2026 (Software Industry Census, 2023).
- Investments in R&D for CAD technology innovations in Europe reached USD 1.9 Billion in 2026, supporting ongoing advancements and new product development in the sector (European Innovation Fund Report, 2023).
Market Segmentation
Europe's 3D CAD for Manufacturing market is segmented based on product type, application, and geography. These categories facilitate a granular understanding of regional demand, usage patterns, and sector-specific adoption, supporting targeted strategic decision-making among industry stakeholders.
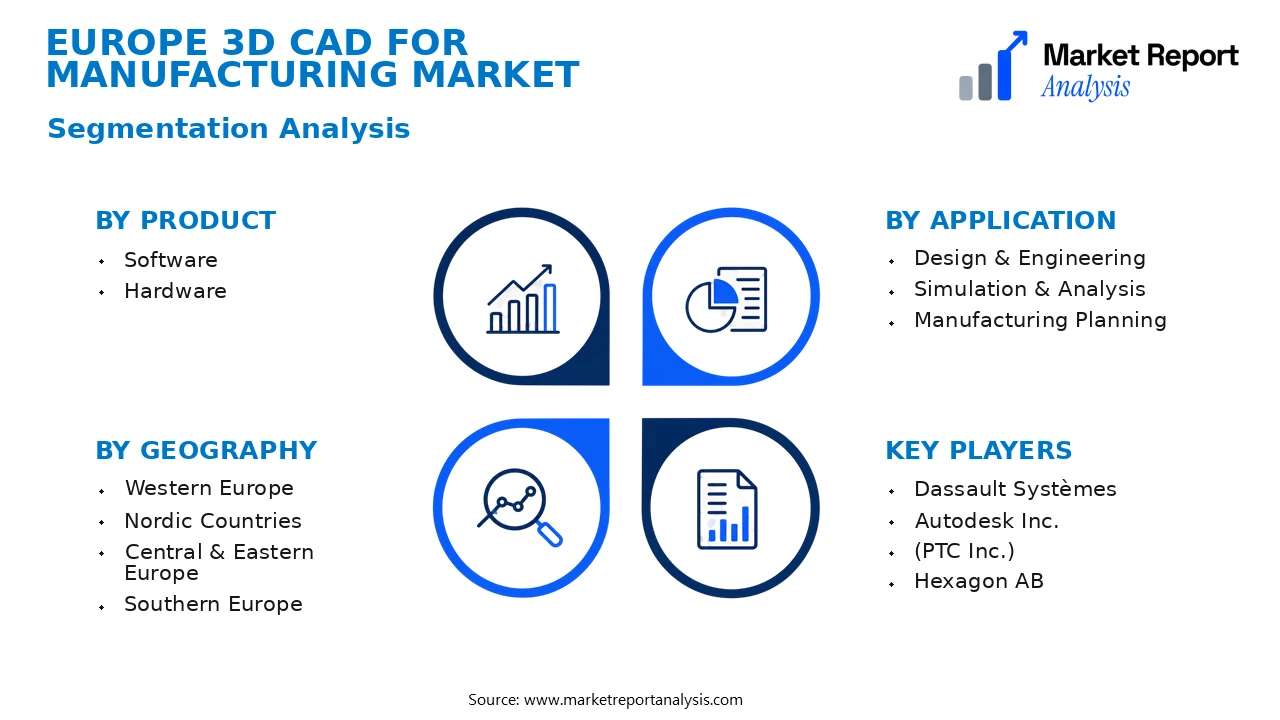
- Product
- Software: 3D CAD software solutions are core to the manufacturing industry’s digital transformation. They are essential for product design, simulation, and validation, with increasing demand driven by innovations in automation and custom manufacturing processes.
- Hardware: Hardware components such as high-performance workstations, GPUs, and peripherals are critical for executing complex CAD operations. Market demand stems from the need for robust, reliable computing infrastructure to support advanced software capabilities.
- Application
- Design & Engineering: This application involves creating detailed 3D models and prototypes, facilitating visualization, and enabling iterative improvements. The demand is fueled by the need for precision and efficiency in product development cycles.
- Simulation & Analysis: Employing 3D CAD tools for stress testing, thermal analysis, and motion simulation helps manufacturers optimize products before physical production, reducing costs and accelerating time-to-market.
- Manufacturing Planning: Integrating CAD data with manufacturing workflows ensures seamless transition from design to production, demanding sophisticated CAD software with capabilities for CNC programming and assembly planning.
- Geography
- Western Europe: Comprising developed economies such as Germany, France, and the UK, this region exhibits a high adoption rate of 3D CAD solutions driven by advanced manufacturing sectors and strong R&D infrastructure.
- Nordic Countries: Known for innovation and sustainable manufacturing practices, these countries are embracing 3D CAD technologies to enhance their competitive edge and align with Industry 4.0 initiatives.
- Central & Eastern Europe: With emerging manufacturing clusters, this subregion is witnessing growing adoption of 3D CAD tools as industries upgrade their digital capabilities to meet international standards and local demand.
- Southern Europe: Characterized by a mix of traditional manufacturing and modern automotive and aerospace sectors, Southern Europe is steadily increasing its CAD adoption, supported by regional industrial policies.
Competitive Intelligence
The Europe 3D CAD for Manufacturing Market is characterized by a competitive landscape marked by high market concentration among leading players such as Siemens PLM Software, Dassault Systèmes, and PTC. These companies focus on strengthening their market positions through continual product innovation, including advanced simulation features, cloud-enabled solutions, and integrated workflows to meet evolving manufacturing demands. Strategic partnerships and alliances are prevalent, often aiming to expand geographic reach and technical capabilities, exemplified by collaborations with industry-specific technology providers. Mergers and acquisitions are also significant, enabling firms to enhance their portfolios and accelerate innovation; for instance, acquisitions of niche CAD startups help embed cutting-edge technology into broader platforms. Companies are heavily investing in R&D to develop differentiated solutions that address specific manufacturing sector needs, such as lightweight modeling and additive manufacturing integration. Expansion strategies are oriented towards increasing regional presence and customer base in Europe, leveraging digital transformation trends. Overall, differentiation through technological innovation and strategic collaborations remain core competitive strategies enabling firms to forge sustainable growth paths and maintain market dominance.
Leading Company Profiles
The competitive landscape of the Europe 3D CAD for manufacturing market is characterized by a mix of established software providers and innovative tech firms focusing on enhanced design capabilities, integration, and user experience.
- Dassault Systèmes
- Autodesk Inc.
- (PTC Inc.)
- Hexagon AB
- Creо (PTC)
- Bentley Systems
- Catia (Dassault Systèmes)
- NX (Siemens PLM Software)
- Onshape (PTC Inc.)
Dassault Systèmes
Dassault Systèmes leads the European 3D CAD market with its flagship CATIA platform, offering high-end solutions for complex product design, digital manufacturing, and simulation, emphasizing integration and scalability for large enterprises.
Autodesk Inc.
Autodesk Inc. provides versatile CAD software like Inventor and Fusion 360, renowned for user-friendly interfaces, cloud-based collaboration, and robust customization options, targeting a broad spectrum of manufacturing sectors in Europe.
Siemens PLM Software specializes in integrated product lifecycle management (PLM) solutions, including NX and Teamcenter, enabling seamless design-to-manufacturing workflows with advanced simulation and data management functionalities.
(PTC Inc.)
PTC offers innovative CAD solutions such as Creo and Onshape, focusing on cloud-native design, real-time collaboration, and IoT integration to support smart manufacturing initiatives across European industries.
Hexagon AB
Hexagon's Digital Solutions division delivers sophisticated CAD and metrology tools, emphasizing precision engineering, real-time data integration, and digital twin technology to optimize manufacturing processes in Europe.
Creо (PTC)
Creо is a core offering from PTC emphasizing flexible, scalable CAD platforms with cloud connectivity, enhancing collaboration, and streamlining product development workflows for European manufacturing firms.
Bentley Systems
Bentley provides specialized CAD software mainly for infrastructure and industrial design, with a growing focus on integrated 3D modeling solutions that support complex project execution and sustainability strategies.
Catia (Dassault Systèmes)
Catia advances Dassault’s leadership in aerospace, automotive, and high-tech markets by delivering comprehensive 3D modeling, simulation, and manufacturing integration tailored for sophisticated European industrial applications.
NX (Siemens PLM Software)
NX offers an all-encompassing CAD/CAM/CAE solution that provides a high level of automation, simulation, and digital twin capabilities, strengthening Siemens’ strategic presence in European manufacturing innovation.
Onshape (PTC Inc.)
Onshape delivers cloud-native, collaborative CAD technology optimized for agile manufacturing environments, enabling real-time multi-user editing and streamlined product development processes across Europe.
Strategic Business Developments
- April 2023 – Dassault Systèmes – Launched 3DEXPERIENCE platform expansion – Strengthens integrated product lifecycle management capabilities for European manufacturers.
- June 2023 – Autodesk Inc. – Introduced Fusion Cloud AM – Accelerates cloud-based additive manufacturing workflows, boosting digital factory integration.
- August 2023 – Siemens PLM Software – Announced NX 12 Release – Enhances simulation, automation, and additive manufacturing features, reinforcing Siemens’ competitive edge in high-performance design tools.
- October 2023 – PTC Inc. – Completed acquisition of Fractal Analytics – Enhances data-driven design and AI capabilities, supporting smart manufacturing innovation in Europe.
- December 2023 – Hexagon AB – Invested in digital twin tech development – Focuses on Industry 4.0 integration to improve real-time manufacturing insights and predictive maintenance.
Frequently Asked Questions
What is the Europe 3D CAD for Manufacturing Market?
The Europe 3D CAD for Manufacturing Market encompasses the industry of three-dimensional computer-aided design software tailored for manufacturing applications across Europe. It facilitates precise product modeling, engineering analysis, and manufacturing process optimization, enabling companies to innovate and streamline production workflows effectively.
What is the current market size of Europe 3D CAD for Manufacturing Market?
As of 2026, the market size for Europe 3D CAD for Manufacturing is valued at approximately USD 4.2 Billion, reflecting steady growth driven by technological adoption, industry digitalization, and increasing demand for advanced design solutions across diverse manufacturing sectors.
What factors are driving the Europe 3D CAD for Manufacturing Market?
Major drivers include the increasing adoption of digital manufacturing processes, the need for precise and efficient product design, advancements in CAD software capabilities, and competitive pressure to reduce time-to-market. Industry 4.0 initiatives further accelerate market growth.
Which region dominates the Europe 3D CAD for Manufacturing Market?
Western Europe remains the dominant region due to its advanced manufacturing infrastructure, high technological penetration, and on-going industrial modernization efforts, with Germany, France, and the UK leading adoption rates significantly.
Which segment is expected to grow the fastest?
The additive manufacturing segment within the 3D CAD market is projected to experience the fastest growth, driven by rising adoption of 3D printing technologies for rapid prototyping, complex component creation, and customized manufacturing.
Who are the leading companies operating in the Europe 3D CAD for Manufacturing Market?
Key industry players include Dassault Systèmes, Siemens PLM Software, Autodesk, PTC, and Hexagon AB, all of which hold significant market shares through innovation, strategic partnerships, and comprehensive product offerings tailored for manufacturing needs.
Analyst Perspective
The Europe 3D CAD for Manufacturing Market exhibits a mature yet evolving landscape, driven by ongoing technological advancements and regional digital transformation initiatives. Long-term prospects remain promising, with sustained demand from aerospace, automotive, and precision engineering sectors. Commercial opportunities are abundant in software customization, integration with emerging technologies like AI and IoT, and expanding into SMEs seeking advanced design solutions. The evolution of cloud-based CAD platforms presents significant efficiencies and collaboration benefits, making them a strategic focus for vendors. Investment priorities should emphasize R&D for improved user interfaces, interoperability, and data security, alongside strategic partnerships to widen market reach. Competitive intensity is expected to remain high, with incumbent vendors consolidating their positions through innovation and acquisitions. Regional growth potential is strongest in advanced economies within Northern and Western Europe, where industry digitization progresses rapidly. Long-term, the market’s trajectory hinges on technological adoption rates, regional policy support, and the capacity to innovate in a cost-effective manner, positioning industry leaders for sustained growth and competitive advantage.
