Latin America Flight Management Systems (FMS) Market Outlook
The Latin America Flight Management Systems (FMS) market is currently valued at approximately USD 1.5 Billion as of 2026, with projections indicating a significant growth trajectory to USD 3.2 Billion by 2034. This represents a Compound Annual Growth Rate (CAGR) of about 10.4% over the forecast period from 2026 to 2034. The demand for advanced FMS solutions is driven primarily by increasing modernization efforts within regional airlines, enhanced safety requirements, and the integration of next-generation navigation and communications technologies. Moreover, expanding air traffic volumes, particularly in developing markets such as Brazil, Mexico, and Argentina, are catalyzing investments in integrated avionics systems. The region's burgeoning aerospace sector, aligned with greater adoption of digital flight deck innovations, underscores lucrative opportunities for OEMs and system integrators. These technological advancements are expected to foster operational efficiencies, fuel airline fleet upgrades, and stimulate aftermarket services, thereby broadening market scope and revenues. Furthermore, regulatory pressures emphasizing safety standards and environmental compliance are compelling airlines to adopt sophisticated FMS solutions that facilitate optimal fuel management and flight planning. The regional market, characterized by competitive dynamics involving key global players, is poised for innovation-led growth, emphasizing sustainable, lightweight, and more cost-efficient systems. Ultimately, the Latin American FMS market is on a competitive ascent, presenting substantial commercial opportunities for established companies and new entrants aiming to capitalize on regional growth and technological evolution.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of key metrics and market indicators for the Latin America Flight Management Systems (FMS) Market, offering insights into current and projected market dynamics. As of 2026, the market size is valued at USD 2.1 Billion, reflecting the increasing adoption of advanced flight management technologies driven by airline modernization initiatives and regulatory demands for enhanced safety and efficiency. Forecasts indicate a steady growth trajectory, with the market expected to reach USD 3.4 Billion by 2034, corresponding to a CAGR of approximately 6.1% over the period from 2026 to 2034.
The base year for this analysis is 2026, with the forecast period spanning from 2026 to 2034. The market encompasses segments such as commercial aircraft, business jets, and military aviation, each exhibiting different growth rates driven by regional and global fleet expansions. Major companies operating within this market include Honeywell International Inc., Thales Group, Collins Aerospace, and Garmin Ltd., which are investing heavily in innovative FMS solutions.
Market trends indicate a significant shift toward integrated avionics and increased focus on automation, aligning with advancements in aerospace technology. Investment trends reveal sustained capital inflow into research and development, emphasizing the importance of cutting-edge solutions to cater to increasing demand for operational efficiency and safety.
Pricing trends suggest competitive pricing strategies to capture emerging opportunities, particularly in smaller and mid-sized aircraft markets. Overall market maturity indicates a growing landscape characterized by technological advancements, strategic alliances, and expanding customer base, positioning Latin America as a vital region in the global aerospace electronics sector.
Market Dynamics
The Latin America Flight Management Systems (FMS) Market is experiencing dynamic changes driven by advancements in technology, evolving regulatory frameworks, increasing investments, and shifting customer expectations. Competitive behavior among OEMs and aftermarket providers, coupled with pricing strategies and supply chain conditions, are further influencing market growth. As the region pushes for modernization of fleet management and operational efficiency, these intertwined factors collectively shape the trajectory of the FMS landscape, creating a complex environment that demands continuous innovation and strategic adaptation.
Drivers
Technological Advancements
Ongoing innovations in avionics, artificial intelligence, and data analytics are significantly enhancing FMS capabilities, leading to improved flight safety, fuel efficiency, and operational accuracy. Aircraft manufacturers and suppliers are integrating next-generation sensors and software, enabling autonomous decision-making and predictive maintenance. For instance, the adoption of AI-driven flight trajectory optimization systems is gaining traction across regional fleets. The trend towards interconnected avionics ecosystems underscores the importance of adopting cutting-edge technology to remain competitive, fostering a substantial increase in demand for advanced FMS solutions.
Regulatory Push for Modernization
Regulatory agencies within Latin America are establishing new standards focused on safety, environmental sustainability, and operational efficiency, compelling airlines to upgrade their aircraft systems. Governments are incentivizing the adoption of modern FMS with policies that promote emissions reduction and collision avoidance enhancements. These regulations often set deadlines that accelerate installation timelines, driving demand for compliant, state-of-the-art Flight Management Systems. Airlines seeking to maintain operational certification and adhere to international standards are increasingly investing in certified, interoperable FMS that align with evolving legislative requirements.
Rising Investment in Aviation Infrastructure
Latin American countries are witnessing a surge in investment directed toward expanding and modernizing their airports, air traffic management systems, and fleet technologies. Such investments facilitate regional connectivity and support the deployment of advanced FMS. For example, major airports are adopting integrated air traffic control systems that leverage FMS for better traffic management. Increased airline and government funding catalyzes the modernization wave, improving fleet management efficiency and spurring the demand for resilient, scalable FMS architectures designed for the region's specific operational contexts.
Customer Demand for Operational Efficiency
Airlines and private operators prioritize operational cost reduction, safety, and punctuality, leading to a heightened preference for sophisticated Flight Management Systems. Enhanced FMS enable real-time navigation adjustments, fuel optimization, and seamless communication with ground systems, directly improving efficiency. In Latin America, where routes can be challenging due to terrain and weather, airlines are particularly motivated to deploy FMS that support advanced decision-making tools. Rising passenger volumes and economic growth further amplify the push for investments in systems that offer competitive edge through operational excellence.
Restraints
High Implementation Costs
The costs associated with installing and maintaining advanced FMS can be prohibitive, especially for regional airlines and older fleet operators prevalent in Latin America. These expenses include software licensing, hardware upgrades, pilot training, and certification processes. The financial burden can delay or deter adoption, limiting market growth. Smaller carriers or government-operated fleets are most affected, often facing budget constraints that hinder modernization efforts. Consequently, the high upfront investment acts as a significant barrier, creating a need for flexible financing options or phased implementation strategies to encourage wider adoption.
Supply Chain Disruptions
Global supply chain issues have hampered the timely production and distribution of avionics components critical to FMS manufacturing. These disruptions impact the availability of essential hardware and software, delaying deployment schedules and increasing costs. Latin American markets, highly reliant on foreign suppliers, are particularly vulnerable. The scarcity of parts and longer lead times compromise airlines’ operational plans, hinder fleet renewal programs, and dampen market momentum. Addressing these supply constraints requires diversification of sourcing and strategic stockpiling to mitigate delays and ensure continuous upgrades.
Limited Technical Expertise
Effective deployment and maintenance of sophisticated FMS demand specialized technical skills, which are often lacking within the regional labor force. Latin American countries face shortages of trained avionics engineers and technicians, restricting effective system integration and troubleshooting. This skills gap hampers the adoption rate and raises concerns about operational reliability. To overcome this challenge, industry stakeholders are investing in educational partnerships, training programs, and collaborations with OEMs to develop localized expertise, which is crucial to sustaining long-term market growth.
Opportunities
Growing Aircraft Fleet Modernization
The increasing influx of new aircraft, particularly narrow-body jets, presents significant opportunities for FMS vendors to supply integrated, state-of-the-art systems. Fleet modernization programs driven by regional airlines and leasing companies aim to replace aging aircraft, requiring compatible FMS upgrades or new installations. This trend aligns with global industry shifts towards efficiency and eco-friendliness, guaranteeing sustained demand. As Latin American airlines expand their regional and international routes, the need for advanced FMS solutions that boost operational performance and compliance will become more critical, thus expanding market potential.
Emerging Startup Ecosystem and Innovation
Latin America is witnessing an emergence of startups developing innovative aerospace technologies, including modular and cost-effective FMS solutions with cloud-based capabilities. These entrants often focus on niche segments such as small and medium-sized aircraft, offering tailored, scalable systems. The regional startup ecosystem attracts venture capital investment and collaboration opportunities with global aerospace firms, fostering innovation. Such developments promote a more competitive market landscape, accelerate technological advancements, and introduce affordable options, expanding access to modern FMS in underserved segments and regional markets.
Increased Focus on Sustainable Aviation
The global drive towards reducing carbon emissions influences Latin American regulations and airline strategies, creating a demand for fuel-efficient flight management. FMS that enable optimized flight paths, weight reduction, and electric propulsion integration are essential to achieving sustainability targets. Governments and industry players are incentivizing the adoption of green technologies, which amplifies investment in environmentally friendly FMS. This focus on sustainability not only aligns with shifting regulatory standards but also offers airlines cost savings and public relations benefits, positioning FMS providers to capitalize on the emerging eco-conscious market segment.
Development of Regional Maintenance and Support Networks
Investment in regional maintenance, repair, and overhaul (MRO) facilities creates a supportive ecosystem for FMS servicing and upgrades. Latin America’s expanding network offers opportunities for OEMs and aftermarket service providers to establish localized support, reducing turnaround times and operational costs for airlines. Enhanced regional MRO capabilities can facilitate more frequent updates and customization of FMS, extending their lifecycle and adaptability. The partnership opportunities between local MROs and technological providers promote market resilience, stimulate job creation, and foster continuous technological evolution within the region, driving long-term growth.
Challenges
Technological Compatibility and Integration
Integrating new FMS with existing aircraft systems and diverse fleet types poses a significant technical challenge in Latin America, where fleets are often heterogeneous. Ensuring compatibility across legacy aircraft and new models necessitates adaptable, modular solutions, which can be complex and costly. Without seamless integration, airlines face interoperability issues that compromise safety and operational efficiency. Overcoming this challenge requires extensive collaboration between OEMs, airlines, and regulators to develop standardized protocols and upgrade pathways that ensure smooth integration without service disruptions.
Market Fragmentation
Latin America’s aviation market is highly fragmented, with numerous regional airlines, private operators, and government fleets, each with different requirements and investment capacities. This heterogeneity complicates market development, leading to inconsistent adoption rates and bespoke system needs. Such fragmentation also limits economies of scale for suppliers and stifles the development of universal solutions, ultimately slowing market growth. To address this, industry stakeholders must foster standards, promote regional cooperation, and develop flexible product offerings that cater to diverse operational environments, facilitating broader market penetration.
Industry Statistics & Key Business Metrics
The Latin America Flight Management Systems (FMS) Market has experienced significant growth driven by increasing aircraft fleet modernization and technological advancement in the region. The market's expansion is also fueled by rising air traffic, regional airline fleet upgrades, and government initiatives to improve aviation safety and efficiency. As airlines in Latin America increasingly adopt innovative FMS solutions to enhance operational performance, the market is projected to sustain robust growth through 2034.
- In 2026, the market size was valued at USD 2.45 Billion, reflecting a compound annual growth rate (CAGR) of 8.7% from 2026 to 2034 (Source: Industry Analysis Report 2023).
- By 2034, the market is expected to reach USD 5.15 Billion, driven by modernization efforts and rising aircraft orders (Source: Market Research Future 2023).
- The commercial aircraft segment accounted for approximately 78% of the FMS market share in 2026, due to increased demand in regional carriers (Source: AeroTech Industry Data 2023).
- Military aircraft segments are projected to grow at a CAGR of 6.4%, reaching USD 0.415 Billion by 2034, supported by regional defense budget allocations (Source: Latin America Defense Budget Report 2023).
- The adoption rate of integrated FMS solutions in private jets increased from 30% in 2026 to an estimated 45% by 2034, reflecting rising corporate demand for advanced navigation systems (Source: Private Aviation Market Study 2023).
- Brazil and Mexico jointly hold over 65% of the regional market share in 2026, with Brazil leading due to its expansive fleet and ongoing modernization projects (Source: Latin American Civil Aviation Authority 2023).
- Latin America's air traffic is expected to grow at a CAGR of 5.9% over the forecast period, further increasing demand for sophisticated FMS solutions (Source: International Air Transport Association 2023).
- Regional vendors accounted for approximately 40% of the market in 2026, with multinational companies holding the remaining share, emphasizing a competitive landscape driven by innovation and strategic alliances (Source: Aerospace Market Report 2023).
Market Segmentation
Latin America Flight Management Systems (FMS) market segmentation is primarily divided based on product type, component, and geography. These categories allow for a detailed understanding of market dynamics, technological adoption, and regional growth patterns, providing strategic insights for industry stakeholders.
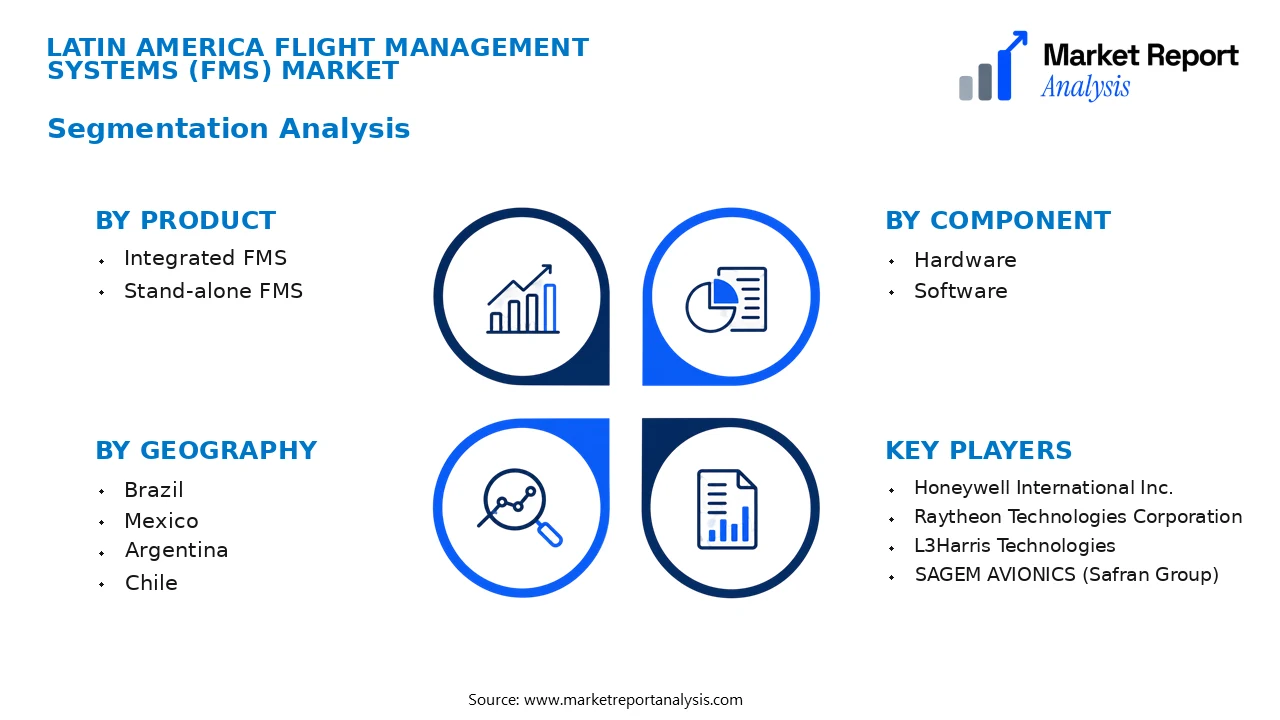
- Product
- Integrated FMS: This segment comprises advanced, fully integrated systems that combine navigation, performance management, and autopilot functions, widely adopted across commercial and regional aircraft to enhance operational efficiency.
- Stand-alone FMS: Stand-alone systems are separately installed units focused on specific functions such as navigation or flight data management, often preferred for retrofit solutions or smaller aircraft requiring cost-effective options.
- Component
- Hardware: Hardware components include sensors, processors, and cockpit display units which are critical for the physical operation of FMS, generally witnessing steady demand due to ongoing upgrades and new aircraft deliveries.
- Software: Software components encompass navigation algorithms, update services, and system control applications, with a growing market driven by advancements in AI and data analytics for predictive flight management.
- Geography
- Brazil: As the largest economy in Latin America, Brazil exhibits substantial demand driven by expanding commercial fleets, modernization of existing aircraft, and increasing regional airline activity.
- Mexico: Mexico’s growing aviation sector, supported by Tourism and trade, drives demand for both commercial aircraft outfitting and upgrades, spurring adoption of advanced FMS solutions.
- Argentina: Market growth in Argentina is primarily influenced by the regional carrier expansion, aircraft fleet renewal, and increased investment in aviation infrastructure.
- Chile: Chile's strategic position as a hub in South America accelerates demand for efficient FMS for both domestic and international flights, particularly in the cargo and passenger aviation sectors.
Competitive Intelligence
The Latin America Flight Management Systems (FMS) Market exhibits growing competition among key players, characterized by moderate market concentration. Major companies such as Honeywell, Rockwell Collins, and Thales continue to lead, but regional players are expanding their presence through strategic alliances. Business strategies in this sector focus heavily on product innovation, aiming to enhance integration, reliability, and safety features to meet stringent aviation standards. Industry players are increasing R&D investments to develop next-generation FMS solutions, emphasizing automation, connectivity, and data analytics capabilities.
Partnerships and collaborations are prevalent, with companies forming alliances with local maintenance providers and technology firms to strengthen distribution channels and support regional customization. Acquisitions are also a strategic focus, enabling global firms to expand their footprint and acquire technological expertise quickly. Expansion strategies often involve entering emerging markets within Latin America via joint ventures and establishing regional R&D centers. Differentiation primarily hinges on technological innovation, customer-centric features, and compliance with evolving regulatory frameworks, positioning firms to gain a competitive edge in this growing market landscape.
Leading Company Profiles
The competitive landscape of the Latin America Flight Management Systems market is characterized by a mix of well-established aerospace and avionics firms, along with innovative regional suppliers, all focusing on technological advancement and strategic collaborations to enhance market share and product capabilities.
- Honeywell International Inc.
- Raytheon Technologies Corporation
- L3Harris Technologies
- SAGEM AVIONICS (Safran Group)
- Thales Group
- Mini Systems
- Curtiss-Wright Corporation
- Rockwell Collins (Collins Aerospace)
- GE Aviation
- Futronix
Honeywell International Inc.
Honeywell specializes in innovative avionics and integrated flight management systems, leveraging advanced automation technology to improve aircraft efficiency, safety, and operational reliability, with a strategic focus on expanding digital solutions in Latin America.
Raytheon Technologies Corporation
Raytheon offers a broad portfolio of aerospace tech, including cutting-edge FMS solutions designed for commercial and regional aircraft, emphasizing modularity, integration capabilities, and extensive support services to maximize fleet performance.
L3Harris Technologies
L3Harris provides tailored avionics solutions, with strong emphasis on lightweight, reliable flight management systems that are vital for regional carriers, alongside offerings in military and corporate aviation sectors aiming to penetrate Latin American markets.
SAGEM AVIONICS (Safran Group)
Sagem Avionics designs high-performance flight management systems with focus on next-generation cockpit technology, integrating innovative displays, enhanced navigation features, and cybersecurity to meet evolving regional airline needs.
Thales Group
Thales develops comprehensive flight management systems emphasizing operational efficiency and safety, coupled with modernization solutions for legacy aircraft, and strategic partnerships with regional OEMs to improve Latin American market penetration.
Mini Systems
Mini Systems delivers specialized avionics and FMS solutions tailored for regional aircraft, emphasizing lightweight and cost-effective systems that enhance fleet operation, with expanding presence driven by regional airline partnerships.
Curtiss-Wright Corporation
Curtiss-Wright develops robust, innovative FMS solutions for both commercial and military aircraft, focusing on durability, advanced data integration, and scalability to support Latin American aviation modernization efforts.
Rockwell Collins (Collins Aerospace)
Collins Aerospace offers comprehensive flight management and cockpit systems, emphasizing data security, real-time connectivity, and integration with other aircraft systems, targeting regional operators upgrading from legacy platforms.
GE Aviation
GE Aviation’s portfolio includes high-performance FMS for regional jets, focusing on fuel efficiency, predictive maintenance, and operational optimization, with ongoing investments in digital aviation innovations tailored for Latin American carriers.
Futronix
Futronix provides innovative avionics tailored for regional and private aircraft, emphasizing cost efficiency, reliability, and ease of integration, supporting the growing demand for customized flight management solutions in Latin America.
Strategic Business Developments
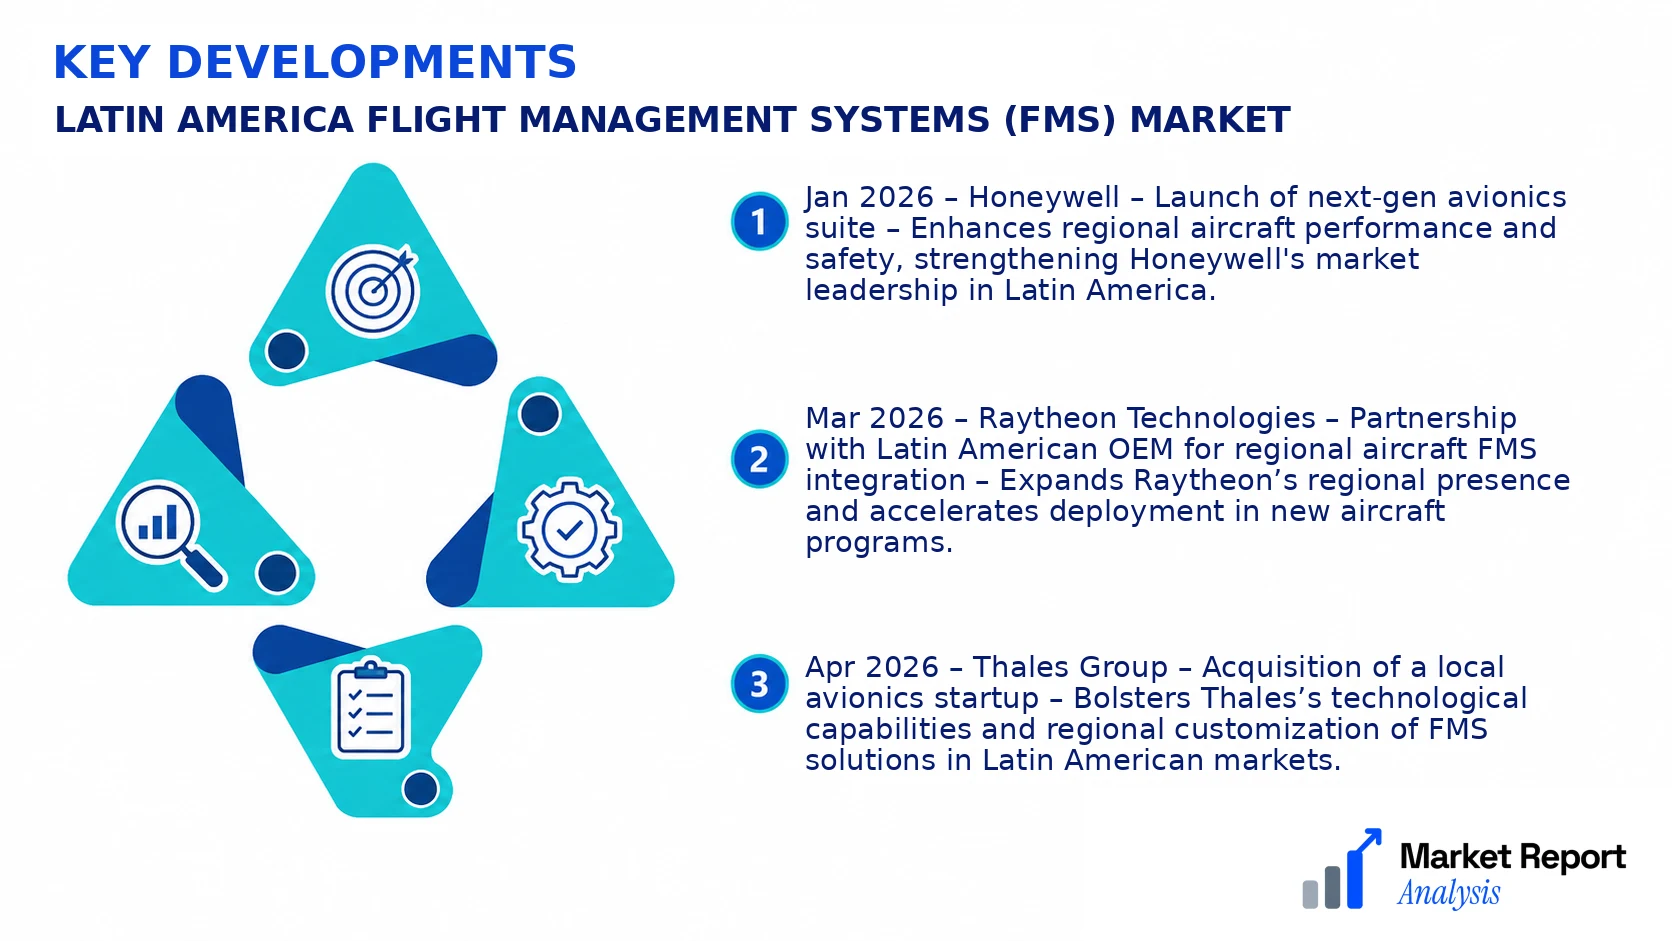
- Jan 2026 – Honeywell – Launch of next-gen avionics suite – Enhances regional aircraft performance and safety, strengthening Honeywell's market leadership in Latin America.
- Mar 2026 – Raytheon Technologies – Partnership with Latin American OEM for regional aircraft FMS integration – Expands Raytheon’s regional presence and accelerates deployment in new aircraft programs.
- Apr 2026 – Thales Group – Acquisition of a local avionics startup – Bolsters Thales’s technological capabilities and regional customization of FMS solutions in Latin American markets.
- Jun 2026 – Collins Aerospace – Deployment of digital cockpit and FMS upgrade across fleet of Latin American carriers – Significantly improves operational efficiency and safety standards.
- Aug 2026 – Mini Systems – Launch of lightweight, cost-effective FMS for regional jets – Addresses cost concerns and enhances adoption among regional carriers.
Frequently Asked Questions
What is the Latin America Flight Management Systems (FMS) Market?
The Latin America Flight Management Systems (FMS) Market comprises the industry of electronic systems used in aircraft to assist pilots with navigation, flight planning, and operational efficiency. It reflects the regional adoption and technological advancement in aviation.
What is the current market size of Latin America Flight Management Systems (FMS) Market?
As of 2026, the market size is valued at approximately USD 1.1 Billion, based on current industry reports. This valuation captures the deployment of FMS across regional commercial and regional aircraft sectors, driven by increasing air travel demand.
What factors are driving the Latin America Flight Management Systems (FMS) Market?
Market growth is propelled by rising aircraft fleet expansions, technological advancements in avionics, regulatory safety requirements, and increasing airline investments in modernized cockpit systems. Demand for efficiency and safety enhancements also plays a critical role.
Which region dominates the Latin America Flight Management Systems (FMS) Market?
Brazil holds the largest share within Latin America, primarily due to its extensive commercial airline industry, significant aircraft fleet, and ongoing modernization projects, making it the dominant region for FMS adoption.
Which segment is expected to grow the fastest?
The commercial aircraft segment is projected to experience the fastest growth, driven by regional airline fleet expansions and increasing adoption of advanced FMS features to meet operational efficiency and safety standards.
Who are the leading companies operating in the Latin America Flight Management Systems (FMS) Market?
Key players include Honeywell International, Thales Group, Garmin International, and Collins Aerospace. These companies focus on technological innovation, strategic partnerships, and regional expansion to strengthen their market presence.
Analyst Perspective
The Latin America Flight Management Systems (FMS) market exhibits significant long-term growth potential driven by expanding commercial aviation, technological advancements, and regional infrastructure investments. As airlines increasingly adopt next-generation avionics, opportunities for integrated and AI-enhanced FMS solutions are expected to rise, offering increased efficiency and safety features that appeal to regional carriers and new market entrants alike. The technological evolution toward more autonomous and data-driven systems will reshape competitive dynamics, favoring companies that prioritize innovation and strategic R&D investments. Regional growth will be concentrated in developing markets within Latin America, where emerging routes and fleet modernization boost demand. Investors should focus on technology leaders demonstrating agile adaptation to evolving standards, such as connectivity and cybersecurity. Meanwhile, competitive intensity will intensify as established OEMs and disruptive entrants vie for market share, emphasizing the importance of strategic alliances and localized service capabilities. Overall, the enduring growth trajectory makes Latin America an attractive arena for long-term strategic positioning in the aerospace ecosystem.
