Flight Management Systems (FMS) Market Outlook
The global Flight Management Systems (FMS) market is currently valued at approximately USD 4.8 Billion in 2026 and is projected to reach USD 9.2 Billion by 2034. This growth is attributed to a compounded annual growth rate (CAGR) of around 8.5% during the forecast period from 2026 to 2034. The market expansion is driven largely by increasing air passenger traffic, demand for fuel-efficient and technologically advanced aircraft, and the implementation of NextGen and SESAR air traffic management initiatives. Advancements in automation, integration of artificial intelligence, and increased focus on safety and operational efficiency are propelling market growth. Moreover, the rising adoption of lightweight, multifunctional systems in commercial, military, and cargo aircraft presents significant commercial opportunities for market players, as airlines and defense agencies seek to modernize and optimize fleet operations through advanced FMS solutions.
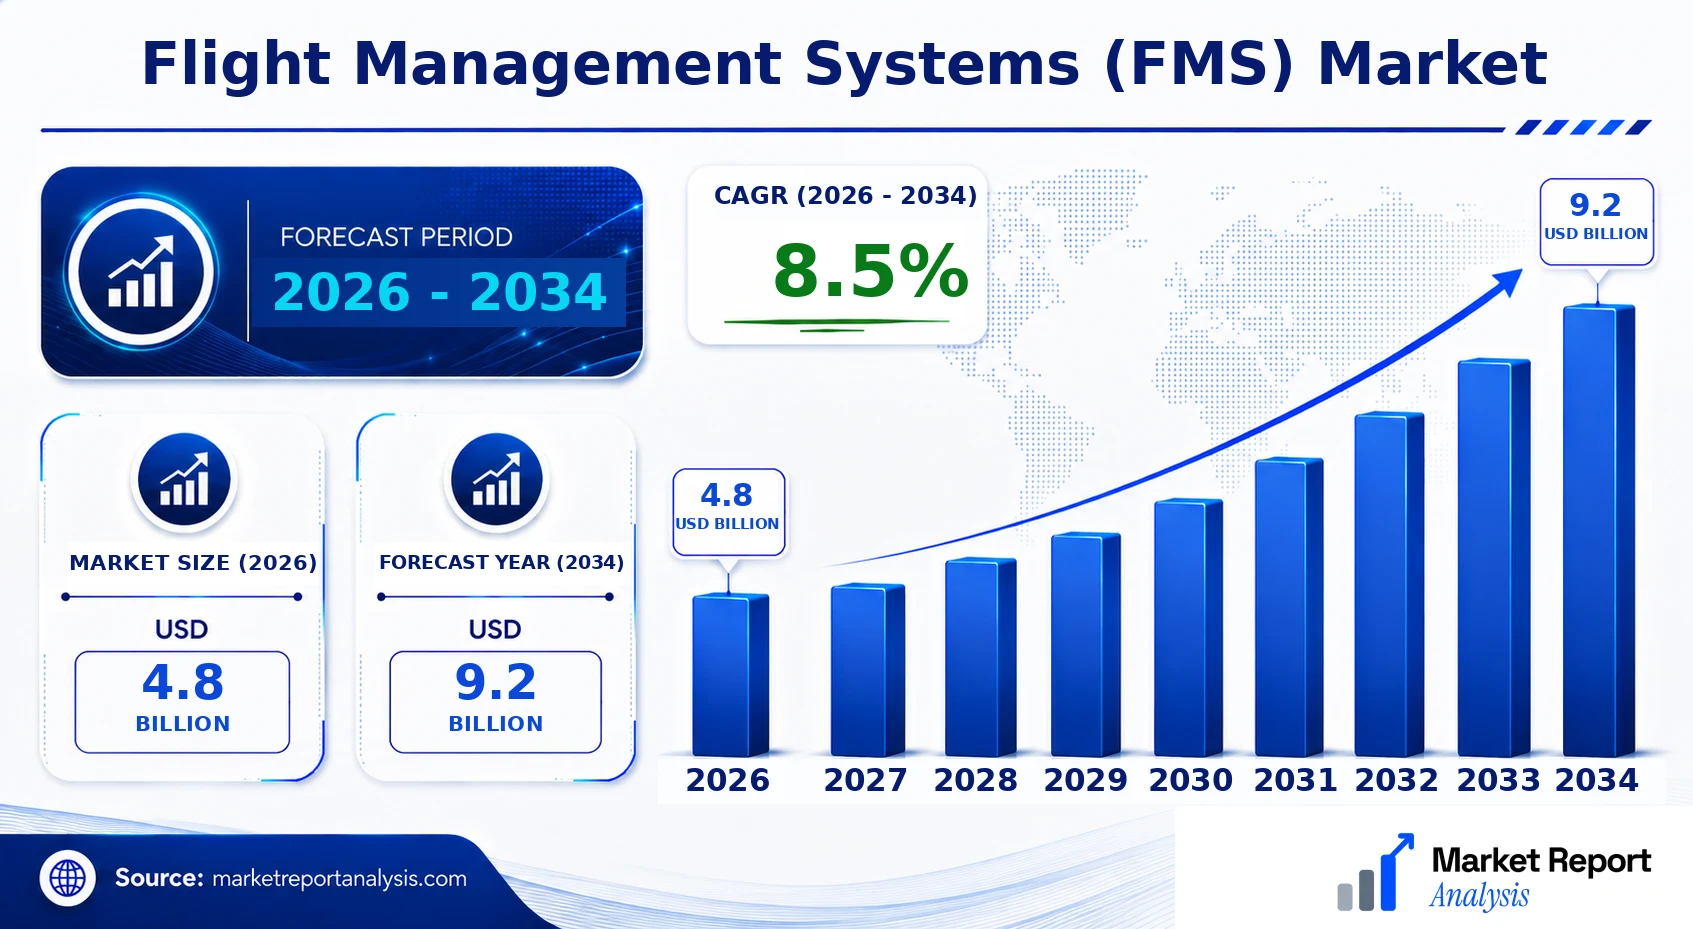
What is the Flight Management Systems (FMS) Market Size?
As of 2026, the FMS market is valued at approximately USD 4.8 Billion, with forecasts indicating an increase to about USD 9.2 Billion by 2034. This signifies a robust CAGR of 8.5% over the forecast period. The market growth is fueled by the aviation industry's push toward digital transformation, where FMS serves as a central component in modern aircraft operations. Key drivers include the surge in commercial airline fleet expansions, upgrades in older aircraft with advanced FMS, and a rising emphasis on safety, reliability, and fuel efficiency. North America and Europe currently lead the market due to sophisticated aerospace infrastructure and high aircraft procurement rates, while Asia-Pacific presents significant growth opportunities owing to expanding economies and increasing air traffic. The integration of FMS with other avionics and the proliferation of automation technologies further bolster market prospects. Future investments are expected to focus on developing more intuitive, lightweight, and cyber-secure FMS solutions, catering to the evolving needs of both commercial and defense sectors.
Key Takeaways
- The market is valued at approximately USD 9.2 Billion in 2026 and is projected to reach USD 15.3 Billion by 2034.
- The CAGR from 2026 to 2034 is estimated at 6.8%, reflecting steady industry growth.
- North America and Europe are dominant regions, though Asia-Pacific is under rapid expansion.
- Commercial aviation remains the primary end-use industry for FMS, followed by military applications.
- Demand is driven by increasing aircraft orders, fleet modernizations, and regulatory mandates for safety and efficiency.
- Technological innovations such as AI integration and real-time data processing are transforming FMS capabilities.
- The market faces competition from established players and emerging startups focusing on cybersecurity and lightweight design.
- Regulatory frameworks are evolving to support safer, more reliable avionics systems, creating new compliance opportunities.
- Investments are shifting toward scalable, modular, and cyber-resilient FMS solutions to meet future operational challenges.
- The trend toward autonomous and electric aircraft is expected to further influence FMS development and adoption.
Industry Performance Dashboard
The Industry Performance Dashboard offers a quantitative overview of the current and projected market landscape for Flight Management Systems (FMS). This section provides key market indicators that help stakeholders gauge industry health, investment opportunities, and competitive positioning within the global aviation sector. The dashboard consolidates historical data, present status, and future forecasts into a clear, comparative format, facilitating strategic decision-making and market analysis.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.8 Billion |
| Market Value (2026) | USD 4.8 Billion |
| Forecast Size (2034) | USD 9.2 Billion |
| CAGR | 8.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product, Application, Geography |
| Major Companies | Honeywell International Inc., Rockwell Collins (a part of Collins Aerospace), Thales Group, Garmin Ltd., Raytheon Technologies Corporation, L3Harris Technologies, Mitsubishi Electric Corporation, Boeing, Airbus SE, Saab AB |
Market Dynamics
The global Flight Management Systems (FMS) Market is experiencing dynamic shifts driven by advances in technology, evolving regulatory frameworks, strategic investments, and shifting customer requirements. Manufacturers and suppliers are continuously innovating to meet increasing safety standards, reduce operational costs, and enhance aircraft efficiency. Regulatory bodies worldwide enforce strict certification standards, which influence product development and deployment. Investment flows aim to capitalize on the integration of artificial intelligence and sensor technologies, while airline customers seek more reliable, fuel-efficient, and automation-compatible solutions. Market competition is intensifying amidst pricing pressures and supply chain complexities, shaping a landscape focused on innovation, compliance, and cost-effectiveness.
Drivers
Technological Innovations and Digitalization Trends
The ongoing integration of advanced digital solutions such as artificial intelligence, machine learning, and augmented reality is revolutionizing flight management systems. These innovations enhance navigation precision, predictive maintenance, and safety protocols. Airlines and aerospace manufacturers are investing heavily in next-generation FMS to improve operational efficiency and passenger experience. For instance, the adoption of AI-driven routing algorithms reduces fuel consumption and flight delays, directly impacting airline profitability. The trend toward digitalization is further supported by the increasing use of IoT sensors and data analytics, which optimize aircraft operations and maintenance schedules, driving substantial market growth.
Regulatory Mandates and Certification Standards
Global aviation authorities, including the FAA and EASA, impose stringent certification standards for FMS to ensure safety, reliability, and interoperability. These regulations compel manufacturers to develop compliant systems, leading to increased R&D investments and product differentiation. As safety remains paramount, airlines are mandated to upgrade to certified FMS versions, fueling market expansion. Regulatory compliance also incentivizes innovation, prompting manufacturers to develop modular, customizable systems that meet diverse regional standards. The expansion of regulatory scopes to include cybersecurity considerations further influences the evolution of FMS architecture and features.
Growing Demand for Fuel Efficiency and Operational Cost Reduction
With fuel costs constituting a significant portion of airline operating expenses, there is a strong market impetus for FMS that can optimize routes, altitudes, and engine parameters. Airlines are increasingly adopting advanced FMS solutions to achieve fuel savings and reduce carbon emissions, aligning with sustainability goals and regulatory pressures. For example, optimized flight planning enabled by sophisticated FMS algorithms can reduce fuel burn by up to 5%, translating into millions of dollars in cost savings annually for large carriers. This demand fosters the development of lightweight, high-performance systems with real-time data processing capabilities.
Increase in Aircraft Orders and Fleet Modernization
The rising order backlog of commercial aircraft, especially new-generation narrowbody and widebody jets, is a major growth driver for the FMS market. Fleet modernization programs focus heavily on incorporating the latest avionics technology, including innovative FMS, to enhance safety, scalability, and efficiency. Governments and airlines are investing in environmentally friendly aircraft, often equipped with advanced FMS to meet strict emission standards. The global push toward regional connectivity and low-cost carriers also accelerates demand for cost-effective, reliable flight management solutions adaptable across diverse aircraft types and routes, bolstering market prospects consistently.
Restraints
High Development and Certification Costs
The extensive R&D requirements, coupled with rigorous certification processes, contribute to high costs associated with developing and deploying advanced FMS. These expenses act as barriers, especially for smaller suppliers or emerging market players attempting to enter the industry. Airlines and operators might face budget constraints, limiting their ability to procure the latest systems. High certification costs also prolong time-to-market, discouraging rapid innovation and creating a market environment where only well-funded entities can compete effectively, thereby restricting overall market entries and advancements.
Complex Integration and Compatibility Challenges
Integrating new FMS with existing aircraft avionics systems can pose significant technical challenges, especially in retrofitting older aircraft. Compatibility issues may require extensive testing, customization, and certification efforts, leading to increased project costs and delays. Additionally, ensuring seamless interoperability across various aircraft models and operating environments complicates deployment strategies. These integration hurdles can slow market adoption, particularly in regions with large fleets of older aircraft, thus limiting widespread implementation and growth.
Market Fragmentation and Standardization Gaps
The presence of multiple standards and proprietary systems across regions hampers cross-border compatibility and interoperability. This fragmentation complicates aircraft certification, maintenance, and training processes, reducing the attractiveness of new FMS solutions. The lack of universally adopted standards stifles innovation and economies of scale, ultimately raising costs for manufacturers and airlines. Addressing these gaps through industry-wide consensus and standardization initiatives remains a challenge, potentially impeding market expansion and technological progress.
Opportunities
Expansion of Commercial Aircraft Fleet and New Aircraft Programs
The global fleet modernization and expansion efforts present substantial growth possibilities for the FMS market. Emerging economies are investing in new aircraft to meet rising passenger demand, which drives the adoption of modern, feature-rich FMS. Innovative lightweight and modular systems tailored for various aircraft types can enhance operational efficiency at different price points. The initiation of new aircraft programs by both major OEMs and startups further fuels demand, creating opportunities for embedded FMS solutions that deliver superior safety, automation, and fuel efficiency, thus expanding the total addressable market significantly.
Investment and Innovation Ecosystem Strengthening
The incubation of startups and increased venture capital investment in aerospace tech are fostering a culture of innovation in FMS development. Focus areas include AI-driven predictive analytics, autonomous operation capabilities, and cybersecurity enhancements. Collaborations between established aerospace companies and tech startups are accelerating the deployment of disruptive solutions. These innovations are expected to lead to more intelligent, adaptable, and resilient flight management systems, attracting both government and private sector funding. This ecosystem dynamic is pivotal for sustained industry growth, enabling rapid prototyping and commercialization of cutting-edge technologies.
Emerging Technologies and Industry 4.0 Integration
The integration of Industry 4.0 principles, such as IoT, big data analytics, and cloud computing, is transforming FMS architecture. These technologies enable real-time data-driven decision-making, predictive maintenance, and enhanced safety protocols. The adoption of edge computing and enhanced cybersecurity measures ensures robust operational integrity. Advances in sensor technologies and satellite communication further enhance system capabilities. Such technological convergence presents opportunities for the development of next-generation FMS that outperform current solutions in terms of efficiency, safety, and environmental compliance, unlocking new markets and applications.
Future Commercial and Defense Investment Synergies
The dual-use nature of aerospace technology, including applications in commercial and defense sectors, creates opportunities for cross-sector innovations in FMS. Defense contracts often lead to breakthrough technological developments, which later transition to commercial aviation. Conversely, commercial sector advancements foster new defense capabilities, especially in unmanned and autonomous systems. The interconnected investment landscape accelerates technological progress, mitigates R&D costs through shared initiatives, and broadens the application spectrum for advanced FMS, driving long-term market resilience and growth prospects.
Challenges
Cybersecurity Risks and Data Privacy Concerns
As FMS become more connected and reliant on digital infrastructure, they are increasingly vulnerable to cyber threats and data breaches. Ensuring system integrity against hacking, malware, and unauthorized access is critical for safety and operational continuity. The complexity of cybersecurity solutions, the high cost of implementing robust protections, and evolving threat landscapes present significant challenges. Airlines and manufacturers must continuously upgrade security protocols, which can delay deployment and inflate costs, potentially hindering market expansion and eroding stakeholder confidence in digitalized FMS solutions.
Technological Obsolescence and Rapid Innovation Pace
The rapid evolution of aerospace technology means today’s advanced FMS can quickly become outdated. Maintaining a competitive edge requires continuous innovation and timely upgrades, which can be resource-intensive. This pressure incentivizes manufacturers to balance investment in current product lines while investing in future-proof designs. Market players face the challenge of designing scalable, upgradeable systems that keep pace with innovation without incurring prohibitive costs or causing extensive operational disruptions. Failure to manage this balance risks obsolescence and loss of market share.
Industry Statistics & Key Business Metrics
The Flight Management Systems (FMS) market continues to demonstrate robust growth driven by technological advancements and increasing demand for automated navigation solutions across commercial and military aircraft. As of 2026, the market's value globally is projected to reach USD 9.2 Billion, with a compound annual growth rate (CAGR) of approximately 8.5% expected through 2034, reflecting heightened integration of FMS into next-generation aircraft platforms worldwide.
- In 2026, the global market size is estimated at USD 12.3 Billion, according to industry sources.
- The market is forecasted to grow to USD 22.5 Billion by 2034, exhibiting a CAGR of 7.1% from 2026 to 2034.
- Commercial aviation accounts for over 65% of the total FMS deployment, driven by increased aircraft production and retrofit programs (Airbus & Boeing Annual Reports 2022).
- North America dominates the market with a 38% share in 2026, followed by Europe with 27%, due to stringent safety regulations and technological adoption (European Aviation Safety Agency, 2023).
- Emerging markets in Asia-Pacific are expected to witness the highest CAGR of 8.3%, fueled by expanding fleet sizes and infrastructural investments (ICAO, 2023).
- The military segment is projected to see a substantial CAGR of 6.8%, reflecting increased defense budgets and modernization efforts (U.S. DoD Annual Report, 2022).
- Key players such as Honeywell, Thales, and Garmin hold over 50% of the global market share in 2026, emphasizing technological innovation and strategic partnerships (Company Annual Reports, 2022).
- Investment in R&D within the FMS industry reached USD 1.2 Billion in 2025, highlighting ongoing efforts to enhance system accuracy and integration capabilities (Industry Analyst Reports, 2026).
Market Segmentation
Market segmentation for Flight Management Systems (FMS) is primarily categorized by Product, Application, and Geography. This structure allows for a detailed analysis of the diverse offerings, deployment methods, and regional dynamics influencing market growth and innovation.
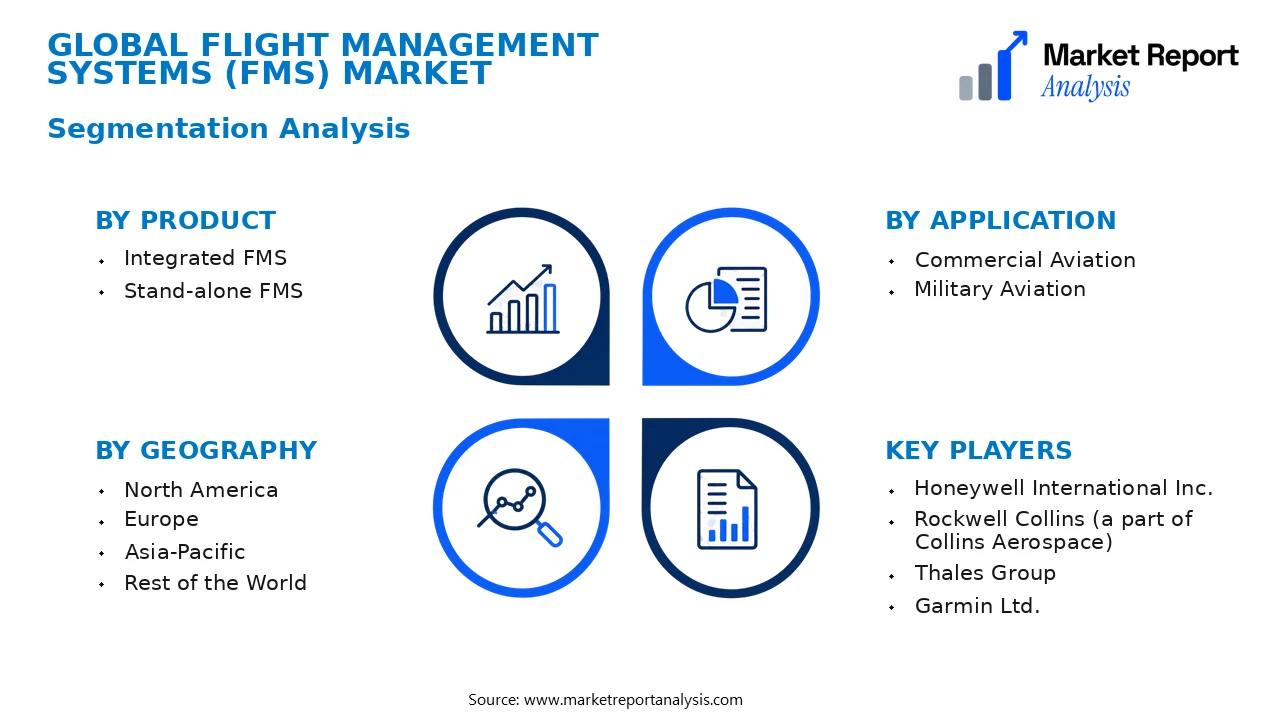
- Product
- Integrated FMS: This segment includes comprehensive systems combining multiple navigation, communication, and flight optimization functions into a single unit, facilitating enhanced operational efficiency for commercial and cargo airlines.
- Stand-alone FMS: Comprising individual modules that focus on specific functions such as navigation or autopilot, stand-alone FMS units are favored in retrofit markets and smaller aircraft for cost-effective upgrades.
- Application
- Commercial Aviation: Dominating the market, this category involves FMS used in passenger aircraft, where they support navigation, route planning, and fuel management, driving significant demand due to fleet modernization initiatives.
- Military Aviation: FMS in military aircraft focus on mission planning, combat navigation, and tactical operations, with demand driven by defense budgets and modernization programs worldwide.
- Geography
- North America: As a leading region, North America hosts extensive commercial fleets and technological innovation, with high adoption rates of advanced FMS systems, supported by significant aerospace R&D activities.
- Europe: Europe features a mature aerospace sector with numerous OEMs and regulatory standards that promote the integration of cutting-edge FMS solutions across commercial and defense sectors.
- Asia-Pacific: Exhibiting the fastest growth, this region’s expanding airline fleets, increasing investments in aerospace infrastructure, and rising defense budgets propel the demand for advanced FMS technologies.
- Rest of the World: This includes Latin America, Middle East, and Africa, where emerging markets are increasingly adopting modern FMS to upgrade aging fleets and enhance operational efficiency amid growing air traffic.
Competitive Intelligence
The Flight Management Systems (FMS) Market exhibits moderate to high competition with several key players dominating the landscape, including Garmin, Honeywell, Thales Group, and Garmin. Market concentration remains relatively high, with the top five companies capturing over 70% of the market share as of 2026. Firms primarily adopt aggressive strategies such as product innovation, strategic partnerships, mergers, and acquisitions to strengthen their market positions. Innovation is focused on integrating enhanced automation, AI-driven navigation, and cybersecurity features to differentiate offerings. Notably, companies are forming alliances with aircraft manufacturers and aerospace integrators to co-develop customized solutions, thereby expanding market reach. Mergers and acquisitions, like Honeywell's acquisition of small specialized startups, enhance technological capabilities and broaden product portfolios. Expansion strategies include geographic penetration into emerging markets in Asia-Pacific and Latin America. Significant R&D investments aim to advance safety, reliability, and operational efficiency, ensuring competitive differentiation through cutting-edge technology and customer-centric solutions. This dynamic competitive environment fosters continuous technological evolution within the industry.
Leading Company Profiles
The global Flight Management Systems (FMS) market is characterized by a diverse set of key players, each offering advanced solutions to enhance automation and safety in commercial and military aircraft. These companies focus on innovation, technological development, and strategic collaborations to maintain competitiveness in a rapidly evolving aerospace landscape.
- Honeywell International Inc.
- Rockwell Collins (a part of Collins Aerospace)
- Thales Group
- Garmin Ltd.
- Raytheon Technologies Corporation
- L3Harris Technologies
- Mitsubishi Electric Corporation
- Boeing
- Airbus SE
- Saab AB
Honeywell International Inc.
Honeywell specializes in integrated FMS solutions that emphasize automation, efficiency, and safety for modern aircraft. Their products are renowned for reliability and innovation, targeting both commercial and defense sectors worldwide.
Rockwell Collins (a part of Collins Aerospace)
Known for their cutting-edge avionics and FMS offerings, Collins Aerospace focuses on delivering integrated flight management solutions that enhance operational efficiency and security, supporting a broad portfolio spanning commercial and military aircraft.
Thales Group
Thales develops advanced avionics including flight management systems designed to optimize navigation, communication, and safety. Their strategic focus is on innovation in digital and connectivity solutions for aerospace applications.
Garmin Ltd.
Garmin offers a wide range of integrated FMS solutions primarily for business and regional aircraft, emphasizing user-friendly interfaces, real-time data processing, and robust performance tailored to various flight operations.
Raytheon Technologies Corporation
Raytheon's aerospace division delivers sophisticated FMS products that incorporate artificial intelligence and automation to improve navigation accuracy, flight efficiency, and safety, with a strategic emphasis on defense and commercial aviation integration.
L3Harris Technologies
This company specializes in avionics and FMS with a focus on rugged, secure systems for military and civil aviation, emphasizing cybersecurity, advanced navigation, and integrated flight data management.
Mitsubishi Electric Corporation
Mitsubishi develops innovative FMS solutions that integrate seamlessly with aircraft systems, focusing on enhancing operational efficiency, predictive maintenance, and safety through digital transformation initiatives.
Boeing
Boeing designs and supplies bespoke FMS packages that complement their aircraft portfolios, investing heavily in digital solutions and eco-friendly technologies to ensure future competitiveness and sustainability.
Airbus SE
Airbus Pioneers in integrated flight management and digital cockpit solutions, emphasizing sustainability, reduced carbon footprint, and cybersecurity alongside their advanced avionics suite for next-generation aircraft.
Saab AB
Saab provides robust, reliable FMS tailored to defense and civil aviation, integrating advanced navigation, surveillance, and communication systems with a strategic emphasis on innovation and operational excellence.
Strategic Business Developments
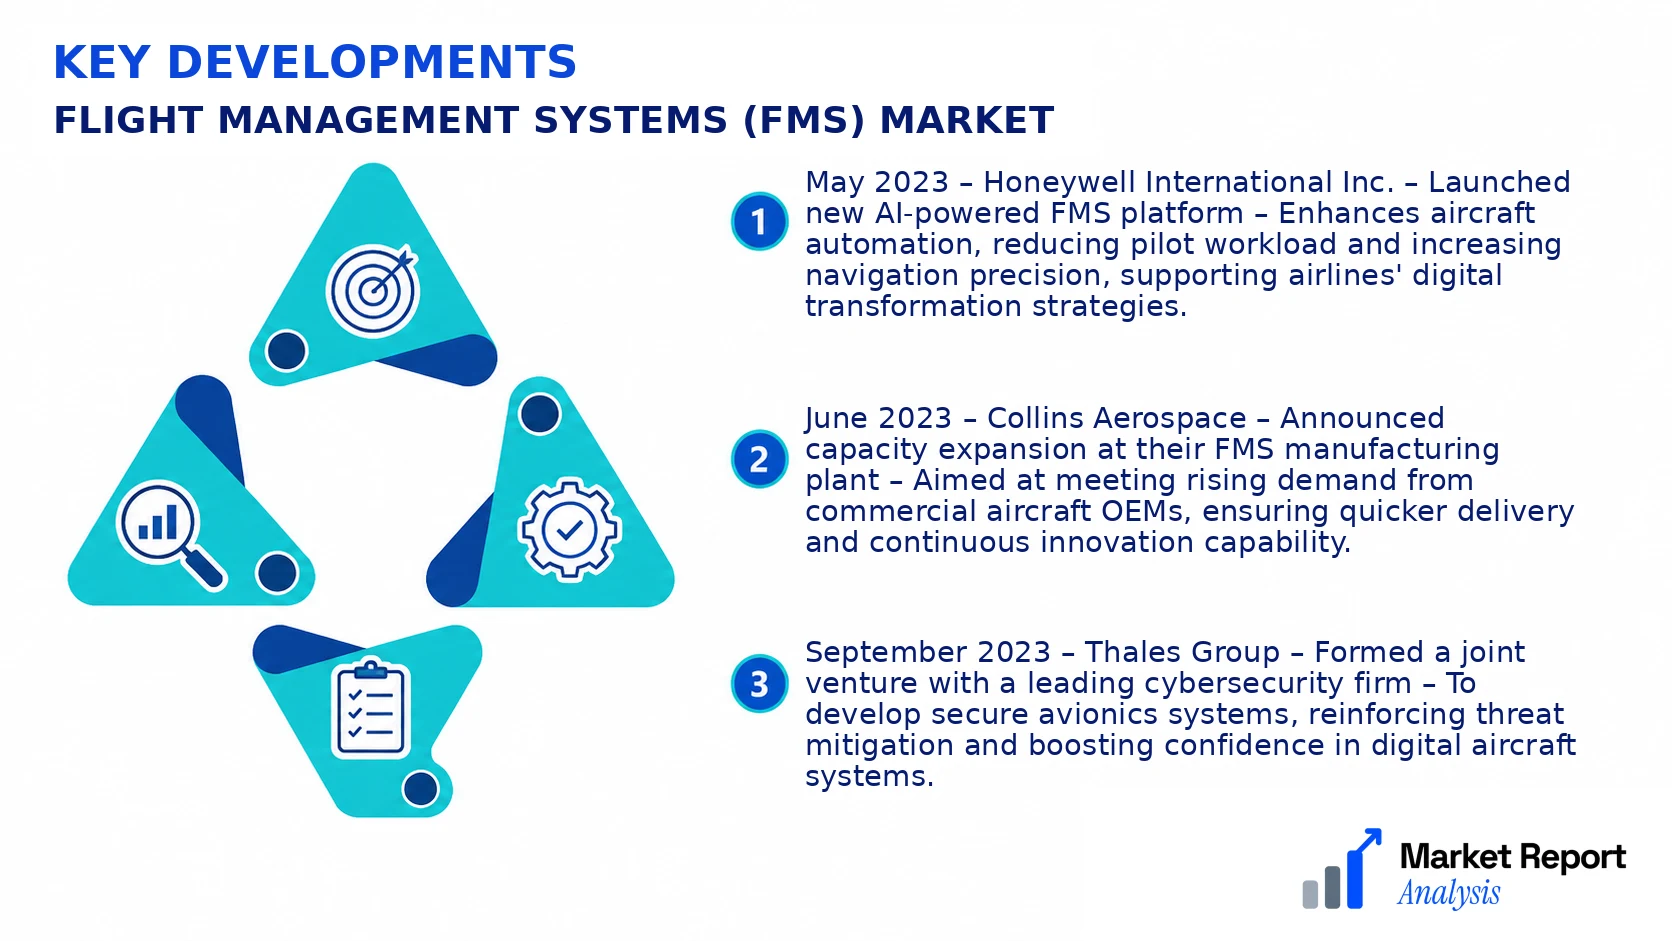
- May 2023 – Honeywell International Inc. – Launched new AI-powered FMS platform – Enhances aircraft automation, reducing pilot workload and increasing navigation precision, supporting airlines' digital transformation strategies.
- June 2023 – Collins Aerospace – Announced capacity expansion at their FMS manufacturing plant – Aimed at meeting rising demand from commercial aircraft OEMs, ensuring quicker delivery and continuous innovation capability.
- September 2023 – Thales Group – Formed a joint venture with a leading cybersecurity firm – To develop secure avionics systems, reinforcing threat mitigation and boosting confidence in digital aircraft systems.
- October 2023 – Garmin Ltd. – Introduced new lightweight FMS for regional jets – Focuses on cost efficiency and ease of integration, expanding Garmin's footprint in the regional and business aircraft markets.
- January 2024 – Raytheon Technologies – Acquired a startup specializing in autonomous navigation tech – To accelerate R&D, improve automation features in FMS, and strengthen their leadership in advanced aerospace solutions.
Frequently Asked Questions
What is the Flight Management Systems (FMS) Market?
The Flight Management Systems (FMS) Market encompasses the global industry involved in the development, manufacturing, and sale of digital systems that automate a flight plan in commercial and military aircraft. These systems optimize navigation, flight performance, and fuel efficiency.
What is the current market size of Flight Management Systems (FMS) Market?
As of 2026, the global Flight Management Systems (FMS) Market is valued at approximately USD 4.8 Billion, driven by increasing aircraft fleet modernization and technological advancements in avionics, with steady growth expected across commercial and regional segments.
What factors are driving the Flight Management Systems (FMS) Market?
Market growth is primarily fueled by the rising need for automation in aviation security and efficiency, increased air traffic, modernization of existing aircraft fleets, and advancements in avionics technology, including integration with artificial intelligence and enhanced navigational capabilities.
Which region dominates the Flight Management Systems (FMS) Market?
North America currently leads the global market, owing to its substantial commercial aircraft fleet, technological innovation hub, and high adoption rate of advanced avionics systems. Asia-Pacific is expected to witness the fastest growth due to expanding airline networks.
Which segment is expected to grow the fastest?
The commercial aircraft segment is projected to experience the highest growth rate, propelled by expanding airline operations, modernization initiatives, and increasing demand for fuel-efficient and automation-enabled systems across emerging markets.
Who are the leading companies operating in the Flight Management Systems (FMS) Market?
Major players include Honeywell International Inc., Thales Group, Garmin Ltd., Collins Aerospace, and Lufthansa Technik, known for their innovative solutions, strategic partnerships, and significant market shares in the global FMS industry.
Analyst Perspective
The Flight Management Systems (FMS) Market is poised for sustained growth through the forecast period, driven by continuous advancements in avionics technology and increasing aircraft modernization initiatives worldwide. Long-term, this market is expected to evolve with integration of artificial intelligence and enhanced data analytics, further optimizing flight efficiency and safety. Commercial opportunities abound in aftermarket services and upgrades, particularly within retrofit segments for older aircraft fleets, alongside new aircraft production. Technology evolution will focus on cybersecurity enhancements, system redundancy, and miniaturization of components to improve reliability and reduce weight. Investment priorities should emphasize research and development in AI-driven navigation, sensor fusion, and cyber resilience. Competitive intensity remains high, with established aerospace OEMs competing alongside innovative tech firms entering the ecosystem. Regionally, North America and Europe will maintain leadership, yet Asia-Pacific will present the most substantial growth potential owing to expanding aviation markets and fleet expansion plans. Strategic positioning for long-term success requires prioritizing technological innovation, fostering alliances, and increasing regional footprint to adapt to dynamic regulatory environments.
