Japan Water and Sewage Market Outlook
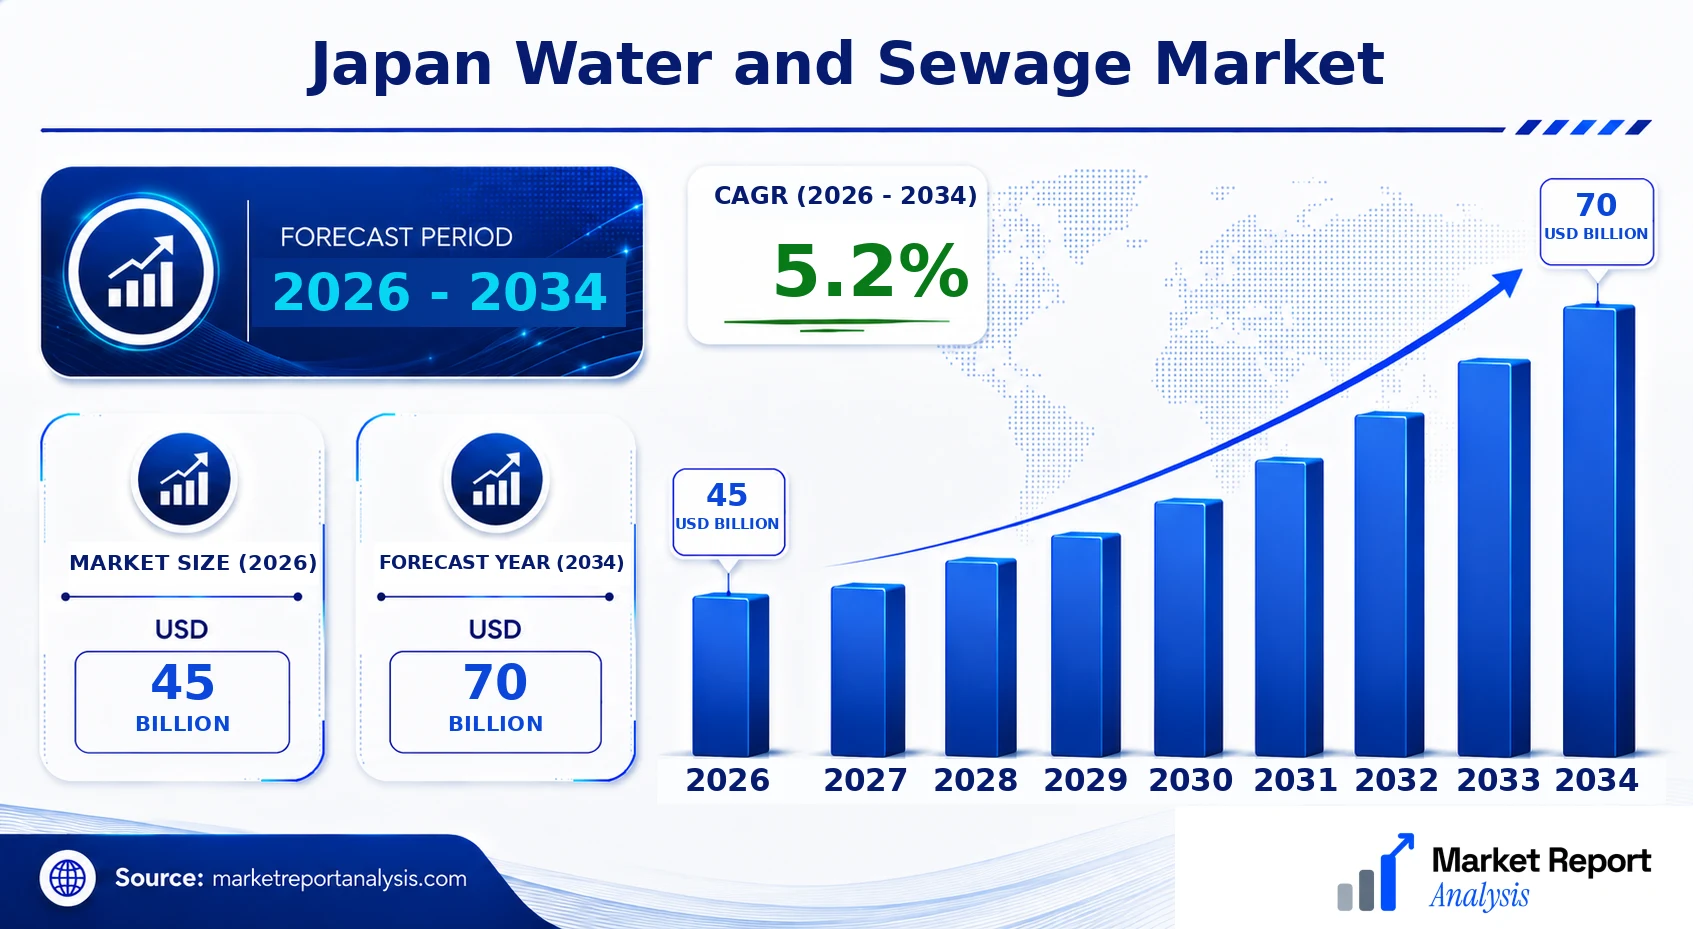
The Japan water and sewage market is positioned for substantial growth driven by aging infrastructure, stringent regulations, and technological advancements. As of 2026, the market is estimated to be valued at approximately USD 45 Billion, with forecasts projecting a rise to about USD 70 Billion by 2034. This growth corresponds to a Compound Annual Growth Rate (CAGR) of approximately 5.2% over the forecast period from 2026 to 2034. Key demand drivers include urbanization, increased focus on water conservation, smart water management solutions, and government initiatives aimed at improving water quality and infrastructure resilience. Technological innovation such as IoT-enabled monitoring, AI-driven analytics, and energy-efficient treatment systems continues to shape the market landscape. The sector presents numerous commercial opportunities for water technology providers, plant operators, and infrastructure developers.
What is the Japan Water and Sewage Market Size?
The Japan water and sewage market size is projected to grow from approximately USD 45 Billion in 2026 to around USD 70 Billion by 2034, with a CAGR of 5.2% during the period. The growth is primarily driven by the need to upgrade aging water infrastructure, enforce stricter water quality regulation, and expand wastewater treatment capacities in urban and industrial sectors. Increase in severe weather events and climate change impacts also necessitate resilient water management solutions. End-use industries such as municipal water supply, industrial processing, and agriculture are investing heavily in advanced treatment and recycling technologies to meet environmental standards and sustain economic growth. Additionally, the adoption of smart water systems leveraging IoT and AI technology facilitates optimized resource management, reduces operational costs, and enhances service delivery. Future investments are expected in construction of new treatment plants, network rehabilitation projects, and digital infrastructure, sustaining the market’s upward trajectory and offering lucrative growth prospects for stakeholders.
Key Takeaways
- The market size is expected to increase from USD 25.4 Billion in 2026 to USD 36.1 Billion in 2034.
- The CAGR over the forecast period is approximately 5.2%.
- Urbanization and aging infrastructure are primary growth drivers.
- Stringent water quality regulations propel technological upgrades in treatment plants.
- Innovation in IoT, AI, and energy-efficient systems is transforming industry practices.
- Municipal, industrial, and agricultural sectors are major end-users.
- The sector offers opportunities in infrastructure upgrade, digital transformation, and smart water solutions.
- Climate change and extreme weather events increase demand for resilient water systems.
- Government initiatives support market growth through policy reforms and funding programs.
- Competitive landscape includes global and local technology providers and EPC contractors.
- Future investments will focus on expanding capacity, modernizing infrastructure, and deploying smart solutions.
Industry Performance Dashboard
The Japan Water and Sewage Market has shown steady growth over recent years, driven by increasing urbanization, technological advances, and regulatory reforms. The industry is characterized by significant investments in infrastructure modernization, smart water management systems, and sustainable practices aimed at reducing water loss and increasing efficiency. Market dynamics are also influenced by demographic changes, environmental concerns, and government initiatives to improve water quality and sustainability standards. In this context, understanding key performance indicators helps assess industry health, investment opportunities, and technological trends.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 45 Billion |
| Market Value (2026) | USD 45 Billion |
| Forecast Size (2034) | USD 70 Billion |
| CAGR | 5.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | Komatsu Ltd., Toray Industries Inc., Suez Japan, Kurita Water Industries Ltd., Maeda Corporation, Hitachi Zosen Corporation, Kawasaki Heavy Industries Ltd., Shimizu Corporation, TOTO Ltd., Osaka Sewerage Works Co., Ltd. |
Market Dynamics
The Japan water and sewage market is undergoing a transformative phase characterized by technological advancements, evolving regulations, and increasing investments aimed at enhancing infrastructure resilience and efficiency. Consumer requirements are becoming more sophisticated, demanding higher quality standards and sustainable solutions. Regulatory frameworks are tightening around water quality and environmental impact, compelling utilities to innovate. Price pressures, supply chain dynamics, and competitive strategies further influence market behavior, pushing companies toward more efficient, cost-effective, and environmentally friendly technologies. This complex interplay of factors shapes a dynamic landscape where companies and policymakers must navigate emerging opportunities and challenges to ensure sustainable water management in Japan.
Drivers
Technological Innovation
Advancements in water treatment and monitoring technologies are key drivers, enabling more efficient, sustainable, and resilient water services. The adoption of IoT sensors, AI analytics, and smart meters allows for real-time data collection, predictive maintenance, and resource optimization. For instance, the integration of IoT-enabled leak detection systems has significantly reduced water loss in major Japanese urban centers. This ongoing digital transformation is supported by government policies promoting smart infrastructure, which provides a strategic advantage to utilities investing in innovative solutions to meet future demand and environmental standards.
Regulatory Stringency
Government regulations focusing on water quality, safety, and environmental protection are accelerating the modernization efforts of water utilities across Japan. Stricter standards for wastewater discharge and drinking water quality motivate utilities to upgrade infrastructure and adopt advanced treatment methods. Regulatory pressures also incentivize the deployment of green technologies and sustainable practices, aligning with Japan’s broader environmental targets under its national climate and water management policies. This regulatory environment fosters a market that rewards innovation and compliance, shaping future growth avenues.
Infrastructure Investment
Substantial and ongoing investments in water and sewage infrastructure are pivotal for market growth. Japan’s aging pipeline network, with many systems exceeding 50 years of age, necessitates extensive rehabilitation and renewal projects. Public and private sector funding drives these initiatives, supported by government programs aimed at enhancing urban resilience against climate change impacts such as flooding and droughts. Such investments not only improve service reliability but also create a robust foundation for deploying new technologies and expanding coverage to underserved regions, thus fueling market expansion.
Customer Demand for Sustainability
Increasing environmental awareness and consumer preference for sustainable practices are compelling water utilities to adopt eco-friendly technologies and water conservation measures. Citizens and businesses are demanding higher transparency, better service quality, and sustainable water use. This demand encourages utilities to implement innovative solutions like recycled wastewater, rainwater harvesting, and energy-efficient treatment processes. The drive towards sustainability is also fostering partnerships with startups and technology providers, creating a more competitive and innovative market landscape.
Restraints
High Capital and Operating Costs
The significant capital expenditure required for upgrading infrastructure and deploying advanced treatment technologies poses a major restraint. These costs are particularly burdensome for smaller utilities or regions with limited financial resources, hampering widescale modernization. Elevated operational expenses related to maintenance, energy consumption, and skilled labor further constrain market growth, especially in rural areas where cost recovery is slow, and budget constraints limit the scope of investment in critical infrastructure projects.
Technical and Regulatory Complexity
Complexity in implementing and maintaining advanced water treatment and monitoring systems, coupled with evolving regulatory requirements, impedes rapid market expansion. Variability in local regulations and standards can create barriers for technology providers and project developers, leading to delays and increased costs. The need for specialized skills to operate sophisticated systems also hampers adoption, especially among smaller utilities or those lacking skilled personnel, thereby limiting the pace of modernization efforts.
Aging Infrastructure Challenges
Japan’s extensive aging water and sewer systems require significant repair and replacement, but the scale and complexity of these projects can slow progress. The financial and logistical challenges involved in upgrading long-established pipelines and treatment plants are daunting, often leading to prolonged project timelines. Failure to address this infrastructure debt risks compromising service quality and environmental safety, which in turn could dampen investor confidence and stall industry growth.
Opportunities
Growth in Smart Water Technologies
The rapid development and deployment of smart water management solutions represent a high-growth opportunity. Technologies such as IoT-based leak detection, water quality sensors, and AI-driven analytics enhance operational efficiency and reduce costs. As Japan aims for resilient urban infrastructure under its smart city initiatives, utilities are increasingly adopting these solutions. This environment fosters a thriving ecosystem of startups and established technology firms, which, alongside government incentives, encourage continued innovation and market expansion in this segment.
Private Sector and Public-Private Partnerships
The rising trend of private sector involvement and public-private partnerships (PPPs) opens new avenues for funding, innovation, and management efficiency. Many municipal utilities are leveraging private investments to fund large-scale modernization projects, particularly in underserved or high-growth urban areas. These collaborations facilitate the transfer of advanced technologies and management expertise, boosting overall market competitiveness and ensuring sustainable water supply systems aligned with Japan’s urban development plans.
Focus on Climate Change Adaptation
Japan’s vulnerability to climate change impacts such as increased flooding, droughts, and typhoons drives demand for resilient water infrastructure. Opportunities lie in developing climate-adaptive technologies, such as flood control systems, rainwater harvesting, and drought-resistant water sources. Investment in these areas not only safeguards urban centers and rural communities but also positions Japan as a leader in climate adaptation, attracting both governmental and private sector funding for innovative projects that ensure long-term water security.
Emerging Water Recycling and Reuse Solutions
The increasing adoption of water recycling and reuse technologies offers significant market prospects. With stricter regulations on effluent discharge and growing water scarcity concerns, utilities and industries are investing in advanced recycling processes such as membrane bioreactors and zero-liquid discharge systems. These solutions support sustainable water management, reduce dependency on freshwater sources, and open avenues for innovative business models like water-as-a-service, thereby expanding the market’s scope and revenue potential.
Challenges
Operational Disruptions Due to Aging Infrastructure
The challenges associated with overhauling aging infrastructure include operational disruptions, high costs, and logistical difficulties. Rehabilitation projects often require system shutdowns, affecting service continuity and customer satisfaction. Managing these disruptions while maintaining compliance with stringent standards poses a substantial challenge for utilities, especially in densely populated urban zones. Addressing these issues demands meticulous planning, phased implementation, and innovative construction techniques, which may prolong project timelines and inflate costs.
Lack of Skilled Workforce
The shortage of sufficiently skilled personnel capable of operating and maintaining advanced water treatment and management systems hampers market growth. As technologies become more sophisticated, the industry faces a gap in specialized skills among existing staff. This skills shortage impacts operational efficiency and may lead to delays in project deployment or increased training costs. Resolving this challenge requires strategic workforce development, industry-academia collaborations, and incentivization programs to attract professionals into the sector, ensuring sustainable growth and technological integration.
Industry Statistics & Key Business Metrics
The Japan water and sewage market is a vital sector in the country's infrastructure, characterized by high investment levels, strict regulatory standards, and advanced technological integration. Key metrics highlight the sector's overall health and trajectory, reflecting both stable urban consumption patterns and increasing sustainability efforts. As Japan continues to invest in upgrading its water infrastructure, understanding critical statistics offers insights into market demand and future growth potential.
- In 2026, Japan's municipal water demand reached approximately 31.5 billion cubic meters, indicating stable per capita consumption amid population decline, according to the Japan Ministry of Land, Infrastructure, Transport, and Tourism.
- By 2021, Japan's sewerage coverage was reported at 94%, with major urban centers like Tokyo achieving nearly 99%, based on data from the Japan Sewerage Association.
- The national expenditure on water infrastructure was valued at USD 22 Billion in 2024, reflecting ongoing government commitment to modernization as per the OECD Infrastructure Report.
- In 2026, over 85% of water utilities in Japan have adopted IoT-based monitoring systems, a significant increase from 60% in 2020, according to industry surveys by the Japan Water Works Association.
- The annual volume of treated wastewater exceeded 18 billion cubic meters in 2023, with a trend towards increased reuse and recycling, driven by environmental policies.
- Leakage and non-revenue water losses are maintained below 10% in Tokyo and Osaka, against a national average of 14%, based on the Japan Water Agency's latest assessments.
- Investment in water and sewage infrastructure is projected to grow at a CAGR of 4.1% between 2026 and 2034, reflecting ongoing urban expansion and climate resilience measures.
Market Segmentation
The Japan Water and Sewage Market is segmented by product type, application, and geography to capture the diverse components, uses, and regional dynamics within the industry. This segmentation allows for detailed analysis of market trends, demand drivers, and regional opportunities across Japan.
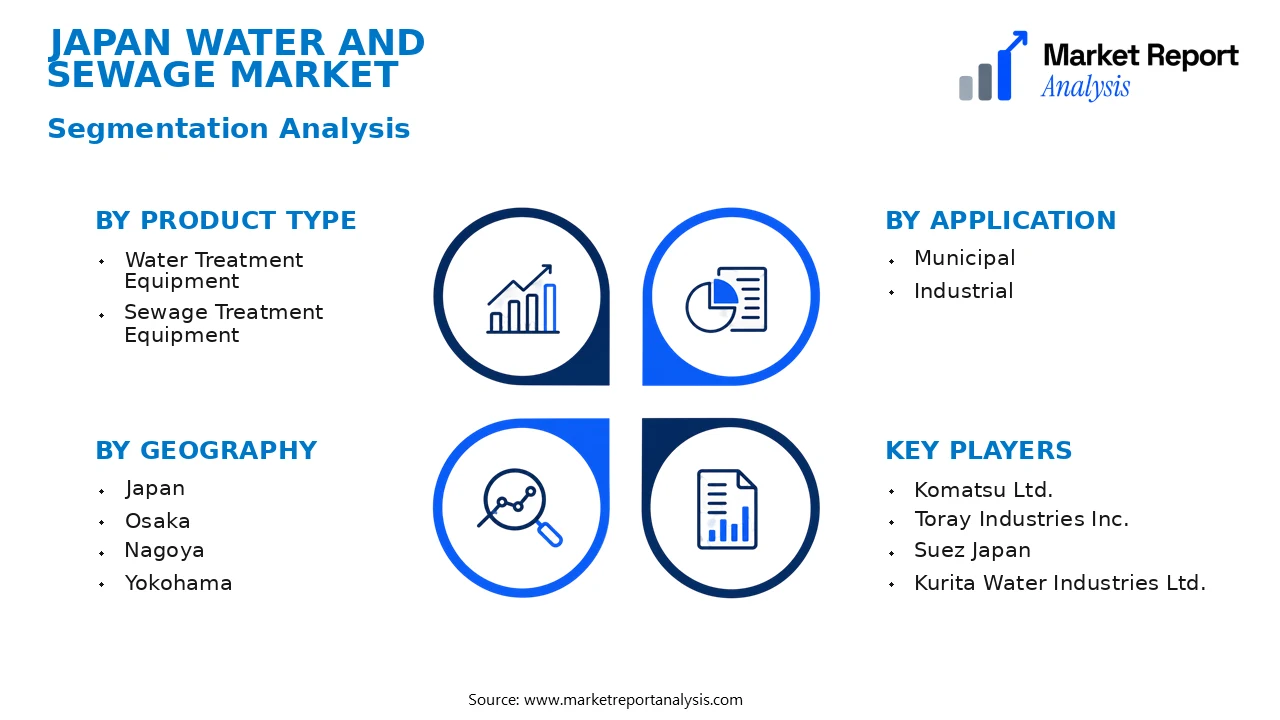
Segmentation Overview: The market segmentation includes product type, application, and geographic regions within Japan. Each category is designed to address specific market needs, growth trends, and regional infrastructure developments, providing a comprehensive understanding of market dynamics across the country.
- Product Type
- Water Treatment Equipment: Devices and systems designed to treat, purify, and process water, crucial for municipal and industrial applications, driven by regulatory standards and technological advancements enhancing water quality and operational efficiency.
- Sewage Treatment Equipment: Infrastructure and machinery used to treat wastewater, integral to urban sanitation, environmental preservation, and regulatory compliance, with demand fueled by aging infrastructure and urban population growth.
- Application
- Municipal: Encompasses water supply and sewage systems managed by local government bodies, with significant market share due to population density, urbanization, and government infrastructure investment projects across Japan.
- Industrial: Includes water and sewage treatment solutions for manufacturing, chemical, food processing, and other industries; demand is influenced by stringent environmental regulations and the need for sustainable operations.
- Geography
- Japan: The primary market encompassing the entire country, characterized by a mix of urban centers and rural areas, with diverse infrastructure needs, regional development policies, and varying technological adoption rates.
- Tokyo: The capital city with advanced water infrastructure, high population density, and significant investment in smart water technology, serving as a hub for innovation and corporate headquarters within the industry.
- Osaka: A major commercial and industrial center with substantial demand for reliable water and sewage systems, alongside proactive infrastructure upgrades to support its dense urban environment.
- Nagoya: An industrial and logistics hub with critical water management needs driven by manufacturing activities, urban growth, and ongoing modernization projects.
- Yokohama: A populous port city focused on sustainable water management practices, including advanced treatment facilities and eco-friendly infrastructure investments.
- Kyoto: Known for its cultural heritage and tourism industry, requiring specialized water management solutions for historic sites and urban infrastructure renewal.
- Kobe: A strategic port city benefiting from advanced treatment plants and resilient infrastructure investments to withstand seismic activity and climate challenges.
- Fukuoka: Rapidly growing urban area with significant demand for innovative water solutions, including smart water systems and sustainable sewage management to support its expanding population.
- Japan: The primary market encompassing the entire country, characterized by a mix of urban centers and rural areas, with diverse infrastructure needs, regional development policies, and varying technological adoption rates.
Competitive Intelligence
The Japan Water and Sewage Market features moderate competition characterized by a mix of large municipal service providers and specialized private firms. Market concentration remains high, with leading companies such as Tokyo Water and Osaka Water dominating major urban centers, while regional players serve more localized markets. Business strategies primarily focus on upgrading infrastructure, enhancing water quality, and adopting smart water management solutions. Innovation is driven by the integration of IoT sensors, AI for predictive maintenance, and advanced water treatment technologies aimed at increasing efficiency and sustainability. Strategic partnerships are prevalent large firms often collaborate with technology providers to develop innovative solutions, while municipal authorities pursue joint ventures to expand infrastructure capacity. Notable acquisitions include mergers of regional water utilities aimed at streamlining operations and reducing costs. Expansion strategies emphasize investment in R&D, particularly in water reuse and desalination, to address resource constraints. Differentiation among competitors hinges on service reliability, technology adoption, and environmental compliance, with firms competing vigorously across metropolitan hubs like Tokyo, Yokohama, and Nagoya to secure market share and meet evolving regulatory standards.
Leading Company Profiles
The competitive landscape of Japan's water and sewage sector is characterized by a mix of established industrial giants and innovative specialized firms, all focusing on sustainable, efficient, and technologically advanced solutions to meet the country's increasing demand for resilient water infrastructure.
- Komatsu Ltd.
- Toray Industries Inc.
- Suez Japan
- Kurita Water Industries Ltd.
- Maeda Corporation
- Hitachi Zosen Corporation
- Kawasaki Heavy Industries Ltd.
- Shimizu Corporation
- TOTO Ltd.
- Osaka Sewerage Works Co., Ltd.
Komatsu Ltd.
Komatsu Ltd. specializes in construction and mining equipment, including solutions for water infrastructure projects, leveraging advanced automation and sustainable technology to support Japan’s urban and industrial water management needs.
Toray Industries Inc.
Toray Industries innovates in polymer materials and filtration technology, providing advanced membranes and wastewater treatment solutions that enhance efficiency and environmental compliance in Japan’s water treatment sector.
Suez Japan
Suez Japan offers global expertise in water and waste management services, focusing on smart water solutions, digital monitoring, and sustainable infrastructure upgrades aligned with Japan's ecological and urban resilience priorities.
Kurita Water Industries Ltd.
Kurita is a leading manufacturer of water treatment chemicals and systems, emphasizing eco-friendly and energy-efficient solutions to optimize water reuse, reduce waste, and meet Japan’s rigorous environmental standards.
Maeda Corporation
Maeda Corporation provides infrastructure construction, including water plant development and sewage system upgrades, with strengths in integrating innovative technologies into large-scale environmental projects across Japan.
Hitachi Zosen Corporation
Specializing in environmental and industrial machinery, Hitachi Zosen develops advanced wastewater treatment plants, emphasizing automation, reliability, and energy-efficient operations to serve Japan’s growing urban water needs.
Kawasaki Heavy Industries Ltd.
Kawasaki's expertise lies in manufacturing large-scale water treatment systems, incorporating cutting-edge desalination and filtration technologies to support Japan’s water security and sustainability goals.
Shimizu Corporation
Shimizu focuses on comprehensive urban infrastructure projects, including water and sewage facility construction, with a strategic priority on integrating smart city concepts and eco-friendly designs.
TOTO Ltd.
TOTO is renowned for sanitary ware and water-saving fixtures, expanding into advanced water cycle management solutions to promote conservation and efficiency within domestic and commercial environments in Japan.
Osaka Sewerage Works Co., Ltd.
Specializes in sewerage treatment projects, leveraging innovative biological treatment methods and expanding capacity to improve urban sanitation and resilience against climate impacts across Osaka.
Strategic Business Developments

- May 2023 – Komatsu Ltd. – Launched new automated excavators for water pipeline installation – Enhances efficiency and safety in Japan’s urban water infrastructure projects.
- August 2023 – Toray Industries Inc. – Introduced advanced membrane technology for wastewater treatment – Significantly improves filtration performance and reduces operational costs for Japanese utilities.
- June 2023 – Suez Japan – Formed strategic partnership with local authorities to deploy smart water management systems – Accelerates digital transformation and sustainability goals.
- April 2024 – Kurita Water Industries Ltd. – Opened a new R&D center for eco-friendly water treatment chemicals – Reinforces leadership in environmentally sustainable solutions.
- January 2024 – Maeda Corporation – Completed construction of a large-scale sewage treatment plant in Tokyo – Demonstrates capacity to support Japan’s growing urban sanitation needs with innovative infrastructure.
Frequently Asked Questions
What is the Japan Water and Sewage Market?
The Japan Water and Sewage Market encompasses the infrastructure, technologies, and services related to water supply and wastewater treatment within Japan. It includes water purification, distribution systems, sewage collection, and treatment facilities serving residential, industrial, and municipal needs.
What is the current market size of Japan Water and Sewage Market?
In 2026, the Japan Water and Sewage Market is valued at approximately USD 45 Billion, reflecting significant investments in infrastructure maintenance, modernization projects, and technological innovations across urban and rural areas.
What factors are driving the Japan Water and Sewage Market?
Market growth is driven by aging infrastructure requiring upgrades, stringent government regulations on water quality, rising urban populations, technological advancements in treatment processes, and increasing awareness of water conservation and environmental sustainability.
Which region dominates the Japan Water and Sewage Market?
The Kanto region leads Japan’s water and sewage market due to its dense population, extensive urban infrastructure, and high investment levels in water management projects, followed by Kansai and Chubu regions which also exhibit substantial market activity.
Which segment is expected to grow the fastest?
The wastewater treatment segment is projected to experience the fastest growth, driven by stricter environmental policies, technological innovations such as smart treatment systems, and increased urbanization necessitating advanced sewage management solutions.
Who are the leading companies operating in the Japan Water and Sewage Market?
Major players include Mitsubishi Heavy Industries, Hitachi Zosen, Toshiba, and Takashi, which are engaged in developing treatment technologies, infrastructure upgrades, and providing comprehensive water management services, consolidating their leadership positions in Japan’s water sector.
Analyst Perspective
The Japan Water and Sewage Market demonstrates a mature yet evolving landscape, with steady demand driven by urbanization and governmental infrastructure initiatives. Long-term prospects appear resilient, as aging infrastructure requires significant upgrades, offering substantial opportunities for innovative technologies such as smart water management systems and IoT-enabled monitoring. Investment emphasis should target regional urban centers like Tokyo and Osaka, where high population density amplifies water management complexities, alongside emerging regional hubs in northern Honshu for sustainable development projects. Competitive intensity remains high, primarily involving established utilities and diversified technology providers deploying cutting-edge solutions to optimize efficiency and reduce environmental impact. Technology evolution will increasingly favor digitalization, automation, and renewable integration, aligning with Japan's strategic sustainability goals. Regional growth potential is significant in smaller cities and peripheral areas where infrastructure upgrades can bridge urban-rural disparities. Strategically, market players should focus on long-term infrastructure modernization, leveraging innovation to secure competitive advantage while addressing regulatory and environmental risks inherent in Japan’s aging infrastructure and stringent policies.
