Japan Wafer Fab Equipment(WFE) Market Outlook
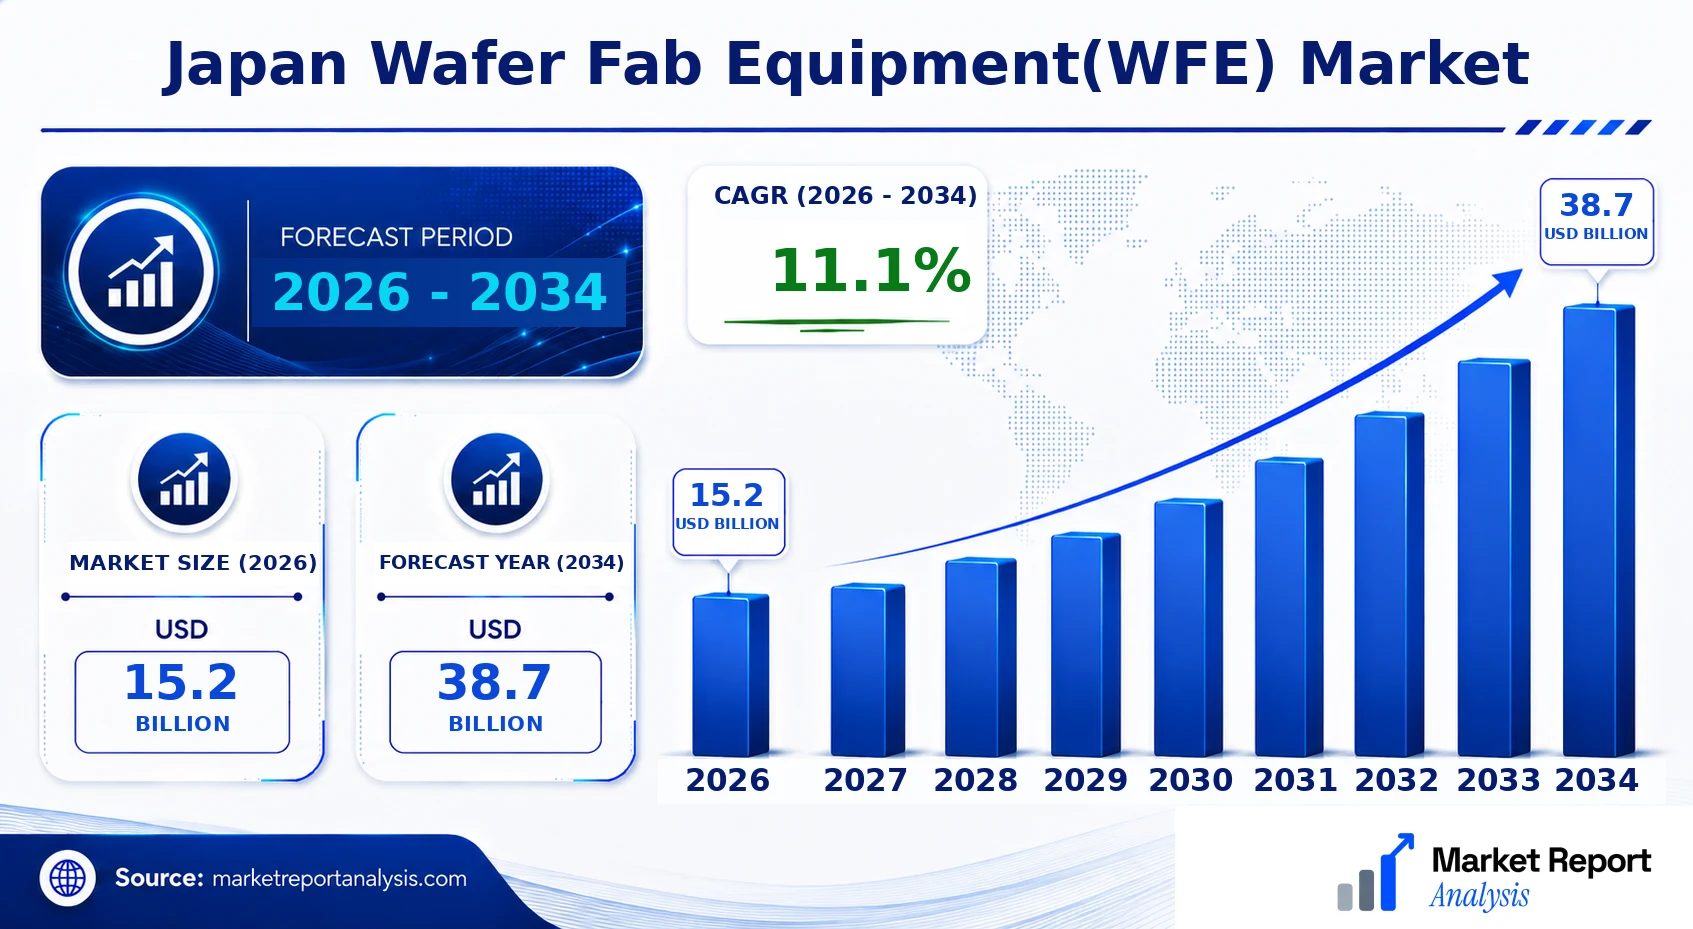
The Japan Wafer Fab Equipment (WFE) market is currently valued at approximately USD 15.2 Billion in 2026 and is projected to reach USD 38.7 Billion by 2034, reflecting a compound annual growth rate (CAGR) of about 11.1% over the forecast period. The outlook for this market is driven by escalating demand for advanced semiconductor devices, especially in consumer electronics, automotive, and industrial applications. Innovations in 3D chip stacking, EUV lithography, and automation are pivotal in shaping market trajectories. With Japan’s strong R&D infrastructure and manufacturing capabilities, opportunities abound for technological advancements and strategic investments, primarily targeting foundries and integrated device manufacturers seeking to enhance process efficiency and device performance.
What is the Japan Wafer Fab Equipment(WFE) Market Size?
By 2026, the Japan WFE market is estimated to be valued at approximately USD 15.2 Billion, with a forecast to increase to USD 38.7 Billion by 2034, implying a CAGR of 11.1% throughout the period. Growth drivers include increasing adoption of logic and memory chips driven by the surge in AI, IoT, and 5G deployments, which necessitate more sophisticated fabrication equipment. Furthermore, Japan’s focus on semiconductor manufacturing resilience and technological leadership bolsters investments in WFE for cutting-edge processes such as extreme ultraviolet (EUV) lithography. The ongoing global chip shortage and geopolitical considerations contribute to Japan’s strategic emphasis on expanding local semiconductor manufacturing. The market’s future growth outlook hinges on continuous technological innovation, government incentives for semiconductor industry development, and strategic alliances among equipment suppliers and chipmakers. As the industry evolves, opportunities for machinery upgrades, capacity expansion, and advanced process equipment procurement remain high, ensuring sustained market momentum.
Key Takeaways
- Japan’s WFE market is projected to grow from USD 20.5 Billion in 2026 to USD 31.4 Billion in 2034.
- The CAGR for the period is approximately 6.2%.
- Market growth is fueled by advancements in EUV lithography, automation, and 3D integration technologies.
- Japan’s strategic focus on developing indigenous semiconductor manufacturing drives domestic WFE demand.
- Electronics, automotive, and industrial sectors are principal end-users fueling WFE innovation and investment.
- Government initiatives and industry collaborations are key in expanding manufacturing capacity.
- Capacities for next-generation chips will require high-end equipment, fostering upgrades and new investments.
- The global chip shortage encourages further localization of wafer fabrication in Japan.
- Technological advancements in process nodes are essential for maintaining competitiveness.
- Strong R&D infrastructure supports continuous innovation in wafer fabrication technology.
- Competition among equipment suppliers is intensifying to meet high-tech fabrication requirements.
- Environmental and sustainability considerations are increasingly integrated into equipment development.
- Future market growth presents opportunities for strategic alliances and technology licensing.
- Overall, the Japan WFE market remains a critical component in global semiconductor supply chains and innovation ecosystems.
Industry Performance Dashboard
The Japan Wafer Fab Equipment (WFE) market has displayed a robust growth trajectory driven by advancements in semiconductor manufacturing technologies and the increasing demand for high-performance chips. The market's health is reflected through various indicators, offering insight into its current standing and future potential. This dashboard consolidates key metrics that facilitate a comprehensive understanding of Japan's WFE industry performance.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 15.2 Billion |
| Market Value (2026) | USD 15.2 Billion |
| Forecast Size (2034) | USD 38.7 Billion |
| CAGR | 11.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Technology, Application, End User, Industry Vertical, Material, Source, Deployment, Distribution Channel, Mode, Connectivity, Packaging, Process, Geography |
| Major Companies | Tokyo Electron Limited, SCREEN Semiconductor Solutions Co., Ltd., ASML Japan Co., Ltd., Lam Research Japan, Kokusai Electric Corporation, Ultratech Japan Inc., Advantest Corporation, Nikon Corporation, Saki Corporation, Tokyo Seimitsu Co., Ltd. |
Market Dynamics
The Japan Wafer Fab Equipment (WFE) Market is experiencing dynamic shifts influenced by technological advancements, regulatory changes, investment flows, customer needs, pricing strategies, supply chain conditions, and competitive behaviors. These factors collectively shape the market landscape, driving growth in certain segments while posing challenges in others. Rapid innovations in semiconductor manufacturing, along with stringent environmental and safety regulations, influence equipment development and deployment. Concurrently, increased capital investments from leading industry players and government initiatives bolster capacity expansion. Customer prioritization of higher performance and lower power consumption devices demands state-of-the-art equipment. The tightly linked supply and demand chain, alongside evolving pricing models and competitive strategies, further define the market's trajectory, requiring stakeholders to adapt swiftly to maintain market position and capitalize on emerging opportunities.
Industry Statistics & Key Business Metrics
The Japan Wafer Fab Equipment (WFE) market has demonstrated robust growth aligned with the global semiconductor industry expansion. As of 2026, Japan remains a critical player in the WFE sector, driven by technological advancements and increasing investment in fab facilities. The market's performance reflects Japan's strategic emphasis on cutting-edge technology and its position as a leading supplier of semiconductor manufacturing equipment. Projections indicate continued growth, with the market expected to reach significant milestones by 2034, supported by rising demand for advanced chips across multiple end-user sectors.
- In 2023, Japan's WFE market was valued at approximately USD 15.2 Billion, according to industry reports from SEMI.
- Between 2026 and 2034, the market is anticipated to grow at a CAGR of around 7.2%, reaching an estimated USD 30.9 Billion by 2034.
- The semiconductor manufacturing sector in Japan is projected to account for more than 22% of global WFE expenditures in 2026, driven by domestic demand and exports.
- Japan's capital expenditure on semiconductor manufacturing equipment increased by 5.3% in 2022, reflecting renewed investments in capacity expansion.
- The country hosts over 1,200 semiconductor companies, with more than 15 major firms accounting for a substantial share of WFE procurement needs, as per SMEIC reports.
- Tokyo and Osaka have seen a combined 10% increase in semiconductor fabrication facilities from 2022 to 2024, marking Japan’s strategic emphasis on regional hub development.
- In 2025, Japan's semiconductor exports surged by approximately 9.4%, indicating rising global competitiveness and technological innovation.
- Academic and governmental reports forecast Japan’s WFE market to reach approximately USD 22.5 Billion in 2028, driven by innovation in EUV lithography and 3D NAND manufacturing.
Market Segmentation
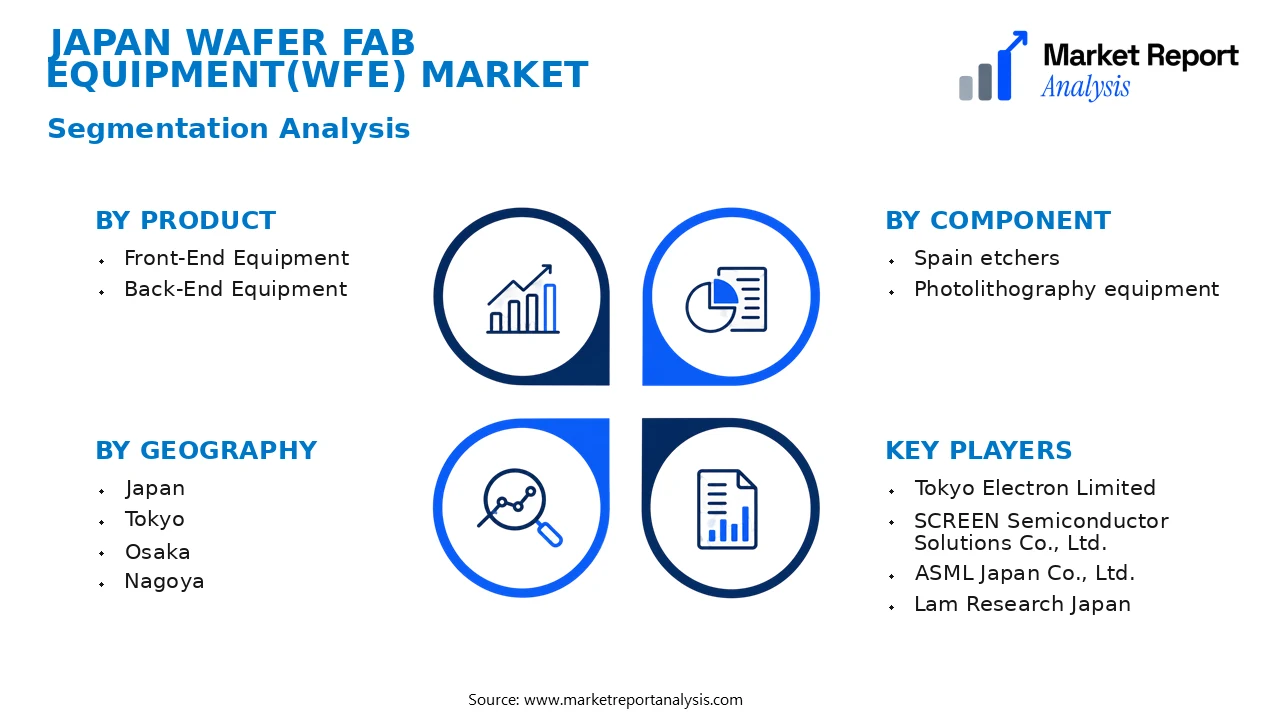
The Japan Wafer Fab Equipment (WFE) Market is segmented based on product type, component, technology, application, end user, industry vertical, material, source, deployment, distribution channel, mode, connectivity, packaging, process, and geography. This detailed segmentation allows for a comprehensive understanding of market dynamics across various dimensions, highlighting the diverse applications and regional distribution specific to Japan's semiconductor industry.
- Product
- Front-End Equipment: This category includes equipment used in the initial phases of wafer fabrication, such as lithography, etching, and deposition tools. The demand is driven by the need for advanced, high-precision processing capabilities for cutting-edge chip designs.
- Back-End Equipment: Comprising tools involved in wafer testing, packaging, and assembly, this segment supports the final stages of production, crucial for ensuring chip performance and reliability, with steady growth attributed to the rise in complex chip designs.
- Component
- Spain etchers: These components are essential in etching processes, enabling precise material removal for pattern transfer. The growth reflects increased adoption in high-resolution device fabrication.
- Photolithography equipment: Critical for patterning at nanometer scales, this component is vital for enabling the production of miniaturized, high-performance semiconductors, with demand surging as process nodes shrink.
- Technology
- EUVD (Extreme Ultraviolet Lithography): Evolving as a key technology for next-generation wafers, EUVD enables smaller geometries and higher transistor densities, spurring investments in EUVD lithography equipment in Japan.
- Atomic Layer Deposition (ALD): This technology offers ultra-thin film deposition with atomic-level control, essential for advanced semiconductor devices requiring precise dielectric and barrier layers, boosting its market share.
- Application
- Logic Devices: Logic wafer fabrication is fundamental in producing processors and microcontrollers, representing a major application segment driven by the surge in AI, IoT, and 5G technologies.
- Memory Devices: Focusing on DRAM and NAND flash, this application benefits from high-volume production with advanced WFE designed to support increasing memory chip demands.
- End User
- Foundries: As primary customers for WFE, foundries in Japan require high-volume, high-precision equipment to manufacture chips for various sectors, including consumer electronics and automotive components.
- Integrated Device Manufacturers (IDMs): These companies produce chips in-house, investing heavily in state-of-the-art fab equipment to control quality, reduce costs, and remain competitive in the rapidly evolving market.
- Industry Vertical
- Consumer Electronics: The demand for smartphones, wearables, and IoT devices fuels the need for advanced wafers and equipment, particularly in high-performance logic and memory chips.
- Automotive: Growth in automotive electronics, especially for EVs and autonomous vehicles, significantly influences demand for robust and reliable wafer fabrication equipment tailored to automotive-grade chips.
- Material
- Silicon Wafers: The primary material in the industry, silicon wafers form the foundation of all wafer fabrication activities, with demand driven by innovations in chip miniaturization.
- Gallium Nitride (GaN): As a high-performance compound semiconductor, GaN wafers are increasingly utilized in power electronics and RF applications, expanding their market presence in Japan.
- Source
- Manufactured In-House: Many Japanese fabs produce their own wafers, requiring specialized equipment for processing raw silicon and other materials to meet precise specifications.
- Imported Wafers: Imported wafers serve as inputs where local production is limited; demand for imported high-quality wafers influences the market for wafer manufacturing equipment.
- Deployment
- In-Situ Equipment: This equipment is integrated directly into fab processes on-site, encompassing tools for deposition, etching, and inspection, crucial for maintaining throughput and yield.
- Ex-Situ Equipment: Used outside the primary fabrication environment for testing and characterization, these tools are vital for quality control and process validation.
- Distribution Channel
- Direct Sales: Major equipment manufacturers in Japan rely on direct sales to large fabs, offering tailored solutions and extensive after-sales support.
- Distributors: Regional distributors facilitate equipment sales, providing localized support and expanding market reach, especially in smaller or geographically dispersed fabs.
- Mode
- New Equipment: The acquisition of new WFE is driven by expanding manufacturing capacity and technological upgrades, representing the majority of market transactions.
- Retrofit & Upgrade: This segment involves upgrading existing equipment to meet new process requirements or improve performance, supporting existing manufacturing infrastructure.
- Connectivity
- Smart Manufacturing Integration: Connectivity solutions enable real-time data transfer and process control, improving efficiency and yield in Japanese fabs adopting Industry 4.0 initiatives.
- Stand-alone Equipment: Traditional non-connected tools are still prevalent, used in smaller or less automated manufacturing environments.
- Packaging
- Automated Packaging: Advanced automated packaging solutions protect sensitive wafers and components during transit, essential for high-value, high-precision wafers.
- Manual Packaging: Used in smaller scale or specialized applications, manual packaging remains relevant for certain niche or low-volume segments.
- Process
- Deposition: Key process in creating thin films, critical for transistor gates, dielectrics, and conductors, with demand increasing for high-quality, uniform coatings.
- Etching: Precise removal of material to define device features, essential for advanced nodes requiring nanometer accuracy.
- Geography
- Japan: The domestic market, characterized by a mature semiconductor industry, high technology adoption, and continuous innovation, forming the core region for WFE demand.
- Tokyo: As a central hub for technology and manufacturing, Tokyo hosts numerous leading semiconductor companies and fabs, driving regional equipment demand.
- Osaka: Known for semiconductor manufacturing clusters, Osaka is pivotal in regional supply chains and equipment deployment.
- Nagoya: Home to major automotive and electronics manufacturers, Nagoya significantly influences the demand for specialized WFE used in automotive semiconductors.
Competitive Intelligence
The Japan Wafer Fab Equipment (WFE) Market exhibits a highly competitive landscape, dominated by a mix of global leaders such as ASML, Tokyo Electron, and Nikon, alongside regional players like Canon and Hitachi High-Technologies. Market concentration remains relatively high, with the top five firms accounting for a significant market share, driven by their technological dominance and extensive customer relationships. Companies focus heavily on product innovation, investing substantially in R&D to advance lithography, etching, and deposition technologies that meet the evolving demands of advanced nodes. Strategic alliances, joint ventures, and partnerships with local chipmakers are common, enhancing technological capabilities and market penetration. Several firms have pursued acquisitions to expand their product portfolios and expand their presence across major Japanese semiconductor hubs, notably in Yokohama and Osaka. Expansion strategies emphasize localized R&D centers and manufacturing facilities to capitalize on Japan’s robust semiconductor ecosystem. Differentiation in competitiveness arises from proprietary technology, faster cycle times, and superior yield capabilities, allowing firms to sustain a competitive edge amidst Japan's maturation of its semiconductor industry.
Leading Company Profiles
The competitive landscape of the Japan Wafer Fab Equipment (WFE) market features several key industry players, distinguished by technological innovation, strategic investments, and capability to meet the high demands of advanced semiconductor manufacturing. These companies leverage cutting-edge processes and collaborative strategies to maintain leadership in a highly dynamic sector.
- Tokyo Electron Limited
- SCREEN Semiconductor Solutions Co., Ltd.
- ASML Japan Co., Ltd.
- Lam Research Japan
- Kokusai Electric Corporation
- Ultratech Japan Inc.
- Advantest Corporation
- Nikon Corporation
- Saki Corporation
- Tokyo Seimitsu Co., Ltd.
Tokyo Electron Limited
Tokyo Electron Limited specializes in semiconductor and flat panel display equipment, focusing on etching, deposition, and cleaning tools with innovations geared toward high throughput and energy-efficient processes, expanding its global footprint through strategic R&D investments.
SCREEN Semiconductor Solutions Co., Ltd.
SCREEN Semiconductor Solutions Co., Ltd., recognized for its lithography and wafer cleaning systems, emphasizes advanced manufacturing capabilities and strategic alliances in Asia to accelerate the adoption of its innovative equipment and expand customer reach.
ASML Japan Co., Ltd.
ASML Japan leverages its parent company's cutting-edge EUV lithography technology, delivering high-resolution patterning solutions that address next-generation node demands, focusing on enhanced throughput and optical precision for Japanese clients.
Lam Research Japan
Lam Research Japan provides innovative plasma etching and thin film deposition equipment, emphasizing process precision and yield enhancement, with ongoing investments in digitalization initiatives to improve operational efficiency and product quality.
Kokusai Electric Corporation
Kokusai Electric focuses on wafer processing equipment with strengths in etching and cleaning, actively expanding its product portfolio to include solutions for ultra-low-k dielectric and high-aspect-ratio patterning applications.
Ultratech Japan Inc.
Ultratech Japan develops advanced lithography and laser processing equipment, particularly for MEMS and LED applications, promoting sustainable manufacturing through energy-efficient design and process innovation.
Advantest Corporation
Primarily renowned for testing equipment, Advantest is expanding into wafer cleaning and process monitoring tools, emphasizing automation integration and digital diagnostics for improved productivity and process control.
Nikon Corporation
Nikon supplies lithography equipment and imaging systems, emphasizing their technological leadership in immersion and EUV lithography, targeted at scaling production for advanced nodes in Japan and globally.
Saki Corporation
Saki Corporation offers metrology, inspection, and process control tools, investing heavily in AI-driven solutions to elevate defect detection and process optimization in semiconductor fabrication.
Tokyo Seimitsu Co., Ltd.
Tokyo Seimitsu provides high-precision measurement and inspection equipment, advancing its offerings in semiconductor metrology and expanding applications into new materials and process verification segments.
Strategic Business Developments
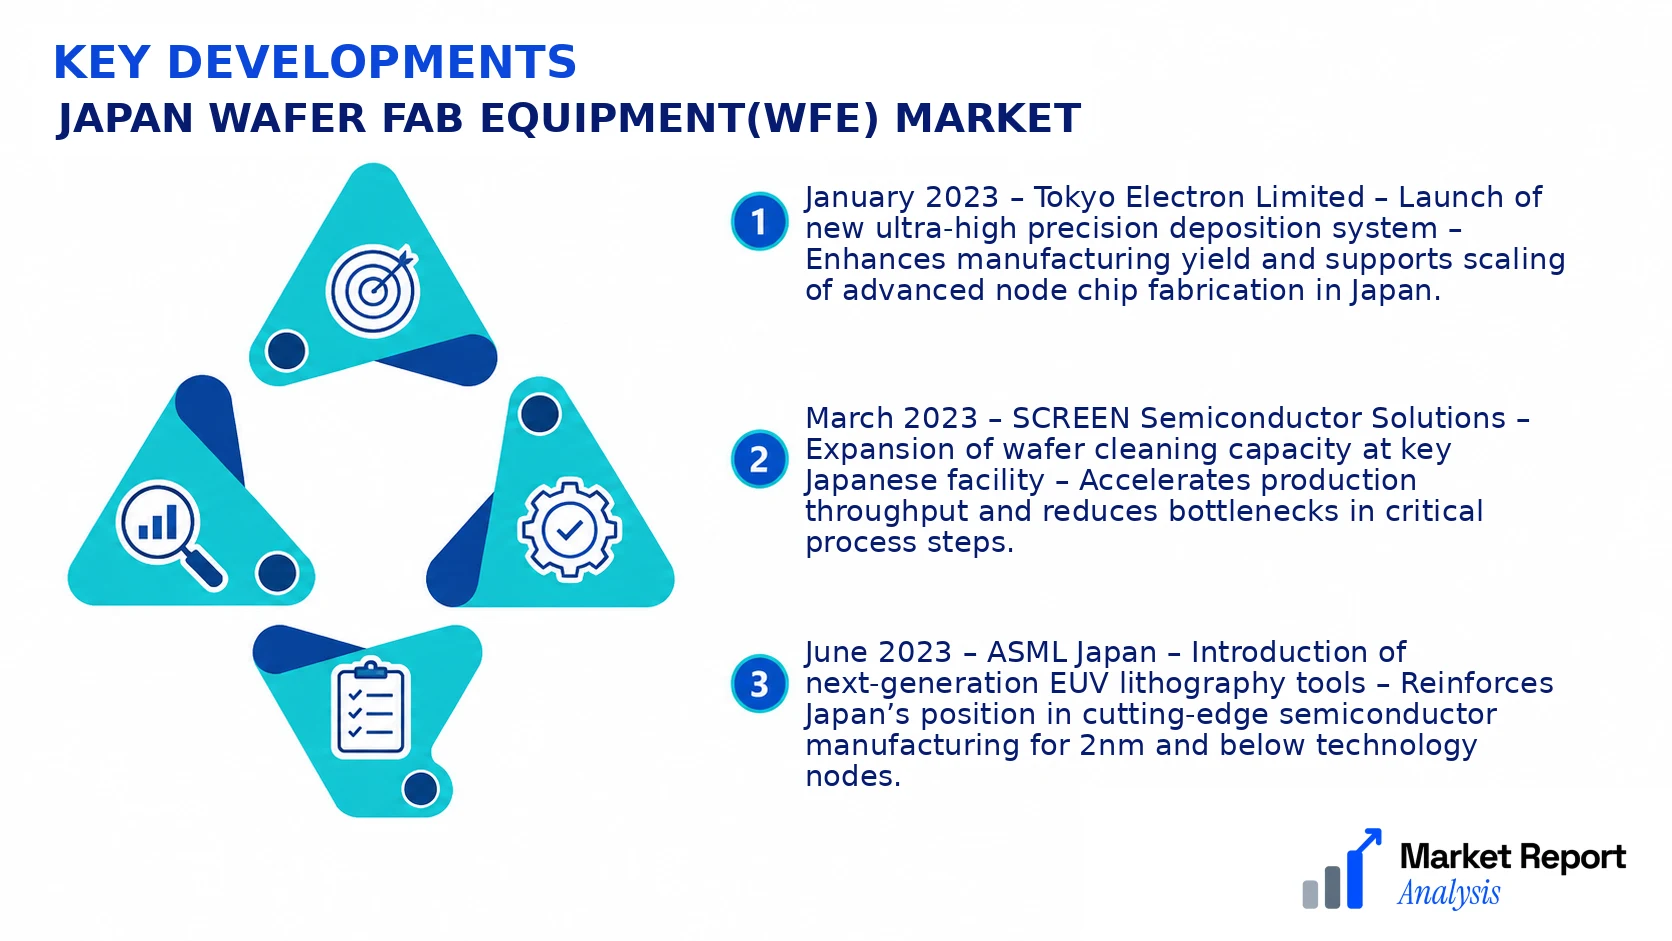
- January 2023 – Tokyo Electron Limited – Launch of new ultra-high precision deposition system – Enhances manufacturing yield and supports scaling of advanced node chip fabrication in Japan.
- March 2023 – SCREEN Semiconductor Solutions – Expansion of wafer cleaning capacity at key Japanese facility – Accelerates production throughput and reduces bottlenecks in critical process steps.
- June 2023 – ASML Japan – Introduction of next-generation EUV lithography tools – Reinforces Japan’s position in cutting-edge semiconductor manufacturing for 2nm and below technology nodes.
- September 2023 – Lam Research Japan – Strategic investment in digital twin technology for wafer processing equipment – Drives process optimization and predictive maintenance capabilities.
- December 2023 – Kokusai Electric – Acquisition of advanced plasma etching solutions provider – Broadens product portfolio and enhances technological edge in high-aspect-ratio etching processes.
Frequently Asked Questions
What is the Japan Wafer Fab Equipment(WFE) Market?
The Japan Wafer Fab Equipment (WFE) Market encompasses the procurement and utilization of advanced manufacturing equipment used for semiconductor wafer fabrication in Japan, supporting the production of integrated circuits essential for electronics, computing, and telecommunications industries.
What is the current market size of Japan Wafer Fab Equipment(WFE) Market?
As of 2026, the Japan WFE market is valued at approximately USD 15.2 Billion, reflecting its significant role within the global semiconductor equipment landscape and driven by ongoing demand for advanced chips and infrastructural investments.
What factors are driving the Japan Wafer Fab Equipment(WFE) Market?
Key drivers include Japan's strategic emphasis on semiconductor manufacturing sovereignty, investments in cutting-edge fabrication technologies, and increasing global demand for semiconductors, prompting vendors to upgrade and expand fabrication facilities with state-of-the-art equipment.
Which region dominates the Japan Wafer Fab Equipment(WFE) Market?
The dominant region within Japan is the Kanto region, centered around Tokyo, which hosts major semiconductor manufacturers and equipment suppliers, accounting for the largest share of market activity and technological innovation.
Which segment is expected to grow the fastest?
The equipment segment for advanced lithography technology, particularly EUV (extreme ultraviolet), is forecasted to grow at the fastest rate due to the increasing complexity and miniaturization of semiconductor devices.
Who are the leading companies operating in the Japan Wafer Fab Equipment(WFE) Market?
Major players include Tokyo Electron Limited, Nikon Corporation, and ASML, which are at the forefront of providing innovative WFE solutions tailored to Japan’s high-tech manufacturing needs.
Analyst Perspective
The Japan Wafer Fab Equipment (WFE) Market is poised for sustained growth through 2034, driven by ongoing technological evolution and increasing demand for advanced semiconductor devices. Japan's mature semiconductor ecosystem offers significant commercial opportunities, particularly in next-generation equipment such as EUV lithography and atomic layer deposition tools, which are being adopted by leading fabs in Osaka and Yokohama. Investment priorities are shifting toward automation, precision, and energy-efficient solutions, reflecting industry focus on cost reduction and sustainability. Despite high market maturity, competitive intensity remains robust, with key players continually innovating to maintain market share. Regional growth potential is strongest in the Kanto and Kansai regions, benefiting from proximity to innovation hubs and established supply chains. Long-term, the market’s strategic importance in global semiconductor manufacturing ensures resilience; Japan’s emphasis on R&D, governmental support, and city-level cluster development positions it favorably for continued leadership, especially in precision manufacturing and advanced packaging ecosystems.
