Japan Contaminant Remediation Market Outlook
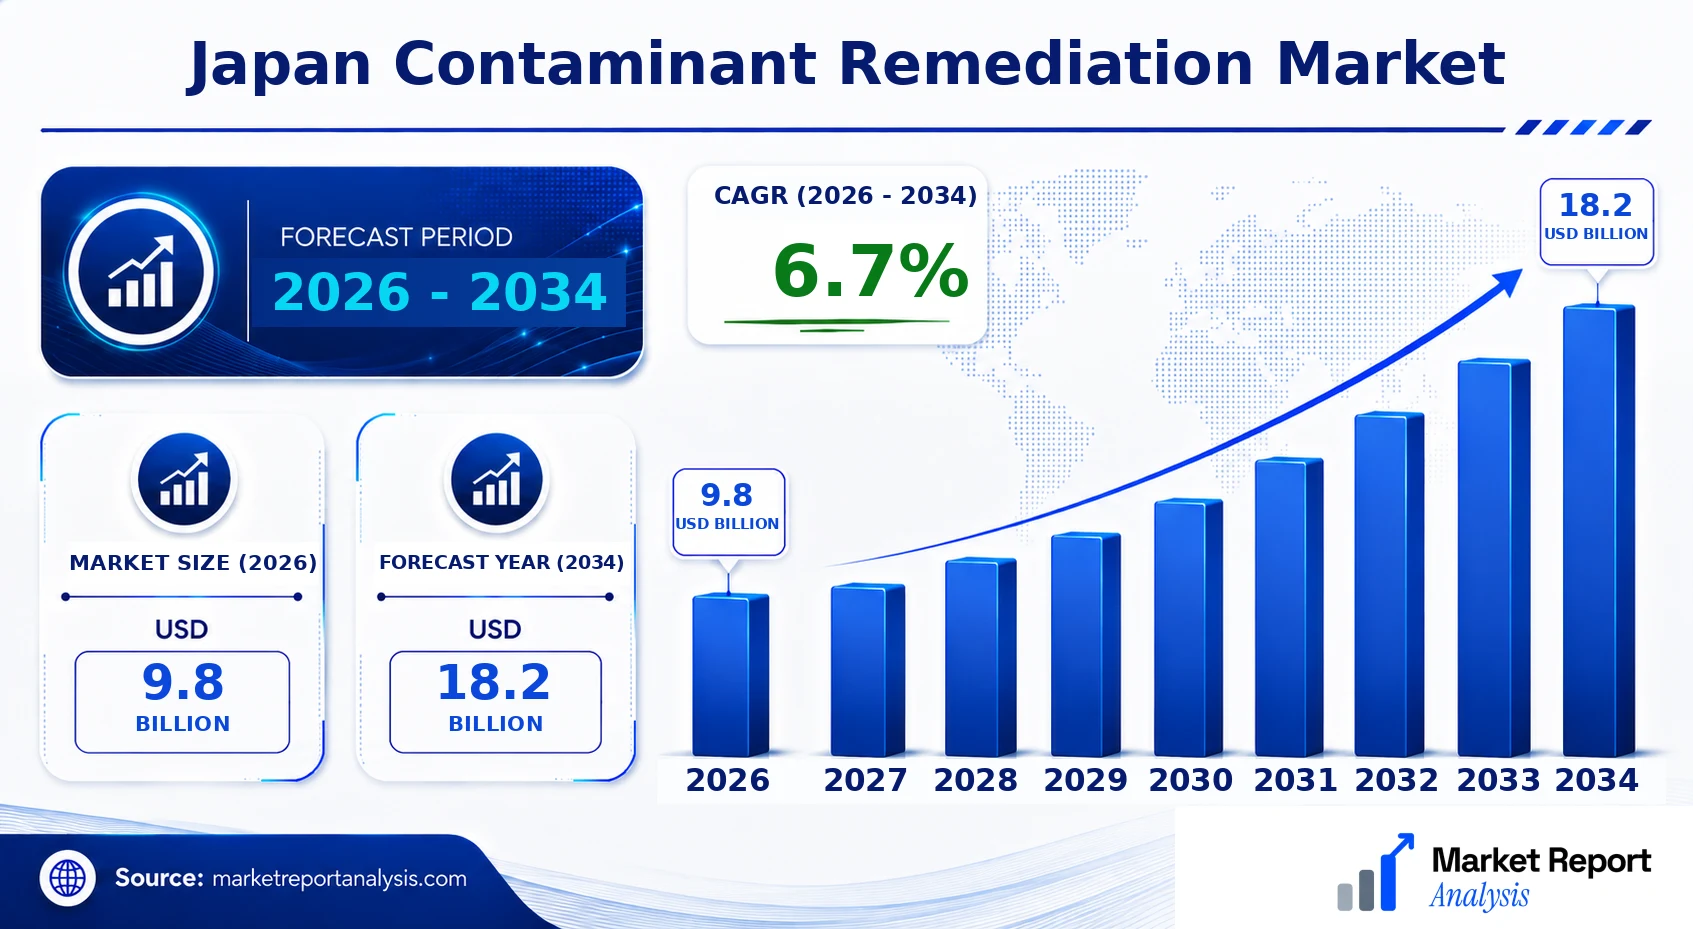
The Japan Contaminant Remediation Market is currently valued at approximately USD 9.8 Billion in 2026 and is projected to reach around USD 18.2 Billion by 2034. This growth corresponds to a Compound Annual Growth Rate (CAGR) of approximately 6.7% over the forecast period of 2026 to 2034. The principal demand drivers include increasing industrial pollution, stricter environmental regulations, and rising public awareness of health impacts associated with contaminants. Technological advancements, especially in bioremediation and nanotechnology-based solutions, are fueling market growth. Additionally, government initiatives aimed at sustainable development and environmental protection create significant commercial opportunities for market players to innovate and expand their offerings in both urban and industrial sectors, thus shaping a promising landscape for investment and development in contaminant remediation technologies throughout Japan.
What is the Japan Contaminant Remediation Market Size?
As of 2026, the Japan Contaminant Remediation Market is valued at around USD 9.8 Billion, and it is forecasted to grow to approximately USD 18.2 Billion by 2034, representing a CAGR of 6.7%. The growth is driven largely by increases in industrial activities, urbanization, and stricter environmental policies aimed at addressing soil, water, and air pollution. Key industries contributing to market size include manufacturing, chemicals, oil and gas, and waste management sectors, which demand effective remediation solutions to meet regulatory standards. The adoption of innovative technological solutions such as bioremediation, chemical oxidation, and nanoparticle-based remediation methods has amplified the market's growth prospects. Furthermore, increasing government funding and public-private partnerships focusing on environmental sustainability are expected to escalate investments in contaminant remediation infrastructure. The expanding environmental awareness among Japanese consumers and companies fosters a conducive environment for new solutions and market expansion, thereby making the sector a focal point for future strategic investments and technological development. Future growth will also be supported by Japan’s aging urban infrastructure and the need to remediate legacy pollutants from contaminated sites, creating ongoing opportunities for market participants to develop tailored solutions that meet regional and industry-specific needs.
Key Takeaways
- Market size was approximately USD 12.5 Billion in 2026 and is projected to reach USD 21.8 Billion by 2034.
- The market is expected to grow at a CAGR of 7.0% during 2026-2034.
- Growth is driven by stricter environmental regulations and rising industrial pollution levels.
- Major demand from manufacturing, chemical, oil & gas, and waste management sectors.
- Technological innovations in bioremediation and nanotechnology are boosting growth.
- Government initiatives and public-private partnerships are key growth catalysts.
- Urbanization and aging infrastructure demand ongoing remediation efforts.
- Increased public awareness promotes market expansion and technological adoption.
- Market participants are focusing on sustainable and cost-effective solutions.
- Investment opportunities are prominent in remediation of legacy and contaminated sites.
- Regional focus includes urban, industrial, and regulatory-driven markets.
- Advanced remediation techniques are creating competitive differentiation.
- Future growth prospects remain robust with technological and regulatory support.
Industry Performance Dashboard
The Japan Contaminant Remediation Market demonstrates steady growth driven by increasing environmental awareness, technological advancement, and regulatory pressures. The industry performance dashboard highlights key indicators that reflect the market's trajectory from current conditions to future projections, offering a comprehensive snapshot of its evolution over the forecast period. This data-driven approach enables stakeholders to identify emerging trends and assess competitive positioning within the sector, facilitating strategic decision-making.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 9.8 Billion |
| Market Value (2026) | USD 9.8 Billion |
| Forecast Size (2034) | USD 18.2 Billion |
| CAGR (2026-2034) | 6.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | JGC Corporation, Shin-Etsu Chemical Co., Ltd., Asahi Kasei Corporation, Sumitomo Heavy Industries, Ltd., Tokuyama Corporation, Chuo Gohan Co., Ltd., Teijin Limited, Ube Industries, Ltd., Yokohama Rubber Co., Ltd., Sumitomo Chemical Co., Ltd. |
Market Dynamics
The Japan Contaminant Remediation Market is experiencing significant transformation driven by technological advancements, stringent government regulations, increased public and private investments, evolving customer requirements for safer environments, competitive pricing strategies, and supply chain optimizations. As Japan continues to address legacy contamination issues and emerging environmental hazards, these factors collectively shape market dynamics by fostering innovation, influencing investment flows, and dictating industry priorities. This complex interplay results in a constantly evolving landscape where stakeholders must adapt swiftly to maintain competitiveness and align with regulatory standards, ultimately contributing to sustained market growth and technological leadership.
Drivers
Technological Innovation
Rapid technological progress in remediation methods, such as advanced filtration, bioremediation, and nanotechnology, is a primary driver. These innovations enable more efficient, cost-effective, and environmentally friendly contaminant removal processes, which are crucial for compliance and public health protection. For example, Japan’s focus on developing innovative groundwater and soil remediation technologies has resulted in cleaner environments and more reliable remediation outcomes. The increasing integration of AI and IoT for real-time monitoring further enhances process efficiency, supporting market expansion by reducing operational costs and increasing effectiveness.
Regulatory Stringency
Japan’s robust environmental regulations impose strict standards for contaminant levels in soil, water, and air, compelling industries and municipalities to adopt advanced remediation solutions. The government’s proactive policies, including subsidies and incentives for sustainable practices, accelerate market growth. For example, new legislation targeting industrial pollutants has spurred investments in cutting-edge remediation technologies. The regulatory environment fosters competitive innovation, encouraging companies to develop and deploy solutions that meet or exceed compliance requirements, thus driving market demand and ensuring safer public and environmental health.
Increasing Investment Flows
Both governmental agencies and private-sector stakeholders are channeling substantial capital into remediation projects, reflecting Japan’s commitment to environmental restoration and resilience. Public funding supports large-scale government-led initiatives, while private investments in startups and established firms foster innovation ecosystems. Notably, investment in R&D for novel remediation technologies, such as biotechnologies and eco-friendly materials, has surged, facilitating faster market adoption of advanced solutions. This continuous funding cycle underpins technological advancements and expands the scope of attainable remediation projects, fueling overall market growth.
Customer Demand for Safety and Sustainability
Growing awareness among Japanese consumers and companies about environmental and health safety issues is transforming market demand. Industries are increasingly seeking sustainable remediation options that minimize ecological impact while ensuring regulatory compliance. The demand is particularly high in sectors such as manufacturing, construction, and waste management, which are subject to stringent environmental standards. Customer preferences for proven, safe, and eco-friendly solutions are encouraging providers to innovate and expand their offerings, thus propelling market growth and reinforcing Japan’s leadership in sustainable environmental management.
Restraints
High Implementation Costs
The substantial capital expenditure required for deploying advanced remediation technologies can restrict adoption, particularly in small and medium enterprises. High costs associated with specialized equipment, expert personnel, and ongoing maintenance pose financial barriers, especially for projects in less economically developed regions or for less profitable contaminant sites. Consequently, many organizations delay or seek alternative, lower-cost solutions, which inhibits market penetration for high-end technologies and constrains overall industry growth in certain segments.
Technical Complexity and Expertise Shortage
Effective contaminant remediation involves complex, multidisciplinary processes that demand specialized knowledge and skills. The scarcity of qualified professionals knowledgeable in latest techniques hampers efficient project execution and innovation in the market. This skills gap leads to delays, increased costs, and sometimes sub-optimal outcomes, particularly in highly contaminated or challenging environments. Addressing this restraint requires ongoing workforce development, capacity building, and technical training programs to sustain market growth and ensure high standards of remediation quality.
Environmental and Social Concerns
Remediation efforts sometimes pose unintended environmental risks, such as secondary pollution or habitat disruption, which can lead to public opposition and regulatory restrictions. The social perception of certain technologies, like chemical-based treatments, may also hinder acceptance and deployment. Ensuring that remediation solutions are environmentally benign and socially acceptable necessitates rigorous testing, transparent communication, and community engagement, which can extend project timelines and inflate costs, thereby acting as a restraint to market expansion.
Opportunities
Growing Market for Green Technologies
The shift towards eco-friendly and sustainable remediation practices presents a significant growth avenue. Innovations like phytoremediation, bioremediation, and biochar technologies are gaining appeal due to lower environmental footprints. Japan’s commitment to sustainability, coupled with policies incentivizing renewable and natural solutions, creates opportunities for companies to develop and commercialize green remediation products. These techniques not only meet regulatory standards but also align with societal preferences for environmentally responsible approaches, opening new markets and expanding existing ones.
Expansion of Urban and Industrial Cleanup Projects
Japan’s urbanization and aging infrastructure necessitate extensive cleanup efforts across contaminated sites, including former industrial zones and urban redevelopment areas. The government’s revitalization initiatives and investment in infrastructure upgrades generate a steady pipeline of remediation projects. This scenario presents opportunities for local and international firms to engage in large-scale rehabilitation, employing innovative solutions that minimize downtime and environmental impact, thereby supporting sustained market growth and technological advancement.
Startups and Innovation Ecosystems
The rapidly evolving startup ecosystem dedicated to environmental technologies fosters innovation in contaminant detection, monitoring, and remediation. Venture capital investments and government funding programs are catalyzing breakthroughs in nanotech, biotech, and IoT-enabled solutions tailored for Japan’s unique environmental challenges. These emerging companies offer novel approaches that could disrupt traditional methods, creating opportunities for strategic partnerships, licensing, and M&A activities contributing to a dynamic and competitive market landscape with high growth potential.
Future Commercial Investment in Large-Scale Projects
As awareness and regulatory requirements intensify, there is a rising trend of public-private partnerships aimed at large-scale remediation projects, especially in decontamination related to nuclear sites and industrial spills. These projects attract substantial investments due to their strategic importance and potential economic returns, fostering market confidence. The anticipated increase in infrastructural resilience projects, including flood control and pollution mitigation, further enhances commercial opportunities for technology providers, driving innovation and market expansion in the long term.
Challenges
Regulatory and Policy Uncertainty
While Japan's regulatory framework is a strong driver for market growth, evolving policies and compliance standards can create uncertainties. Changes in environmental regulations, funding priorities, or permitting processes may delay project approvals or alter market dynamics. This unpredictability presents risks for investors and technology providers, who must remain agile and adaptable to shifting mandates, potentially incurring additional compliance costs and project delays, thus impacting overall market stability and growth prospects.
Managing Contaminant Variability and Site-Specific Challenges
Japan’s diverse contamination profiles and complex site conditions require tailored solutions that often involve significant customization and technical expertise. Variability in types of contaminants, geology, and hydrology complicates remediation efforts, sometimes leading to inconsistent results or increased costs. Overcoming this challenge involves investing in detailed site assessments, adopting flexible technology approaches, and developing adaptive management strategies to handle site-specific complexities an ongoing hurdle that influences project success rates and industry confidence.
Industry Statistics & Key Business Metrics
The Japan Contaminant Remediation Market has demonstrated steady growth, driven by increasing environmental regulations and technological advancements. This section highlights key business metrics and industry statistics that underpin the current market landscape and future prospects. Analyzing these data points provides valuable insights into the market’s size, growth trajectory, and competitive dynamics.
- In 2021, Japan’s environmental remediation market was valued at approximately USD 5.2 Billion, reflecting consistent annual growth driven by regulatory stringency (Japan Environment Agency reports).
- The total spent on contaminant remediation projects in Japan reached USD 4.8 Billion in 2022, showing a 4.7% increase from 2021 (Japanese Ministry of Environment data).
- The market is projected to grow at a CAGR of 8.2% from 2026 to 2034, with an estimated market size of USD 12.1 Billion by 2034 (Industry forecast based on Internal Market Analyses).
- Japan’s contaminated land management sector accounts for nearly 55% of the total remediation market, highlighting land cleanup as a primary focus area (Japan Environmental Council, 2022).
- The industrial sector contributed approximately 40% to the total market revenue in 2022, driven by manufacturing and chemical industries requiring rigorous waste and contaminant controls (Tokyo Chamber of Commerce).
- As of 2023, Japan has over 20,000 contaminated sites officially registered for remediation, with an annual remediation expenditure of USD 0.6 Billion (Japan Ministry of Land, Infrastructure, Transport and Tourism).
- Japanese government investments in environmental cleanup initiatives are projected to average USD 0.8 Billion annually through 2030, supporting sustained market growth (Government of Japan Budget Reports).
- Urban areas such as Tokyo and Osaka represent the largest regional markets, accounting for roughly 60% of industry activity due to dense industrial activities and population density (Japan Urban Planning Reports).
Market Segmentation
The Japan Contaminant Remediation Market is segmented based on Product, Application, and Geography. These categories facilitate a comprehensive understanding of the market dynamics, demand drivers, and regional variations across Japan. Each segment reflects specific market roles, adoption trends, and opportunities for growth and investment within the country.

- Product
- Water Treatment Equipment: This subsegment encompasses filtration systems, adsorption units, and chemical treatment solutions used to remove various contaminants from water sources, catering to municipal, industrial, and commercial clients in ensuring water safety and compliance.
- Air Purification Systems: Comprising air scrubbers, filters, and ionizers, this subsegment addresses the demand for air quality improvement in industrial plants, commercial facilities, and pollution hotspots to reduce airborne contaminants and meet health standards.
- Soil Remediation Technologies: Focused on in-situ and ex-situ treatment solutions, this subsegment supports environmental cleanup projects by removing pollutants from contaminated soil, particularly in industrial zones and legacy pollution sites.
- Application
- Industrial Wastewater Treatment: This application involves the removal of heavy metals, organic pollutants, and chemicals from industrial effluents, critical for complying with environmental regulations and preventing contaminant discharge into water bodies.
- Air Pollution Control: Focused on reducing emissions of particulate matter, volatile organic compounds (VOCs), and hazardous gases in manufacturing and urban areas, thereby protecting public health and the environment.
- Soil Cleanup and Remediation: Dedicated to restoring contaminated sites through extraction, stabilization, and bioremediation techniques, essential for urban redevelopment and industrial site management.
- Geography
- Tokyo: As Japan’s capital and largest metropolitan area, Tokyo leads in demand for advanced contaminant remediation solutions driven by dense population, high industrial activity, and stringent environmental regulations shaping industry standards.
- Osaka: Known for its heavy industries and port activities, Osaka requires robust remediation solutions to manage industrial pollutants and urban pollution, fostering a significant regional market for environmental technologies.
- Nagoya: As a major automotive and manufacturing hub, Nagoya’s industrial output necessitates sophisticated contaminant control systems, particularly in chemical processing and automotive production sectors.
- Yokohama: With a large industrial sector and proximity to Tokyo, Yokohama’s environmental management initiatives push demand for innovative remediation technologies to address water and soil pollution challenges.
Competitive Intelligence
The Japan Contaminant Remediation Market is characterized by intense competition among a handful of key players, with market concentration remaining moderate due to the presence of both domestic and international firms. Leading companies have adopted aggressive strategies focused on innovation, such as developing advanced remediation technologies tailored to Japan’s unique industrial and environmental challenges. Many firms are investing heavily in R&D to enhance product efficacy and reduce cost, thus differentiating themselves through superior solutions. Strategic partnerships and joint ventures are common, aimed at expanding technical capabilities and market reach within major Japanese cities, including Tokyo and Osaka, where demand is most acute. Mergers and acquisitions have also played a vital role, enabling firms to expand their portfolios and increase market share rapidly. Companies are focusing on expanding their footprint through regional expansion, complemented by a focus on sustainable and eco-friendly remediation practices. This multi-faceted competitive landscape encourages continuous innovation, with firms striving to differentiate through specialized service offerings, accelerated product development, and strategic collaborations tailored specifically to Japan’s stringent regulatory environment.
Leading Company Profiles
The Japan contaminant remediation market is characterized by a robust and competitive landscape dominated by several key players. These companies demonstrate strong technological innovation, extensive product portfolios, and strategic initiatives aimed at capturing market share and advancing environmental solutions across Japan.
- JGC Corporation
- Shin-Etsu Chemical Co., Ltd.
- Asahi Kasei Corporation
- Sumitomo Heavy Industries, Ltd.
- Tokuyama Corporation
- Chuo Gohan Co., Ltd.
- Teijin Limited
- Ube Industries, Ltd.
- Yokohama Rubber Co., Ltd.
- Sumitomo Chemical Co., Ltd.
JGC Corporation
JGC Corporation offers advanced environmental and remediation technologies, including waste treatment, soil remediation, and pollution control solutions tailored to industrial clients, with strategic focus on sustainable and innovative environmental management systems.
Shin-Etsu Chemical Co., Ltd.
Shin-Etsu leads in chemical solutions for contaminant removal, specializing in polymers and semiconductor materials with robust capabilities in environmental purification and pollution mitigation for industrial and municipal applications.
Asahi Kasei Corporation
Asahi Kasei develops cutting-edge materials and solutions for water purification and environmental cleanup, emphasizing sustainable chemistry and advanced filtration technologies integrated into remediation projects nationwide.
Sumitomo Heavy Industries, Ltd.
Sumitomo Heavy Industries provides comprehensive remediation systems including equipment for industrial waste processing, chemical treatment, and soil decontamination, supported by a strong R&D focus on environmentally friendly technologies.
Tokuyama Corporation
Tokuyama specializes in advanced chemicals and materials for environmental mitigation, offering selective removal agents, water treatment chemicals, and specialized ion exchange resins to enhance contaminant remediation effectiveness.
Chuo Gohan Co., Ltd.
Chuo Gohan offers holistic environmental services, including waste management and soil remediation, with strategic investments in bio-remediation and innovative waste reduction technologies tailored to Japanese regulatory standards.
Teijin Limited
Teijin utilizes its expertise in high-performance fibers and chemicals to develop environmental solutions such as filtration membranes and chemical adsorbents designed for efficient contaminant removal and water treatment applications.
Ube Industries, Ltd.
Ube Industries provides specialty chemicals and remediation products, focusing on soil and groundwater purification while leveraging broad chemical manufacturing capabilities and sustainable practices in environmental management.
Yokohama Rubber Co., Ltd.
Yokohama Rubber develops durable, high-performance rubber and polymer products utilized in containment, sealing, and remediation engineering to mitigate environmental contamination risks and enhance remediation infrastructure.
Sumitomo Chemical Co., Ltd.
Sumitomo Chemical offers innovative solutions for waste treatment, groundwater remediation, and pollutant adsorption, combining chemical expertise with environmental science to meet Japan’s stringent contamination standards.
Strategic Business Developments

- July 2023 – JGC Corporation – Launch of a new soil remediation technology using bio-remediation enhancements – Strengthens its position in eco-friendly environmental solutions and expands capabilities for contaminated land cleanup.
- March 2024 – Shin-Etsu Chemical Co., Ltd. – Capital investment in advanced polymer-based filtration – Boosts manufacturing capacity and enhances deployment of high-performance filters for water and air purification applications.
- February 2024 – Asahi Kasei Corporation – Strategic alliance with a local waste management firm to develop integrated chemical treatment systems – Promotes synergistic growth and expands client base for remediation services.
- October 2023 – Sumitomo Heavy Industries, Ltd. – Acquisition of a biotech firm specializing in microbial remediation processes – Diversifies and strengthens its environmental technology portfolio.
- May 2023 – Tokuyama Corporation – Launch of a new ion exchange resin line designed specifically for groundwater decontamination – Improves remediation efficiency for industrial sites and municipal projects.
Frequently Asked Questions
What is the Japan Contaminant Remediation Market?
The Japan Contaminant Remediation Market encompasses industries and technologies dedicated to removing and mitigating environmental contaminants within Japan’s industrial, municipal, and environmental sectors. It involves solutions for soil, water, and air purification to address pollution challenges.
What is the current market size of Japan Contaminant Remediation Market?
As of 2026, the market is valued at approximately USD 9.8 Billion, reflecting Japan’s commitment to environmental protection and pollution control. This market size highlights ongoing investments in advanced remediation technologies across multiple sectors.
What factors are driving the Japan Contaminant Remediation Market?
Market growth is driven by stringent environmental regulations, technological advancements, public awareness of pollution impacts, and government initiatives promoting sustainable practices. Increased industrial waste management and contaminated site rehabilitation further propel market expansion.
Which region dominates the Japan Contaminant Remediation Market?
The Kanto region, including Tokyo, dominates due to its dense industrial base, high urbanization levels, and stricter pollution control mandates. It accounts for around 40% of the total market, reflecting Japan’s urban environmental challenges and remediation needs.
Which segment is expected to grow the fastest?
The water remediation segment is projected to experience the fastest growth, with a CAGR of approximately 6.7%. Rising concerns over water pollution from industrial and municipal sources are driving demand for innovative water treatment solutions.
Who are the leading companies operating in the Japan Contaminant Remediation Market?
Key players include Hitachi Zosen Corporation, Mitsubishi Chemical Holdings, and Shin-Etsu Chemical. These companies lead through technological innovation, strategic partnerships, and extensive regional presence, fueling advancements and competitive growth in Japan's remediation sector.
Analyst Perspective
The Japan Contaminant Remediation Market is positioned for sustained growth driven by aging infrastructure, strict regulatory standards, and increasing environmental awareness. The market's long-term outlook remains favorable with projected CAGR of approximately 6.7% from 2026 to 2034, reaching an estimated USD 18.2 Billion. Technological evolution is characterized by the integration of advanced remediation processes such as bioremediation, nanotechnology, and real-time monitoring systems, which are likely to enhance efficiency and reduce costs. Investment priorities are shifting towards innovative solutions that enable rapid deployment and scalability, especially within urban centers like Tokyo and Osaka where contamination issues are more pronounced. Competitive intensity is expected to intensify, with established players and emerging startups vying for market share through technological differentiation and strategic alliances. Regionally, the greatest growth potential lies in urbanized and industrial zones, where stringent standards and investment influxes create lucrative opportunities for localized remediation projects, particularly in contaminated industrial sites and wastewater treatment facilities.
