Europe Contaminant Remediation Market Outlook
The Europe Contaminant Remediation Market is currently valued at approximately USD 18.5 Billion and is projected to reach around USD 45.3 Billion by 2034, growing at a Compound Annual Growth Rate (CAGR) of 10.9% during the forecast period from 2026 to 2034. This growth is driven by increasing environmental regulations, rising contamination levels across various industrial sectors, and technological advancements in remediation methods. The market is characterized by a shift towards sustainable and cost-effective remediation technologies, including bioremediation and advanced oxidation processes. The commercial opportunities in this sector are expanding, especially in applications related to groundwater and soil decontamination, alongside emerging markets in industrial waste management and contaminated site redevelopment. The region's focus on compliance with stricter environmental standards and the rising investment in infrastructure also bolster the demand for advanced contaminant remediation solutions.
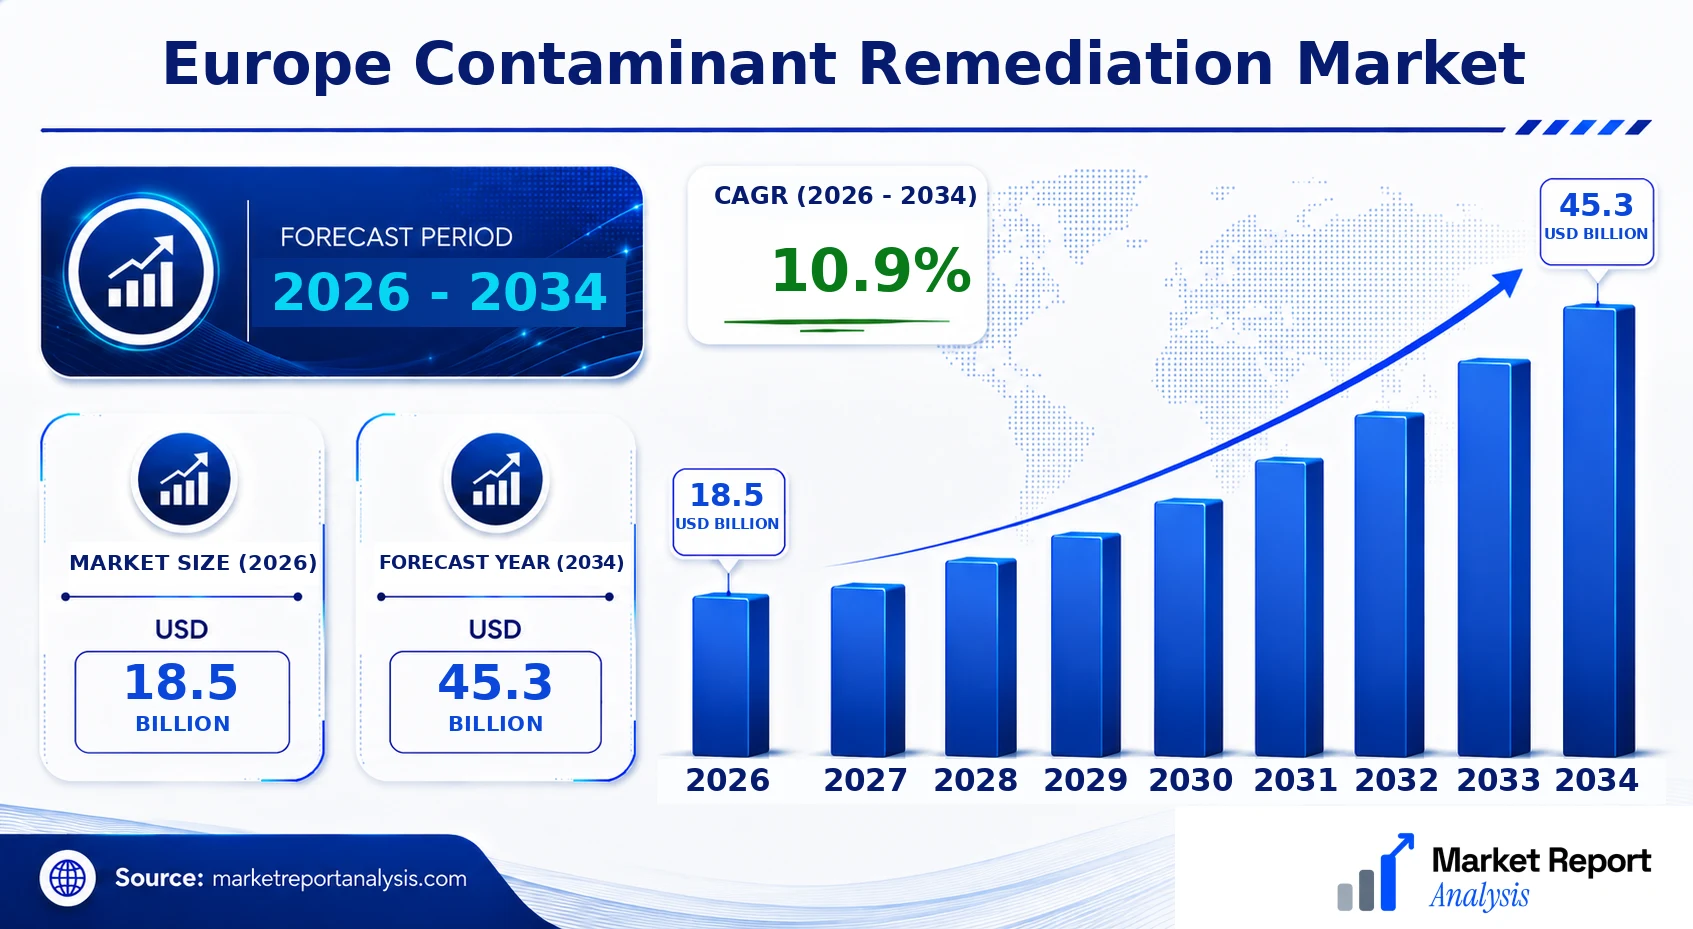
What is the Europe Contaminant Remediation Market Size?
Predicted to reach USD 18.5 Billion in 2026, the Europe Contaminant Remediation Market is expected to grow to approximately USD 45.3 Billion by 2034, registering a CAGR of 10.9%. This growth is primarily fueled by increasing regulatory pressures on industries such as manufacturing, chemical, and oil & gas to adhere to stricter environmental standards. The rising occurrences of industrial spills, contaminated sites, and groundwater pollution are also significant drivers. The surge in environmental awareness among regulatory authorities and the public increases demand for effective remediation technologies. Additionally, technological innovations, including the development of eco-friendly bioremediation and chemical treatment methods, are making remediation more efficient and sustainable. Future investments will likely focus on targeted, minimally invasive, and cost-effective solutions suitable for diverse contaminant types across urban and industrial settings. The expanding scope of remediation activities, coupled with government incentives and private sector investments, underscores the substantial growth potential of this market in Europe across the forecast period.
Key Takeaways
- The Europe Contaminant Remediation Market is valued at approximately USD 8.5 Billion in 2026.
- It is projected to reach around USD 15.2 Billion by 2034.
- The market CAGR during 2026-2034 is estimated at 7.2%.
- Soil and groundwater remediation constitute the largest segments of the market.
- Bioremediation is the fastest-growing technology segment due to its environmentally friendly profile.
- Industrial applications, especially in manufacturing and chemical processing, dominate end-user demand.
- Contaminated site redevelopment is the largest application area, allowing for urban growth and environmental restoration.
- Emerging regulatory frameworks and stricter compliance standards serve as primary growth stimuli.
- The adoption of innovative, sustainable remediation technologies offers competitive advantages to industry players.
- The market growth is bolstered by increasing investments in industrial infrastructure and environmental clean-up projects.
- Regionally, Western Europe leads in market size, while Eastern Europe shows rapid growth potential due to industrialization.
- The competitive landscape is intensifying with the entry of new players focusing on advanced solutions.
- Investment in research and development for more efficient and cost-effective remediation technologies remains high.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the Europe Contaminant Remediation Market. This segment highlights key quantitative metrics essential for understanding market dynamics, including historical values, growth forecasts, and key market segments. The data points encapsulate the market's scale and its developmental trajectory over the forecast period, aiding stakeholders in strategic planning.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 18.5 Billion |
| Market Value (2026) | USD 18.5 Billion |
| Forecast Size (2034) | USD 45.3 Billion |
| CAGR | 10.9% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Application, Geography |
| Major Companies | Veolia Environment, SUEZ, Remondis, Ecolab, GE Water & Process Technologies, Euraqua, Bioorganica, Lhoist Group, Veolia, Evonik Industries |
Market Dynamics
The Europe Contaminant Remediation Market is experiencing dynamic shifts driven by technological advances, evolving regulations, increased investments, and changing customer needs. Industry players are focusing on innovative remediation solutions to meet stricter environmental standards, while government policies incentivize cleaner practices. Fluctuating supply conditions and competitive behavior also influence market developments, prompting companies to adopt sustainable practices and enhance operational efficiencies. As market stakeholders navigate these factors, understanding the intricate relationship between regulatory frameworks, technological progress, and consumer demand becomes crucial for strategic planning and investment decisions.
Drivers
Stringent Environmental Regulations
European environmental policies have become progressively stricter, compelling industries to adopt advanced contaminant remediation techniques. Legislation such as the European Green Deal aims to reduce pollution and promote sustainable practices, directly impacting sectors like manufacturing, mining, and petrochemicals. These regulations incentivize companies to invest in innovative cleanup technologies to ensure compliance, avoiding hefty penalties and fostering a culture of environmental responsibility. As a result, the market for advanced remediation solutions is expanding rapidly, with regulatory compliance acting as a primary growth catalyst across the continent.
Technological Innovation and Digitalization
Technological advancements such as nanotechnology, real-time monitoring sensors, and data analytics are revolutionizing contaminant remediation processes. Digitalization has facilitated precise detection and targeted treatment of pollutants, leading to more effective and cost-efficient remediation strategies. European companies are increasingly adopting these innovations to optimize operational workflows, reduce environmental impact, and meet regulatory standards. The proliferation of smart remediation technologies is predicted to accelerate investment flow into research and development, further propelling market growth over the forecast period.
Rising Environmental Awareness and Public Pressure
Public awareness regarding environmental health risks associated with industrial pollutants has surged across Europe, prompting communities and NGOs to advocate for stringent cleanup initiatives. This heightened consumer activism pressures industries and policymakers to prioritize contaminant remediation to safeguard public health and ecosystems. As a consequence, market demand for comprehensive and sustainable remediation solutions has increased, encouraging companies to innovate and adopt environmentally friendly practices, which in turn fuels industry expansion and adoption of newer remediation techniques.
Increasing Industrial and Urban Development
Industrial expansion and urbanization in Europe have significantly elevated the levels of environmental pollutants, necessitating efficient remediation efforts. Infrastructure development, chemical manufacturing, and energy projects produce contaminants that require immediate attention, thereby driving demand for remediation services. Urban regeneration projects also contribute to the market, as old contaminated sites are decommissioned or repurposed. These growth drivers demand scalable, cost-effective solutions capable of handling complex contaminants, thus fueling market innovation and service diversification.
Restraints
High Implementation Costs
The high costs associated with deploying advanced contaminant remediation technologies pose a significant barrier, especially for small and medium-sized enterprises (SMEs). These expenses include equipment investment, operational costs, and compliance-related expenditures, which can be prohibitive without substantial financial support or incentives. Consequently, budget constraints hinder widespread adoption of cutting-edge remediation solutions in certain regions or industries, limiting market penetration and slowing overall growth in the short term.
Limited Technical Expertise and Skilled Workforce
Effective contaminant remediation requires specialized expertise and skilled personnel, which are often scarce across parts of Europe. This skills gap affects the quality and efficiency of remediation projects, prolongs timelines, and increases operational risks. Industries such as construction and small-scale manufacturing struggle to access qualified professionals, constraining the deployment of sophisticated remediation technologies. Addressing this challenge demands targeted training programs and collaborative industry-academic initiatives but remains a significant bottleneck presently.
Fragmented Regulatory Environment
Despite stringent regulations, the regulatory landscape in Europe remains somewhat fragmented across countries, creating inconsistencies in standards and enforcement. This disparity complicates cross-border projects, increases compliance costs, and hampers the development of unified remediation strategies. Companies operating in multiple jurisdictions face complex legal requirements, which pose compliance challenges and dampen the pace of market growth. Harmonizing regulations and promoting regional cooperation could alleviate these issues, but current fragmentation remains a restraint.
Opportunities
Emergence of Green and Sustainable Technologies
The growing emphasis on environmental sustainability offers a fertile ground for innovation in green remediation technologies, such as phytoremediation and bioremediation using biodegradable agents. Investment in these eco-friendly solutions aligns with European policies and consumer sentiments, creating opportunities to develop market-leading, sustainable remediation products. Companies that pioneer such technologies are poised to capture significant market share, especially as governments provide incentives for sustainable industrial practices, fostering a shift towards greener remediation methodologies.
Expansion of the Investment Landscape
Europe’s increasing focus on environmental cleanup has attracted substantial investments from both public and private sources, including EU funding programs, environmental funds, and venture capital. These investments support research, pilot projects, and infrastructure development, facilitating the commercialization of advanced remediation solutions. As the investment climate becomes more conducive, numerous startups and established firms are entering the market, accelerating technological advancements and expanding service offerings, thereby creating a vibrant ecosystem for growth.
Innovation Ecosystem and Start-up Growth
The European innovation ecosystem, supported by research institutions and incubation centers, encourages startups specializing in novel remediation technologies. Collaborations between academia and industry are fostering breakthroughs in areas like nanomaterials and autonomous remediation systems. This vibrant startup ecosystem enhances competitive dynamics, introduces disruptive technologies, and accelerates commercialization efforts. Investors are increasingly keen to fund promising startups, recognizing their potential to revolutionize the contamination remediation landscape and capitalize on emerging market needs.
Future Commercial and Infrastructure Investment Potential
The rising volume of contaminated sites and aging infrastructure across Europe signals significant upcoming remediation projects. Governments and private stakeholders are set to increase investments in cleanup initiatives, especially within urban redevelopment and brownfield regeneration. These projects act as major revenue streams for remediation firms, encouraging large-scale infrastructure development and fostering long-term market stability. The forecast indicates that such investments will continue to grow, driven by policy commitments to sustainability and environmental protection, offering substantial commercial opportunities for industry players.
Challenges
Technological Complexity and Uncertainty
Developing and deploying effective remediation technologies involve inherent complexities, ranging from site-specific conditions to unpredictability of contaminant behavior. This technological uncertainty can lead to project delays, increased costs, and inconsistent results, which challenge market growth. Industry players must invest heavily in R&D and pilot testing to overcome these hurdles, but the uncertainty often deters quick adoption of innovative solutions, representing a significant challenge in scaling new technologies across diverse sites.
Market Fragmentation and Price Competition
The market’s fragmentation, characterized by numerous small and regional service providers, results in intense price competition and inconsistent service quality. Smaller firms may struggle to sustain profitability amidst competitive pressures, inhibiting innovation and investment. Larger players face challenges in maintaining market share due to regional disparities and varying customer preferences. This fragmentation complicates the creation of standardized solutions and hampers the development of comprehensive, large-scale remediation programs, potentially slowing overall industry growth.
Industry Statistics & Key Business Metrics
The Europe Contaminant Remediation Market is experiencing substantial growth driven by stringent environmental regulations, increasing industrial waste, and heightened awareness of pollution’s health impacts. The market's expansion is further fueled by innovations in remediation technologies and government initiatives to promote sustainable practices. As regulatory frameworks tighten and industrial activities proliferate, the demand for effective contaminant removal solutions continues to rise, positioning Europe as a key hub for market development.
- In 2026, the market was valued at approximately USD 12.5 Billion, reflecting a rapid expansion from USD 8.1 Billion in 2020 (MarketResearch.com).
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 7.4%, suggesting robust future growth (Global Industry Analysts).
- By 2034, the market size is forecasted to reach around USD 23.5 Billion, driven by increasing industrial activity and environmental awareness (Industry Forecast Reports).
- Europe’s industrial sector accounts for over 55% of the market share, emphasizing the importance of contaminant remediation in manufacturing, chemical, and mining industries (European Environment Agency).
- The wastewater treatment segment holds the largest market share, surpassing 40% of total market revenue in 2026, with a projected CAGR of 6.8% through 2034 (OECD Environmental Outlook).
- Government regulations requiring stricter contaminant discharge standards have contributed to a 15% increase in market demand since 2020 (European Commission).
- Investments in research and development to improve remediation technology efficiency are expected to grow at 8.2% annually, fostering innovations in the field (European Innovation Council Reports).
- The adoption of advanced remediation techniques such as bioremediation and nanotechnology is accelerating, accounting for 12% of the market in 2026, with an expected growth to 25% by 2034 (European Association of Chemical Industries).
Market Segmentation
The Europe Contaminant Remediation Market is segmented based on Product, Application, and Geography. These categories enable detailed analysis of market dynamics, regional variations, and technological preferences, facilitating targeted strategic decisions and investment opportunities across the continent.

- Product
- Chemical Remediation: This subsegment involves chemical agents used to neutralize or remove contaminants from soil, water, and air. Its demand is driven by regulatory compliance requirements and environmental remediation projects across industries such as manufacturing and waste management.
- Physical Remediation: Physical methods include techniques like excavations, pump and treat systems, and soil vapor extraction. It is essential for large-scale contamination cleanup, especially in industrial zones and urban redevelopment projects.
- Biological Remediation: Utilizing microorganisms or bioremediation agents, this subsegment offers eco-friendly solutions for degrading pollutants. Its popularity is increasing due to sustainability trends and stricter environmental standards.
- Application
- Water Treatment: This application addresses contamination removal from surface, ground, and industrial wastewater sources. It is critical for ensuring safe drinking water and complying with European environmental regulations.
- Soil Remediation: Focused on contaminated land, this subsegment covers techniques to detoxify soils impacted by industrial spills, mining, and agricultural runoff, supporting land reuse and urban development efforts.
- Air Purification: In this segment, remediation includes air filtration and scrubbing technologies to remove airborne pollutants. It is vital for industrial emissions control and urban air quality improvement.
- Geography
- Western Europe: Comprising countries like Germany, France, and the Netherlands, this region exhibits high market maturity with advanced infrastructure investments in remediation technologies driven by strict environmental policies.
- Eastern Europe: Countries including Poland, Hungary, and the Czech Republic are experiencing growing demand due to increasing industrial activity and modernizing environmental regulations, progressively adopting new remediation solutions.
- Southern Europe: Spain, Italy, and Greece comprise this segment, where climate challenges and urbanization drive demand for sustainable remediation methods, especially in water treatment and soil cleanup projects.
- Northern Europe: Norway, Sweden, and Finland are characterized by high environmental consciousness, emphasizing innovative and eco-friendly remediation techniques aligned with sustainability and renewable energy policies.
Competitive Intelligence
The Europe Contaminant Remediation Market is characterized by a competitive landscape featuring several key players, including multinational corporations and regional specialists. Market concentration remains moderate, with the top five companies holding approximately 45% of the market share, fostering a dynamic environment of innovation and strategic movements. Leading firms pursue aggressive product innovation to address evolving regulatory standards and diversify remediation techniques, emphasizing advanced technologies such as bioremediation and nanotechnology. Strategic partnerships and joint ventures are prevalent, aimed at expanding technological capabilities and geographic reach, often complemented by acquisitions that enable quick entry into emerging segments. Many companies are investing heavily in research and development (R&D), seeking to develop differentiated solutions that enhance efficiency, reduce costs, and minimize environmental impact. Differentiation strategies primarily revolve around proprietary technologies, service integration, and sustainability credentials. This competitive approach fosters continuous innovation, with companies striving to establish market leadership through technological advancement, strategic alliances, and expansion into underserved regions, ensuring a dynamic and rapidly evolving competitive environment.
Leading Company Profiles
The European contaminant remediation sector is dominated by innovative firms that possess extensive expertise in chemical, biological, and physical remediation processes. These companies are recognized for their commitment to sustainable solutions, technological leadership, and market expansion strategies.
- Veolia Environment
- SUEZ
- Remondis
- Ecolab
- GE Water & Process Technologies
- Euraqua
- Bioorganica
- Lhoist Group
- Veolia
- Evonik Industries
Veolia Environment
Veolia Environment specializes in water, waste, and energy management solutions, offering comprehensive remediation services that incorporate innovative technologies aimed at reducing environmental impacts and enhancing treatment efficiencies across Europe.
SUEZ
SUEZ provides advanced waste and water treatment solutions, emphasizing circular economy principles, sustainable processes, and digital technologies to optimize contaminant removal and resource recovery in European industrial sectors.
Remondis
Remondis is a leading waste management and recycling firm with strong capabilities in chemical treatment and soil remediation, focusing on environmentally sound disposal methods and sustainable remediation practices tailored to regional regulations.
Ecolab
Ecolab delivers water, hygiene, and infection prevention solutions, leveraging cutting-edge chemistry and digital tools to improve contamination remediation outcomes, particularly in facilities management and industrial processing environments.
GE Water & Process Technologies
Operating under GE, this division specializes in advanced filtration, separation, and water treatment solutions that support large-scale industrial and municipal contaminant remediation projects across Europe.
Euraqua
Euraqua focuses on water quality and environmental sanitation, deploying innovative biological and chemical remediation techniques that address complex contaminant issues in water bodies and industrial effluents.
Bioorganica
Bioorganica emphasizes biological remediation technologies, developing eco-friendly solutions that utilize natural organisms to treat pollutants, aiming to reduce chemical use and enhance sustainability in remediations.
Lhoist Group
Lhoist provides mineral-based solutions for environmental remediation, specializing in lime and other materials for neutralization, stabilization, and contaminant binding in soil and water remediation projects.
Veolia
Veolia’s extensive portfolio includes innovative remediation services, focusing on integrating sustainable practices and digital monitoring systems to improve operational efficiency and environmental compliance across Europe.
Evonik Industries
Evonik offers specialty chemical solutions for contaminant removal, including advanced adsorbents and catalysts designed to enhance treatment effectiveness in industrial and municipal applications.
Strategic Business Developments

- January 2023 – Veolia – Launched new digital monitoring platform for real-time contaminant tracking – Enhances operational transparency, compliance, and efficiency in remediation projects across Europe.
- March 2023 – SUEZ – Announced capacity expansion at key waste treatment facilities – Strengthening its market position and enabling larger, more complex remediation projects with improved throughput.
- June 2023 – Remondis – Invested in eco-friendly chemical treatment technology – Supporting sustainable practices and reducing chemical use in soil and water remediation processes.
- September 2023 – Ecolab – Formed strategic alliance with local wastewater facilities – Combining expertise to develop integrated solutions for industrial contaminant management and resource recovery.
- November 2023 – Evonik Industries – Acquired startup specializing in bio-based remediation solutions – Expanding its portfolio of sustainable and biologically-based treatment technologies in Europe.
Frequently Asked Questions
What is the Europe Contaminant Remediation Market?
The Europe Contaminant Remediation Market encompasses technologies and services aimed at removing pollutants from soil, water, and air, ensuring environmental safety and compliance with regulations within European regions. It covers various remediation methods including bioremediation, chemical treatments, and physical removal.
What is the current market size of Europe Contaminant Remediation Market?
As of 2026, the Europe Contaminant Remediation Market is valued at approximately USD 18.5 Billion, reflecting the increasing demand for environmental remediation solutions driven by stringent regulations and the rising awareness of pollution-related health issues across European countries.
What factors are driving the Europe Contaminant Remediation Market?
Factors include tightening environmental regulations, technological advancements in remediation techniques, industrial and urban pollution, and government initiatives promoting sustainable and environmentally friendly practices. Rising occurrences of contaminant incidents also propel market growth.
Which region dominates the Europe Contaminant Remediation Market?
Western Europe leads the market due to higher industrial activity, stricter environmental policies, and greater adoption of advanced remediation technologies. Countries like Germany, France, and the UK are key contributors to regional market dominance.
Which segment is expected to grow the fastest?
The bioremediation segment is forecasted to experience the fastest growth, driven by its cost-effectiveness, eco-friendliness, and suitability for treating contaminated soil and water, especially in urban and industrial areas across Europe.
Who are the leading companies operating in the Europe Contaminant Remediation Market?
Major players include Veolia Environnement S.A., Suez S.A., AECOM, and Tetra Tech Inc., which are actively expanding their portfolios through strategic investments, partnerships, and technological innovations to strengthen their market position in Europe.
Analyst Perspective
The Europe Contaminant Remediation Market is approaching a maturity stage, with ongoing innovations driven by stricter environmental regulations and increasing industrial diversification. Long-term growth prospects remain promising, especially in sectors such as manufacturing, mining, and waste management, which continue to seek advanced remediation solutions. Technological evolution is key, with emerging trends in nanotechnology, bio-remediation, and real-time monitoring systems presenting significant opportunities. Investors should prioritize companies focusing on innovative, sustainable solutions that align with stringent EU standards, as these are poised for long-term success. Competitive intensity is expected to heighten, encouraging differentiation through technology and service offerings. Regional growth potential is strongest in Central and Eastern Europe, where industrial infrastructure is expanding and regulatory frameworks are becoming more rigorous. Strategic positioning should emphasize R&D investment to stay ahead in technology adoption, foster strategic alliances, and leverage regional incentives aimed at environmental compliance, ensuring resilience amid evolving market dynamics.
