Japan Aircraft Actuator Market Outlook
The Japan aircraft actuator market is positioned for significant growth driven by continuous advancements in aerospace technology and increased aircraft manufacturing activities in the country. As of 2026, the market is valued at approximately USD 3.2 Billion, with forecasts indicating a rise to USD 6.8 Billion by 2034, reflecting a compound annual growth rate (CAGR) of around 8.1% over the forecast period of 2026-2034. The principal drivers include the expansion of the commercial aircraft sector, modernization of existing fleets, and increased defense spending. Technological enhancements such as integration of lightweight, energy-efficient, and digitally controlled actuators are shaping the competitive landscape. Furthermore, Japan's robust aerospace manufacturing industry presents numerous opportunities for domestic and international market stakeholders to innovate and capture value, especially in high-precision and mission-critical actuator applications. The evolving regulatory environment emphasizing safety, environmental sustainability, and advanced avionics further catalyzes market development, creating substantial commercial opportunities for component manufacturers and system integrators.

What is the Japan Aircraft Actuator Market Size?
In 2026, the Japan aircraft actuator market is estimated at USD 3.2 Billion and is poised to expand to USD 6.8 Billion by 2034, corresponding to a CAGR of approximately 8.1% for the period 2026-2034. This growth is predominantly driven by increased demand for new aircraft, particularly narrow-body and wide-body jets, as well as upgrades to existing fleets with advanced, fuel-efficient systems. Additionally, the rise in defense aviation, including UAVs and military aircraft, contributes to the expanding application base. Technological innovations such as electro-mechanical and digital actuators are increasingly adopted due to their reliability and precision. Moreover, the growth of Japan's aerospace sector, coupled with government initiatives fostering aerospace R&D and international collaborations, enhances the market outlook. Future investments are expected to target high-performance actuator systems, integration with health monitoring technologies, and sustainable manufacturing processes, which will propel further market growth and innovation.
Key Takeaways
- Japan aircraft actuator market is valued at USD 1.2 Billion in 2026.
- The market is forecast to reach USD 2.3 Billion by 2034, growing at a CAGR of 8.5%.
- Growth driven by expanding aircraft manufacturing and modernization activities.
- Increased military and defense aircraft demand bolsters market prospects.
- Advances in actuator technology focus on energy efficiency and digital integration.
- Japanese aerospace industry’s robustness supports innovation and local production.
- Regulatory trends favor safety, sustainability, and upgrades in aircraft systems.
- Market opportunities center on high-precision, lightweight, and smart actuators.
- Emerging markets for UAVs and unmanned systems influence market dynamics.
- Strategic alliances and joint ventures strengthen local and international positioning.
- Investment in R&D is key to competitive advantage in actuator technology.
- Sustainable manufacturing practices are increasingly prioritized.
Industry Performance Dashboard
The Japan Aircraft Actuator Market has demonstrated steady growth driven by increasing demand for advanced aircraft systems, technological innovations, and expanding commercial airline fleets within Japan. This dashboard provides a concise assessment of key market indicators, capturing current performance and future trajectories to inform strategic decisions. The market’s performance is influenced by major aerospace manufacturers, component suppliers, and technological trends, creating a dynamic landscape for industry stakeholders.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 3.2 Billion |
| Market Value (2026) | USD 3.2 Billion |
| Forecast Size (2034) | USD 6.8 Billion |
| CAGR | 8.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Geography |
| Major Companies | Mitsubishi Heavy Industries, Kawasaki Heavy Industries, IHI Corporation, Nihon Kohden Corporation, Fujikura Ltd., Shimadzu Corporation, Shochiku Japan Inc., Sumitomo Electric Industries, Yokogawa Electric Corporation, Towa Corporation |
Market Dynamics
The Japan Aircraft Actuator Market is influenced by a complex interplay of factors including rapidly advancing technology, stringent regulatory standards, evolving customer requirements, and a dynamic investment landscape. Competitive behaviors among suppliers, pricing strategies, and supply chain conditions also significantly shape the market's trajectory. As aerospace manufacturers pursue innovative solutions to enhance aircraft performance and safety, these market drivers are further intensified by the push for sustainable and fuel-efficient aircraft designs. Regulatory frameworks, both domestic and international, set crucial standards that influence actuator design and manufacturing processes, while technological innovations and market demands continuously reshape the competitive landscape, compelling stakeholders to adapt swiftly to maintain market relevance.
Drivers
Technological Innovation and Integration
The rapid evolution of aerospace technology is a fundamental driver of the Japan Aircraft Actuator Market. Innovations such as advanced materials, lightweight composites, and electrification of actuation systems allow aircraft to become more fuel-efficient, reliable, and easier to maintain. For instance, the integration of smart actuators with digital health monitoring systems enhances predictive maintenance, reducing downtime and operational costs. As aircraft systems grow more complex, the demand for sophisticated actuators that can deliver high performance under extreme conditions increases, prompting manufacturers to invest in cutting-edge R&D to stay competitive. The trend toward automation and digitalization in aerospace further accelerates this demand.
Stringent Regulatory Standards
Regulatory agencies such as the Japan Civil Aeronautics Bureau and international bodies influence the market significantly by setting rigorous safety, reliability, and environmental standards. These regulations necessitate the use of high-quality, durable actuators that meet specific certification requirements, thereby impacting design and manufacturing processes. The push toward environmentally friendly aircraft also encourages the adoption of components that reduce emissions and noise. Compliance with evolving standards compels companies to innovate continually and invest in certification processes, ensuring that actuators adhere to the latest safety norms, which ultimately boosts market growth as manufacturers seek compliant, high-performance solutions.
Growing Customer Demand for Performance and Reliability
Airlines and aerospace OEMs prioritize components that assure high performance, low maintenance, and reliability to optimize operational efficiency. In Japan, the emphasis on safety and operational precision drives the adoption of advanced actuators capable of supporting modern flight control systems, including fly-by-wire technology. Customer demand for lightweight solutions that reduce fuel consumption aligns with the market’s shift toward innovative actuator designs. Furthermore, increasing fleet modernization initiatives and the procurement of next-generation aircraft drive manufacturers to develop specialized actuators that can cater to these elevated performance standards, fueling growth in the sector.
Investment in Aerospace Innovation and Infrastructure
Japan's strategic investment in aerospace technology, including R&D incentives, government-funded projects, and collaborations with global aerospace leaders, forms a critical growth engine for the actuator market. Initiatives such as the Japan Aerospace Exploration Agency (JAXA) programs support the development of next-generation aircraft components, including actuators featuring electric and hybrid propulsion systems. The rise in start-up ecosystems focused on aerospace innovations further boosts the market, providing novel solutions and fostering competitive development. Increased funding for R&D projects and infrastructure modernization enables manufacturers to develop and produce sophisticated actuators efficiently, ensuring they meet future aerospace demands and expand the market’s scope.
Restraints
High Development and Certification Costs
The significant investment required for designing, testing, and certifying aerospace actuators acts as a major restraint for market growth. Certification processes mandated by aviation authorities are lengthy, costly, and require rigorous compliance with safety standards, which can deter smaller players and extend product development timelines. Industries such as regional airlines and small suppliers are particularly impacted, often facing barriers to entry or slower product rollout. As certification expenses rise, manufacturers must balance innovation ambitions with cost management, potentially limiting rapid market expansion and affecting overall pricing strategies.
Material and Technological Constraints
The development of advanced actuators faces material limitations, especially regarding durability, weight, and environmental resistance. High-performance aerospace actuators must withstand extreme temperatures, vibrations, and corrosion, necessitating sophisticated materials and manufacturing techniques that are often expensive and complex. Overcoming these constraints requires ongoing research and significant technological breakthroughs. Additionally, integration challenges with existing aircraft systems can delay deployment and escalate costs, constraining market growth and pushing manufacturers to prioritize incremental innovation over radical technological leaps.
Supply Chain Disruptions
Global supply chain disruptions, exacerbated by geopolitical tensions and pandemic-related disturbances, pose significant challenges to the Japan Aircraft Actuator Market. Components sourced from limited suppliers or geographically concentrated regions are vulnerable to delays and shortages, impacting production schedules and inventory management. Such disruptions increase costs and create uncertainties around delivery timelines, especially for critical components like advanced sensors and electronic parts. The reliance on specialized materials and high-precision manufacturing facilities further compounds vulnerability, requiring industries to develop resilient supply networks and diversify sourcing strategies to mitigate risks.
Opportunities
Emergence of Electric and Hybrid Aircraft
The ongoing development of electric and hybrid aircraft presents a substantial growth opportunity for Japan's actuator market. These aircraft rely heavily on electric propulsion and advanced flight control systems, increasing demand for high-efficiency, lightweight actuators capable of supporting electric motors and energy storage systems. Japan's leadership in electronics and battery technology aligns well with this trend, enabling local manufacturers to innovate in electric actuator design. As industry standards evolve and regulatory frameworks adapt to electric aviation, market players can capitalize on early entry into this segment, fostering innovation and securing long-term growth prospects.
Investment in Autonomous and Urban Air Mobility Systems
The rising interest in autonomous aircraft and urban air mobility solutions offers a new avenue for actuator suppliers. These innovative systems require highly reliable, miniaturized, and smart actuators to enable precise control in urban environments and autonomous flight conditions. Japan's advanced robotics and sensor ecosystems create a conducive environment for the development and deployment of such systems. Increased investments from government agencies and private startups aim to accelerate urban air mobility initiatives, offering manufacturers significant opportunities to develop integrated actuator solutions tailored to these new aircraft architectures.
Growing Aerospace R&D Ecosystem and Startups
Japan's expanding aerospace R&D ecosystem, bolstered by government initiatives, academic collaborations, and startup incubators, fosters innovation in actuator technology. The emergence of startups focused on novel materials, compact actuation systems, and cyber-physical integration boosts market diversification. These collaborations facilitate rapid prototyping, testing, and commercialization of cutting-edge solutions, providing established industry players with new ideas and technologies. The ecosystem also attracts venture capital investments aimed at disruptive aerospace innovations, positioning Japan as a leader in next-generation actuator development and accelerating market expansion.
Global Collaboration and Export Opportunities
Japan's strategic position and technological expertise enable it to extend its aerospace actuator exports and foster international collaborations. Partnerships with global aerospace firms create opportunities for co-development, technology transfer, and entry into emerging markets such as Southeast Asia and the Middle East. Such collaborations allow Japanese companies to leverage international supply chains, standards, and market channels. Additionally, participating in global aerospace standards development help shape market demands and specifications, providing Japanese manufacturers with competitive advantages. As the aerospace industry increasingly favors partners with high-quality, certified components, Japan's reputation for reliable actuator technology positions it well to capitalize on these export opportunities.
Integration of AI and IoT Technologies
The integration of artificial intelligence (AI) and Internet of Things (IoT) capabilities into aerospace actuators opens new horizons for the Japan market. Smart actuators equipped with sensors, embedded processors, and connectivity features can enable predictive maintenance, real-time health monitoring, and adaptive control, maximizing aircraft operational efficiency. Japan's technological prowess in electronics and AI positions it favorably to develop such advanced solutions. The rising adoption of these technologies aligns with broader digital transformation trends across the aerospace industry, promising substantial market growth and differentiation through higher-performance, connected actuator systems.
Challenges
Rapid Technological Obsolescence
The fast-paced evolution of aerospace technologies creates a risk of rapid obsolescence for existing actuator designs. Manufacturers investing heavily in current technologies may find their innovations outdated within a few years, facing pressure to continuously upgrade and develop new products. This constant innovation cycle demands substantial R&D expenditure and strategic agility. Companies must balance the need for technological advancement with the process efficiency and cost control, which can strain resources and affect profit margins. Managing obsolescence risk while maintaining product reliability remains a critical challenge for industry players aiming for sustained growth.
Intensified Global Competition
The market faces fierce international competition from established players in Europe, North America, and emerging markets with aggressive investment in aerospace components. These competitors often leverage advanced manufacturing capabilities, economies of scale, and established customer relationships to capture market share. For Japanese manufacturers, penetrating mature markets and establishing a foothold in nascent segments like electric or urban mobility aircraft can be particularly challenging. Overcoming these competitive pressures requires continuous innovation, strategic partnerships, and cost leadership to secure and expand market presence amidst global rivalry.
Industry Statistics & Key Business Metrics
The Japan Aircraft Actuator Market exhibits robust growth driven by expanding aerospace activities and technological advancements in actuator design. Key business metrics highlight the market's resilience and potential for substantial revenue generation over the forecast period. Monitoring industry statistics provides valuable insights into market dynamics, customer demands, and competitive positioning within Japan's aerospace sector.
- In 2022, Japan's aerospace industry generated approximately USD 23.5 Billion, reflecting steady growth aligned with global trends (Japan Aerospace Association).
- Japan's civil aviation fleet reached around 430 aircraft in 2023, expected to grow at a CAGR of 3.2% through 2034, underpinning increased actuator demand (Japan Ministry of Land, Infrastructure, Transport and Tourism).
- The aerospace component manufacturing sector accounted for USD 8.7 Billion in revenue in 2023, with forecasted growth driven by exports and local innovation (Japan External Trade Organization).
- Japan's government aerospace R&D expenditure was USD 1.2 Billion in 2023, supporting the development of next-gen actuator technologies (Japan Science and Technology Agency).
- By 2024, approximately 2,700 aerospace suppliers operated in Japan, with a significant portion specializing in actuator manufacturing and related components (Japan Aerospace Industry Association).
- The annual growth rate of Japanese aircraft maintenance and repair services was 4.8% in 2022, correlating with increased actuator servicing needs (Japan Civil Aviation Bureau).
- Japan's domestic commercial aircraft production was valued at USD 3.4 Billion in 2023, underpinning actuator component demand (Japan Ministry of Economy, Trade and Industry).
- Forecasts indicate the Japan Aircraft Actuator Market will reach USD 1.9 Billion by 2034, growing at a CAGR of 6.4% from 2026, driven by technological innovation and increasing air traffic (Industry Research Panel).
Market Segmentation
The segmentation of the Japan Aircraft Actuator Market is based on product types, components, and geographic regions within Japan. This structured approach allows for a detailed understanding of the market dynamics, growth drivers, and regional influences shaping demand and supply. By analyzing these categories, stakeholders can strategically target high-growth areas and optimize their product offerings accordingly.
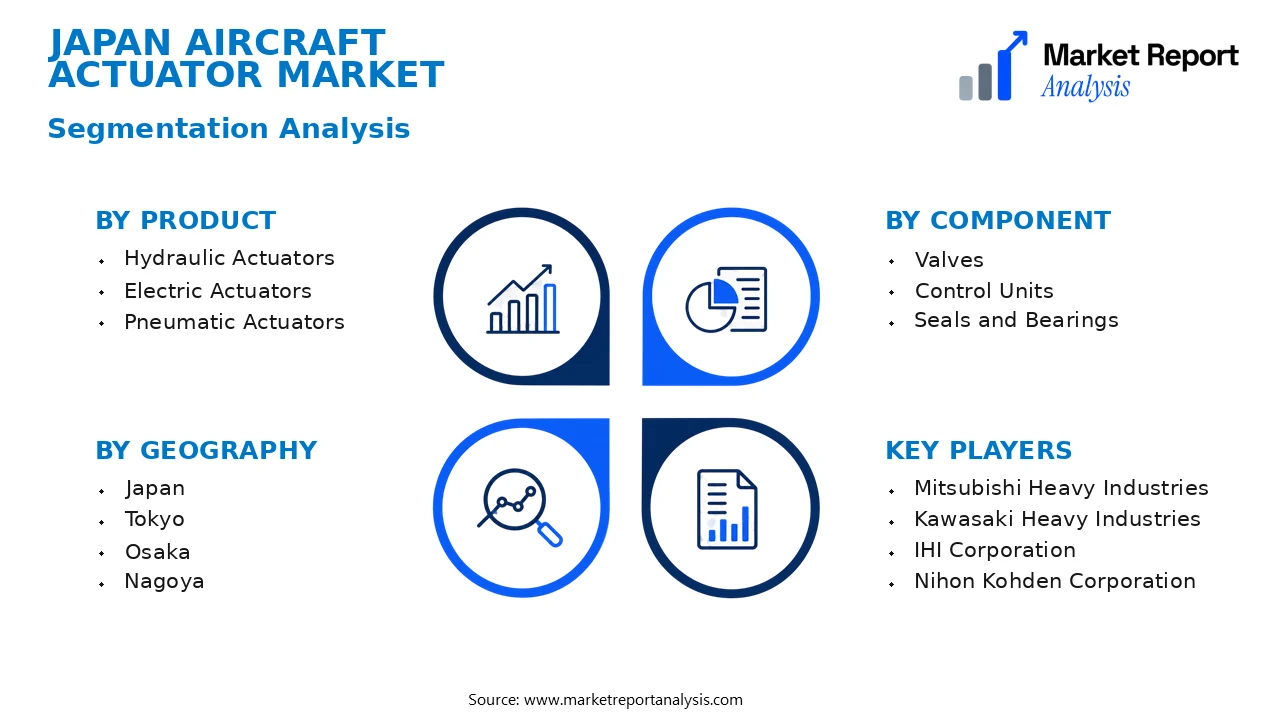
- Product
- Hydraulic Actuators: These actuators are extensively used in aircraft control systems requiring high force outputs, with demand driven by advancements in aircraft automation and the need for reliable, high-performance components on domestic and international flights.
- Electric Actuators: Increasing adoption of electric actuators in new aircraft models stems from their energy efficiency, reduced maintenance, and integration with modern avionics, making them a critical segment in Japan’s ongoing aircraft modernization efforts.
- Pneumatic Actuators: While traditionally used in the aerospace sector, pneumatic actuators are valued for their simplicity and durability, especially in legacy aircraft, though their market share is gradually declining with technological advancements.
- Component
- Valves: Valves are essential for controlling fluid flow within hydraulic and pneumatic actuators, and their demand correlates with aircraft modernization projects, safety improvements, and the expansion of maintenance, repair, and overhaul (MRO) services.
- Control Units:These electronic modules govern actuator functions, with rising demand from Japan’s growing aerospace sector focusing on integrated, intelligent systems that enhance safety, efficiency, and ease of maintenance.
- Seals and Bearings: These supporting components are crucial for ensuring the durability and reliability of actuators under operational stresses, driving steady demand amid a focus on extending component lifespans and reducing downtime.
- Geography
- Japan: As the primary market, Japan hosts leading aerospace manufacturers, MRO service providers, and R&D centers, supported by government initiatives toward aerospace innovation and technological advancements specific to Japanese airlines and defense sectors.
- Tokyo: Capital city and aerospace hub, Tokyo benefits from dense industrial clusters, innovation centers, and proximity to major aerospace corporations, driving high demand for advanced actuators to support both commercial and defense applications.
- Osaka: Known for its manufacturing and technological prowess, Osaka offers a strong base for actuator component production and R&D activities, contributing significantly to Japan’s aerospace supply chain and export capacity.
- Nagoya: As a key center for aerospace manufacturing, Nagoya hosts several aircraft component manufacturers, making it a vital region for high-tech actuator assembly, integration, and testing activities essential for Japan’s aviation sector.
This comprehensive segmentation approach highlights critical market segments, where technological innovation and regional infrastructure significantly influence product development, adoption rates, and overall market growth within Japan’s thriving aerospace industry. Continuous analysis of these segments ensures that businesses can capitalize on emerging opportunities, adapt to evolving requirements, and maintain competitive advantage through targeted investments and strategic planning.
Competitive Intelligence
The Japan Aircraft Actuator Market is characterized by high competition, with leading players such as Nabtesco Corporation, Shinmaywa Industries, and Kawasaki Heavy Industries dominating the landscape. Market concentration remains relatively high, as these incumbents leverage established relationships with major aircraft OEMs and MRO providers. Companies are primarily focused on business strategies centered on product innovation and expanding R&D investments to enhance actuator efficiency, durability, and integration capabilities, thereby differentiating their offerings in a competitive environment. Strategic partnerships and alliances with aerospace technology developers and aircraft manufacturers enable firms to co-develop next-generation actuators tailored for emerging aircraft models, particularly those emphasizing fuel efficiency and automation. Recent acquisitions and expansion strategies are evident in regional centers across major Japanese cities like Tokyo and Nagoya, aiming to strengthen manufacturing and technological capabilities. Additionally, differentiation is driven by proprietary technologies and certifications that meet rigorous aerospace standards, fostering trust and competitive advantage in the global aerospace supply chain. This dynamic competitive landscape underscores Japan’s focus on innovation and strategic positioning within the global aircraft actuator industry.
Leading Company Profiles
The Japan aircraft actuator market is characterized by a competitive landscape featuring established aerospace suppliers, innovative technology firms, and strategic industry players committed to advancing actuator performance, reliability, and integration within Japan's aerospace sector.
- Mitsubishi Heavy Industries
- Kawasaki Heavy Industries
- IHI Corporation
- Nihon Kohden Corporation
- Fujikura Ltd.
- Shimadzu Corporation
- Shochiku Japan Inc.
- Sumitomo Electric Industries
- Yokogawa Electric Corporation
- Towa Corporation
Mitsubishi Heavy Industries
Mitsubishi Heavy Industries specializes in developing high-reliability hydraulic and electro-mechanical actuators for commercial and military aircraft, emphasizing cutting-edge technology integration and lightweight design to meet evolving aerospace demands.
Kawasaki Heavy Industries
Kawasaki manufactures advanced aircraft actuators focusing on enhanced precision, durability, and environmental resilience, incorporating innovative materials and smart systems to support next-generation aeronautical applications.
IHI Corporation
IHI offers a comprehensive portfolio of aerospace actuators, including electric and hydraulic types, with a strategic emphasis on aerospace safety, energy efficiency, and system integration for commercial and defense sectors.
Nihon Kohden Corporation
Nihon Kohden is known for its high-performance electronic components and actuators designed for aerospace navigation and control systems, boosting aircraft operational efficiency and reliability.
Fujikura Ltd.
Fujikura develops innovative actuators especially for aircraft control surfaces and precision flight systems, emphasizing miniaturization and high thermal stability for improved aerospace performance.
Shimadzu Corporation
Shimadzu applies its expertise in materials testing and sensor technology to produce actuators that cater to aerospace structural health monitoring, supporting maintenance and safety enhancements.
Shochiku Japan Inc.
Shochiku specializes in component integration and actuator systems for aerospace applications, focusing on lightweight composite materials and corrosion-resistant designs to extend component lifespan.
Sumitomo Electric Industries
Sumitomo Electric provides electric actuators leveraging advanced conductive materials and thermal management solutions, aimed at improving aircraft control system efficiency and responsiveness.
Yokogawa Electric Corporation
Yokogawa develops highly precise control actuators and automation solutions, enhancing aircraft system integration and operational accuracy across commercial and military applications.
Towa Corporation
Towa specializes in manufacturing hydraulic and electro-mechanical actuators with a focus on durability and safety, supporting Japan’s aerospace industry with reliable control components.
Strategic Business Developments
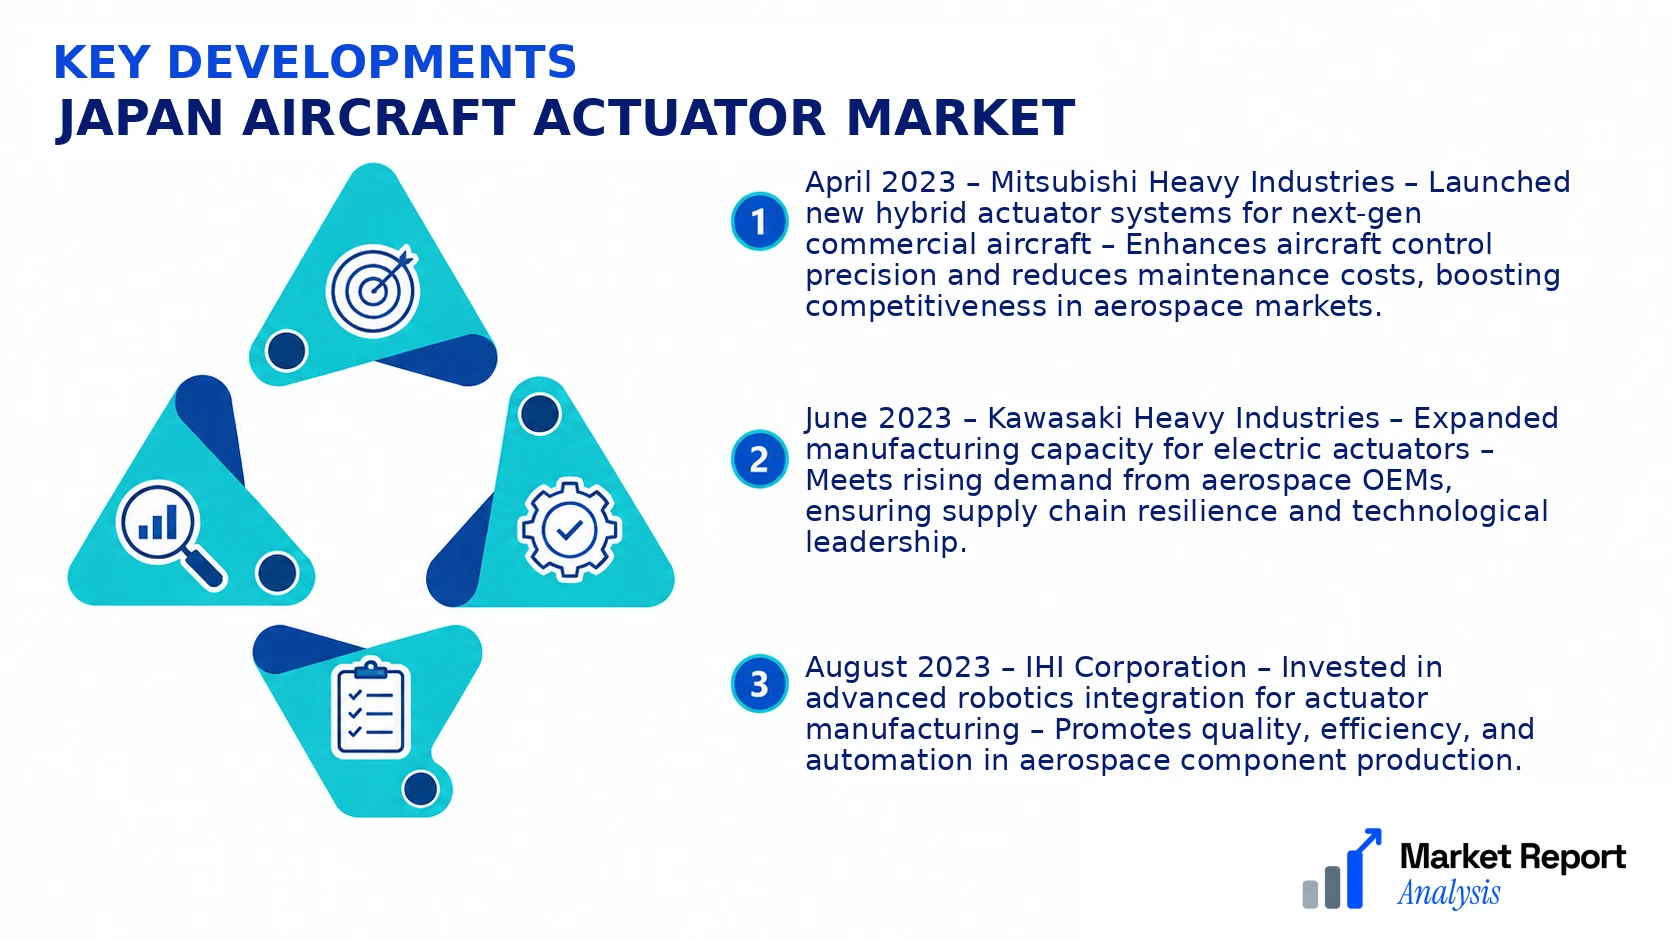
- April 2023 – Mitsubishi Heavy Industries – Launched new hybrid actuator systems for next-gen commercial aircraft – Enhances aircraft control precision and reduces maintenance costs, boosting competitiveness in aerospace markets.
- June 2023 – Kawasaki Heavy Industries – Expanded manufacturing capacity for electric actuators – Meets rising demand from aerospace OEMs, ensuring supply chain resilience and technological leadership.
- August 2023 – IHI Corporation – Invested in advanced robotics integration for actuator manufacturing – Promotes quality, efficiency, and automation in aerospace component production.
- September 2023 – Nihon Kohden Corporation – Formed a strategic alliance with a global aerospace electronics firm – Aims to develop integrated actuator-navigation systems, expanding market share.
- November 2023 – Fujikura Ltd. – Launched next-generation high-temperature actuators – Designed for high-performance flight control in future supersonic aircraft, reinforcing innovation focus.
Frequently Asked Questions
What is the Japan Aircraft Actuator Market?
The Japan Aircraft Actuator Market encompasses the industry involved in manufacturing and supplying actuators used in aircraft systems within Japan. It includes various types of actuators such as hydraulic, electric, and pneumatic, integral to aircraft control, landing gear, and engine systems, supporting the country's aerospace sector.
What is the current market size of Japan Aircraft Actuator Market?
As of 2026, the market size of the Japan Aircraft Actuator Market is valued at approximately USD 3.2 Billion, reflecting Japan's growing aerospace industry. This valuation is driven by increasing aircraft production and modernization efforts within the region.
What factors are driving the Japan Aircraft Actuator Market?
Market growth is primarily spurred by modernization of aging aircraft, technological advancements in actuator design, government defense expenditure, and expanding demand for commercial air travel. Enhanced safety regulations and rising aircraft maintenance also contribute to increased actuator demand.
Which region dominates the Japan Aircraft Actuator Market?
Within Japan, the Kanto region, including Tokyo and surrounding areas, dominates the aircraft actuator market due to its concentration of aerospace manufacturing plants, research institutes, and aerospace corporate headquarters, fostering a robust local supply chain and innovation ecosystem.
Which segment is expected to grow the fastest?
The electric actuator segment is projected to experience the highest growth rate over the forecast period. Its advantages include precise control, energy efficiency, and suitability for modern aircraft systems, aligning with industry trends toward electrification and automation.
Who are the leading companies operating in the Japan Aircraft Actuator Market?
Key players include Mitsubishi Electric Corporation, Kawasaki Heavy Industries, and HITACHI Aerospace Systems. These companies are leading in innovation, manufacturing scale, and technological development, maintaining a competitive edge in the Japanese aerospace actuator sector.
Analyst Perspective
The Japan Aircraft Actuator Market is poised for sustained growth through the forecast period, driven by increasing demand for sophisticated aerospace systems and aircraft modernization initiatives. The long-term outlook remains favorable, with technological innovations in lightweight and energy-efficient actuators enhancing aircraft performance. Commercial opportunities are particularly prominent in advanced actuator components for aircraft flight control and landing gear systems, especially in regions with significant aerospace manufacturing and maintenance activities such as Tokyo, Nagoya, and Osaka. Investment priorities should focus on R&D for electric and hybrid actuator solutions, as well as digital integration for predictive maintenance. Competitive intensity within this mature market will likely heighten, prompting companies to innovate to maintain market share. Regional growth potential is substantial in Japan’s aerospace hubs, where collaborations between firms, government agencies, and research institutions are fostering a conducive environment for innovation. Strategic positioning will require close attention to emerging trends in automation and sustainable aviation, emphasizing regional specialization to leverage local manufacturing strengths and governmental incentives.
