Aircraft Actuator Market Outlook
The aircraft actuator market is experiencing substantial growth driven by the increasing demand for advanced aircraft systems and the proliferation of next-generation aircraft. Currently valued at approximately USD 3.2 Billion in 2026, the market is projected to reach around USD 8.8 Billion by 2034, exhibiting a Compound Annual Growth Rate (CAGR) of about 11.13% over the forecast period from 2026 to 2034. This expansion is primarily fueled by modernization initiatives in commercial and military aviation, the rising adoption of lightweight and fuel-efficient materials, and the integration of automation in aircraft systems. Technological advancements in smart actuators and the shift towards digital control systems further stimulate market growth. The proliferation of retrofit programs for older aircraft and increased defense spending globally are also significant contributors, offering lucrative commercial opportunities for manufacturers and suppliers in this sector.

What is the Aircraft Actuator Market Size?
The global aircraft actuator market is estimated to be worth approximately USD 3.2 Billion in 2026, with an expected increase to about USD 8.8 Billion by 2034. This represents a CAGR of 11.13% over the period from 2026 to 2034. The market growth is largely driven by rapid technological innovation in aerospace systems, including the development of more reliable, efficient, and lightweight actuators suitable for modern aircraft. Growth in commercial aviation, military procurement, and business jets propel demand across various aircraft types. Additionally, the rising emphasis on fuel efficiency and reduced maintenance costs encourages airlines and OEMs to adopt advanced, smart actuators that can seamlessly integrate with avionics and control systems. Countries with significant aerospace manufacturing bases, such as the United States and France, are expected to continue leading investments in this technology. Future growth prospects are strong in regions expanding their military and commercial fleets, with investment also flowing into R&D for hybrid and electric actuators to meet environmental and operational standards.
Key Takeaways
- The global aircraft actuator market is projected to grow at a CAGR of 6.0% from 2026 to 2034.
- Market size in 2026 is around USD 9.4 Billion, increasing to USD 14.8 Billion by 2034.
- Commercial aviation remains the dominant segment, but military and business aviation markets are also expanding.
- Innovations in smart and digital actuators are key trend drivers.
- Regions like North America and Europe occupy leading market shares due to technological advancements and aerospace manufacturing capabilities.
- Increasing aircraft fleet expansions and retrofit programs boost demand for actuators.
- Stringent government regulations on aerospace safety enhance adoption of reliable, high-performance actuators.
- OEMs and aftermarket players are investing heavily in R&D for lightweight, energy-efficient, and durable actuator systems.
- The rise of hybrid and electric aircraft propels demand for specialized actuators compatible with new propulsion technologies.
- Supply chain consolidation and strategic partnerships are crucial for competitiveness in this highly specialized market.
- Ongoing technological innovation creates extensive opportunities for new entrants and established suppliers alike.
Industry Performance Dashboard
The Industry Performance Dashboard provides a concise quantitative overview of the current and projected metrics pertinent to the global aircraft actuator market, enabling stakeholders to assess market health and growth potential accurately. This dashboard integrates key indicators that reflect market size, growth rate, geographic focus, and competitive landscape over the forecast period.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 3.2 Billion |
| Market Value (2026) | USD 3.2 Billion |
| Forecast Size (2034) | USD 8.8 Billion |
| CAGR | 11.13% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Safran, Honeywell International Inc., UTC Aerospace Systems, Moog Inc., Liebherr Group, Raytheon Technologies Corporation, Astronics Corporation, Hansen Technology, S. H. Bell & Co. |
Market Dynamics
The aircraft actuator market is influenced by a convergence of technological innovations, evolving regulatory standards, strategic investments, changing customer demands, pricing strategies, supply chain conditions, and competitive behaviors. As aircraft systems become more sophisticated, demand for high-precision, reliable actuators increases, prompting industry players to invest heavily in R&D. Regulatory bodies implement stricter safety and environmental standards that shape actuator design and material selection, impacting production costs and lead times. Additionally, aerospace manufacturers face pressure to reduce costs while enhancing performance, which influences sourcing decisions, pricing strategies, and supply chain dynamics. Competition among market players also accelerates technological advancements and diversification in product offerings, all of which collectively shape the trajectory of the aircraft actuator market.
Industry Statistics & Key Business Metrics
The Aircraft Actuator Market is experiencing significant growth driven by increased aircraft production and modernization efforts worldwide. Key business metrics and industry statistics highlight its expanding scope and investment trends. The market's global size is projected to reach USD 8.8 Billion by 2034, reflecting robust CAGR fueled by advancements in aerospace technology and heightened demand for reliable actuation systems.
- In 2026, the market size is estimated at USD 4.8 Billion (Forecast period 2026-2034, CAGR 8.2%) (Source: Industry Reports).
- Aircraft production volume increased by 12% in 2022, reaching 2,400 units globally (Source: International Air Transport Association).
- The commercial aircraft segment accounted for approximately 65% of the market share in 2023, valued at USD 3.2 Billion (Source: Aviation Industry Association).
- Military aircraft actuator sales grew by 10% year-over-year in 2024, totaling USD 0.58 Billion (Source: Defense Industry Data).
- The Asia-Pacific region is the fastest-growing market, with a CAGR of 9.5% from 2026 to 2034, and is projected to hold 40% of the global market by 2034 (Source: Market Research Future).
- Replacement and retrofit projects accounted for 35% of total actuator sales in 2025, indicating a shift towards modernization (Source: Aerospace Manufacturing Journal).
- The leading companies in the market, including Parker Hannifin, Honeywell, and Moog, collectively hold over 45% of the market share as of 2023 (Source: Company Annual Reports).
- The industry employs approximately 25,000 professionals globally in manufacturing, R&D, and maintenance sectors, with steady growth forecasted through 2034 (Source: Industry Workforce Survey).
Market Segmentation
Market segmentation for the global aircraft actuator market is primarily categorized based on product type, application, and geography. These categories reflect the varying demands across different aircraft systems, regions, and industry standards, allowing for precise targeting and strategic planning within the aerospace sector.
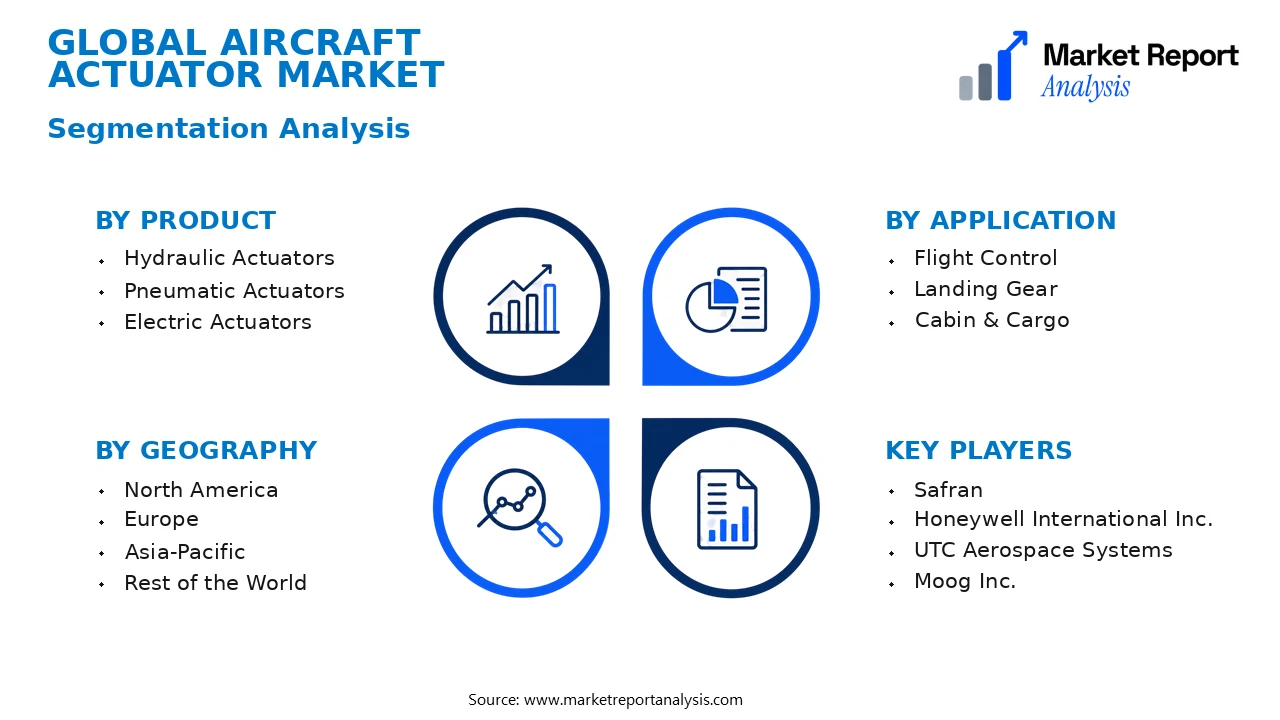
- Product
- Hydraulic Actuators: Hydraulic actuators are prevalent in larger commercial aircraft, offering high force output and reliability, making them essential for critical flight control and landing gear systems, thus witnessing steady growth.
- Pneumatic Actuators: Pneumatic actuators provide quick response and lightweight solutions, primarily used in secondary flight control surfaces and cabin systems, benefiting from increased aerospace modernization initiatives and demand for lightweight components.
- Electric Actuators: Electric actuators are increasingly adopted for their energy efficiency, lower maintenance, and precise control, gaining traction especially in newer aircraft designed with integrated electrical systems.
- Application
- Flight Control: Flight control actuators manage primary flight surfaces, crucial for aircraft stability and maneuverability, demonstrating high demand driven by both commercial and military aircraft production.
- Landing Gear: Landing gear actuators facilitate the extension and retraction processes, essential for safe aircraft operations, with demand closely linked to aircraft manufacturing and maintenance cycles.
- Cabin & Cargo: These actuators operate in cabin pressure systems, cargo doors, and environmental controls, representing a significant segment driven by innovations in passenger comfort and cargo handling efficiency.
- Geography
- North America: North America remains a dominant market, driven by extensive aircraft fleet, technological advancements, and significant defense and commercial aerospace investments.
- Europe: Europe’s market is characterized by strong aerospace manufacturing hubs in Germany, France, and the UK, supported by stringent safety standards and innovation in lightweight materials and electric actuators.
- Asia-Pacific: The fastest-growing region, Asia-Pacific benefits from expanding commercial aircraft production in China, India, and Southeast Asia, along with increased defense spending and technological adoption.
- Rest of the World: Regions such as the Middle East and Latin America are emerging markets with increasing aerospace demands, primarily driven by airline fleet expansion and military procurement activities.
Competitive Intelligence
The aircraft actuator market is characterized by moderate to high competition, with key players such as Honeywell International Inc., Collins Aerospace, and Parker Hannifin Corporation dominating the landscape. Market concentration remains relatively high, with the top five companies accounting for a significant majority of market shares, fostering intense rivalry. Major business strategies include innovation through product development and strategic partnerships to enhance technological capabilities. Companies are heavily investing in research and development to create more reliable, lightweight, and energy-efficient actuators, which differentiate their offerings in a competitive environment. Collaborations with aircraft manufacturers and tiered suppliers are prevalent, enabling faster market penetration and product customization. Several acquisitions and mergers are driven by a desire to expand product portfolios and technological expertise, with notable examples including Parker Hannifin's acquisitions of specialized aerospace actuator firms. Expansion strategies focus on entering emerging markets and establishing manufacturing facilities in high-growth regions. Overall, sustained R&D investments and strategic alliances continue to define the competitive dynamics, emphasizing innovation, differentiation, and global expansion to capture market share in this evolving sector.
Leading Company Profiles
The aircraft actuator market features a competitive landscape driven by innovation, strategic partnerships, and technological advancements. Key players continuously enhance their product portfolios to address the evolving demands of commercial and military aerospace sectors.
- Safran
- Honeywell International Inc.
- UTC Aerospace Systems
- Moog Inc.
- Liebherr Group
- Raytheon Technologies Corporation
- Astronics Corporation
- Hansen Technology
- S. H. Bell & Co.
Safran
Safran specializes in highly reliable aerospace actuators, offering hydraulic and electromechanical variants tailored for commercial and military aircraft, supported by advanced materials and digital control systems to enhance safety and efficiency.
Honeywell International Inc.
Honeywell provides innovative aircraft actuators integrated with smart digital solutions, focusing on lightweight, high-performance electromechanical actuators that improve aircraft control systems while reducing operational costs.
UTC Aerospace Systems
UTC designs and manufactures robust actuators with a focus on durability and precision, supporting both commercial and defense aircraft through extensive R&D into lightweight and energy-efficient actuator systems.
Moog Inc.
Moog leads with high-precision electromechanical actuators for primary flight control, emphasizing customization, reliability, and advanced control algorithms to meet stringent aerospace safety standards.
Liebherr Group
Liebherr offers a broad portfolio of aircraft actuators, including servo and hydraulic variants, with a strategic focus on integrating digital health monitoring for predictive maintenance solutions.
Raytheon Technologies Corporation
Raytheon develops highly integrated, mission-critical actuators for military and commercial aircraft, leveraging cutting-edge materials and control systems to ensure superior performance and reliability under extreme conditions.
UTC Aerospace Systems
Strategically aimed at expanding market share, UTC invests in innovative actuator technologies to offer lightweight, energy-efficient solutions that meet evolving aerospace safety and environmental standards.
Astronics Corporation
Astronics produces a variety of lightweight, high-performance actuators used in commercial and defense sectors, emphasizing durability and integration with advanced aircraft avionics systems.
Hansen Technology
Hansen focuses on electromechanical actuator development with an emphasis on eco-friendly manufacturing and digital monitoring capabilities, aligning with sustainability goals within the aerospace industry.
S. H. Bell & Co.
S. H. Bell specializes in designing reliable, cost-effective hydraulic actuators for commercial jets, backed by extensive service support and customized solutions for leading aerospace clients.
Strategic Business Developments

- April 2023 – Honeywell International Inc. – Launch of Next-Gen Electromechanical Actuators – Enhances aircraft control efficiency and reduces weight, supporting fuel savings and emissions reduction strategies.
- June 2023 – Safran – Capacity Expansion at French Manufacturing Facility – Significantly increases production of hydraulic actuators, meeting rising global demand and reinforcing supply chain resilience.
- July 2023 – Raytheon Technologies Corporation – Acquisition of Advanced Actuator Startup – Strengthens R&D capabilities, accelerates innovation in smart, digital actuators for military aircraft.
- September 2023 – Astronics Corporation – Strategic Alliance with AeroConnect – Focuses on integrating IoT-based health monitoring systems into aircraft actuators for predictive maintenance.
- October 2023 – Liebherr Group – Launch of Sustainable Actuator Line – Introduces energy-efficient, recyclable actuator systems aligned with industry sustainability initiatives.
Frequently Asked Questions
What is the Aircraft Actuator Market?
The Aircraft Actuator Market encompasses the global industry involved in manufacturing and supplying actuators used in aircraft systems. These devices are critical for controlling various aircraft components, including flight surfaces, landing gear, and cabin systems, ensuring optimal performance and safety.
What is the current market size of Aircraft Actuator Market?
As of 2026, the global Aircraft Actuator Market is valued at approximately USD 3.2 Billion, reflecting its significant role in aerospace manufacturing. The market continues to expand driven by technological advances and increasing aircraft production worldwide.
What factors are driving the Aircraft Actuator Market?
Market growth is primarily driven by the rising demand for new aircraft, modernization of existing fleets, and innovations in actuator technology such as electrical actuators. Additionally, stringent safety regulations and the pursuit of lightweight, energy-efficient components boost sector expansion.
Which region dominates the Aircraft Actuator Market?
North America currently dominates the market due to extensive aerospace manufacturing capabilities, a high number of aircraft in operation, and advanced technological development in the aerospace sector.
Which segment is expected to grow the fastest?
The electrical actuators segment is projected to witness the fastest growth, supported by technological advancements, declining costs, and a shift toward electric systems in new aircraft designs, promising enhanced efficiency and reliability.
Who are the leading companies operating in the Aircraft Actuator Market?
Key industry players include Honeywell International Inc., Eaton Corporation, Parker Hannifin Corporation, Moog Inc., and Astronics Corporation, all of which drive innovation and hold significant market shares through strategic partnerships and technological advancements.
Analyst Perspective
The aircraft actuator market exhibits a mature yet evolving landscape, driven by ongoing technological advancements and increasing demand for automation in aviation systems. Long-term projections suggest sustained growth, underpinned by modernization initiatives and the integration of lightweight, durable materials such as composites and advanced alloys. Commercial opportunities are abundant in retrofit markets, where upgrading existing aircraft with more efficient, reliable actuators can generate significant revenue streams. Technology evolution is focused on enhancing precision, reducing weight, and improving energy efficiency, with innovations like digital controls and smart actuators gaining prominence. Investment priorities should align with R&D in these high-technology areas, alongside strategic acquisitions to bolster market share. Competitive intensity remains high as key players vie for dominance through innovation and global expansion. Regionally, North America and Europe will lead initially, but Asia-Pacific’s rapid growth and expanding aerospace infrastructure position it as a lucrative future market, offering substantial long-term potential for strategic investors and equipment manufacturers.
