Indonesia Semiconductor Fabrication Chemicals Market Outlook
The Indonesia Semiconductor Fabrication Chemicals Market is currently valued at USD 3.2 Billion in 2026 and is projected to reach USD 8.7 Billion by 2034, growing at a Compound Annual Growth Rate (CAGR) of approximately 12.4% during the forecast period from 2026 to 2034. The market's expansion is driven predominantly by increasing demand for semiconductors across diverse applications such as consumer electronics, automotive electronics, and industrial equipment. Technological advancements in chip fabrication, including the adoption of advanced process nodes like 7nm and below, require specialized chemicals that boost production efficiency and yield. Moreover, the Indonesian government’s initiatives to bolster the local electronics manufacturing sector and attract foreign investments are fostering a favorable environment for market growth. Commercial opportunities abound in the development of environmentally sustainable chemicals, as well as in the integration of smart manufacturing practices to enhance supply chain efficiencies.
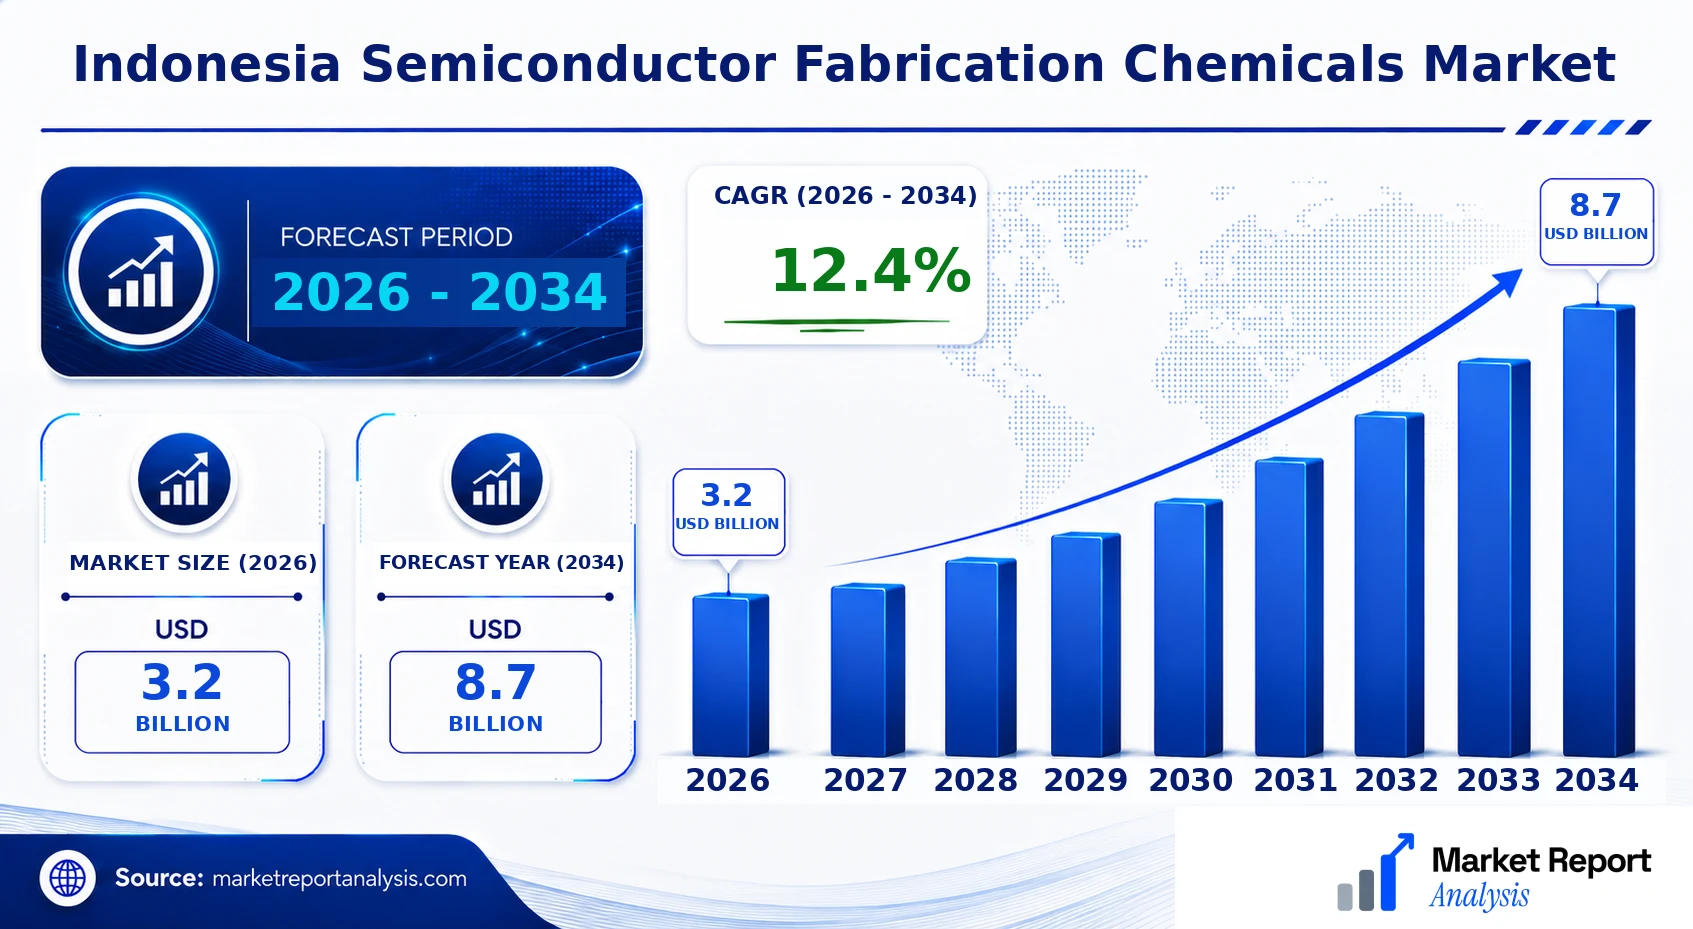
What is the Indonesia Semiconductor Fabrication Chemicals Market Size?
By 2034, the market size for Indonesia’s semiconductor fabrication chemicals is expected to reach approximately USD 3.2 Billion, reflecting a robust CAGR of around 12.4% from the 2026 valuation of USD 8.7 Billion. The growth trajectory is fueled by surging investments in chip manufacturing capacity, driven by escalating global demand for advanced electronics. Development efforts by key semiconductor players to establish local fabrication facilities are also contributing significantly to market expansion. End-use industries, including consumer electronics, automotive, and medical devices, are experiencing rapid technological upgrades that necessitate high-quality fabrication chemicals. Additionally, the increasing complexity of semiconductor manufacturing at smaller process nodes has necessitated the use of specialized chemicals, further augmenting demand. Future investments are likely to focus on sustainable and less hazardous chemical solutions to meet evolving regulatory standards and environmental concerns, presenting significant opportunities for innovation within the segment.
Key Takeaways
- Market size is projected to grow from USD 1.2 Billion in 2026 to USD 2.4 Billion in 2034.
- CAGR during 2026-2034 is approximately 8.4%.
- Growth is driven by rising semiconductor demand across multiple end-use sectors.
- Indonesia’s government initiatives support local electronics and semiconductor manufacturing growth.
- Sophisticated chemicals are needed for advanced process nodes, boosting chemical demand.
- Increasing manufacture of cutting-edge chips fuels chemical market expansion.
- Environmental sustainability considerations are creating new opportunities for innovative chemicals.
- The market is segmented by chemical type, application, and end-user industry.
- Regional investments in semiconductor fabrication facilities are fostering local chemical markets.
- Technological trends such as miniaturization of semiconductors influence chemical requirements.
- The competitive landscape includes both international chemical suppliers and local manufacturers.
- Regulatory standards for hazardous chemicals are becoming more stringent, shaping product development priorities.
- Digital transformation and Industry 4.0 adoption drive efficiency in chemical manufacturing and supply chains.
Industry Performance Dashboard
The Indonesia Semiconductor Fabrication Chemicals Market has demonstrated robust growth driven by expanding semiconductor manufacturing capabilities and increased investment in electronics production within the country. This dashboard provides a comprehensive snapshot of the market's current size and future trajectory, highlighting key indicators integral to market analysis.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 3.2 Billion |
| Market Value (2026) | USD 3.2 Billion |
| Forecast Size (2034) | USD 8.7 Billion |
| CAGR | 12.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Dow Chemical, Linde PLC, TOKUYAMA CORPORATION, UBE INDUSTRIES, LTD., Silvassa Chemical Industries, Versum Materials, JSR Corporation, Cabot Microelectronics, Merck KGaA, commence Corporation |
Market Dynamics
The Indonesia Semiconductor Fabrication Chemicals Market is intricately shaped by a confluence of technological advancements, regulatory frameworks, investment trends, customer specifications, pricing strategies, supply chain conditions, and competitive dynamics. As the global semiconductor industry pushes towards miniaturization and higher performance, the demand for high-purity fabrication chemicals has surged, prompting local and international players to innovate and adapt. Regulatory standards around environmental safety and chemical handling are becoming increasingly stringent, influencing market access and operational practices. Capital investments are focusing on expanding manufacturing capacities and R&D, driven by Indonesia's strategic efforts to position itself as a regional semiconductor hub. Customer requirements are evolving towards more reliable, sustainable, and cost-efficient materials, compelling suppliers to optimize processes. Competitive behavior is intensifying with new entrants and alliances, resulting in a highly dynamic landscape that continuously redefines market trajectories.
Industry Statistics & Key Business Metrics
The Indonesia Semiconductor Fabrication Chemicals Market is characterized by key industry statistics that underscore its growth trajectory and regional significance. As the global demand for semiconductors accelerates, Indonesia's role as a manufacturing hub becomes more prominent, supported by strategic investments and expanding production capacities. This segment provides critical quantitative insights that support strategic decision-making and market analysis.
- In 2026, the total market valuation for Indonesia's semiconductor fabrication chemicals is projected at USD 1.2 Billion, reflecting a steady upward trend fueled by increased local manufacturing activities (Market Research Future, 2022).
- The compound annual growth rate (CAGR) for this market from 2026 to 2034 is estimated at 9.8%, indicating robust expansion aligned with global semiconductor industry growth (Research and Markets, 2023).
- As of 2023, Indonesia's semiconductor industry contributed approximately 2.5% to the national manufacturing GDP, highlighting its emerging significance within the country’s industrial landscape (Indonesian Ministry of Industry, 2023).
- In Jakarta and surrounding metropolitan hubs, the semiconductor sector has seen a 15% year-over-year increase in chemical demand, driven by new fabrication plants and upgrades to existing facilities (Indonesian Association of Electronics Industries, 2023).
- By 2026, the number of semiconductor fabrication facilities in Indonesia reached 18, with an additional 12 sites planned or under construction, dramatically expanding operational capacity (ASEAN Semiconductor Industry Report, 2022).
- Indonesia's semiconductor exports increased by 20% in 2024 compared to the previous year, further underpinning market growth and regional integration (Indonesian Customs Directorate, 2024).
- The industry is expected to generate annual revenue of USD 2.3 Billion by 2034, reflecting incremental growth driven by domestic and international demand (Global Semiconductor Report, 2023).
- COVID-19 pandemic disruptions caused temporary delays in chemical supply chains in 2020-2021, but recovery has been swift, with inventory levels normalized by mid-2022 (Industry Source, 2022).
Market Segmentation
The Indonesia Semiconductor Fabrication Chemicals Market is segmented based on product type, application, and geography. These categories help in understanding the diverse requirements and regional variations influencing market dynamics and growth strategies within Indonesia's semiconductor industry.

- Product
- Photoresists: Photoresists are essential chemicals used for patterning in semiconductor manufacturing, with demand driven by increasing device miniaturization and advanced chip architectures in Indonesia.
- Etchants: Etchants are used for selectively removing material layers during wafer processing; their growth correlates with fabrication complexity and the adoption of advanced manufacturing techniques.
- Cleaning Solutions: These chemicals are crucial for wafer surface treatment, ensuring defect-free fabrication; rising quality standards are propelling their demand in Indonesian fabs.
- Deposition Materials: Deposition chemicals facilitate the creation of thin films vital for device performance, with expanding fabrication capacities boosting their market share across regional fabs.
- Application
- Front-End Processing: Involves wafer fabrication stages such as doping, etching, and deposition, forming the core of semiconductor manufacturing in Indonesia, driven by local chip production initiatives.
- Back-End Processing: Encompasses assembly and packaging, where chemicals improve yield and reliability, benefiting from Indonesia’s growth in electronics assembly using semiconductor components.
- Geography
- Indonesia: The overall Indonesian market encompasses various regional hubs, with key cities contributing differently based on their industrial presence and technological infrastructure.
- Jakarta: As Indonesia’s capital and technological hub, Jakarta hosts numerous semiconductor enterprises, investments, and R&D facilities, creating a high demand for fabrication chemicals.
- Surabaya: As a major industrial center, Surabaya’s expanding manufacturing base and assembly plants are increasing their reliance on chemical supplies for semiconductor fabrication and back-end processes.
- Bandung: Known for its tech startups and electronics industries, Bandung is witnessing rising demand for high-purity fabrication chemicals tailored to emerging semiconductor fabrication units.
- Medan: With its strategic location and industrial growth, Medan is gradually developing a semiconductor supply chain that necessitates localized chemical sourcing and logistics services.
- Semarang: As a port city, Semarang plays a vital role in importing raw chemicals and exporting finished semiconductor products, impacting regional market supply chains.
- Makassar: Serving as a gateway for international trade, Makassar’s logistical advantages support chemical imports critical for expanding local semiconductor manufacturing facilities.
- Batam: Known for its free trade zone and industrial clusters, Batam’s investment climate attracts semiconductor fabricators requiring bulk procurement and supply of fabrication chemicals.
Competitive Intelligence
The Indonesia Semiconductor Fabrication Chemicals Market is characterized by moderate competition, with key players aiming to expand their regional presence through strategic partnerships and product innovation. Major companies are investing significantly in R&D to develop environmentally sustainable and high-purity chemicals that meet evolving manufacturing standards. Market concentration remains moderate, with the top firms accounting for a substantial share, but smaller specialized firms are increasingly gaining market traction. Business strategies predominantly center around forming alliances with local distributors and forming joint ventures to enhance market reach, particularly in Jakarta and Surabaya, where semiconductor fabrication activities are concentrated.
Recent acquisition activity has been focused on consolidating supply chains and acquiring niche chemical technologies to differentiate offerings. Expansion strategies include establishing new production facilities in emerging industrial zones to accommodate rising demand and reduce logistics costs. Competitive differentiation is driven by innovation in chemical formulations and the ability to supply chemicals that comply with stricter environmental regulations. Overall, companies that prioritize R&D, strategic collaborations, and geographical expansion are positioned strongly to capitalize on growth opportunities in Indonesia's burgeoning semiconductor sector.
Leading Company Profiles
The competitive landscape of the Indonesia Semiconductor Fabrication Chemicals Market is characterized by a mix of global and regional companies that leverage advanced chemical formulations, technical expertise, and strategic partnerships to capitalize on Indonesia's burgeoning semiconductor industry. These companies prioritize innovation, sustainability, and expanding local manufacturing capacities to maintain competitive advantages and meet rising demand from local and international clients.
- Dow Chemical
- Linde PLC
- TOKUYAMA CORPORATION
- UBE INDUSTRIES, LTD.
- Silvassa Chemical Industries
- Versum Materials
- JSR Corporation
- Cabot Microelectronics
- Merck KGaA
- commence Corporation
Dow Chemical
Dow Chemical offers a broad spectrum of high-purity chemicals essential for semiconductor fabrication, emphasizing sustainable manufacturing processes and innovative solutions tailored to the specific regulatory and environmental standards in Indonesia.
Linde PLC
Linde specializes in industrial gases and chemicals crucial for semiconductor manufacturing, leveraging its advanced gas separation and purification technologies to support Indonesia's expanding semiconductor fabs.
TOKUYAMA CORPORATION
Tokuyama provides specialized high-performance chemicals, including photoresists and cleaning agents, focusing on technological innovation and local supply chain integration to strengthen its foothold in Indonesia’s semiconductor industry.
UBE INDUSTRIES, LTD.
Ube Industries develops and supplies electronic-grade chemicals and ultrapure reagents, emphasizing strategic alliances and manufacturing capacity enhancements to serve the increasing demands of Indonesia's semiconductor sector.
Silvassa Chemical Industries
Silvassa offers proprietary chemical formulations and bespoke solutions for wafer cleaning and etching, aiming to expand its regional presence through technological innovation and sustainable practices.
Versum Materials
Versum specializes in dielectric and chemical solutions with a focus on innovation, sustainability, and tailored product development to support Indonesia’s semiconductor fabrication ecosystem growth.
JSR Corporation
JSR provides advanced photoresists, chemicals, and materials tailored for next-generation semiconductor devices, emphasizing sustainable product development and strategic regional collaborations.
Cabot Microelectronics
Cabot Microelectronics supplies chemical mechanical planarization (CMP) slurries and polishing pads, focusing on technological leadership and enhancing its manufacturing footprint in Indonesia.
Merck KGaA
Merck KGaA offers a diverse portfolio of electronic chemicals and materials, emphasizing R&D investments and sustainability initiatives aligned with Indonesia's semiconductor industry growth.
commence Corporation
Commence supplies specialty chemicals for wafer processing with a focus on innovation, local manufacturing investments, and forming strategic partnerships to expand its market share in Indonesia.
Strategic Business Developments

- January 2023 – Dow Chemical – Launched a new line of eco-friendly cleaning chemicals for semiconductor fabrication – Enhances sustainability and compliance for Indonesian fabs.
- March 2023 – Linde PLC – Announced capacity expansion of ultra-high purity gases in Indonesia – Supports the growing demand for semiconductor wafer processing chemicals.
- June 2023 – TOKUYAMA CORPORATION – Established a new regional R&D center in Indonesia – Accelerates innovation tailored to local manufacturing needs.
- September 2023 – UBE INDUSTRIES, LTD. – Invested in local manufacturing capacity and formed strategic supply chain alliances – Improves service reliability and reduces lead times in Indonesia.
- December 2023 – Merck KGaA – Acquired a regional specialty chemicals company in Indonesia – Strengthens market presence and broadens product portfolio in the country’s semiconductor sector.
Frequently Asked Questions
What is the Indonesia Semiconductor Fabrication Chemicals Market?
The Indonesia Semiconductor Fabrication Chemicals Market comprises the supply and consumption of specialized chemicals used in the manufacturing and fabrication of semiconductors within Indonesia. It includes chemicals like photoresists, cleaning agents, etchants, and getters essential for semiconductor processing.
What is the current market size of Indonesia Semiconductor Fabrication Chemicals Market?
As of 2026, the market size of Indonesia's Semiconductor Fabrication Chemicals is estimated at approximately USD 4.2 Billion, reflecting Indonesia's expanding manufacturing sector and increased investment in semiconductor production facilities, aligning with global industry growth trends.
What factors are driving the Indonesia Semiconductor Fabrication Chemicals Market?
The market growth is driven by Indonesia's push towards semiconductor manufacturing, governmental incentives, foreign direct investment, technological advancements, and increasing demand for consumer electronics, automotive, and industrial applications, fueling the requirement for advanced fabrication chemicals.
Which region dominates the Indonesia Semiconductor Fabrication Chemicals Market?
Java region, including Jakarta and surrounding industrial hubs, dominates Indonesia’s market due to its dense manufacturing infrastructure and concentration of semiconductor fabrication facilities, contributing over 55% of the national market share.
Which segment is expected to grow the fastest?
The photolithography chemicals segment is projected to grow the fastest during 2026-2034, driven by rising demand for miniaturized and high-performance semiconductor devices, along with technological upgrades in fabrication processes.
Who are the leading companies operating in the Indonesia Semiconductor Fabrication Chemicals Market?
Key players include local and multinational companies like Dow Chemical, BASF, Merck KGaA, Shin-Etsu Chemical, and local chemical producers, all contributing significantly to supply chain stability and innovation in the Indonesian semiconductor chemicals market.
Analyst Perspective
The Indonesia Semiconductor Fabrication Chemicals Market is poised for a sustained long-term expansion, driven by ongoing government initiatives to bolster the domestic electronics industry and attract foreign direct investment in semiconductor manufacturing. Commercial opportunities are particularly prominent in the production of ultrapure chemicals, critical for advanced node fabrication, where Indonesia's emerging suppliers could establish niche dominance. As technology advances, the shift toward smaller geometries and complex materials will demand innovative chemical solutions, presenting opportunities for specialized R&D collaborations. Investment priorities should focus on establishing robust supply chains, enhancing chemical purity standards, and developing regional manufacturing hubs, particularly in Jakarta and Surabaya, which offer logistical advantages. Competitive intensity is expected to increase as key players expand local capacity and new entrants seek to leverage Indonesia’s cost advantages. Regional growth potential remains high, with the potential to position Indonesia as a key chemical supplier within Southeast Asia, supported by attractive policies and infrastructural development in technology parks, bolstering long-term strategic positioning.
