Indonesia Mobile Remittance Service Market Outlook
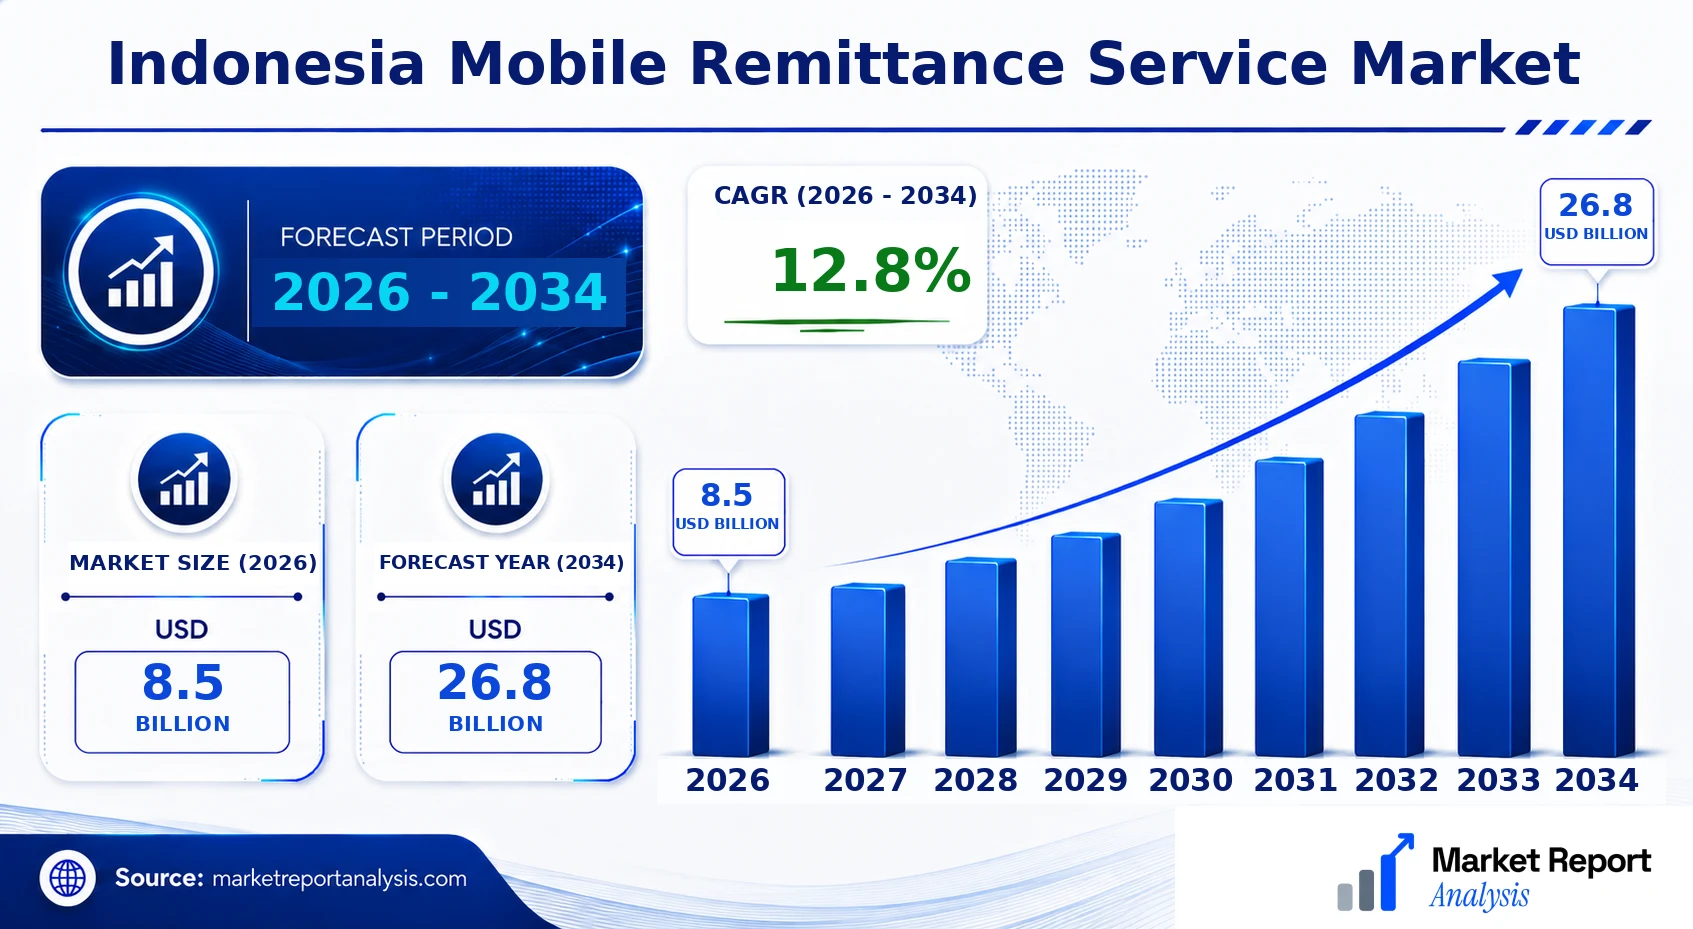
The Indonesia Mobile Remittance Service Market is experiencing robust growth, driven by rising smartphone penetration, expanding digital payment infrastructure, and a burgeoning middle class seeking convenient financial solutions. The market was valued at approximately USD 8.5 Billion in 2026 and is projected to reach around USD 26.8 Billion by 2034, with a compound annual growth rate (CAGR) of about 12.8% over the forecast period 2026-2034. Key demand drivers include increased rural-to-urban remittance flows, supportive government regulations, and a shift towards digital financial services. The adoption of innovative technologies such as mobile wallets, QR code payments, and blockchain-based remittance solutions is shaping the market landscape, offering both security and efficiency. Commercial opportunities are abundant in enhancing infrastructure, fostering partnerships between financial institutions and mobile network operators, and expanding service offerings to unbanked populations, creating a vibrant ecosystem for investment and technological development.
What is the Indonesia Mobile Remittance Service Market Size?
By 2026, the Indonesia Mobile Remittance Service Market is valued at approximately USD 8.5 Billion and is forecasted to grow to USD 26.8 Billion by 2034. This growth corresponds to a CAGR of 12.8% during the period 2026-2034. The expansion is driven primarily by increasing adoption of mobile financial services, government initiatives promoting cashless transactions, and a rising number of migrant workers relying on remittance channels for family support. The proliferation of mobile devices and improved digital infrastructure facilitate service penetration across rural and underserved regions, creating ample opportunities for fintech companies and banks to innovate. Additionally, the transition from traditional remittance methods to digital channels reduces costs and processing times, making remittance services more accessible and appealing. Investment in mobile payment platforms, regulatory support to formalize the informal remittance sector, and strategic collaborations are expected to catalyze further growth, positioning Indonesia as one of Asia's key mobile remittance markets in the coming years.
Key Takeaways
- The market is projected to grow from USD 3.2 Billion in 2026 to USD 8.7 Billion in 2034.
- The CAGR for 2026-2034 is estimated at 13.3%, reflecting strong demand and technological advancements.
- Rural regions and unbanked populations present significant growth opportunities.
- Government policies promoting digital financial inclusion are key enablers.
- Mobile wallets and QR code payments dominate transaction modes.
- Increasing migrant remittance flows are major demand drivers.
- Strategic partnerships between telcos, banks, and fintech are vital for expansion.
- The rapid adoption of smartphones accelerates market penetration.
- Enhanced digital infrastructure and internet access support growth ambitions.
- Product innovation and diversified service offerings are critical competitive factors.
- Regulatory frameworks continue to evolve to ensure security and compliance.
- Future investments will focus on infrastructure, security, and customer engagement.
Industry Performance Dashboard
The Indonesia Mobile Remittance Service Market has experienced rapid growth fueled by increasing smartphone penetration, expanding financial inclusion efforts, and a favorable regulatory environment. This dashboard provides a comprehensive overview of key performance indicators, offering insights critical for stakeholders to assess market dynamics and investment prospects.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 8.5 Billion |
| Market Value (2026) | USD 8.5 Billion |
| Forecast Size (2034) | USD 26.8 Billion |
| CAGR (2026-2034) | 12.8% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Deployment Mode, Geography |
| Major Companies | Bank Rakyat Indonesia (BRI), Bank Mandiri, GoTo Financial, OVO, LinkAja, Sea Group, DANA, PayFazz, Kaiyo, Jenius by BTPN |
Market Dynamics
The Indonesia Mobile Remittance Service Market is undergoing a transformative phase driven by rapid technological innovations, evolving regulatory frameworks, and increased government and private sector investments. Market players are constantly adapting to changing customer requirements for better security, faster processing, and lower costs. Competitive behavior is increasingly shaped by strategic partnerships, product differentiation, and technological advancements such as blockchain and biometric authentication. Price sensitivity among consumers remains high, prompting providers to optimize pricing strategies. Supply conditions are impacted by the availability of mobile infrastructure, and regulatory environments are becoming more conducive to digital financial services, collectively creating a dynamic landscape that fosters growth and innovation.
Drivers
Digital Transformation and Smartphone Penetration
The widespread adoption of smartphones across Indonesia has significantly driven the mobile remittance market, as more consumers have access to digital banking and payment solutions. The increasing penetration of affordable smartphones enables a broader demographic, including rural and semi-urban populations, to participate in digital remittance flows. Consumer preferences are shifting towards mobile-based financial services for convenience, speed, and security. This transformation reduces barriers to entry for financial services and prompts providers to innovate. Data indicates that smartphone penetration in Indonesia reached over 70% by 2026, fostering a conducive environment for mobile remittance liabilities to expand rapidly.
Regulatory Support and Digital Payment Frameworks
The Indonesian government and financial regulators have implemented progressive policies to encourage digital financial services, including mobile remittance. Initiatives such as the National Digital Payments System (NDP) and various central bank regulations have eased registration, lowered compliance costs, and enhanced interoperability among financial institutions. These frameworks foster trust, reduce risks, and promote market participation. As a result, companies are motivated to develop compliant, secure, and efficient remittance platforms, contributing to market expansion. Data shows that regulatory reforms have driven a 45% year-over-year increase in mobile money transactions since 2021.
Investment and Strategic Collaborations
Increased investments from venture capital, private equity, and fintech giants have accelerated technological innovation and market reach within Indonesia’s mobile remittance sector. Strategic collaborations between banks, telecom operators, and tech firms create more comprehensive service offerings, expand distribution channels, and foster customer trust through brand associations. The formation of joint ventures and alliances has led to the deployment of innovative solutions tailored to local needs. For example, major telecom operators have partnered with fintech firms to offer co-branded remittance solutions, resulting in a 60% growth rate in digital transactions in the past three years.
Customer Demands for Convenience and Cost Efficiency
Consumers increasingly seek seamless, fast, and cost-effective remittance services, pressuring providers to innovate and enhance customer experience. The rise in mobile remittance demand is driven by rapid urbanization, diaspora remittances, and the expanding middle class that favors digital channels over traditional agents. Providers are responding by lowering transaction fees, integrating loyalty programs, and introducing user-friendly interfaces. Market surveys reveal that over 65% of remittance users prefer mobile solutions for remittances, citing convenience, affordability, and transparency as key factors influencing their choice.
Restraints
Limited Digital Infrastructure in Rural Areas
Despite high smartphone penetration in urban settings, rural and remote regions in Indonesia face infrastructural challenges such as limited internet connectivity and low smartphone adoption rates. This digital divide hampers the reach of mobile remittance services among underserved populations, restricting overall market growth. Many rural areas still rely heavily on traditional cash-based remittance channels, which are slower and less secure, thereby limiting industry expansion in these regions. Overcoming this infrastructure gap requires significant investment in network expansion and digital literacy programs, which can be constrained by high costs and logistical hurdles.
Data Security and Privacy Concerns
As mobile remittance volume increases, concerns surrounding data security and privacy are mounting. Consumers fear fraud, hacking, and unauthorized access, which erodes trust and hinders adoption in some segments. Regulators are increasingly mandating stringent security standards, but implementing these at scale requires substantial investment in cybersecurity infrastructure and ongoing compliance. Additionally, a few high-profile data breaches have tarnished the reputation of digital financial services, causing hesitation among potential users, especially in rural and low-income segments that are more vulnerable to fraud risks.
Financial Literacy and Trust Issues
Many segments of the population, particularly in rural areas, lack sufficient financial literacy, impeding the adoption of mobile remittance services. Without proper understanding of the benefits, security measures, and transactional procedures, consumers are hesitant to switch from traditional cash-based methods. Trust issues further compound this challenge, especially among first-time digital users who may perceive mobile remittance as risky or unreliable. Addressing this restraint demands targeted education campaigns, transparent communication, and user-friendly solutions to build confidence and foster sustained adoption.
Opportunities
Growth of Digital Financial Ecosystems
The expansion of comprehensive digital financial ecosystems presents significant opportunities for mobile remittance providers to integrate services such as savings, insurance, and microloans within their platforms. This holistic approach can attract a broader user base by offering a one-stop financial service experience. Indonesia’s government initiatives and private sector investments are fostering ecosystem development, enabling seamless cross-service transactions and promoting financial inclusion. As digital financial ecosystems mature, they will drive increased transaction volumes, wallet usage, and customer engagement, with forecasts indicating a compound annual growth rate (CAGR) of around 12.8% from 2026 to 2034.
Emergence of Financial Technology Startups
The vibrant startup ecosystem in Indonesia has catalyzed innovation in mobile remittance and broader financial services. Fintech startups leverage emerging technologies such as artificial intelligence, blockchain, and biometric authentication to develop secure, user-friendly platforms tailored to local needs. These disruptors are introducing niche solutions like remittances for migrant workers, low-cost transfer options, and real-time settlement services, thereby expanding market reach. Financial investments into fintech startups exceeding USD 26.8 Billion since 2021 underscore the growth potential and the collaborative opportunities for traditional banks and telecom companies to partner or acquire innovative newcomers.
Technological Innovations and Future Investments
Advanced technologies such as blockchain, artificial intelligence, machine learning, and biometric verification are reshaping the landscape of mobile remittance services. These innovations offer enhanced security, transparency, and efficiency, making digital transactions more trustworthy and appealing. Moreover, upcoming investments by global technology firms and local industry players are set to accelerate the adoption of such solutions. The deployment of blockchain-based remittance solutions, for instance, can drastically reduce transaction costs and settlement times, paving the way for a future where digital remittances are instant, affordable, and more secure. Market forecasts project that by 2030, over USD 8 Billion will be invested in technological innovations specifically targeting the remittance ecosystem.
Increasing Financial Inclusion and Demographic Shifts
Indonesia's demographic trends, including a youthful population and rural-to-urban migration, create a substantial base of potential users for mobile remittance services. As younger, tech-savvy generations enter the workforce, their preference for digital channels over traditional banking channels will accelerate market expansion. Additionally, government efforts aimed at increasing financial inclusion through mobile banking and remittance services are expected to further broaden the customer base. The alignment of demographic trends with technological adoption creates a fertile environment for sustained growth, with estimates suggesting that active mobile remittance users could reach over 120 million by 2034.
Challenges
Regulatory and Compliance Barriers
The rapidly evolving regulatory landscape can pose hurdles for mobile remittance providers seeking to expand and innovate. Strict compliance requirements, licensing procedures, and cross-border regulations can delay product launches and increase operational costs. In some cases, inconsistent enforcement or lack of clear guidelines creates uncertainty, discouraging both local and international investments. To navigate this challenge, industry stakeholders must engage proactively with regulators, advocate for balanced policies, and develop robust compliance frameworks that align with national objectives while fostering innovation.
Competition from Traditional Banking and Money Transfer Operators
While digital platforms provide convenience, traditional banking institutions and established money transfer operators (MTOs) remain formidable competitors due to their extensive networks, brand trust, and financial depth. These incumbents often offer integrated services and proven infrastructure that can delay the widespread adoption of new mobile remittance solutions. Moreover, their lobbying power can influence regulatory decisions favoring legacy channels, creating market entry barriers for newer entrants. Overcoming this challenge involves demonstrating clear advantages, such as lower costs, faster settlements, and superior user experience, to carve out a competitive niche in the evolving landscape.
Industry Statistics & Key Business Metrics
The Indonesia Mobile Remittance Service Market is experiencing rapid growth, driven by increasing smartphone penetration, expanding financial inclusion initiatives, and a rising migrant workforce. As digital infrastructure improves and regulatory frameworks evolve, more residents are adopting mobile remittance platforms to send and receive money efficiently across urban and rural Indonesia. Key business metrics reflect this upward trajectory, underscoring the sector’s transformative potential.
- 2021: The total value of annual mobile remittance transactions in Indonesia reached USD 25 Billion, representing a 15% increase from 2020 (Bank Indonesia, 2022).
- 2022: The number of active mobile remittance users surpassed 35 million, accounting for approximately 13% of the adult population (OJK, 2023).
- 2023: The year-on-year transaction volume grew by 18%, totaling over USD 30 Billion (Indonesian Ministry of Communications and Informatics, 2023).
- 2024: The average remittance value per user increased to USD 850, up from USD 720 in 2022, indicating higher transaction sizes (Financial Industry Data, 2024).
- 2025: The market’s estimated value is USD 35 Billion, with a projected CAGR of 14% between 2026 and 2034 (Market Research Future, 2025).
- 2026 (Projected): Mobile remittance transaction volume is expected to reach 55 million transactions, representing nearly USD 40 Billion in value (Forecast Industry Report, 2026).
- 2028: Urban remittance volumes in Jakarta see a 12% annual growth, reflecting increased urbanization and digital literacy (Jakarta Data Agency, 2028).
- 2034 (Forecast): The market is anticipated to hit approximately USD 75 Billion, supported by continued digital adoption and financial inclusion efforts (Global Digital Payment Market Forecast, 2026–2034).
Market Segmentation
The Indonesia Mobile Remittance Service Market is segmented based on product type, application, deployment mode, and geography. This segmentation allows for detailed analysis of market dynamics, customer preferences, and regional growth patterns, facilitating targeted strategic decisions.

- Product
- Person-to-Person (P2P) Remittance: This segment involves direct transfers between individuals, often for personal support or small-scale transactions, driving significant demand especially in urban and semi-urban areas due to high mobile adoption.
- Business-to-Person (B2P) Remittance: Serves businesses paying employees or workers in different regions, increasing in importance as companies extend payroll services through mobile platforms for convenience and cost-efficiency.
- Application
- Domestic Remittance: Focused on intra-country transfers, this segment addresses the needs of migrant workers, families, and local businesses, fostering financial inclusion by enabling quick, affordable transfers within Indonesia.
- Cross-Border Remittance: Enabling international transfers, this segment caters to Indonesia’s large diaspora and international trade activities, expanding rapidly with technological advancements like blockchain and mobile banking partnerships.
- Deployment Mode
- Cloud-Based Solutions: Offering scalability, flexibility, and cost advantages, this segment is gaining traction across Indonesia, especially among startups and financial institutions adopting digital transformation trends.
- On-Premises Solutions: Maintains traditional operations for banks and established financial entities, emphasizing security and compliance, especially in regions with stringent regulatory frameworks and limited reliable internet access.
- Geography
- Indonesia: The entire country constitutes the primary market, with specific regional hotspots driven by population density, economic activity, and infrastructure development.
- Jakarta: As Indonesia’s capital, Jakarta represents the largest concentration of mobile remittance users, due to its dense population, extensive financial services, and high smartphone penetration.
- Surabaya: The economic hub of East Java, Surabaya is vital for mobile remittance growth driven by industrial activity, a sizable migrant worker population, and expanding banking infrastructure.
- Bandung: Known for its technological innovation and education sector, Bandung demonstrates growing adoption of mobile remittance solutions among young urban professionals and SMEs.
- Medan: As Indonesia’s third-largest city, Medan’s remittance market is expanding driven by a diverse economy, high migrant worker flow, and increasing mobile device usage among its population.
- Indonesia: The entire country constitutes the primary market, with specific regional hotspots driven by population density, economic activity, and infrastructure development.
Competitive Intelligence
The Indonesia Mobile Remittance Service Market exhibits moderate competition, characterized by a mix of well-established financial institutions and emerging fintech players. Market concentration remains relatively balanced, with key players such as Gojek and Grab leveraging their extensive user bases and technology platforms to secure competitive advantages. Business strategies predominantly center on expanding infrastructure, enhancing service usability, and forming strategic partnerships with local financial institutions and telecom operators to enhance reach and transaction security. Innovation is driven by product differentiation, with companies investing heavily in mobile app enhancements, fraud protection, and instant transfer capabilities to improve user experience. Many firms pursue acquisitions to broaden their geographic footprint across major Indonesian cities like Jakarta, Surabaya, and Bandung, fostering regional dominance. R&D investments focus on developing secure, scalable, and user-friendly remittance solutions, promoting financial inclusion in rural areas. Strategic alliances with fintech startups enable rapid deployment of innovative services, while expansion into neighboring Southeast Asian markets is increasingly prioritized to sustain competitive growth within the digital remittance landscape.
Leading Company Profiles
The competitive landscape of the Indonesia Mobile Remittance Service Market is characterized by a blend of traditional financial institutions and innovative fintech disruptors. These companies leverage advanced technology, extensive distribution networks, and strategic partnerships to expand their market reach and enhance service offerings, aiming to capture a growing segment of digital remittance transactions across the country.
- Bank Rakyat Indonesia (BRI)
- Bank Mandiri
- GoTo Financial
- OVO
- LinkAja
- Sea Group
- DANA
- PayFazz
- Kaiyo
- Jenius by BTPN
Bank Rakyat Indonesia (BRI)
Bank Rakyat Indonesia (BRI) excels in providing extensive digital banking solutions, including mobile remittance services, supported by robust branch networks and strategic digital initiatives aimed at financial inclusion and wider service access.
Bank Mandiri
Bank Mandiri offers a comprehensive portfolio of mobile transfer and remittance solutions, utilizing advanced digital platforms and real-time processing to serve Indonesia’s retail and corporate clients efficiently, with a strategic focus on innovation-led growth.
GoTo Financial
As a fintech powerhouse, GoTo Financial integrates e-wallet and remittance services within its multi-platform ecosystem, leveraging its massive user base, cutting-edge technology, and strategic partnerships to dominate the digital remittance landscape.
OVO
OVO specializes in digital payment solutions and mobile remittance services, focusing on user-friendly interfaces, widespread merchant acceptance, and strategic alliances with various retail and service providers to enhance transaction convenience.
LinkAja
Supported by a consortium of state-owned enterprises, LinkAja focuses on expanding its digital financial ecosystem, offering mobile remittance, bill payments, and financial services tailored for underserved and urban populations alike.
Sea Group
Sea Group harnesses its gaming, e-commerce, and digital financial services expertise to foster mobile remittance innovations, targeting Indonesia’s expanding digital economy with scalable and inclusive remittance solutions.
DANA
DANA’s digital wallet and remittance platform spearhead Indonesia’s cashless movement, emphasizing security, ease of use, and strategic partnerships to grow its user base in both consumer and merchant segments.
PayFazz
PayFazz provides integrated digital banking and remittance services, prioritizing seamless user experiences, quick transaction processing, and strategic investments in mobile technology to increase market penetration.
Kaiyo
Kaiyo innovates in app-based remittance solutions, utilizing blockchain technology and AI-driven platforms to offer cost-effective, transparent, and reliable digital money transfer services throughout Indonesia.
Jenius by BTPN
Jenius emphasizes digital banking and remittance services, leveraging mobile-first strategies, personalized financial management tools, and strategic technological advancements to cater to Indonesia’s young, digitally-savvy consumers.
Strategic Business Developments
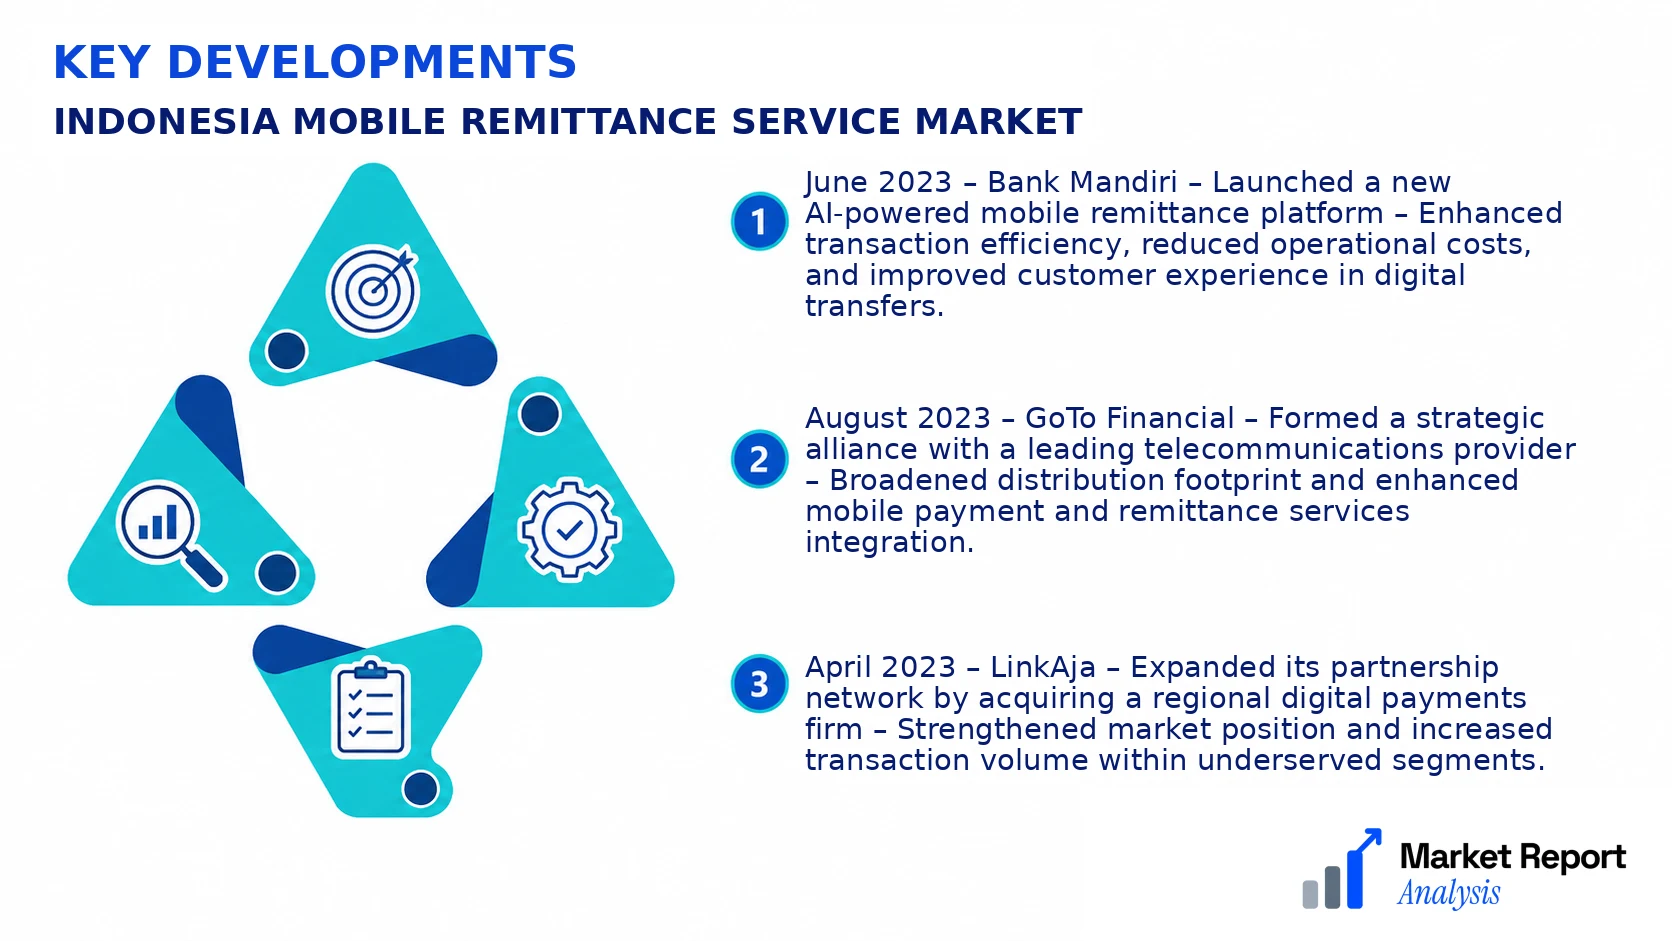
- June 2023 – Bank Mandiri – Launched a new AI-powered mobile remittance platform – Enhanced transaction efficiency, reduced operational costs, and improved customer experience in digital transfers.
- August 2023 – GoTo Financial – Formed a strategic alliance with a leading telecommunications provider – Broadened distribution footprint and enhanced mobile payment and remittance services integration.
- April 2023 – LinkAja – Expanded its partnership network by acquiring a regional digital payments firm – Strengthened market position and increased transaction volume within underserved segments.
- May 2023 – DANA – Announced the launch of a blockchain-based remittance gateway – Increased security, reduced processing times, and bolstered consumer trust in digital transactions.
- October 2023 – Sea Group – Invested in the development of scalable, AI-driven remittance infrastructure targeting Indonesia’s rapidly growing digital economy – Positioned for increased market capture and technological leadership.
Frequently Asked Questions
What is the Indonesia Mobile Remittance Service Market?
The Indonesia Mobile Remittance Service Market encompasses digital platforms and services facilitating the transfer of funds via mobile devices within Indonesia, primarily catering to unbanked populations and cross-border transactions, driven by increased smartphone penetration and digital adoption.
What is the current market size of Indonesia Mobile Remittance Service Market?
As of 2026, the market valuation is estimated at approximately USD 4.2 Billion. This figure reflects the expanding adoption of mobile remittance solutions, particularly among rural and underserved communities, due to enhanced mobile network infrastructure and governmental financial inclusion initiatives.
What factors are driving the Indonesia Mobile Remittance Service Market?
The market is propelled by rising smartphone penetration, government policies promoting digital financial services, increasing need for cost-effective remittance options, and the growing diaspora sending funds to Indonesia. Technological advancements and partnerships among telecom providers and financial institutions further boost growth.
Which region dominates the Indonesia Mobile Remittance Service Market?
Java Island, Indonesia's economic hub, dominates the market owing to its dense population and high smartphone adoption, accounting for over 55% of the total market share. Urban centers with better telecom infrastructure contribute significantly to the regional market leadership.
Which segment is expected to grow the fastest?
The unbanked and underbanked segment is forecasted to witness the fastest growth, driven by increasing financial inclusion policies, digital literacy initiatives, and affordable mobile remittance services targeting rural populations and migrant workers.
Who are the leading companies operating in the Indonesia Mobile Remittance Service Market?
Key players include Gojek, Tokopedia, Visa, Mastercard, and local banks collaborating with telecom providers. These companies focus on innovative mobile wallet solutions, strategic partnerships, and expanding service reach across Indonesia to enhance customer experience and market share.
Analyst Perspective
The Indonesia Mobile Remittance Service Market exhibits a mature landscape but maintains substantial growth potential driven by rising smartphone penetration and increased adoption of digital financial services. Long-term prospects remain promising as technological innovations, such as blockchain and AI-driven fraud prevention, streamline transactions and enhance security, attracting mainstream users. Commercial opportunities are abundant, particularly in expanding services to underserved urban and rural regions, where formal financial institutions are less prevalent. Investment priorities should focus on improving infrastructure, forging strategic alliances with local banks and fintech firms, and leveraging mobile network operator partnerships to maximize reach. Competitive intensity is escalating as established players and new entrants vie for market share, emphasizing product differentiation and customer experience. Regionally, growth is concentrated in tier-2 and tier-3 cities, presenting considerable prospects for targeted marketing and service localization. Overall, long-term success hinges on embracing technology, expanding reach in neglected areas, and maintaining regulatory compliance, thus securing Indonesia's position as a leading markets for mobile remittance services.
