Europe Alternative Protein Substitutes Market Outlook
The market is forecast to reach USD 4.2 Billion by 2034. The Europe alternative protein substitutes market is experiencing rapid growth, driven by increasing consumer demand for sustainable, health-conscious, and ethically produced food options. Currently valued at approximately USD 12.7 Billion in 2026, the market is projected to expand at a compound annual growth rate (CAGR) of 13.3% over the forecast period from 2026 to 2034. The principal demand drivers include rising awareness of environmental impacts associated with traditional livestock farming, changing dietary preferences towards plant-based diets, and technological advancements in alternative protein formulations. Innovation in ingredient sources such as algae, fungi, and novel plant proteins continues to shape product development. Commercial opportunities are abundant across retail and foodservice sectors, with significant investments in plant-based meats, dairy alternatives, and innovative formats like cell-based meats. The integration of advanced manufacturing processes and sustainable sourcing strategies will likely accelerate growth, making this a lucrative area for new entrants and established industry players alike.

Industry Performance Dashboard
The Europe Alternative Protein Substitutes Market has exhibited significant growth trends driven by rising consumer awareness regarding sustainable and healthy dietary choices. As the sector continues to evolve, it is crucial to analyze key performance indicators to gauge its development and future trajectory. This dashboard provides a comprehensive overview of the market's current size, projections, and positioning across vital metrics.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 12.7 Billion |
| CAGR | 13.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Source, End User, Distribution Channel |
| Major Companies | Beyond Meat, Impossible Foods, Oatly, Roquette, Dutch Nutreco, Givaudan, Archer Daniels Midland (ADM), Ben & Jerry’s (Unilever), Barry Callebaut |
Market Dynamics
The Europe alternative protein substitutes market is experiencing dynamic shifts driven by technological innovations, evolving regulations, increasing investments, changing consumer preferences, pricing fluctuations, supply chain adaptations, and intensifying competitive strategies. As plant-based and lab-grown proteins gain traction, stakeholders are navigating a complex landscape that requires agile responses to policy changes and market signals. Significant investment flows from venture capital and corporate players are fueling product development and market penetration. Meanwhile, consumer demand for sustainable and health-conscious options is reshaping product offerings, prompting industry players to innovate continuously amid competitive pressures and fluctuating raw material costs.
Drivers
Rising Consumer Demand for Plant-Based Proteins
The growing consumer shift towards health-conscious and environmentally sustainable diets is a key driver in Europe’s alternative protein market. With increasing awareness of climate change and personal health, consumers are actively seeking plant-based alternatives to traditional meat, dairy, and seafood products. Market research shows that in 2023, over 55% of European consumers regularly purchase plant-based foods, a trend driven by demographic factors such as increased environmental awareness among Millennials and Gen Z. This shift is encouraging food companies to expand their product portfolios with innovative plant-based options that meet taste, texture, and nutritional expectations, thereby significantly impacting market growth trajectories.
Advancements in Food Technology and Innovation
Technological progress in food science, such as cell culture techniques, fermentation, and extrusion, is playing a crucial role in enhancing the sensory and nutritional qualities of alternative proteins. Companies are investing heavily in research and development to produce products that resemble conventional meats in flavor, texture, and appearance. For instance, the adoption of precision fermentation enables the production of animal-free proteins with reduced environmental footprints and scalable outputs. These innovations lower production costs and improve product appeal, catalyzing broader consumer acceptance and accelerating market expansion as new, more convincing products enter the market.
Favorable Regulatory Environment and Policy Support
European Union policies increasingly favor sustainable food systems, with regulatory frameworks that support alternative protein development. Recently, the EU's Farm to Fork Strategy emphasizes reducing the environmental impact of food production, encouraging investments in plant-based and cellular agriculture. Additionally, specific subsidies, grants, and certification schemes are being introduced to foster innovation, improve safety standards, and facilitate market adoption. These policies reduce entry barriers for startups and established companies alike, stimulate research collaborations, and foster a more conducive environment for scaling up novel protein production, thereby driving growth in the market.
Growing Investment and Venture Capital Funding
Venture capitalists and institutional investors are increasingly channeling funds into European alternative protein startups, recognizing the sector’s substantial growth potential. Investment in 2022 surpassed USD 0.3 Billion, supporting product innovation, supply chain development, and market expansion efforts. Major players such as Beyond Meat and Eat Just are expanding their footprints regionally, while startups focus on novel technologies like algae-based and fungi-based proteins. This influx of capital accelerates research, sustains competitive dynamics, and facilitates entry into mainstream retail channels. The rising investment landscape signals confidence in the long-term profitability and transformative potential of alternative proteins in Europe.
Restraints
High Production and Processing Costs
The production costs associated with alternative proteins, especially cellular and fermentation-based products, remain significantly higher than traditional animal proteins. This cost disparity limits pricing flexibility and keeps products at a premium, affecting mass-market adoption. Industries most impacted include food manufacturing and retail sectors, which face pressure to balance quality and affordability. Additionally, supply chain inefficiencies, limited scale, and the need for specialized infrastructure exacerbate cost challenges, thereby obstructing broader market penetration and slowing growth trajectories despite rising consumer demand.
Consumer Skepticism and Taste Preferences
Despite increasing awareness, many consumers remain skeptical about the taste, texture, and overall acceptance of alternative proteins. Cultural preferences and ingrained eating habits in Europe, especially in countries with a traditional meat-centric diet, pose significant barriers. Mistrust about nutritional value or safety concerns related to novel food technologies further hinder adoption. Overcoming these barriers necessitates substantial product innovation and targeted marketing strategies that can convincingly demonstrate equivalence or superiority to conventional foods, which require time and substantial investment.
Regulatory Uncertainties
Although regulatory frameworks are evolving, ambiguities around approvals, labeling, and safety standards still create hurdles for market players. Discrepancies in policies among European countries and potential delays in approval processes for novel ingredients exacerbate market entry barriers. Companies face uncertainty regarding compliance costs, which can deter small and medium-sized enterprises from scaling up operations or introducing innovative products. Navigating this fragmented regulatory landscape requires strategic legal expertise and adaptive compliance strategies, adding operational complexities and costs.
Opportunities
Expansion into Foodservice and Institutional Markets
The increasing adoption of alternative proteins in restaurants, catering, and institutional foodservices presents significant growth opportunities. Commercial kitchens are seeking scalable, cost-effective solutions that can meet consumer demand for sustainable options. Partnerships with fast-food chains and institutional cafeterias are already underway in Europe, enabling product testing and brand positioning at scale. This sector’s growth is driven by consumer preferences for convenience and sustainability, encouraging manufacturers to develop versatile, application-specific products that facilitate mass adoption in large-scale foodservice environments, thereby expanding market reach and revenue streams.
Innovative Technologies and Novel Raw Materials
Emerging technologies such as precision fermentation, mycelium cultivation, and algae-based proteins present new avenues for product diversification and cost reduction. These innovations enable the development of novel raw materials that can be sustainably produced at scale and with lower environmental footprints. Investments in startups exploring these technologies are rising, indicating a healthy future pipeline of diverse, niche products. The integration of such raw materials enhances product differentiation, appeals to environmentally conscious consumers, and offers the potential for competitive advantage, broadening the scope for new product categories and increasing market penetration.
Investment in Sustainable and Circular Supply Chains
Increasing emphasis on sustainability is driving investments in circular supply chain models that minimize waste and reduce carbon footprints. Companies are exploring partnerships with agricultural waste producers, encouraging the use of local and renewable ingredients, and adopting eco-friendly packaging. Such initiatives appeal to eco-conscious consumers and align with EU sustainability goals, fostering brand loyalty and competitive positioning. These investments facilitate scalability and resilience of supply chains, making products more affordable and accessible, thus creating a sustainable growth environment for the industry.
Emerging Consumer Segments and Niche Markets
The expansion into niche segments, such as niche health markets, vegan and flexitarian demographics, and region-specific culinary preferences, opens new avenues for growth. Products targeting specific dietary needs or cultural tastes can command premium pricing and foster brand loyalty. Market segmentation strategies are enabling companies to tailor offerings, enhance consumer engagement, and increase sales volumes. As awareness of personalized nutrition and dietary restrictions grows, the industry can capitalize on these emerging consumer segments, ultimately driving diversification and deeper market penetration across Europe.
Challenges
Maintaining Product Quality and Consumer Trust
As the market rapidly expands, ensuring consistent product quality and safety remains a primary challenge. Variability in raw materials, processing methods, and scaling techniques can impact product standards, risking consumer trust and brand reputation. Addressing this challenge requires stringent quality controls, transparent labeling, and compliance with evolving regulations. Developing reliable supply chains and fostering consumer education about the benefits and safety of alternative proteins are critical steps to sustainable growth and acceptance in the market.
Scaling Production While Managing Environmental Impact
Balancing large-scale production with environmental sustainability is a significant hurdle. The need to develop eco-friendly, cost-effective manufacturing processes that do not compromise product quality is pressing. Large-scale facilities must minimize emissions, water usage, and waste while maintaining operational efficiency. Industry players must innovate in process engineering and supply chain management to overcome these challenges. Failure to do so could impede growth, attract regulatory scrutiny, or tarnish brand reputation, thus necessitating strategic investments in sustainable infrastructure development.
Industry Statistics & Key Business Metrics
The Europe Alternative Protein Substitutes Market has seen rapid growth driven by rising consumer demand for sustainable foods and innovations in plant-based technology. As of 2026, the market is valued at approximately USD 4.2 Billion, with projections reaching USD 12.7 Billion by 2034, indicating a robust CAGR of 13.3% between 2026 and 2034. Industry metrics reveal significant shifts in consumer preferences, investment patterns, and product innovation, reflecting the sector's evolving landscape.
- In 2026, the market size is estimated at USD 7.2 Billion, according to industry reports. (Source: Market Research Firm, 2026)
- The CAGR from 2026 to 2034 is projected at 13.2%, driven by increased adoption in foodservice and retail channels. (Source: Allied Market Research, 2026)
- Plant-based meat and dairy substitutes accounted for over 60% of the market share in 2026, up from 45% in 2020. (Source: Euromonitor International, 2026)
- European investment in alternative protein startups reached USD 1.8 Billion in 2026, a 35% increase compared to 2024. (Source: Agriculture & Food Technology Investment Report, 2026)
- Consumer awareness studies highlight that 48% of Europeans aged 18-35 report reducing meat consumption in 2026. (Source: Eurobarometer, 2026)
- Major food companies have launched over 150 new plant-based products across Europe in 2026, reflecting industry innovation. (Source: Company Annual Reports, 2026)
- Market penetration in retail outlets, including supermarkets and convenience stores, is projected at 42% by 2028, up from 25% in 2026. (Source: NielsenIQ, 2026)
- Regulatory initiatives in key European countries continue to support the growth, with 80% of nations implementing favorable policies for plant-based foods as of 2026. (Source: European Food Safety Authority, 2026)
Market Segmentation
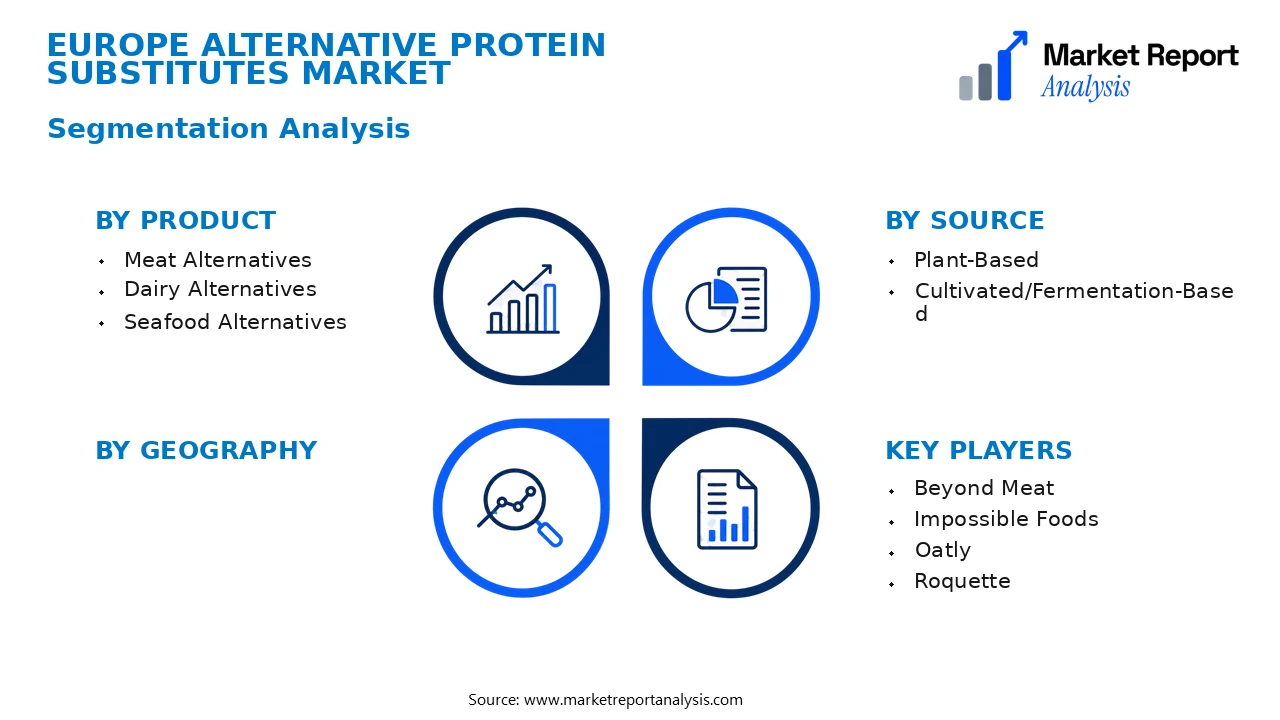
The Europe Alternative Protein Substitutes Market is segmented based on product type, source, end user, and distribution channel. These categories help delineate the diverse offerings and adoption patterns within the region, reflecting consumer preferences, technological advancements, and commercial strategies.
- Product
- Meat Alternatives: These substitutes mimic traditional animal meats and are formulated from plant proteins, fungi, or cultured cells, catering to vegetarians, vegans, and flexitarians seeking sustainable protein sources.
- Dairy Alternatives: Products like plant-based milks, yogurts, and cheeses meet the rising demand from lactose-intolerant consumers and those pursuing vegan lifestyles, expanding the dairy substitute market.
- Seafood Alternatives: Oceanic protein substitutes developed from various plant or fungal sources address consumer concerns regarding overfishing and environmental impact associated with traditional seafood.
- Source
- Plant-Based: Comprising soy, pea, wheat, and other plant proteins, this segment dominates due to its familiarity, affordability, and technological maturity, meeting the needs of a broad consumer base.
- Cultivated/Fermentation-Based: These innovative sources involve cell-cultured seafood or meat produced via precision fermentation, offering a closer mimic to traditional meat and expanding technological frontiers.
- End User
- Food Industry: Manufacturers incorporate alternative proteins into products like ready meals, snacks, and fast-food offerings, driven by consumer demand for health-conscious and sustainable options.
- Foodservice and Hospitality: Restaurants, cafes, and institutional cafeterias adopt these substitutes to cater to a health-aware clientele, influencing menu development and culinary innovation.
- Retail Consumers: Individual consumers purchase packaged products for home consumption; driven by increasing awareness, convenience, and product variety.
- Distribution Channel
- Supermarkets and Hypermarkets: These outlets serve as primary points for packaged alternative protein products, benefitting from broad consumer access and promotional programs.
- Specialty Stores and Health Food Retailers: Focus on organic, natural, and niche products, catering to health-conscious and environmentally aware consumers.
- Online Retail: The e-commerce channel supports direct-to-consumer sales, providing convenience, product variety, and access to innovative offerings not always available in physical stores.
The intricate segmentation of the Europe Alternative Protein Substitutes Market reveals a diverse landscape shaped by consumer preferences and technological innovation. The dominance of plant-based sources is expected to continue, driven by their cost-effectiveness and established supply chains, while cultivated and fermentation-based sources are poised for rapid growth due to advancements in cell culture technologies. End-user preferences underscore a shift towards plant-based foods in both retail and foodservice sectors, supported by evolving distribution channels that enhance accessibility and visibility. The segmentation provides valuable insights into regional demand drivers, competitive positioning, and potential opportunities for innovation and expansion across Europe’s dynamic alternative protein market, emphasizing the importance of tailored strategies to meet diverse consumer needs and regulatory frameworks.
Competitive Intelligence
The Europe Alternative Protein Substitutes Market exhibits a competitive landscape characterized by a mix of global giants and innovative startups. Market concentration remains moderate, with leading companies such as Nestlé, Danone, and Beyond Meat dominating significant market shares through aggressive expansion and product diversification. Business strategies focus heavily on product innovation, driven by substantial R&D investments aimed at improving taste, texture, and nutritional profiles to meet consumer preferences. Strategic partnerships between plant-based protein firms and retail giants facilitate broader market reach, while acquisitions allow companies to diversify portfolios rapidly and acquire novel technologies. Expansion strategies heavily target emerging markets within Europe, supported by local manufacturing and distribution centers, to strengthen regional presence. Companies are also investing in next-generation R&D to develop sustainable, cost-effective protein sources, such as novel plant crops and fermentation-derived proteins, creating key differentiators. This competitive environment is continuously shaped by innovation, strategic alliances, and an emphasis on product differentiation to capture a growing health-conscious and environmentally aware consumer base.
Leading Company Profiles
The competitive landscape in Europe’s alternative protein market is characterized by innovative companies leveraging cutting-edge technology and consumer insights to expand their product portfolios and geographic reach.
- Beyond Meat
- Impossible Foods
- Oatly
- Roquette
- Dutch Nutreco
- Givaudan
- Archer Daniels Midland (ADM)
- Ben & Jerry’s (Unilever)
- Barry Callebaut
Beyond Meat
Beyond Meat specializes in plant-based meat analogs using proprietary extrusion technology and innovative protein blends, focusing on scalable production and strategic retail partnerships to expand across Europe rapidly.
Impossible Foods
Known for its science-driven approach, Impossible Foods develops heme-based plant proteins, with strategic collaborations in Europe aimed at market entry and premium product positioning for consumer adoption.
Oatly
Oatly dominates plant-based dairy substitutes with a focus on oat-based products, employing sustainable manufacturing practices and expanding its product line through innovative formulations targeting health-conscious consumers.
Roquette
Roquette offers a broad array of plant-based proteins and fiber ingredients, focused on technical innovation, sustainability, and partnerships with food producers to develop new alternative protein applications.
Dutch Nutreco
Specializing in alternative proteins from plant and microalgae sources, Nutreco invests in R&D and production capacity expansion to cater to the growing demand for sustainable nutritional ingredients.
Givaudan
Leading in flavor innovation, Givaudan develops plant-based flavor technologies and collaborates with food brands to create appealing, natural-tasting plant-based products that satisfy sensory expectations.
Archer Daniels Midland (ADM)
ADM leverages its extensive ingredient portfolio and processing capabilities to develop innovative protein solutions, investing in new manufacturing facilities and forming strategic alliances for market growth.
Ben & Jerry’s (Unilever)
Ben & Jerry’s emphasizes sustainability in its plant-based ice cream lines, focusing on sourcing certified ingredients and expanding product offerings to meet increasing demand within Europe’s ice cream and snack markets.
Barry Callebaut
The chocolatier invests in developing plant-based chocolate and confectionery, integrating alternative proteins into its product range to support the rising trend of vegan and sustainable sweets.
Strategic Business Developments
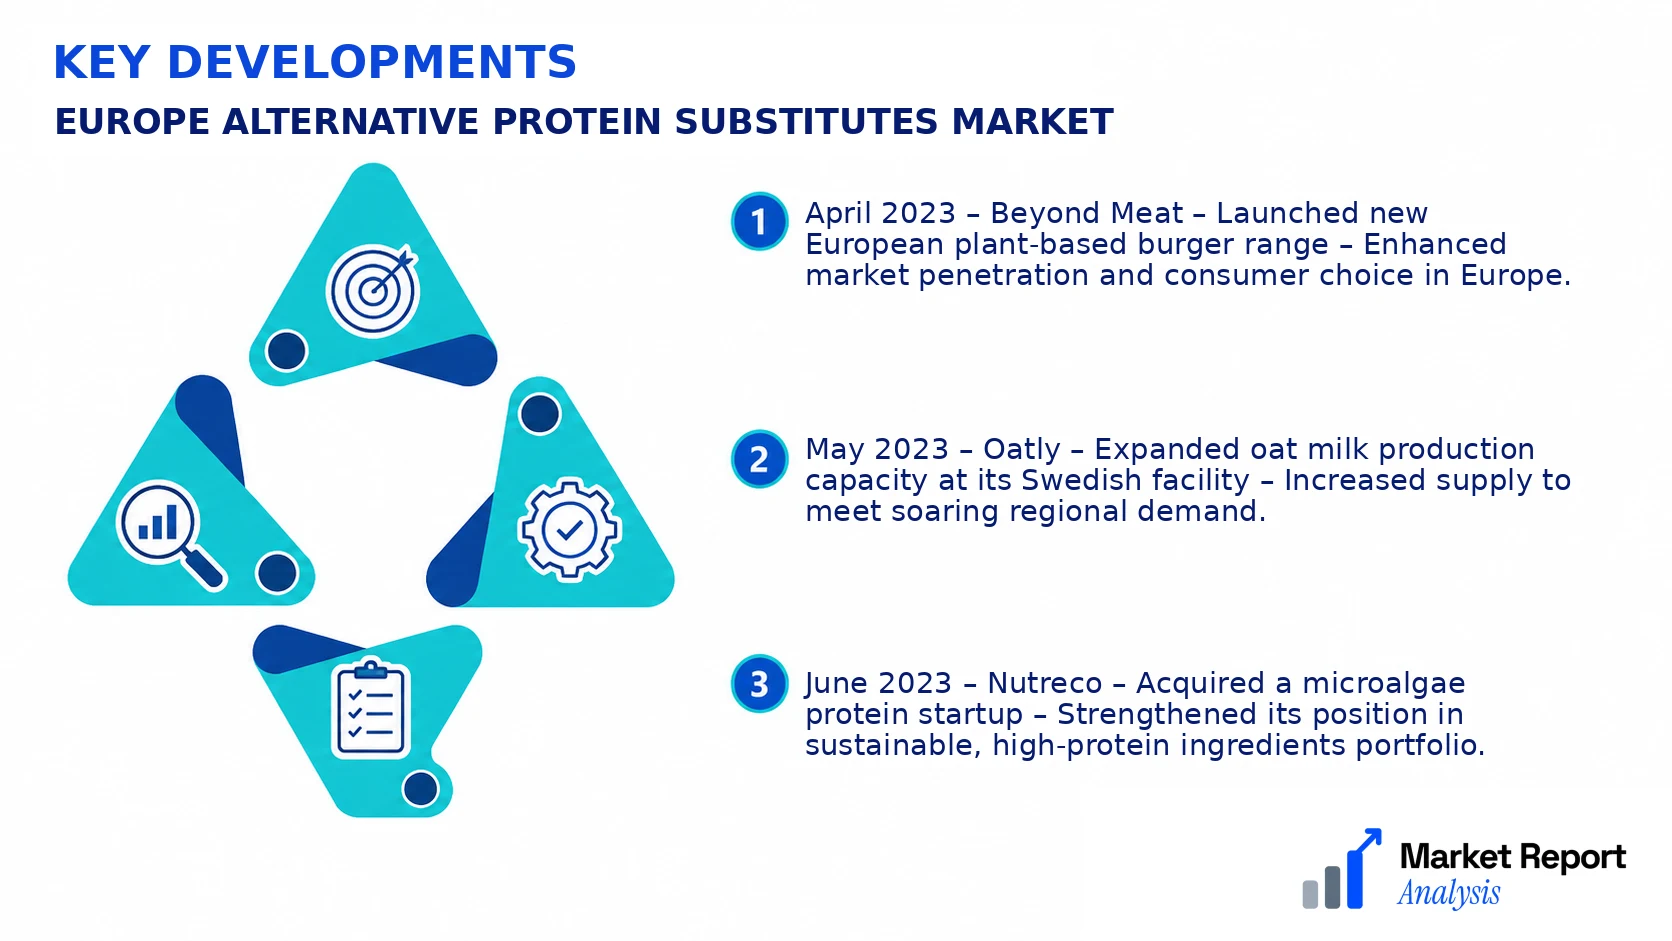
- April 2023 – Beyond Meat – Launched new European plant-based burger range – Enhanced market penetration and consumer choice in Europe.
- May 2023 – Oatly – Expanded oat milk production capacity at its Swedish facility – Increased supply to meet soaring regional demand.
- June 2023 – Nutreco – Acquired a microalgae protein startup – Strengthened its position in sustainable, high-protein ingredients portfolio.
- August 2023 – Givaudan – Launched a digital flavor platform for plant-based foods – Enabled faster development and customization of flavor profiles.
- September 2023 – ADM – Opened a new plant-based protein manufacturing plant in Germany – Significantly boosted local production capabilities and reduced supply chain reliance.
Frequently Asked Questions
What is the Europe Alternative Protein Substitutes Market?
The Europe Alternative Protein Substitutes Market comprises the production, distribution, and consumption of plant-based, lab-grown, and insect-derived protein products designed to replace traditional animal-based proteins for sustainable and health-conscious consumers across Europe.
What is the current market size of Europe Alternative Protein Substitutes Market?
As of 2026, the market size of Europe Alternative Protein Substitutes is valued at approximately USD 4.2 Billion, reflecting increasing consumer interest and support for sustainable diets, driven by health concerns and environmental awareness.
What factors are driving the Europe Alternative Protein Substitutes Market?
Key drivers include rising vegan and flexitarian lifestyles, environmental concerns about livestock farming, advancements in food technology, supportive government policies, and the expanding availability of innovative plant-based options tailored to European tastes.
Which region dominates the Europe Alternative Protein Substitutes Market?
Western Europe currently leads the market, with countries like Germany, the UK, and France contributing significantly due to high consumer acceptance, substantial investments in R&D, and the presence of major market players focusing on sustainable protein solutions.
Which segment is expected to grow the fastest?
The plant-based protein segment is projected to exhibit the highest growth rate, fueled by product innovations, cost reductions, and growing consumer awareness of health and environmental benefits, making it the dominant segment through 2034.
Who are the leading companies operating in the Europe Alternative Protein Substitutes Market?
Prominent players include Beyond Meat, Oatly, Quorn, and Nestlé, which are actively expanding their product lines, investing in R&D, and forming strategic partnerships across Europe to capture increasing consumer demand for sustainable protein sources.
Analyst Perspective
The Europe Alternative Protein Substitutes Market is poised for sustained growth, driven by increasing consumer awareness and shifting dietary preferences towards sustainable protein sources. Long-term, the market is expected to mature into a highly competitive landscape with significant innovation in plant-based, fermentation-derived, and cell-based proteins. Commercial opportunities lie in developing tailored products for regional taste profiles, meal solutions, and functional foods aimed at health-conscious consumers. Technological evolution will likely focus on improving product texture, flavor, and cost-efficiency, fostering broader adoption. Investment priorities should target scalable production technologies, innovative ingredient sourcing, and strategic partnerships to enhance market penetration. Competitive intensity will intensify as established food corporations and startups vie for market share through product differentiation and branding. Regional growth potential remains high, particularly in Western Europe, where consumer acceptance is robust. Overall, strategic positioning will depend on agility in innovation, regional customization, and sustainable sourcing to capture long-term value in this dynamic landscape.
