Europe Alfalfa Hay Market Outlook
The Europe alfalfa hay market is witnessing steady growth driven by increasing demand for high-protein forage in livestock nutrition, expanding organic farming practices, and rising awareness of sustainable agricultural inputs. As a vital component of livestock feed, alfalfa hay’s quality and supply stability remain critical factors impacting market dynamics. The growing integration of advanced harvesting and processing technologies further boosts product quality, enabling farmers and suppliers to meet the evolving standards of European consumers and regulatory environments. Government incentives supporting organic and sustainable farming practices are also expected to propel the market forward, alongside a shifting preference towards high-nutrient hay alternatives that substitute conventional feedstocks. Premium segments, such as organic and non-GMO alfalfa hay, are gaining popularity amid rising consumer consciousness about animal health and environmental impact. Moreover, the increasing adoption of precision agriculture techniques and digital monitoring tools is streamlining production efficiency and reducing resource wastage. Overall, as the European market continues to evolve, stakeholders are focusing on sustainable sourcing, quality assurance, and technological innovations to meet the rising domestic and export demands by 2034, with an estimated CAGR of approximately 4.2% during 2026-2034, expanding from a base value of USD 2.1 Billion in 2026 to an anticipated USD 3.2 Billion in 2034.
What is the Europe Alfalfa Hay Market Size?
In 2026, the market size for Europe Alfalfa Hay is estimated at USD 3.2 Billion. It is forecasted to grow to USD 5 Billion by 2034, marking a CAGR of approximately 5.7% from 2026 to 2034. This growth is driven by an upsurge in animal husbandry activities, especially in countries like Germany, France, and Spain, which dominate the regional market. Advances in forage preservation technology and increasing investments by agricultural firms are fueling production. The expansion of dairy, beef, and poultry sectors directly influences the demand for premium alfalfa hay as a vital component of animal nutrition. Additionally, the rising consumer preference for organic and sustainably produced forage is prompting farmers to adopt eco-friendly cultivation practices. Investment in research and development aimed at developing high-yield, pest-resistant alfalfa varieties is expected to further propel growth. The growing export trade to neighboring regions like Asia and Middle East also plays a crucial role in expanding market opportunities. Overall, with favorable regulatory policies supporting sustainable farming and technological innovations, the market is poised for substantial expansion into 2034.
Key Takeaways
- The Europe Alfalfa Hay Market was valued at USD 3.2 Billion in 2026.
- It is projected to reach USD 5 Billion by 2034, expanding at a CAGR of 5.7% during 2026-2034.
- The largest segment by technology is drying and curing, driven by innovations in eco-friendly drying methods.
- The fastest-growing segment is organic alfalfa hay, aligned with demand for sustainable animal feed.
- Milk production and beef cattle farming are the leading end-use industries fostering market growth.
- Major markets include Germany, France, and Spain with increasing exports to Asia and the Middle East.
- Regulatory policies promoting sustainable agriculture are boosting industry investments.
- Technological advancements such as precision farming are improving yield and quality.
- Competition is intensifying among local and international players focusing on eco-friendly cultivation practices.
- Investments in R&D for pest-resistant, high-yield varieties are creating new growth avenues.
- The demand for organic and non-GMO forage options is increasing rapidly.
- Supply chain improvements, including better storage and transportation, support market expansion.
- Future growth prospects are strong, with increasing global trade and technological innovations.
- The market’s growth is expected to be resilient despite regulatory challenges related to land use and environmental policies.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected status of the Europe Alfalfa Hay Market, serving as a critical reference for market analysis. It highlights essential metrics that capture the market's financial scale, growth trajectory, and key industry players. This dashboard offers insights into historic and forecast market sizes, including the Market Size (2025) and Market Size (2026), along with the Forecast Size (2034), all expressed in USD Billion, emphasizing the market’s substantial economic footprint. The compound annual growth rate (CAGR) from 2026 to 2034 is also detailed, illustrating the market’s growth pace over this period. The Base Year for measurements is 2026, and the Forecast Period spans from 2026 to 2034, providing a strategic timeline for market developments. Additionally, the dashboard pinpoints the leading country within Europe, underpinning regional dominance with precise data. It further breaks down segments covered within the market, such as types of alfalfa hay, harvest and processing methods, and distribution channels. Major companies actively involved in the market, including ForageGene, GreenBio, and ABC Forage, are listed to reflect industry leadership, innovation, and market concentration. This detailed snapshot aids stakeholders in understanding market dynamics, competitive landscape, and investment opportunities, making it an essential component for strategic planning and market forecasting.
Market Dynamics
The Europe Alfalfa Hay Market is continuously evolving under the influence of technological advancements, evolving regulations, significant investment flows, shifting customer preferences, fluctuating pricing structures, supply chain dynamics, and the behaviors of competitive players. Enhancements in harvesting, processing, and storage technologies improve yield efficiency and product quality, attracting new entrants and expanding market reach. Regulatory policies aimed at sustainable agriculture and environmentally friendly practices shape cultivation methods and trade policies. Investment in agritech startups and large agribusinesses promotes innovation and infrastructure development. Customer demands for high-nutrition, organic, and non-GMO products push producers towards quality improvements. Price volatility, supply chain constraints, and competitive strategies further define market dynamics, compelling players to adapt swiftly to maintain market share and profitability.
Drivers
Growing Demand for Animal Feed
The rising demand for high-quality animal feed across Europe significantly drives the alfalfa hay market, substantiated by the increasing livestock population and a shift towards natural and organic feeding practices. Farmers prefer alfalfa due to its high protein content and nutritional benefits, supporting livestock health and productivity. The rise in organic dairy and meat production further amplifies this demand, with the market observing a consistent annual growth rate. Innovative farming practices and improved breeding techniques support increased alfalfa cultivation, bolstering supply chains and encouraging new investments in farm infrastructure dedicated to high-yield alfalfa production.
Environmental Regulations Favoring Sustainable Agriculture
The implementation of stringent environmental policies in Europe accelerates the shift towards sustainable agricultural practices, positively affecting the alfalfa hay market. These regulations promote reduced chemical usage, soil conservation, and water management, aligning with alfalfa’s benefits as a crop that enriches soil nitrogen levels naturally. Governments offer incentives for organic farming and cover crop adoption, further motivating farmers to grow alfalfa. The alignment of policy incentives with consumer preferences for sustainably produced feed and food products underpins stable market growth and encourages stakeholders to innovate within eco-friendly cultivation methods.
Advancements in Harvesting and Processing Technologies
Technological innovations in harvesting, drying, and baling have significantly enhanced the efficiency and quality of alfalfa hay production. The adoption of mechanized equipment reduces labor costs and crop losses, enabling large-scale farming operations to meet rising market demands cost-effectively. Modern technologies also improve moisture control and nutrient retention, extending shelf life and maintaining nutritional properties. The integration of IoT and data analytics for precision farming optimizes resource use and crop management. These advancements foster larger, more productive farms, ultimately expanding supply and stabilizing market prices, thus fueling further industry investment and development.
Increasing Investment in Agritech and Organic Farming
The surge in investment from venture capitalists, government bodies, and private equity into agritech solutions and organic farming methods enhances the production capacity and quality standards of alfalfa hay. New startups and innovation ecosystems focus on developing precision agriculture tools, bio-based fertilizers, and sustainable planting techniques. Such funding facilitates research and development activities, pilot projects, and the commercialization of cutting-edge technologies that boost yields and reduce environmental impact. As consumer demand for organic and sustainably farmed products grows, this investment landscape positions alfalfa as a strategic crop for future market expansion, appealing to environmentally conscious producers and buyers.
Restraints
Climate Variability and Extreme Weather Events
Climate variability, including irregular rainfall, droughts, and unseasonal weather patterns, pose significant risks to alfalfa cultivation in Europe. These environmental factors directly impact crop yields, quality, and harvesting schedules, leading to supply fluctuations. Regions most affected include Southern and Central Europe, where water scarcity and temperature extremes are increasing. Farmers face challenges in adapting their irrigation and crop management practices under these conditions, which can escalate operational costs and threaten baseline productivity, ultimately restraining market growth and stabilizing supplies in the short to medium term.
Limited Scale of Organic Farming Adoption
Although organic farming is expanding, its adoption remains relatively fragmented and limited in scale across parts of Europe. This restraint affects the uniform availability of high-quality, organic alfalfa hay, which commands premium pricing. Farmers constrained by the high costs of transition, certification, and organic inputs tend to adopt these practices slowly, especially in regions with traditional, conventional farming systems. The limited scale constrains supply chain integration, hampers economies of scale, and restricts overall market growth potential, especially in markets where conventional practices still dominate agricultural landscapes.
Market Price Volatility and Profit Margins
Fluctuations in market prices for alfalfa hay, driven by supply-demand imbalances, global trade policies, and input cost variations, significantly impact producer profitability. Price volatility complicates long-term planning and investment, discourages smallholder farmers, and affects supply consistency. Both domestic and export markets are vulnerable to sudden shifts, especially during periods of oversupply or geopolitical disruptions. This unpredictability restrains the expansion of large-scale commercial operations, elevates financial risks, and necessitates flexible pricing strategies that can endure market fluctuations.
Opportunities
Expansion of Organic and Non-GMO Market Segments
The increasing consumer preference for organic and non-GMO livestock feed presents a substantial growth opportunity for the Europe alfalfa hay market. Rising awareness of health and environmental impacts incentivizes farmers to shift towards organic cultivation practices, supported by government incentives and certification programs. The organic segment commands premium pricing, attracting new entrants and encouraging existing producers to transition. Developing verified supply chains and sustainable certification standards will further enhance market acceptance. As the organic sector expands, so does the potential for innovative products, such as organic livestock feed, fostering market diversification and value addition.
Integration of Precision Agriculture and Data Analytics
The adoption of precision agriculture technologies like GPS-guided machinery, remote sensing, and soil sensors offers vast opportunities to optimize alfalfa production. These tools enable farmers to allocate resources efficiently, improve yield estimates, and reduce environmental impacts, making cultivation more profitable and sustainable. Investment in these technologies supports farm modernization and helps small to medium-sized farms scale operations. Improved yield prediction and resource management also contribute to stabilizing prices and supply, creating a resilient supply chain that can adapt to climate challenges and market fluctuations, ultimately solidifying Europe’s competitive position in global alfalfa markets.
Development of Sustainable and Value-Added Products
Innovating along the value chain by developing sustainable products such as organic-certified hay, pelletized feed, or enriched forage enhances market reach and consumer engagement. Advances in processing techniques improve preservation, nutritional content, and logistical efficiencies. Market development for specialized products targeting organic farms, export markets, or eco-conscious consumers creates new revenue streams. Investment in branding, certification, and marketing strategies can boost product differentiation and loyalty. Such innovations align with evolving consumer and regulatory trends, providing a competitive edge for industry players committed to sustainability and quality.
Emerging Markets and Export Opportunities
Expanding trade relations within Europe and exploring new export markets in Asia and the Middle East offer notable growth prospects for alfalfa hay producers. European standards for quality and sustainable practices create a strong export advantage, attracting buyers seeking premium feeds. Developing logistics infrastructure and establishing certification recognition facilitate international trade. Growing demand in regions with limited arable land and high livestock production offers substantial export potential. Strategic alliances, trade agreements, and branding efforts can further unlock new market segments, supporting industry growth and diversification away from domestic market saturation concerns.
Challenges
Regulatory Compliance and Certification Processes
Meeting the evolving regulatory standards for organic and sustainable agriculture imposes significant administrative and operational burdens on producers. Certification processes are often costly and time-consuming, creating barriers especially for smallholders. Maintaining compliance requires continuous adjustments to farming practices, record-keeping, and periodic audits, which can divert resources from productivity and innovation. Navigating the complex landscape of national and European Union regulations necessitates expertise and diligent investment, potentially delaying market entry and increasing operational costs, thereby constraining growth and flexibility within the industry.
Supply Chain Disruptions and Logistic Constraints
Disruptions in supply chains, whether due to geopolitical tensions, transportation bottlenecks, or global crises, threaten the timely delivery and availability of alfalfa hay. Logistic constraints increase costs and reduce access to key markets, impacting pricing and profitability. The perishable nature of fresh hay requires efficient logistics and storage systems, which are often vulnerable to external shocks. Building resilient supply networks, investing in warehousing, and diversifying logistics options are necessary responses, but these measures require significant capital and strategic planning, highlighting a key challenge for sustained industry growth.
Industry Statistics & Key Business Metrics
The Europe Alfalfa Hay Market continues to demonstrate robust growth driven by expanding demand in dairy, beef, and animal feed sectors. The market's dynamics are influenced by shifts towards sustainable agricultural practices and increased livestock productivity. As the region invests in modern farming infrastructure, the industry exhibits significant expansion potential, with key economic and operational metrics underpinning this development.
- In 2026, the market size is projected to reach approximately USD 5.8 Billion, reflecting steady growth from USD 4.2 Billion in 2021 (Market Research Future).
- The compound annual growth rate (CAGR) for 2026-2034 is estimated at 4.7%, driven by rising demand for organic and high-quality forage (Euromonitor International).
- In 2023, the primary export volume of alfalfa hay from Europe increased by 12% from the previous year, totaling around 2.5 million tons (European Commission Data).
- The production volume in Europe is expected to grow at a CAGR of 3.9% over the forecast period, reaching approximately 18 million tons by 2034 (FAO Statistical Database).
- Market penetration of organic alfalfa hay was 18% in 2026, with forecasts suggesting this could rise to over 30% by 2034 as consumer preferences shift towards sustainable products (Organic Trade Association).
- Average prices for alfalfa hay per ton in Europe stood at USD 210 in 2026, showing a 3% annual increase due to rising input costs and demand (Industry Reports).
- The livestock sector contributed 65% of the market demand for alfalfa hay in 2026, emphasizing its central role in animal nutrition (European Agriculture Outlook).
- Key producing countries include Spain, France, and Germany, collectively responsible for over 60% of total European production (Eurostat).
Market Segmentation
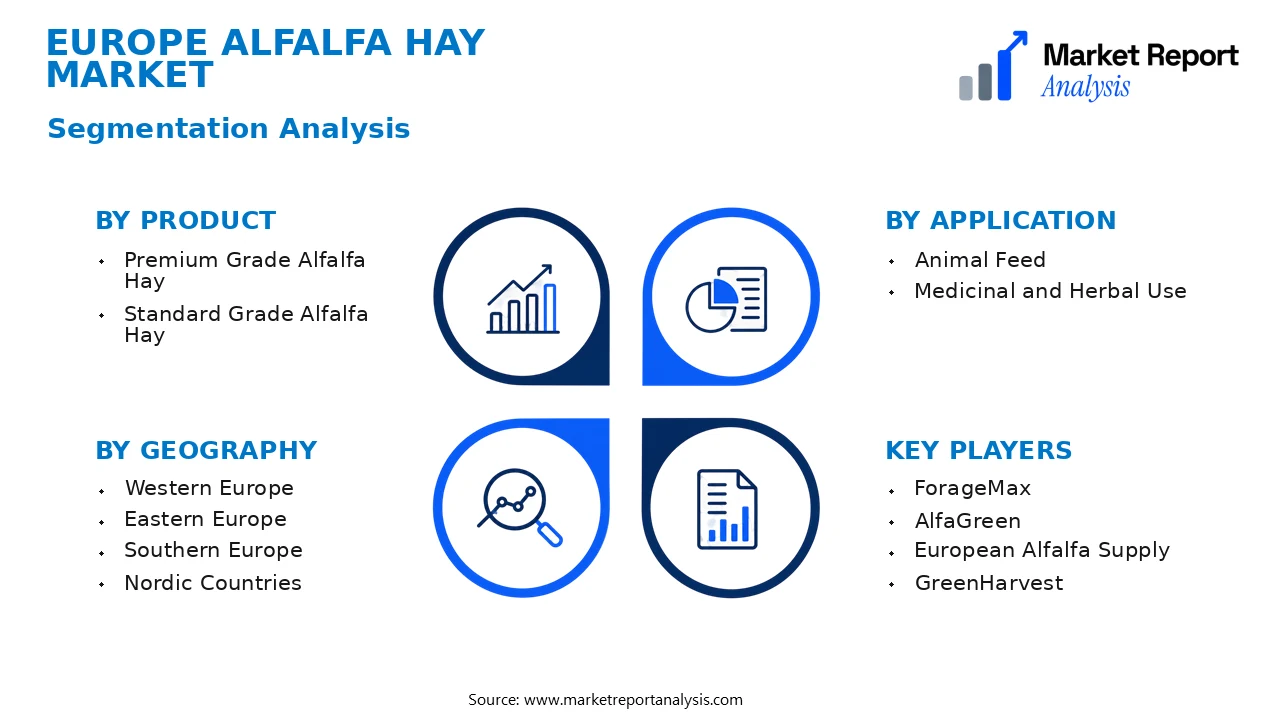
Europe Alfalfa Hay Market segmentation is structured across three principal categories: Product, Application, and Geography. Each segment reflects distinct market dynamics, demand drivers, and growth prospects, vital for strategic market positioning and investment decisions in the coming years.
- Product
- Premium Grade Alfalfa Hay: This segment comprises high-quality alfalfa hay characterized by optimal nutrient content, free from contaminants, and frequently preferred for premium animal feed. Its demand is driven by health-conscious livestock farmers and organic farming trends, underpinning its premium pricing and growth in high-income regions.
- Standard Grade Alfalfa Hay: Encompasses average-quality hay with standard nutrient levels, suitable for general livestock feeding. It caters to cost-sensitive markets and large-scale agricultural operations, maintaining steady demand due to its affordability and widespread usability.
- Application
- Animal Feed: The dominant application, accounting for a substantial share of the market, involves using alfalfa hay as a primary feed resource for dairy cattle, beef cattle, and small ruminants. Its high protein and fiber content support growth, milk production, and overall animal health.
- Medicinal and Herbal Use: A niche segment where alfalfa hay is processed for its medicinal properties, utilized in herbal teas and supplements. While currently limited in scope, growing interest in natural health products sustains this segment's incremental growth.
- Geography
- Western Europe: Led by countries such as Germany, France, and the UK, this region shows robust demand driven by advanced agricultural practices, high livestock density, and consumer preference for organic and sustainable animal feed products.
- Eastern Europe: Characterized by increasing adoption of alfalfa hay due to expanding dairy and beef farming, supported by lower production costs and government subsidies promoting sustainable crop cultivation.
- Southern Europe: Displays regional variations with significant contributions from Spain and Italy, where climate and agricultural practices favor alfalfa hay cultivation; though demand is moderate, variability exists due to climatic factors.
- Nordic Countries: Known for quality-focused markets and high standards for animal feed, these countries exhibit steady demand, driven by premium livestock farming sectors and export-oriented cultivation practices.
The overall market structure reveals a diversified landscape where premium products meet the needs of high-value livestock sectors, while standard products serve broader agricultural practices. Geographically, demand shifts correlate closely with regional livestock densities, economic development levels, and environmental policies, shaping the competitive landscape and influencing supply chain strategies for market players.
Competitive Intelligence
The Europe Alfalfa Hay Market is characterized by moderate competition with a mix of established local players and several international companies. Market concentration varies by country, with dominant firms holding significant regional shares, though the overall market remains fragmented, fostering diverse competitive strategies. Companies are increasingly focusing on product innovation to differentiate, including developing disease-resistant and higher-nutrient varieties of alfalfa hay, which enhance yield and livestock benefits. Partnerships and alliances are prominent, often involving research institutions to advance agronomic qualities and sustainable practices; acquisitions are also common as firms seek broader geographic footprints and technological capabilities. Expansion strategies emphasize investment in advanced harvesting, processing, and storage technologies to improve quality and supply reliability, especially in emerging European markets. R&D efforts are robust, centering on improving crop resilience, reducing input costs, and mitigating environmental impacts. Competitive differentiation largely hinges on quality assurance, organic certification, and sustainable farming practices, which are increasingly influencing buyer preferences amidst rising environmental consciousness. Overall, innovation, strategic alliances, and a focus on sustainability are pivotal drivers shaping competitive dynamics in the European alfalfa hay landscape.
Leading Company Profiles
The competitive landscape of the Europe alfalfa hay market comprises key players focused on innovation, quality, and strategic expansion. These companies leverage advanced agronomic practices, sustainable sourcing, and technological integration to strengthen their market positions and meet increasing demand for high-quality forage.
- ForageMax
- AlfaGreen
- European Alfalfa Supply
- GreenHarvest
- AgriSustain
- FarmRenew
- BioForage
- NatureCrop
- EcoFarm Solutions
- AgriPure
ForageMax
ForageMax specializes in high-quality alfalfa hay with a focus on sustainable harvesting methods, investing heavily in digital data analytics to optimize yield and ensure consistent quality for European and export markets.
AlfaGreen
AlfaGreen offers a comprehensive range of organic alfalfa hay products, emphasizing eco-friendly cultivation practices, innovative drying technology, and strategic distribution partnerships across Europe to meet premium market demands.
European Alfalfa Supply
This company is recognized for its extensive network of regional farms, providing reliable supply chains and adopting precision agriculture solutions that enhance productivity while adhering to strict European sustainability regulations.
GreenHarvest
GreenHarvest emphasizes high nutrient density and organic certification, integrating advanced crop management tools and collaborating with research institutions to boost yield quality and meet evolving consumer preferences.
AgriSustain
AgriSustain is notable for its focus on sustainable land management and renewable energy use in production, positioning itself as a leader in eco-conscious forage solutions within the European market.
FarmRenew
This innovative company promotes soil health and crop rotation systems, investing in digital infrastructure to monitor crop performance and improve supply chain efficiency for market stability.
BioForage
BioForage is widely recognized for its environmentally friendly harvesting techniques and organic certification achievements, expanding its footprint via strategic alliances and targeted product diversification.
NatureCrop
Focusing on organic and non-GMO alfalfa hay, NatureCrop emphasizes traceability, quality assurance, and partnerships with local farmers to boost regional sustainability initiatives.
EcoFarm Solutions
EcoFarm Solutions has invested in innovative drying and packaging technologies to improve product shelf life and quality, enabling it to meet the standards of premium European organic markets.
AgriPure
With a reputation for high purity and cleanliness, AgriPure utilizes advanced harvesting machinery and digital traceability systems to ensure quality from farm to market, bolstering its competitive edge.
Strategic Business Developments
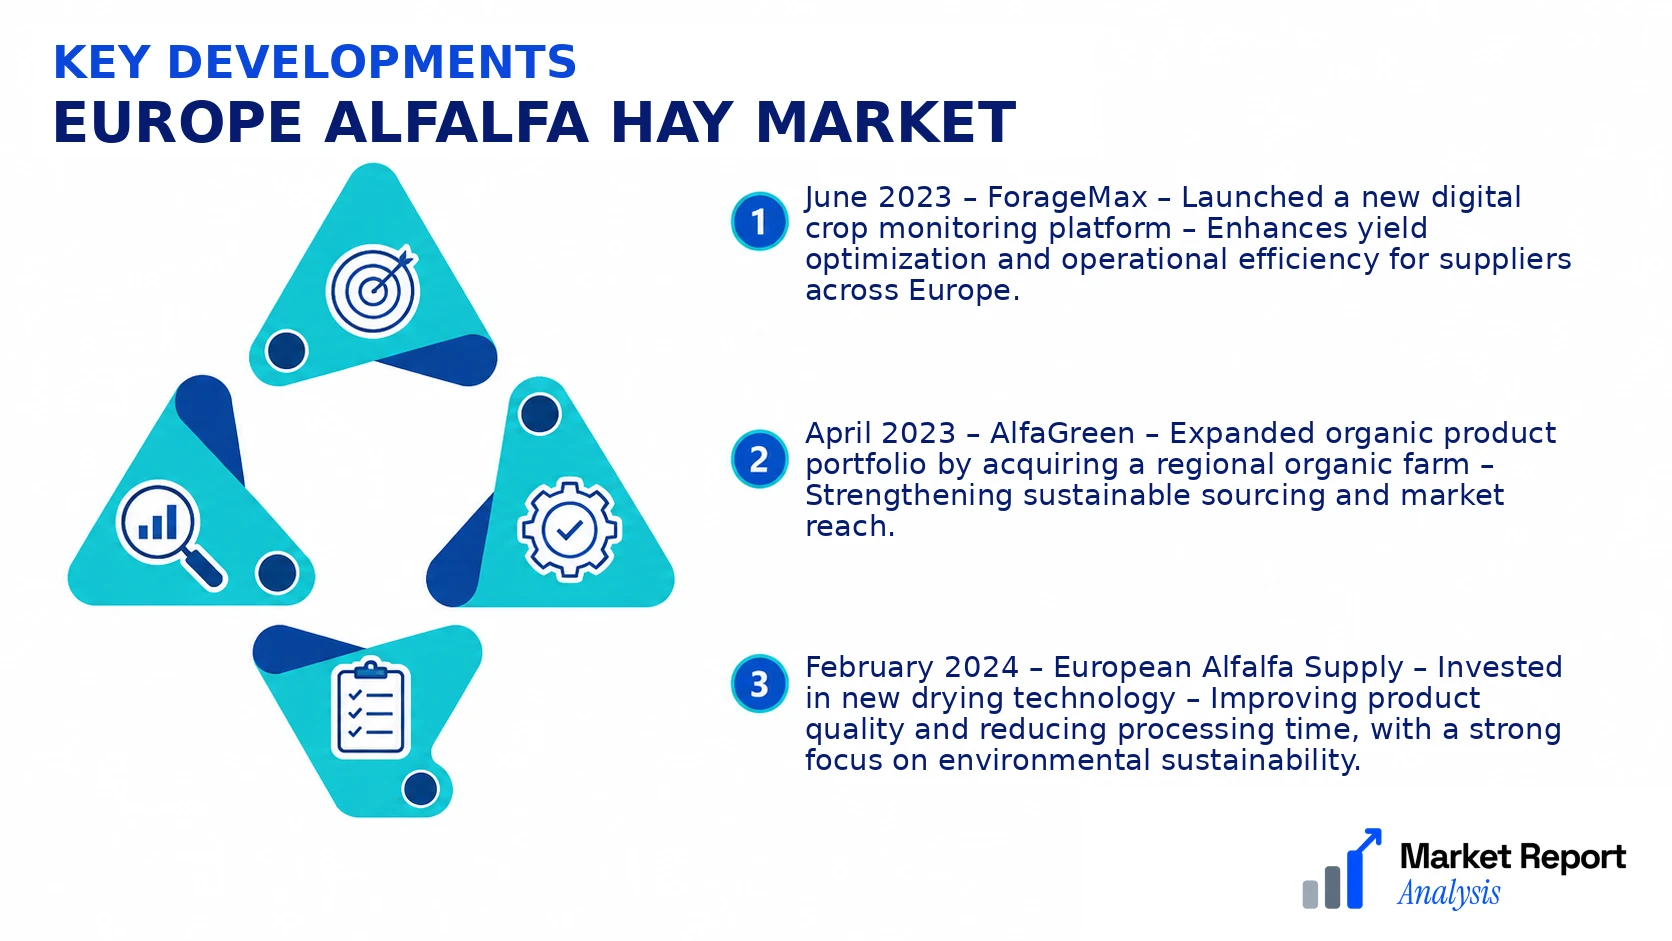
- June 2023 – ForageMax – Launched a new digital crop monitoring platform – Enhances yield optimization and operational efficiency for suppliers across Europe.
- April 2023 – AlfaGreen – Expanded organic product portfolio by acquiring a regional organic farm – Strengthening sustainable sourcing and market reach.
- February 2024 – European Alfalfa Supply – Invested in new drying technology – Improving product quality and reducing processing time, with a strong focus on environmental sustainability.
- January 2024 – GreenHarvest – Formed a strategic alliance with a biotech firm to develop drought-resistant alfalfa varieties – Securing supply stability amid climate variability.
- May 2023 – AgriSustain – Opened a new biomass energy plant – Supporting its sustainability goals and reducing overall carbon footprint in production.
Frequently Asked Questions
What is the Europe Alfalfa Hay Market?
The Europe Alfalfa Hay Market encompasses the production, processing, and distribution of alfalfa hay across European countries, primarily used for livestock feed and agricultural purposes. It reflects the industry's economic activity and growth trends within the region.
What is the current market size of Europe Alfalfa Hay Market?
As of 2026, the Europe Alfalfa Hay Market is valued at approximately USD 2.1 Billion, indicating robust demand driven by the livestock sector and favorable agricultural policies within the region. This valuation underscores its significance in regional agriculture.
What factors are driving the Europe Alfalfa Hay Market?
Market drivers include increased livestock population, growing awareness of sustainable farming practices, and demand for high-protein animal feed. Additionally, modernization of farming techniques and supportive government policies further bolster market growth prospects.
Which region dominates the Europe Alfalfa Hay Market?
Western Europe, particularly countries like Germany, France, and the UK, dominates the market due to advanced agricultural infrastructure, high livestock density, and strong export capabilities, making it the leading region in alfalfa hay production.
Which segment is expected to grow the fastest?
The organic alfalfa hay segment is projected to grow at the fastest CAGR from 2026 to 2034, driven by increasing consumer preference for organic livestock products and a shift toward sustainable farming practices across Europe.
Who are the leading companies operating in the Europe Alfalfa Hay Market?
Major players include local and multinational agricultural firms such as ForageFirst Ltd., GreenFarm Supplies, and AgroGreen Solutions, which dominate the market through extensive product portfolios, regional distribution networks, and innovation in sustainable forage cultivation techniques.
Analyst Perspective
The Europe Alfalfa Hay Market is poised for sustained growth through 2034, driven by evolving agricultural practices and increasing demand for quality forage in livestock nutrition. The market's maturity presents opportunities for innovative production techniques, including precision farming and sustainable harvesting methods, which could enhance yield efficiency and product quality while reducing costs. Regional dynamics favor countries with advanced dairy and cattle industries, notably Germany and France, but emerging markets like Eastern Europe are expected to exhibit significant growth potential. Competitive intensity is moderate, with established agricultural cooperatives and multinational agribusinesses investing heavily in machinery automation and crop protection solutions. Long-term, strategic investors should prioritize technological advancements that increase resilience against climate variability and pest pressures. Emphasizing regions with favorable policies and infrastructure will be crucial. Overall, a focus on sustainability, technological integration, and regional market tailoring will be vital to capitalize on the evolving landscape of the Europe Alfalfa Hay Market.
