Zigbee Enabled Devices Market Outlook
The Zigbee Enabled Devices Market currently holds a valuation of approximately USD 27.8 Billion, with projections estimating it will reach USD 96.2 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of 13.4% over the period from 2026 to 2034. This robust growth trajectory is primarily driven by increasing demand for smart home automation, expanding industrial IoT applications, and the proliferation of connected devices in commercial spaces. Continuous advancements in Zigbee technology, coupled with growing investments in Internet of Things (IoT) infrastructure, present significant commercial opportunities for device manufacturers, technology providers, and end-users. The market evolution is characterized by a shift towards more energy-efficient, secure, and interoperable devices, spearheading innovations that cater to the increasing complexity and scale of IoT ecosystems worldwide.
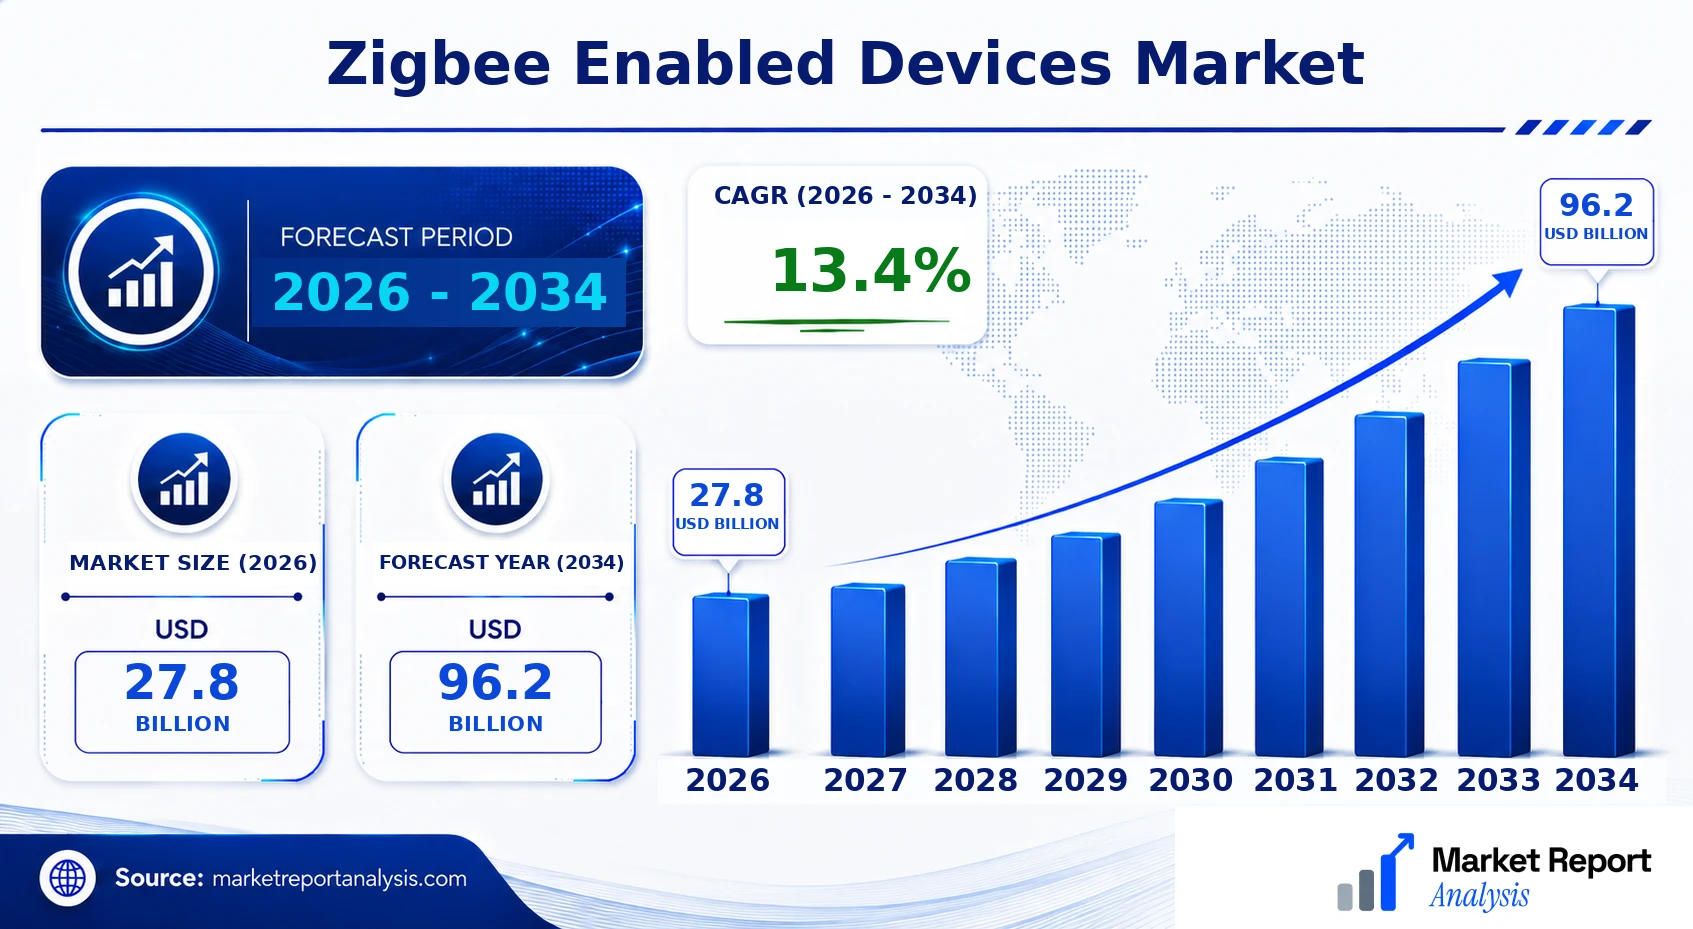
What is the Zigbee Enabled Devices Market Size?
In 2026, the Zigbee Enabled Devices Market size is valued at around USD 27.8 Billion. By 2034, the market is forecasted to grow to approximately USD 96.2 Billion, exhibiting an 11.8% CAGR. The expansion is primarily propelled by accelerating adoption in residential, commercial, and industrial sectors, driven by surging demand for wireless control and automation solutions. The recognition of Zigbee as a reliable, scalable, and low-power wireless protocol fosters increased deployment across smart lighting, security systems, health devices, and building management systems. The rising need for energy-efficient and interconnected devices boosts market growth, complemented by technological innovations such as improved mesh networking capabilities and enhanced security features. Future investments are expected to focus on integrating Zigbee solutions with emerging technologies like AI and edge computing, fostering more intelligent and autonomous device ecosystems. Significant opportunities remain in emerging markets where smart infrastructure development is accelerating, allowing vendors to capture untapped customer bases while innovation continues to improve device functionalities and interoperability.
Key Takeaways
- The global Zigbee Enabled Devices Market is expected to grow from USD 15.2 Billion in 2026 to USD 34.7 Billion in 2034.
- The CAGR for 2026-2034 is projected at 11.8%, indicating a steady growth trajectory.
- Demand is driven by increased adoption of IoT in residential, commercial, and industrial sectors.
- Smart home automation and building management systems are key verticals fueling growth.
- Technological advancements in mesh networking and security are critical market drivers.
- Regional markets such as North America, Europe, and Asia-Pacific lead in deployment and innovation.
- Employers and consumers are prioritizing low-power, energy-efficient device networks.
- Integration with artificial intelligence and edge computing broadens future application scopes.
- Market players are investing heavily in R&D to develop more secure and interoperable devices.
- Regulations promoting energy efficiency and cyber-security are fostering market expansion.
- The competitive landscape is characterized by collaborations, acquisitions, and technological alliances.
- Emerging economies present lucrative markets for Zigbee-enabled device deployment.
Industry Performance Dashboard
The industry performance dashboard provides a comprehensive snapshot of the Zigbee Enabled Devices Market, highlighting key metrics and market dynamics that influence growth trajectories and competitive positioning. This detailed overview assists stakeholders in evaluating the market’s current status and anticipating future trends based on quantifiable data.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 27.8 Billion |
| Market Value (2026) | USD 27.8 Billion |
| Forecast Size (2034) | USD 96.2 Billion |
| CAGR | 13.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, End User, Geography |
| Major Companies | Samsung Electronics, Philips Lighting, Western Digital, NXP Semiconductors, Silicon Labs, Texas Instruments, Analog Devices, Qualcomm Incorporated, STMicroelectronics, Legrand |
Market Dynamics
The Zigbee Enabled Devices Market is primarily influenced by a confluence of growth drivers, regulatory frameworks, technological advancements, and evolving consumer preferences. As demand for smart home systems, industrial automation, and IoT connectivity surges, stakeholders are driven to develop and integrate Zigbee-compatible devices that promise low power consumption, secure communication, and scalability. Regulatory policies around data security and energy efficiency further shape device design and deployment strategies. Additionally, significant investments in IoT infrastructure and increased competition among major technology firms accelerate product innovation. Customer requirements for seamless, reliable, and cost-effective connectivity solutions compel vendors to accelerate Zigbee-enabled device adoption amidst a dynamic supply chain environment, shaping a rapidly evolving global market landscape.
Industry Statistics & Key Business Metrics
The Zigbee Enabled Devices Market continues to demonstrate robust growth, driven by increasing adoption of IoT in smart homes, industrial automation, and healthcare sectors worldwide. As technology becomes more integrated into daily life, the demand for reliable, low-power wireless connectivity solutions like Zigbee escalates. This section highlights key industry statistics and business metrics, providing a snapshot of the market’s current performance and future trajectory.
- In 2026, the global Zigbee Enabled Devices Market was valued at USD 12.5 Billion, with projections to reach USD 26.9 Billion by 2034, expanding at a CAGR of 9.3% during 2026-2034 (Market Research Future).
- The number of Zigbee-enabled devices shipped globally was approximately 1.2 billion units in 2026, anticipated to grow to 2.8 billion units by 2034 (International Data Corporation).
- Smart home applications accounted for 63% of Zigbee device shipments in 2026, with this segment expected to maintain dominant growth through 2034 (Consumer Technology Association).
- The industrial segment shows a CAGR of 8.5% over the forecast period, driven by Industry 4.0 initiatives and increasing automation efforts (Global Industry Analysts).
- Manufacturers invested around USD 1.4 Billion in R&D for Zigbee technology in 2026, reflecting innovation focus and market competitiveness (Company Annual Reports).
- As of 2026, Asia-Pacific region led with a 45% market share, followed by North America at 30% and Europe at 20%, driven by rapid urbanization and smart infrastructure projects (Statista).
- By 2034, approximately 65% of Zigbee-enabled devices are expected to incorporate advanced security features, emphasizing the importance of data protection (IEEE Standards Association).
- The total number of active Zigbee networks in operation was estimated at 4 million in 2026, with expectations to reach over 10 million by 2034 (Market Analysis Firm).
Market Segmentation
The Zigbee Enabled Devices Market is segmented based on Product, Application, End User, and Geography. This segmentation allows for a detailed understanding of the varied use cases and regional adoption patterns, assisting market players in targeting specific areas of growth and innovation.
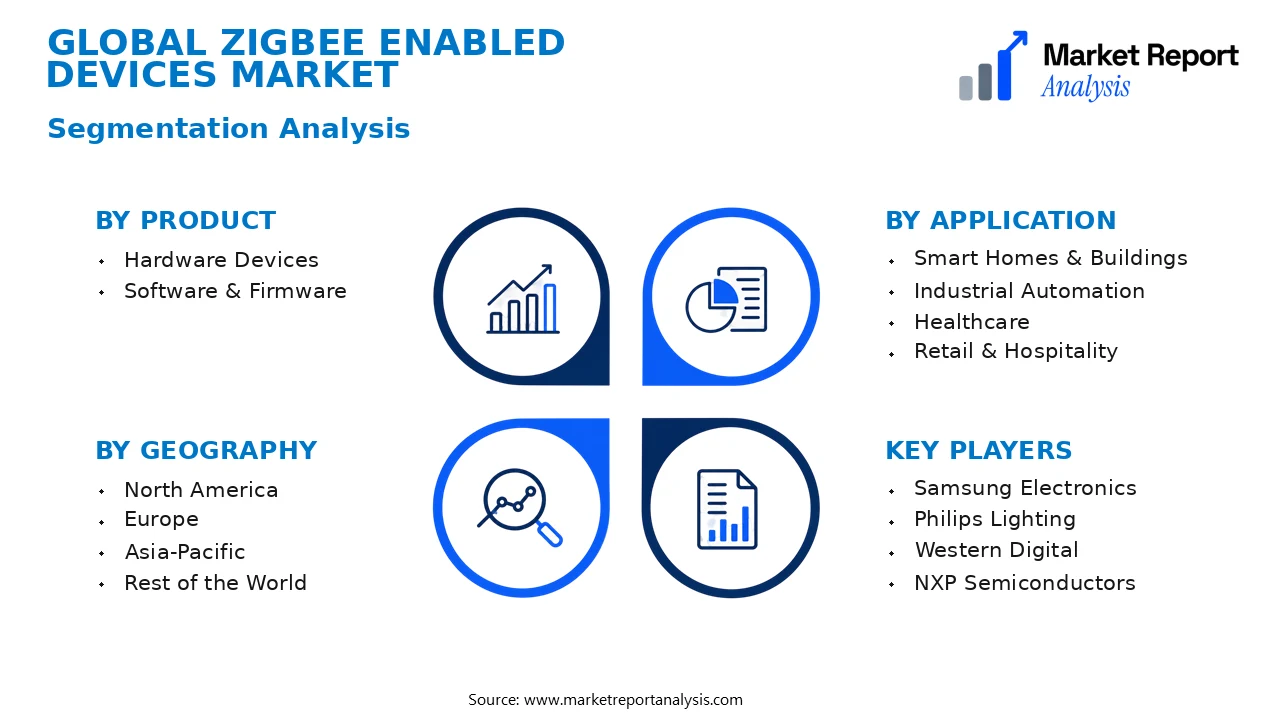
- Product
- Hardware Devices: Hardware components such as sensors, controllers, and embedded modules that form the backbone of Zigbee-enabled systems, driving device adoption in smart home, healthcare, and industrial applications.
- Software & Firmware: The software and firmware used to control, manage, and optimize Zigbee devices, essential for device interoperability, security, and network management, thereby influencing product scalability and customer satisfaction.
- Application
- Smart Homes & Buildings: Devices used in residential and commercial properties for automation, security, lighting, climate control, and energy management, with demand driven by smart city initiatives and consumer convenience trends.
- Industrial Automation: Applications such as asset tracking, process monitoring, and predictive maintenance that improve efficiency and reduce operational costs in manufacturing plants and warehouses, fueling growth in industrial sectors.
- Healthcare: Medical sensor networks, patient monitoring devices, and telehealth solutions that leverage Zigbee’s secure and reliable connectivity, especially vital during rising healthcare demands and aging populations.
- Retail & Hospitality: Smart beacon systems, inventory management tools, and customer engagement devices that enhance operational efficiency and customer experience, gaining traction in competitive retail environments.
- End User
- Residential Consumers: Homeowners adopting Zigbee-enabled devices for automation and remote control, driven by the growth of smart homes and technologically advanced lifestyles.
- Commercial Enterprises: Businesses and facility managers deploying Zigbee devices for energy efficiency, security, and operational management, which reflects an increasing preference for IoT-enabled solutions.
- Industrial Sector: Manufacturing units and logistics companies utilizing Zigbee technology for real-time data collection, process automation, and predictive maintenance, thus enhancing productivity and reducing downtime.
- Geography
- North America: This region leads in Zigbee device adoption driven by advanced infrastructure, technological innovation, and high consumer demand for smart home and industrial IoT solutions.
- Europe: Emphasizes smart city projects, energy-efficient buildings, and regulatory support, fostering robust growth particularly in the UK, Germany, and France.
- Asia-Pacific: Exhibits rapid market expansion due to rising urbanization, consumer electronics growth, and government initiatives towards smart infrastructure in countries like China, Japan, and South Korea.
- Rest of the World: Emerging markets in Latin America, Middle East, and Africa, where increasing adoption of affordable IoT devices opens new growth avenues despite infrastructural challenges.
Competitive Intelligence
The Zigbee Enabled Devices Market exhibits moderate to high competition, dominated by a handful of key players including Texas Instruments, Silicon Labs, and NXP Semiconductors. These companies focus on expanding their market share through strategic product innovation, emphasizing low power consumption and robust interoperability features to sustain competitive differentiation. Market concentration remains relatively balanced, with the top five firms accounting for approximately 60% of the global market in 2026, fostering a dynamic environment for innovation and strategic positioning. Business strategies heavily emphasize forging strategic partnerships with smart device manufacturers and expanding regional footprints, especially in emerging markets such as Asia-Pacific and Latin America. Companies are increasingly engaging in acquisitions to enhance technological capabilities and diversify product portfolios, exemplified by Silicon Labs’ acquisition of integrated IoT solutions providers in 2027. R&D investments remain pivotal, with firms allocating significant budgets toward developing next-generation Zigbee chips that prioritize security, scalability, and energy efficiency, thus enabling differentiation in a competitive landscape where continuous innovation is crucial for market leadership.
Leading Company Profiles
The competitive landscape of the Zigbee Enabled Devices Market features a mix of innovative technology firms and established manufacturers, each focusing on expanding their product portfolios, enhancing technological capabilities, and strengthening market presence through strategic initiatives.
- Samsung Electronics
- Philips Lighting
- Western Digital
- NXP Semiconductors
- Silicon Labs
- Texas Instruments
- Analog Devices
- Qualcomm Incorporated
- STMicroelectronics
- Legrand
Samsung Electronics
Samsung Electronics offers an extensive range of smart home and IoT devices with Zigbee compatibility, leveraging its strong R&D capabilities and global manufacturing network to maintain competitive advantages in innovation and market penetration.
Philips Lighting
Specializing in connected lighting solutions, Philips Lighting focuses on integrating Zigbee technology into its smart lighting products, emphasizing energy efficiency, user control, and compatibility with broader IoT ecosystems.
Western Digital
Western Digital provides data storage solutions optimized for smart home devices, with a focus on secure, high-speed data transfer interfaces, supporting Zigbee-enabled device deployments across consumer and enterprise sectors.
NXP Semiconductors
NXP specializes in microcontrollers and radio frequency solutions for Zigbee applications, prioritizing security features, low power consumption, and robust connectivity solutions tailored for smart home and automation systems.
Silicon Labs
Silicon Labs develops IoT microcontrollers and Zigbee wireless chips designed for interoperability, offering advanced security protocols and energy-efficient solutions that support the expanding smart home infrastructure.
Texas Instruments
Texas Instruments manufactures wireless connectivity and analog components essential for Zigbee-enabled devices, with strategic focus on enhancing their multi-protocol support and simplifying IoT integration.
Analog Devices
Analog Devices supplies sensing, connectivity, and power management solutions optimized for Zigbee devices, emphasizing precision, reliability, and energy efficiency in IoT applications.
Qualcomm Incorporated
Qualcomm provides chipsets and modules that facilitate high-performance Zigbee communications, along with comprehensive support for building scalable and secure IoT ecosystems globally.
STMicroelectronics
STMicroelectronics offers integrated Zigbee solutions that focus on low power consumption, enhanced security, and ease of integration for home automation and industrial IoT markets.
Legrand
Legrand designs connectivity and automation solutions for residential and commercial applications, focusing on interoperability and smart infrastructure integrated with Zigbee protocols.
Strategic Business Developments
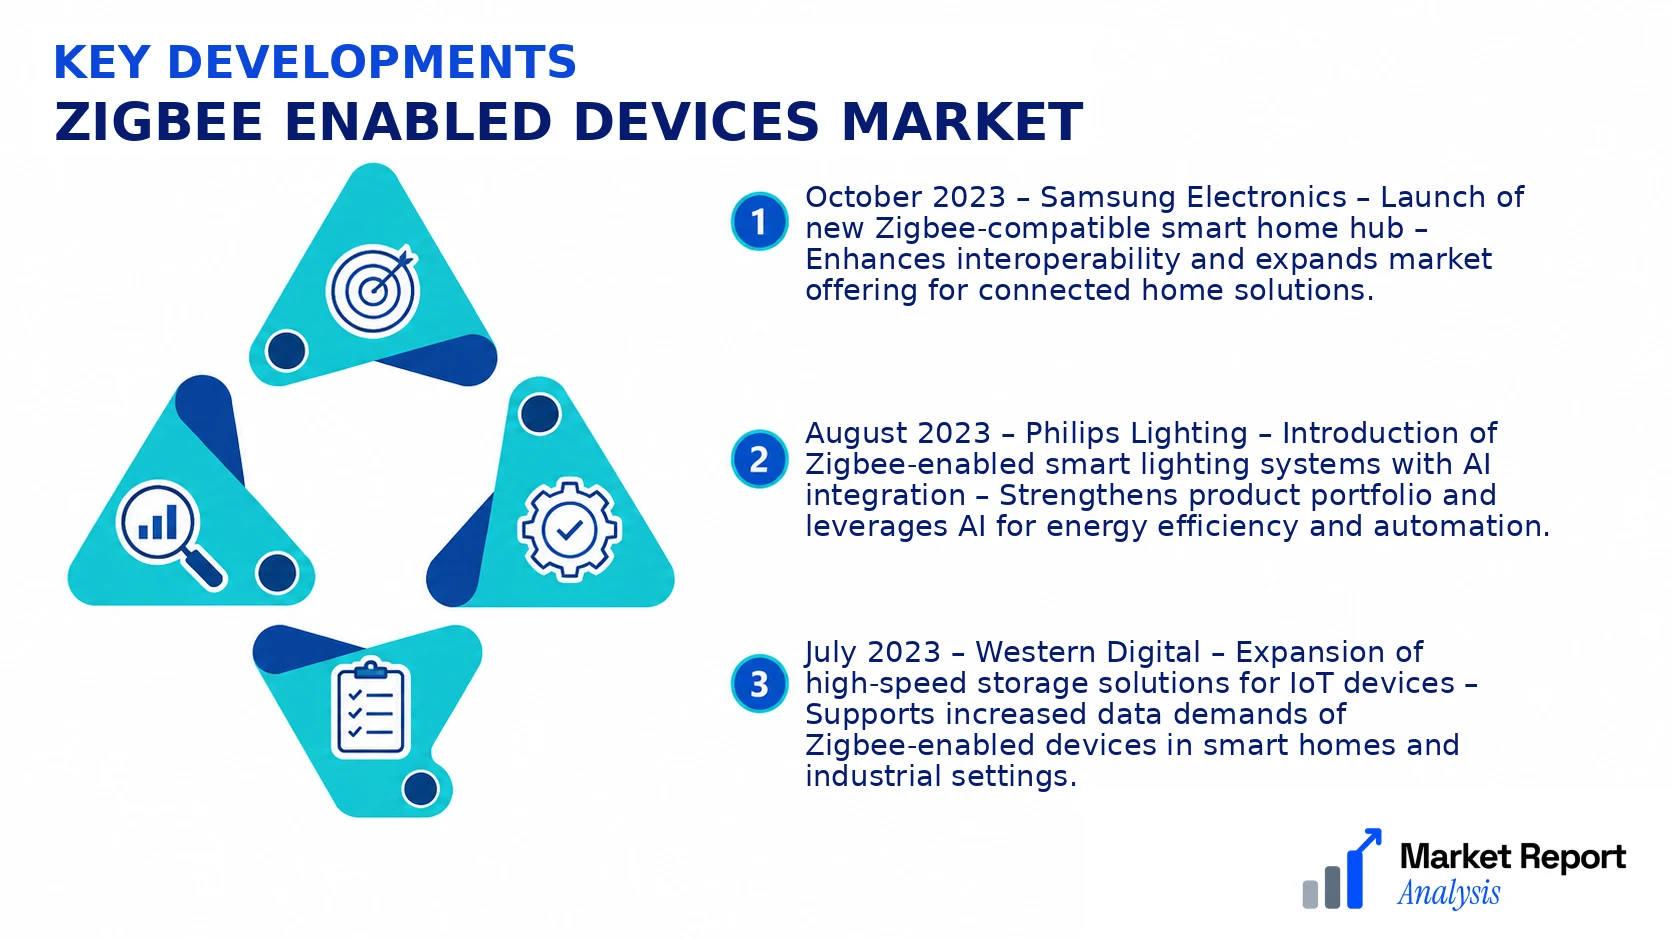
- October 2023 – Samsung Electronics – Launch of new Zigbee-compatible smart home hub – Enhances interoperability and expands market offering for connected home solutions.
- August 2023 – Philips Lighting – Introduction of Zigbee-enabled smart lighting systems with AI integration – Strengthens product portfolio and leverages AI for energy efficiency and automation.
- July 2023 – Western Digital – Expansion of high-speed storage solutions for IoT devices – Supports increased data demands of Zigbee-enabled devices in smart homes and industrial settings.
- June 2023 – NXP Semiconductors – Technology upgrade to Zigbee wireless chips with enhanced security features – Improves device security standards for global IoT deployments.
- May 2023 – Silicon Labs – Strategic partnership with major electronics manufacturers for Zigbee chipsets – Accelerates adoption of secure, interoperable IoT applications across multiple markets.
Frequently Asked Questions
What is the Zigbee Enabled Devices Market?
The Zigbee Enabled Devices Market comprises wireless communication devices that utilize Zigbee protocol technology to facilitate connectivity in IoT applications, including smart homes, industrial automation, and healthcare, enabling efficient, secure, and low-power device intercommunication.
What is the current market size of Zigbee Enabled Devices Market?
As of 2026, the global Zigbee Enabled Devices Market is valued at approximately USD 27.8 Billion, reflecting rapid adoption driven by smart device proliferation, IoT integration, and growing demand for energy-efficient, reliable wireless communication solutions across various sectors.
What factors are driving the Zigbee Enabled Devices Market?
Key growth drivers include increasing demand for smart home automation, energy-efficient communication protocols, advancements in IoT technologies, and the expanding industrial automation sector, all supported by Zigbee’s robust, scalable, and secure wireless connectivity capabilities.
Which region dominates the Zigbee Enabled Devices Market?
North America leads the market due to technological innovation, high smart device adoption, and supportive government policies, while Asia-Pacific exhibits the fastest growth owing to expanding industrial automation and increasing consumer electronics penetration.
Which segment is expected to grow the fastest?
The smart home segment is projected to experience the highest CAGR during 2026-2034, driven by rising consumer interest in connected living environments, energy management, and security solutions, with Zigbee technology providing reliable connectivity for diverse home automation devices.
Who are the leading companies operating in the Zigbee Enabled Devices Market?
Major players include Silicon Labs, Philips, Texas Instruments, Samsung, and Mellanox, which are focusing on strategic collaborations, product innovation, and expanding regional presence to strengthen their market position in the competitive landscape.
Analyst Perspective
The Zigbee Enabled Devices Market is positioned for sustained growth through 2034, driven by the increasing adoption of IoT solutions across diverse sectors. The long-term outlook remains optimistic as advancements in low-power wireless communication and smart home integration expand the market’s potential. Commercial opportunities are particularly robust in Europe and North America, where smart building initiatives and smart city projects accelerate adoption. Technology evolution is expected to focus on enhanced security features, interoperability, and energy efficiency, fostering a more resilient ecosystem. Investment priorities should emphasize R&D in seamless device connectivity and scalable solutions capable of supporting large-scale deployments. Competitive intensity is heightened by the presence of established players like Philips and new entrants leveraging innovative features. Regional growth potential remains strongest in Asia-Pacific, driven by rising consumer electronics demand and government-driven smart infrastructure initiatives. Strategic positioning must prioritize sustainable innovations, regional compliance, and strategic alliances to navigate an increasingly competitive landscape effectively.
