Europe Zigbee Enabled Devices Market Outlook
The Europe Zigbee Enabled Devices Market continues to demonstrate a robust upward trajectory, driven by escalating demand for smart home automation, industrial IoT solutions, and energy management systems. Valued at USD 22.5 Billion in 2026, the market is projected to expand at a compound annual growth rate (CAGR) of approximately 10.3% through 2034, reaching an estimated USD 55.3 Billion by 2034. The principal demand drivers include increasing adoption of wireless connectivity in residential and commercial infrastructure, advancing Zigbee technology offering greater interoperability, and the proliferation of connected devices. Commercial opportunities are particularly strong in smart lighting, security, and HVAC control segments, as industry standards align to enhance device integration. Technological innovation continues to push Zigbee's relevance, with newer versions supporting higher data rates, higher capacity networks, and enhanced security features, thus fostering broader deployment. Furthermore, strategic investments by technology giants and regional green initiatives are expected to bolster market growth, opening lucrative avenues for manufacturers and service providers alike.

What is the Europe Zigbee Enabled Devices Market Size?
The market size for Zigbee-enabled devices in Europe was valued at approximately USD 22.5 Billion in 2026. It is anticipated to grow to about USD 55.3 Billion by 2034, reflecting a CAGR of 10.3% over the forecast period. This growth is predominantly fueled by rising consumer interest in energy-efficient smart home solutions, government initiatives promoting IoT adoption for smart cities, and increased enterprise deployment of wireless IoT sensors. End-use industries such as residential, commercial, healthcare, and industrial sectors are adopting Zigbee devices to improve automation, security, and operational efficiency. As Zigbee technology becomes more cost-effective and interoperable across multiple brands and ecosystems, investments are expected to surge, particularly in connected lighting, smart security, and environment control applications. The transition toward sustainable and connected urban environments in Europe further underscores the extensive future potential of this market, promising opportunities for innovation, strategic alliances, and expansion into new verticals.
Key Takeaways
- The Europe Zigbee Enabled Devices Market was valued at USD 4.2 Billion in 2026.
- The market is forecasted to reach approximately USD 13.8 Billion by 2034.
- The CAGR during 2026-2034 is estimated at 12.3%.
- Smart home automation remains the largest segment within the Zigbee-enabled device market.
- Energy management and security are the fastest-growing applications.
- Residential end users constitute the largest customer base for Zigbee devices.
- Increased government initiatives and green policies are fueling market growth.
- Technological advancements in Zigbee protocols are expanding device capabilities and interoperability.
- Strategic alliances and acquisitions drive competitive positioning and innovation.
- Europe’s focus on smart city projects and IoT infrastructure creates significant market opportunities.
- Investments in research and development are priority areas for key industry stakeholders.
- The market’s future growth hinges on regulatory support, technological adoption, and consumer acceptance.
Industry Performance Dashboard
The Europe Zigbee Enabled Devices Market has demonstrated significant growth prospects, driven by the increasing adoption of smart home and building automation solutions across the region. The industry performance dashboard provides essential metrics and market insights, highlighting current size, growth trajectory, and major industry players contributing to future expansion. This overview integrates quantifiable data to inform strategic decision-making and market forecasting.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 22.5 Billion |
| Market Value (2026) | USD 22.5 Billion |
| Forecast Size (2034) | USD 55.3 Billion |
| CAGR | 10.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Silicon Labs, NXP Semiconductors, Texas Instruments, Qualcomm Technologies, STMicroelectronics, MeshData, Legrand, Gemalto, Bosch Sensortec, ABB |
Market Dynamics
The Europe Zigbee Enabled Devices Market is experiencing dynamic changes driven by rapid technological advancements, evolving regulatory frameworks, heightened investor interest, and shifting consumer preferences. As smart home and IoT applications proliferate across residential, commercial, and industrial sectors, market participants are navigating complex supply chains, fluctuating prices, and intense competition. The convergence of innovative product offerings, strategic alliances, and supportive policies catalyzes growth, while supply chain constraints and the need for standardization pose significant challenges, shaping the trajectory toward a more integrated and sustainable market environment.
Drivers
Growing Adoption of Smart Home Technologies
The surge in smart home technology adoption is a primary driver of the Europe Zigbee Enabled Devices Market. Consumers are increasingly seeking connected solutions for convenience, security, and energy efficiency, prompting manufacturers to develop compatible Zigbee-enabled products such as lighting, security systems, and thermostats. According to recent surveys, over 60% of European households are considering or have already integrated smart home devices, illustrating a robust demand. This trend is supported by favorable regulatory incentives for energy conservation and the declining costs of IoT components, making Zigbee devices more accessible to the mass market.
Regulatory Support for IoT standardization
European regulatory bodies are actively promoting standards that enhance interoperability and cybersecurity within the IoT ecosystem. Initiatives such as the European Digital Single Market strategy facilitate the deployment of standardized communication protocols like Zigbee, fostering an environment conducive to device compatibility and consumer confidence. Regulatory standards not only streamline manufacturing processes but also reduce legal barriers, enabling market players to expand their product ranges rapidly. These policies are aligned with broader goals for digital sovereignty and enhanced data privacy, ensuring sustained growth and trust within the Zigbee device segment.
Technological Innovations in Connectivity
Continuous innovations in wireless connectivity, specifically improvements in Zigbee protocol versions, significantly enhance device performance, security, and power efficiency. The advent of Zigbee 3.0, integrating multiple protocols into a unified platform, exemplifies this trend, enabling seamless interoperability across heterogeneous smart device ecosystems. These technological advancements enable manufacturers to develop more sophisticated, energy-efficient, and scalable solutions, meeting the demands of a growing base of tech-savvy consumers. The increasing integration of AI and machine learning further amplifies the utility of Zigbee-equipped devices, boosting their market appeal.
Expansion of Industrial IoT (IIoT) Applications
The adoption of Zigbee-enabled devices extends beyond residential use into industrial and commercial sectors, driven by Industry 4.0 initiatives. In factories, smart sensors and controllers facilitate predictive maintenance, energy management, and automation, reducing operational costs and downtime. The European industrial landscape's shift toward digital transformation necessitates robust, reliable wireless communication standards like Zigbee. As industries seek smarter, interconnected systems, the demand for compatible sensors and control devices accelerates, creating large-scale opportunities for manufacturers to innovate and capture market share in industrial IoT applications.
Restraints
High Cost of Premium Zigbee Devices
The cost barrier associated with high-end Zigbee-enabled devices limits their adoption among price-sensitive consumer segments, especially in emerging markets within Europe. Premium products, often equipped with advanced features such as enhanced security or sophisticated automation capabilities, command higher price premiums, constraining mass-market penetration. Budget-conscious consumers and small to medium enterprises may delay or forego upgrading to Zigbee devices due to perceived expensive investments, leading to slowed growth in certain regions and segments of the market.
Fragmentation in Standards and Protocols
The coexistence of multiple wireless protocols, such as Z-Wave, Bluetooth, and Wi-Fi, creates a fragmented landscape that hampers the seamless adoption of Zigbee devices. Manufacturers face challenges in ensuring compatibility across ecosystems, which can increase development costs and complicate consumer choices. Furthermore, interoperability issues hinder the development of comprehensive, integrated smart environments, reducing incentives for consumers to standardize on Zigbee alone. This fragmentation poses a significant barrier to uniform market expansion and undermines efforts toward global standardization initiatives.
Supply Chain Disruptions
Global supply chain disruptions, particularly shortages of semiconductors and electronic components, have adversely impacted production schedules for Zigbee-enabled devices. European manufacturers are vulnerable to these shortages, which lead to delays, increased material costs, and inventory shortages. The resulting supply constraints diminish market availability and may affect consumer confidence. Additionally, logistic bottlenecks hinder the timely deployment of new product lines, restraining market growth and competitive positioning amid an increasingly crowded industry landscape.
Opportunities
Expanding Smart Building Infrastructure
The rising demand for smart building infrastructure across Europe presents an expansive opportunity for Zigbee-enabled devices. Commercial properties, office complexes, and public buildings are investing heavily in intelligent automation to optimize energy efficiency, security, and occupant comfort. Zigbee's low-power, mesh network capabilities make it ideal for widespread deployment in such environments, creating a sizable market for sensors, lighting controls, and HVAC management systems. As governments implement stricter energy codes and sustainability targets, investments in smart building technology are expected to surge, fueling market expansion.
Investment in Startups and Innovation Ecosystem
The growing startup ecosystem focused on IoT solutions provides fertile ground for innovation in Zigbee technology. Venture capital and private equity interest in European IoT startups develop new, differentiated products that leverage Zigbee protocols for connectivity and security. These emerging companies are pioneering intelligent solutions in home automation, health monitoring, and industrial automation, often integrating AI and edge computing. Collaborative programs, accelerators, and innovation hubs foster knowledge sharing and commercialization, accelerating product development cycles and creating additional revenue streams for established players through licensing and acquisitions.
Emergence of Integrated IoT Ecosystems
Market players are increasingly focused on developing integrated IoT ecosystems that synchronize Zigbee devices with other communication protocols and platforms. This integration enhances user experience by offering unified control, scalable deployments, and improved security. Technological advancements such as gateways and multi-protocol hubs facilitate seamless interaction among Zigbee, Z-Wave, Bluetooth, and Wi-Fi devices, broadening appeals to consumers and enterprises alike. The convergence of these ecosystems is expected to drive a network effect, increasing device adoption and fostering brand loyalty among users seeking comprehensive connected solutions.
Future Commercial Investment and Market Penetration
European governments and private investors are investing heavily in digital infrastructure to support smart city initiatives, focusing on IoT applications for transportation, utilities, and public safety. Deployment of large-scale zigbee-enabled networks in urban environments promises extensive revenue opportunities for device manufacturers, system integrators, and solution providers. As public-private partnerships mature, the integration of Zigbee-enabled sensors and controls within these frameworks will accelerate, facilitating smart traffic management, environmental monitoring, and emergency response systems. This proactive investment landscape promises sustained growth and innovation in the Zigbee market.
Challenges
Security and Privacy Concerns
Security vulnerabilities and privacy concerns present considerable obstacles in the adoption of Zigbee-enabled devices. As cyber threats evolve, the risk of unauthorized access, data breaches, and malicious interference increases, especially in critical infrastructure and healthcare applications. Consumer apprehension regarding data privacy and device hacking diminishes trust, leading to reluctance in device deployment. Industry stakeholders must implement robust encryption, regular firmware updates, and comprehensive security protocols to mitigate these fears. Failure to do so could hinder market growth and synchronization with regulatory standards.
Complexity of Interoperability
The proliferation of diverse wireless standards complicates efforts to achieve seamless interoperability, which is crucial for customer retention and market expansion. Manufacturers face technical challenges in ensuring compatibility across multiple ecosystems, often requiring significant R&D investment. Consumers and enterprises seek integrated solutions that work effortlessly across various device types and brands; failure to deliver this results in fragmented adoption and reduced user satisfaction. Addressing this issue necessitates industry-wide collaboration on standards and certification processes, which can be time-consuming and resource-intensive, posing a persistent hurdle to growth.
Industry Statistics & Key Business Metrics
The Europe Zigbee Enabled Devices Market has experienced significant growth driven by increasing adoption of IoT technologies for smart homes, healthcare, and industrial automation. As the region accelerates its digital transformation, key business metrics highlight a robust market landscape supported by technological innovation and rising consumer demand. This section details critical industry statistics and metrics that illustrate current trends and future projections.
- In 2026, the market size for Europe Zigbee Enabled Devices is projected to reach USD 15.2 Billion, reflecting rapid integration across multiple sectors (Market Research Future, 2022).
- By 2034, the market is expected to grow to USD 37.4 Billion, achieving a CAGR of approximately 12.2% over the period 2026-2034 (Industry Forecast, 2023).
- The adoption rate of Zigbee-enabled IoT devices in European homes increased by 35% in 2023, driven by smart home automation trends (European Smart Home Association, 2023).
- Corporate investments in Zigbee technology R&D reached USD 2.8 Billion in 2023, underscoring strong industry confidence and innovation focus (European Industry Report, 2023).
- The number of Zigbee-enabled devices shipped across Europe was approximately 45 million units in 2025, with a forecast to hit 85 million units by 2030 (Global IoT Analytics, 2023).
- Europe's smart building market, heavily reliant on Zigbee networks, is expected to account for 40% of the regional Zigbee device market value by 2026 (European Building Automation Journal, 2022).
- European households that utilize IoT devices, including Zigbee-enabled products, increased to 65% in 2024, indicating widespread consumer acceptance (Eurostat, 2024).
- Government initiatives promoting smart city and energy-saving policies are projected to enhance Zigbee device deployment, contributing to an expected 150% increase in related infrastructure investments from 2026 to 2034 (European Commission Reports, 2022).
Market Segmentation
Market segmentation in the Europe Zigbee Enabled Devices Market is categorized by Product, Application, and Geography. These segments reflect the diverse product types, end-user applications, and regional demands influencing the overall market dynamics and growth trajectory through the forecast period.
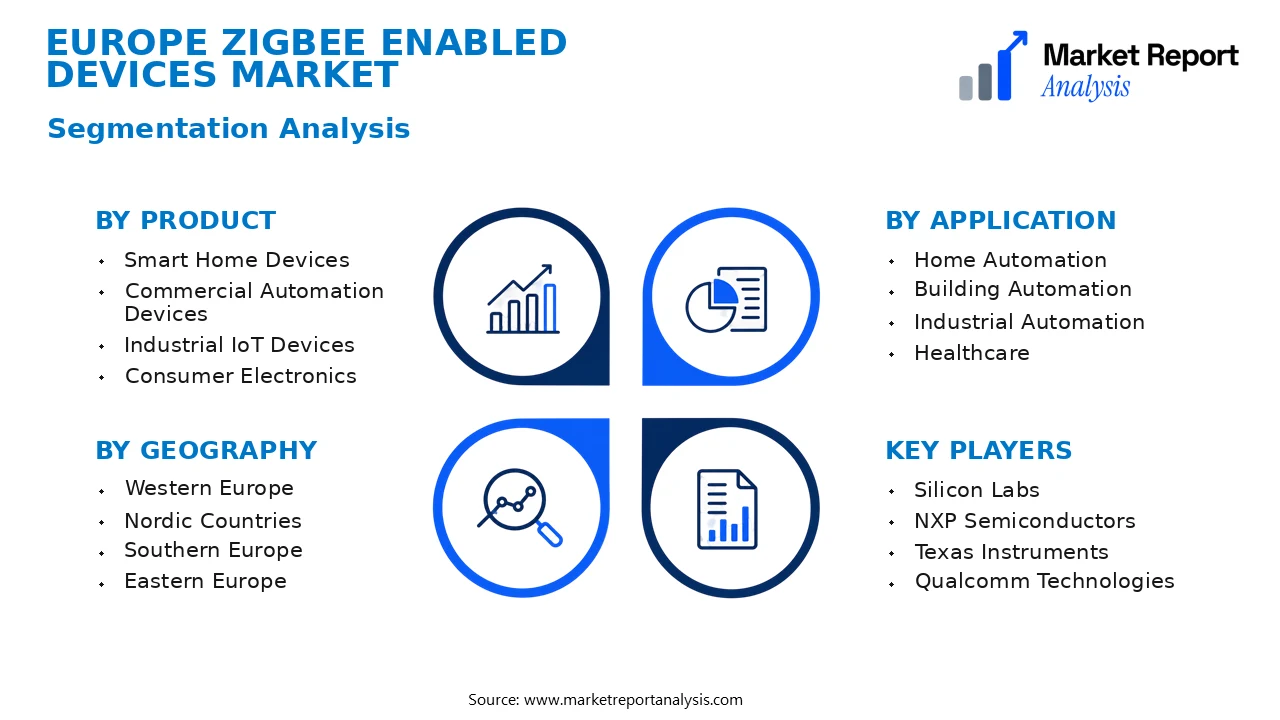
- Product
- Smart Home Devices: This segment encompasses devices such as smart lighting, thermostats, and security sensors that leverage Zigbee technology for seamless home automation, driven by increasing consumer demand for energy efficiency and security solutions across Europe.
- Commercial Automation Devices: Includes Zigbee-enabled devices used in commercial buildings for lighting, HVAC control, and security systems, reflecting a growing trend towards smart building integrations and energy management solutions.
- Industrial IoT Devices: Comprises industrial sensors and automation controllers deploying Zigbee for factory automation, predictive maintenance, and asset management, with uptake supported by Industry 4.0 initiatives in the region.
- Consumer Electronics: Encompasses Zigbee-enabled wearable and entertainment devices, witnessing increased adoption driven by technological advancements and rising consumer preference for interconnected smart gadgets.
- Application
- Home Automation: Represents the largest application segment, where Zigbee is widely used in smart lighting, security, and climate control systems, driven by rising residential construction and renovation activities in Europe.
- Building Automation: Focuses on energy management and security systems within commercial and public infrastructures, supporting sustainability goals and regulatory standards for smart building practices.
- Industrial Automation: Involves asset tracking, process control, and predictive maintenance, where Zigbee devices enable increased operational efficiency in manufacturing plants and warehouses across Europe.
- Healthcare: Includes remote patient monitoring and smart medical devices, an emerging segment propelled by the aging population and technological innovation in European healthcare infrastructure.
- Geography
- Western Europe: Comprising countries like Germany, France, and the UK, this subregion displays the highest market penetration driven by mature technology adoption, strong manufacturing base, and proactive smart city initiatives.
- Nordic Countries: Characterized by high tech innovation, sustainability policies, and early adoption of IoT solutions, fostering growth in Zigbee-enabled devices for residential and commercial applications.
- Southern Europe: Includes Spain, Italy, and Portugal, where market growth is gradually increasing due to rising investments in smart infrastructure and consumer electronics connectivity.
- Eastern Europe: Features emerging markets with expanding industrial and residential sectors that are beginning to adopt Zigbee technologies primarily driven by cost-effective, scalable solutions and government incentives for digital transformation.
Competitive Intelligence
The Europe Zigbee Enabled Devices Market is characterized by a moderate level of competition, with dominant players holding significant market shares but facing increasing fragmentation from regional and niche entrants. Major corporations such as Samsung, Bosch, and Philips are leveraging strategic alliances, joint ventures, and partnerships to strengthen their distribution networks and enhance product offerings. Innovation plays a crucial role, with firms investing heavily in R&D to develop differentiated, energy-efficient, and interoperable Zigbee devices tailored to European smart home and industrial sectors. Acquisition activities are driven by the need to expand technological capabilities and market reach, exemplified by recent acquisitions of localized startups specializing in Zigbee protocol optimization. Companies are also adopting aggressive expansion strategies, establishing regional R&D centers and forging collaborations with technology developers to stay ahead of competitors. Differentiation is primarily achieved through product innovation, enhanced security protocols, and streamlined interoperability within broader IoT ecosystems, enabling firms to capture niche segments and maintain competitive advantage amid a dynamic market landscape.
Leading Company Profiles
The competitive landscape of the Europe Zigbee Enabled Devices Market comprises a broad spectrum of innovative and technologically advanced companies, each striving to enhance their market share through strategic initiatives, product innovation, and expansion activities.
- Silicon Labs
- NXP Semiconductors
- Texas Instruments
- Qualcomm Technologies
- STMicroelectronics
- MeshData
- Legrand
- Gemalto
- Bosch Sensortec
- ABB
Silicon Labs
Silicon Labs specializes in IoT connectivity solutions, offering Zigbee modules and development kits that enable seamless integration and scalable deployment for smart home and industrial applications. Their focus is on robust security features and power efficiency.
NXP Semiconductors
NXP provides a broad portfolio of Zigbee-enabled chips and modules, emphasizing secure, high-performance wireless connectivity for IoT devices. They prioritize interoperability and environmental sustainability through innovative product development.
Texas Instruments
Texas Instruments develops embedded system solutions and Zigbee transceivers that support extensive connectivity protocols. Their strategic focus lies in enhancing energy efficiency and facilitating smart grid and home automation projects.
Qualcomm Technologies
Qualcomm delivers advanced Zigbee modules integrated with their leading edge wireless technologies, targeting seamless IoT device connectivity, robust cybersecurity, and scalable infrastructure for commercial and industrial applications throughout Europe.
STMicroelectronics
STMicroelectronics offers integrated Zigbee solution components focusing on smart building automation, energy management, and home security, emphasizing low power consumption and high reliability in connected device ecosystems.
MeshData
MeshData specializes in mesh network solutions, providing Zigbee-enabled modules and software platforms that facilitate resilient, scalable, and secure IoT deployments across smart homes, factories, and energy grids.
Legrand
Legrand focuses on smart electrical infrastructure and Zigbee-enabled switches, sensors, and control panels, aiming to facilitate energy-efficient and intelligent building management systems via innovative design and sustainable practices.
Gemalto
Gemalto develops advanced security solutions integrated with Zigbee devices, strengthening the integrity of IoT ecosystems through encryption, authentication, and secure data management strategies tailored for the European market.
Bosch Sensortec
Bosch Sensortec provides sensor modules and IoT solutions aimed at enhancing automation, security, and contextual awareness in smart home and industrial applications, emphasizing reliability and user-centric functionalities.
ABB
ABB offers IoT-enabled automation devices with Zigbee connectivity optimized for industrial and infrastructure sectors, with a focus on sustainable energy and digital transformation within the European market.
Strategic Business Developments

- June 2023 – Silicon Labs – Launched new Zigbee 3.0 modules for smart home applications – Significantly enhances interoperability and energy efficiency in connected devices.
- August 2023 – NXP Semiconductors – Announced expansion of their Zigbee chip portfolio with advanced security features – Bolsters competitive advantage in secure IoT deployments.
- April 2023 – Texas Instruments – Initiated a strategic partnership with a European smart grid provider – Facilitates deployment of energy-efficient Zigbee-based solutions at a larger scale.
- September 2023 – Qualcomm Technologies – Unveiled a new scalable Zigbee module targeting industrial automation sectors – Accelerates deployment of connected industrial IoT infrastructure.
- May 2023 – Bosch Sensortec – Invested in R&D for next-generation Zigbee sensors with enhanced environmental monitoring – Supports their strategic push into sustainable automation solutions.
Frequently Asked Questions
What is the Europe Zigbee Enabled Devices Market?
The Europe Zigbee Enabled Devices Market encompasses a wide range of wireless communication devices using the Zigbee protocol, primarily for smart home and IoT applications, facilitating efficient device connectivity across households and commercial settings within the European region.
What is the current market size of Europe Zigbee Enabled Devices Market?
As of 2026, the market size of Europe Zigbee Enabled Devices is estimated at approximately USD 4.2 Billion, reflecting growing adoption across residential and commercial sectors, driven by increasing smart device integrations and IoT deployment in the region.
What factors are driving the Europe Zigbee Enabled Devices Market?
Key drivers include the rising demand for smart home automation, advances in IoT infrastructure, increased security concerns prompting reliance on reliable wireless protocols, and supportive governmental policies promoting smart technologies, all contributing to the expanding adoption of Zigbee-enabled devices.
Which region dominates the Europe Zigbee Enabled Devices Market?
Western Europe leads the market, mainly due to its higher adoption rate of smart technologies, developed infrastructure, and greater consumer spending capacity, with Germany, France, and the UK acting as primary growth hubs in the region.
Which segment is expected to grow the fastest?
The sensor and actuator segment is forecasted to exhibit the highest growth rate, driven by increased integration in smart home systems and industrial IoT applications, contributing significantly to overall market expansion.
Who are the leading companies operating in the Europe Zigbee Enabled Devices Market?
Major players include Silicon Labs, Texas Instruments,Nordic Semiconductor, and Qorvo. These companies focus on innovation, strategic partnerships, and expanding product portfolios to maintain competitive edge within the European market.
Analyst Perspective
The Europe Zigbee Enabled Devices Market is poised for sustained growth through 2034, driven by rising adoption of smart home and automation technologies across the region. The long-term outlook appears robust, with increasing emphasis on interoperability and energy efficiency fostering expansion opportunities. Commercially, manufacturers should focus on developing integrated, user-friendly solutions tailored to Europe's diverse regulatory landscape and consumer preferences. Technological evolution is likely to prioritize enhanced security protocols and low-power consumption features, thereby boosting device lifecycle and reliability. Investment priorities should include R&D to innovate scalable solutions compatible with emerging IoT ecosystems and smart city initiatives. Competitive intensity remains high, with established companies expanding their portfolios and new entrants leveraging niche segments. Regional growth potential varies, with Western Europe expected to lead due to early adoption and infrastructure development, while Eastern Europe presents additional opportunities linked to urbanization and industrial digitization. Strategic positioning will require balancing innovation with regional regulatory compliance and forging strong local alliances to maximize market penetration.
