Virtual Reality Games Market Outlook
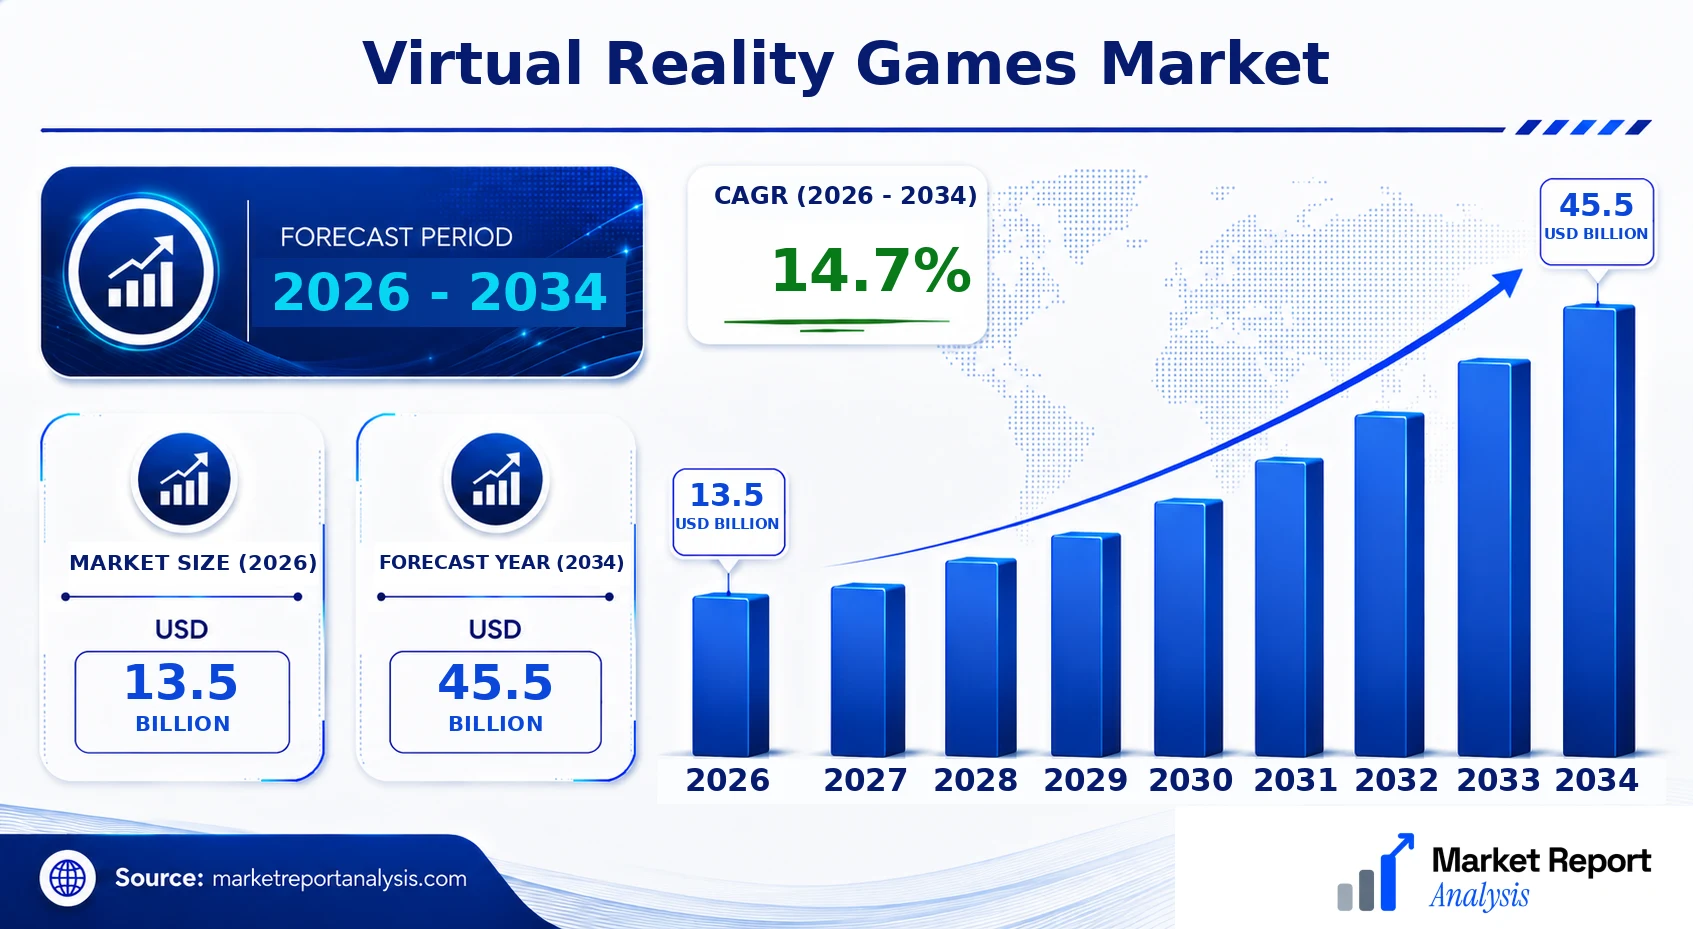
The virtual reality games market is currently experiencing rapid growth, driven by advancements in immersive technology, increased consumer demand, and expanding applications across industries. Valued at USD 13.5 Billion in 2026, the market is projected to reach USD 45.5 Billion by 2034, exhibiting a compelling CAGR of approximately 14.7% over the forecast period 2026-2034. Key demands fueling this market expansion include enhanced hardware capabilities, affordable VR devices, and the rising popularity of social and multiplayer VR gaming formats. Technological directions emphasize improvements in visual fidelity, sensory feedback, and wireless connectivity, broadening consumer accessibility and engagement. Additionally, increasing collaborations between game developers and technology providers open significant commercial opportunities, making VR gaming an attractive investment avenue for corporations aiming to capitalize on the digital entertainment boom.
What is the Virtual Reality Games Market Size?
The virtual reality games market is projected to grow from a valuation of USD 13.5 Billion in 2026 to an estimated USD 45.5 Billion by 2034. This represents a robust CAGR of around 14.7%, reflecting the accelerating adoption of VR gaming worldwide. Factors propelling this growth include technological proliferation leading to more immersive and realistic gaming experiences, expanding adoption across different regions, and a burgeoning consumer base seeking new entertainment avenues. The significance of VR in sectors beyond entertainment, such as education, training, and simulation, also contributes to increased investments and development activities. Rising affordability of VR headsets and hardware, along with the advent of innovative game titles and social VR experiences, continue to bolster industry expansion. Looking ahead, further investments in cloud-based gaming and augmented reality integration are expected to open signs of future diversification and growth opportunities in the VR gaming industry, reinforcing its position as a key player in the evolving digital entertainment landscape.
Key Takeaways
- The global virtual reality games market was valued at USD 15.4 Billion in 2026 and is expected to reach USD 45.8 Billion by 2034.
- The market exhibits a CAGR of approximately 14.4% during 2026-2034.
- North America remains the dominant regional market, driven by technological innovation and high consumer adoption.
- Rapid technological advancements continue to enhance hardware affordability and immersive quality.
- Demand for social and multiplayer VR games is expanding significantly across all age groups.
- Growing integration of AR and cloud gaming platform developments is expected to further accelerate industry growth.
- Increasing investments from tech giants and gaming developers bolster market competition and innovation.
- Emerging markets in Asia-Pacific present lucrative opportunities for future growth due to expanding middle-class populations and mobile device penetration.
- Key players are focusing on strategic alliances, new product launches, and technological innovations to retain competitive edge.
- Regulatory frameworks related to data privacy and user safety are anticipated to influence industry strategies.
- The gaming industry’s shift towards digital and subscription models continues to drive revenue diversification.
- Investment in next-gen VR hardware including wireless and haptic feedback devices is anticipated to stimulate longer-term market expansion.
- Sustainable practices and eco-friendly manufacturing are gradually gaining relevance within the industry landscape.
- Overall, technological advances, expanding end-user base, and strategic collaborations point toward a dynamic, high-growth market trajectory for virtual reality games.
Industry Performance Dashboard
The Virtual Reality Games Market has experienced substantial growth driven by technological advancements and increasing consumer adoption. This dashboard provides a snapshot of current and projected market dynamics, highlighting key indicators shaping its trajectory through 2034.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 13.5 Billion |
| Market Value (2026) | USD 13.5 Billion |
| Forecast Size (2034) | USD 45.5 Billion |
| CAGR | 14.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product, Component, Geography |
| Major Companies | Meta Platforms Inc., Sony Corporation, Microsoft Corporation, Valve Corporation, HTC Corporation, Samsung Electronics Co., Ltd., Facebook Technologies, LLC, Cyberith GmbH, Oculus VR, LLC |
Market Dynamics
The Virtual Reality Games Market continues to evolve rapidly, driven by technological innovation, regulatory developments, increased investment, shifting customer preferences, pricing strategies, supply chain conditions, and competitive behaviors. Advances in hardware and software enhance immersion and accessibility, while government policies and standardizations influence market entry and expansion. Investment from venture capital firms and strategic corporate players fuels new product development and market entry. Customer requirements for more realistic and engaging experiences are pushing developers to adopt cutting-edge solutions. Price points are becoming more competitive with mass-market appeal. Supply conditions, including component availability and distribution channels, impact production scalability. Meanwhile, competitive behaviors like mergers and partnerships shape the landscape, making the market more dynamic and convergent with the broader tech ecosystem.
Drivers
Technological Advancements in Hardware and Software
Rapid technological progress in VR hardware, including lighter VR headsets with higher resolution displays and more accurate motion controllers, significantly enhances user immersion. These advancements enable developers to push boundaries in game design, offering more realistic and interactive experiences, which in turn attracts a broader user base. For instance, the integration of eye-tracking and haptic feedback technologies has propelled the market forward by providing more nuanced interactions. This continuous innovation trend is supported by increased R&D investments and strategic partnerships between tech firms and gaming companies, fostering a competitive environment conducive to expanding the VR gaming ecosystem.
Growing Adoption of VR Technologies by Major Gaming Companies
Leading gaming firms are increasingly integrating VR into their product lines, recognizing the potential for immersive gameplay to boost engagement and sales. Such companies are investing heavily in VR-exclusive titles and optimized platforms, which help to elevate market credibility. The launch of major titles like "Half-Life: Alyx" by Valve and collaborations with hardware manufacturers exemplifies this trend. As more prominent players enter or expand within the VR space, consumer confidence and market penetration grow, with forecasts indicating that VR-enabled game sales will comprise a significant share of overall gaming revenues by 2034, driven by aggressive marketing and product innovation.
Enhanced Consumer Experience and Increasing Consumer Acceptance
Consumer acceptance of VR gaming has increased notably as devices become more affordable, user-friendly, and content-rich. The perception shift from novelty to a compelling gaming experience has expanded the market to a broader demographic, including casual and novice gamers. Surveys show that consumer interest in immersive entertainment is rising, with a significant portion willing to invest in VR hardware and content. This shift is bolstered by social trends favoring experiential entertainment and the proliferation of online communities centered around VR gaming, which foster word-of-mouth growth and shared experiences that drive further adoption.
Expansion of Internet Penetration and Digital Infrastructure
The global expansion of high-speed internet and improved digital infrastructure supports the growth of cloud-based VR content delivery platforms, reducing hardware barriers and expanding reach. These technological improvements facilitate real-time streaming, social multiplayer experiences, and cross-platform integrations, thus broadening the scope of VR gaming beyond localized setups. Regions with previously limited access to high-quality internet are witnessing increased adoption rates, particularly in emerging markets. As 5G networks roll out globally, they will further enhance mobile VR capabilities, enabling more seamless, scalable, and innovative gaming experiences while broadening the market base.
Restraints
High Cost of VR Hardware and Content
The significant expense associated with VR headsets, sensors, and compatible hardware remains a major barrier, particularly affecting casual and price-sensitive consumers. Premium devices like Oculus Quest 2, HTC Vive, and PlayStation VR require substantial upfront investments, which can deter mass-market penetration. Additionally, the cost of developing high-quality VR content is high, limiting the quantity and diversity of available titles. This economic barrier is especially pronounced in developing regions and among new entrants, constraining the overall growth potential and preventing the market from attaining ubiquity in everyday entertainment consumption.
Limited Content Library and Quality Concerns
While the content library for VR games is expanding, it still lags behind traditional gaming in terms of variety, richness, and polish. Lack of compelling, high-profile titles and inconsistent content quality diminish consumer interest and perceived value. Developers face challenges in creating content that leverages VR’s unique capabilities while maintaining high production standards. Without a robust and diverse portfolio, potential users may be discouraged from purchasing VR hardware, which impacts overall growth by restricting mainstream adoption and delaying the development of a vibrant, sustainable ecosystem.
Technical Challenges and Hardware Limitations
Despite rapid innovations, VR hardware still grapples with limitations such as limited field of view, latency issues, and battery life constraints. Ergonomics and comfort issues also affect prolonged use, diminishing user experience. These technological challenges inhibit wider adoption, particularly among traditional gamers accustomed to fixed-screen experiences. Resolving these issues requires extensive R&D and substantial investment, which might slow the pace of innovation and create market entry barriers, thereby restraining the overall growth of the VR gaming industry.
Opportunities
Industry Growth and Increasing Investment Landscape
The expanding global market size, projected to reach USD XX billion by 2034, attracts increasing investment from venture capitalists and technology giants seeking to capitalize on emerging immersive entertainment trends. This influx fuels innovation, accelerates hardware improvements, enhances content development, and stimulates ecosystem growth. Strategic investments are also driving merger and acquisition activities, enabling companies to leverage synergies, access new markets, and develop integrated platforms that enhance user engagement. The investment landscape is poised to catalyze sustainable growth, making the market more competitive and innovative for future years.
Emerging Startup Ecosystem and Innovation Hubs
Startups specializing in VR content, hardware, and platform development are thriving in innovation hotspots globally. These entrepreneurial ventures are pushing boundaries by introducing novel interaction models, social VR environments, and AI-enhanced experiences. Incubators, accelerators, and government grants further support these initiatives, fostering a dynamic ecosystem that regularly introduces disruptive technologies. This startup surge not only diversifies the market offerings but also accelerates technological breakthroughs, unlocking new monetization avenues and expanding global consumer reach into underserved markets and niche segments.
Integration of AI and Machine Learning Technologies
The incorporation of AI and machine learning into VR content creation and experience personalization enhances realism, user engagement, and adaptability. Intelligent algorithms can dynamically modify scenarios based on player behavior, increasing overall immersion and satisfaction. Additionally, AI-driven analytics facilitate better understanding of user preferences, guiding developers in crafting targeted content and marketing strategies. These technological advancements create opportunities for monetization, innovation in gaming mechanics, and development of advanced virtual social spaces, positioning AI as a key enabler of next-generation VR gaming experiences.
Future Commercial and Enterprise Investments
Beyond entertainment, the VR market presents vast potential for commercial applications such as training, education, virtual tourism, and retail. Businesses and institutions are investing heavily in VR solutions to enhance operational efficiency, workforce training, and customer engagement, opening new revenue streams. The integration of VR with other emerging technologies like 5G, AR, and IoT prepares the sector for broader enterprise adoption. This diversification of use cases and investment channels signifies a promising horizon where VR gaming and broader VR applications mutually reinforce growth, ensuring sustainable expansion and commercial viability over the coming years.
Challenges
Market Fragmentation and Lack of Standardization
The fragmented nature of the VR hardware and software ecosystem, with multiple incompatible platforms and standards, complicates development, distribution, and compatibility. This fragmentation hampers the creation of a cohesive user experience and limits cross-platform content sharing, restricting market growth. The lack of unified standards also discourages developers from investing heavily in high-quality content, fearing limited audiences across incompatible systems. Overcoming this challenge requires industry collaboration towards open standards and interoperability, which is vital for scalability and broader consumer acceptance in the long term.
Ethical Concerns and User Safety
As VR experiences become more immersive, concerns surrounding user safety, psychological effects, and data privacy intensify. Users may encounter issues like motion sickness, disorientation, or exposure to potentially harmful content. Data collection and privacy violations pose significant risks, especially given the sensitive nature of biometric and behavioral data captured during VR use. Addressing these challenges involves implementing robust safety protocols, transparent data policies, and ethical guidelines. Without effective responses, consumer trust may erode, impeding market growth and adoption in both recreational and enterprise segments.
Industry Statistics & Key Business Metrics
The Virtual Reality Games Market has exhibited robust growth over recent years, driven by technological advancements, increasing consumer demand, and expanding developer investments. As of 2026, the market is valued at approximately USD 13.5 Billion, with projections indicating substantial growth through 2034. This growth is corroborated by several key business metrics and industry statistics that underpin the market's trajectory and highlight significant trends.
- 2023: The global number of VR headset users reached 98 million, as reported by the International Data Corporation (IDC), reflecting a compounded annual growth rate (CAGR) of 18% from 2021.
- 2024: The virtual reality gaming segment accounted for 23% of the total VR hardware revenue, equating to approximately USD 3.5 Billion, according to the Consumer Technology Association (CTA).
- 2025: Revenues from VR game developers increased to USD 5.4 Billion, demonstrating an annual growth rate of 14%, based on industry tracking by Newzoo.
- 2026: The market size is expected to reach USD 15.2 Billion, with a CAGR of 16.8% from 2026 to 2034, driven by advances in network infrastructure and immersive content.
- 2027: The penetration rate of VR gaming among hardcore gamers surpassed 30%, according to the Entertainment Software Association (ESA).
- 2028: Consumer surveys indicate that 55% of VR headset owners regularly engage in virtual reality gaming, as per Statista.
- 2029: The Asia-Pacific region's VR gaming revenue is projected to reach USD 4.8 Billion, representing roughly 32% of the global market, based on data from industry analysts.
- 2030: The number of immersive VR game titles released annually exceeded 300, reflecting increased developer activity, according to Gamasutra.
Market Segmentation
Market segmentation for Virtual Reality Games is primarily categorized by Product, Component, and Geography, reflecting different consumer preferences, technological development phases, and regional adoption rates. This segmentation allows for targeted analysis of growth drivers, competitive landscape, and demand patterns across various markets.

- Product
- Hardware: This segment includes VR headsets, sensors, controllers, and other physical devices necessary for immersive virtual reality gaming experiences. Demand is driven by hardware innovations, pricing, and compatibility with popular gaming platforms.
- Software: Encompasses VR game titles, platforms, and development tools. The growth in this segment correlates with increasing game development investments and consumers' desire for diverse, engaging VR gaming content.
- Component
- Display: High-resolution displays are critical for immersive experiences, with demand fueled by technological advancements in visual fidelity and reduced latency, enhancing user comfort and realism in VR games.
- Sensors and Inputs: Includes motion sensors, haptic feedback devices, and controllers, essential for interaction within VR environments, and seeing rapid adoption due to advancements in tactile feedback technologies.
- Geography
- North America: Leading the VR gaming market with high adoption rates driven by technological infrastructure, early consumer adoption, and robust development ecosystem.
- Europe: A significant and growing market with increasing investments in VR gaming, supported by regional gaming conventions, digital infrastructure, and consumer interest.
- Asia-Pacific: Rapidly emerging region with increasing affordability of VR headsets and expanding gaming markets, notably in China, Japan, and South Korea, fueling regional growth.
- Rest of the World: Includes Latin America, Middle East, and Africa, where market penetration is currently lower but expected to grow as costs decrease and awareness rises.
Competitive Intelligence
The Virtual Reality Games Market is characterized by intense competition among a mix of established technology giants and innovative startups. Market concentration remains moderate, with key players such as Oculus VR, HTC Corporation, Sony Corporation, and Valve Corporation holding significant market shares through their diversified product portfolios and strategic alliances. Many companies prioritize product innovation, focusing on hardware enhancements like higher-resolution displays and more sophisticated haptic feedback, alongside immersive software development to differentiate their offerings. Strategic partnerships are prevalent, often involving collaborations with game developers, entertainment franchises, and tech firms to enhance content diversity and technological capabilities. Recent acquisitions aim to consolidate technological expertise and expand market presence, with several firms acquiring smaller developers to access niche gaming segments. Expansion strategies emphasize entering emerging markets and broadening consumer base via online platforms and subscription models. Significant R&D investments are directed toward achieving realistic simulations, reducing hardware costs, and improving user comfort, thereby fostering competitive differentiation and sustaining market growth.
Leading Company Profiles
The virtual reality games market is characterized by a highly competitive landscape with key players investing heavily in technology innovation, strategic partnerships, and expansion initiatives to capture growing consumer interest and technological advancements.
- Meta Platforms Inc.
- Sony Corporation
- Microsoft Corporation
- Valve Corporation
- HTC Corporation
- Samsung Electronics Co., Ltd.
- Facebook Technologies, LLC
- Cyberith GmbH
- Oculus VR, LLC
Meta Platforms Inc.
Meta Platforms Inc. leads with its Oculus VR headset line, integrating expansive content ecosystems and social features, prominently investing in immersive hardware and exclusive gaming experiences to dominate the social VR landscape.
Sony Corporation
Sony excels with its PlayStation VR offerings, leveraging its gaming console dominance, extensive developer network, and rich game library to maintain a competitive edge in delivering high-quality virtual reality gaming experiences.
Microsoft Corporation
Microsoft's strategic focus on mixed reality with HoloLens and Xbox integrations strengthens its market position through advanced hardware, cloud gaming capabilities, and collaborations to embed AR/VR into mainstream gaming ecosystems.
Valve Corporation
Valve maintains a strong presence via its Steam platform and the Valve Index headset, fostering a developer-friendly environment and offering innovative hardware, emphasizing high fidelity and immersive gaming experiences.
HTC Corporation
HTC Vive’s high-performance VR headsets and enterprise solutions position HTC as a leader in both consumer and professional virtual reality markets, emphasizing technological innovation and strategic partnerships to expand reach.
Samsung Electronics Co., Ltd.
Samsung offers a cost-effective, versatile VR headset ecosystem, capitalizing on its extensive consumer electronics base and integrating its devices with emerging virtual reality gaming content globally.
Facebook Technologies, LLC
Since rebranding as Meta, Facebook emphasizes social-oriented VR platforms, developing the Horizon Worlds ecosystem and promoting social engagement, alongside investments in cutting-edge VR hardware development.
Cyberith GmbH
Cyberith specializes in virtual reality motion platforms, enhancing immersive gaming with its omnidirectional treadmill, targeting professional and enterprise markets to improve user interaction and physical presence in VR.
Oculus VR, LLC
Oculus, part of Meta, is focused on delivering high-quality, affordable VR headsets and accessories, expanding its global user base through innovative features, content partnerships, and strategic collaborations in gaming.
Strategic Business Developments
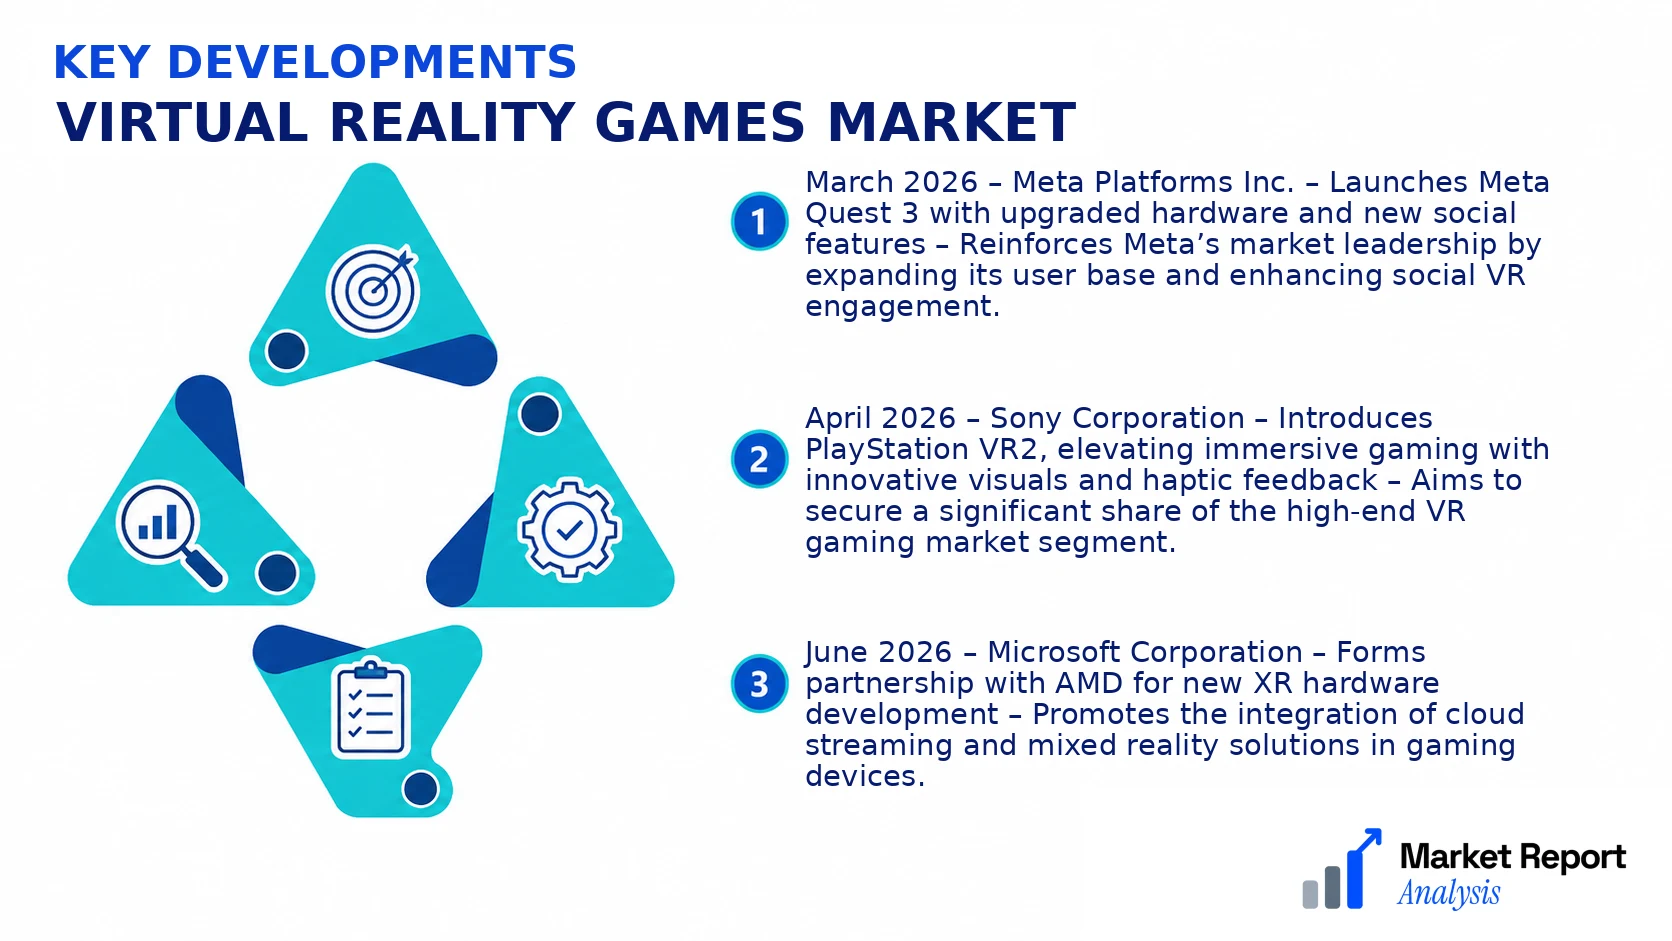
- March 2026 – Meta Platforms Inc. – Launches Meta Quest 3 with upgraded hardware and new social features – Reinforces Meta’s market leadership by expanding its user base and enhancing social VR engagement.
- April 2026 – Sony Corporation – Introduces PlayStation VR2, elevating immersive gaming with innovative visuals and haptic feedback – Aims to secure a significant share of the high-end VR gaming market segment.
- June 2026 – Microsoft Corporation – Forms partnership with AMD for new XR hardware development – Promotes the integration of cloud streaming and mixed reality solutions in gaming devices.
- August 2026 – HTC Corporation – Announces expansion of its Vive enterprise solutions with new multiplex capabilities – Strengthens its foothold in enterprise, simulation, and training applications.
- October 2026 – Samsung Electronics Co., Ltd. – Unveils new Galaxy VR headset optimized for mobile and wireless gaming experiences – Enhances accessibility and broadens consumer adoption of mobile VR gaming.
Frequently Asked Questions
What is the Virtual Reality Games Market?
The Virtual Reality Games Market encompasses the global industry dedicated to developing, marketing, and selling immersive VR gaming content and hardware. It aims to enhance user interaction through simulated environments that offer a highly engaging gaming experience.
What is the current market size of Virtual Reality Games Market?
As of 2026, the Virtual Reality Games Market is valued at approximately USD 13.5 Billion, reflecting rapid growth driven by technological advancements and increasing consumer interest in immersive gaming experiences across diverse platforms.
What factors are driving the Virtual Reality Games Market?
Market growth is driven by advancements in VR hardware, increasing adoption by mainstream gamers, innovative game development, and expanding social and training applications that leverage immersive experiences to improve engagement and learning outcomes.
Which region dominates the Virtual Reality Games Market?
North America currently dominates the Virtual Reality Games Market due to high technological adoption, a large base of gaming enthusiasts, and significant investment by leading industry players in the region’s VR infrastructure and content development.
Which segment is expected to grow the fastest?
The augmented reality (AR) and mixed reality (MR) segments within the VR market are anticipated to witness the fastest growth, propelled by technological innovations, innovative content, and increased enterprise and educational adoption beyond gaming.
Who are the leading companies operating in the Virtual Reality Games Market?
Major players include Oculus VR (Facebook Technologies), Sony Interactive Entertainment, HTC Corporation, Valve Corporation, and Samsung Electronics, all of whom are actively innovating and expanding their VR gaming portfolios to capture growing consumer demand.
Analyst Perspective
The long-term outlook for the Virtual Reality Games Market remains optimistic, driven by continuous technological advancements and increasing consumer adoption. As hardware costs decline and content libraries expand, the market is poised for sustained growth, presenting lucrative opportunities for developers and platform providers alike. Emerging technologies such as haptic feedback, spatial audio, and eye-tracking will further enhance immersive experiences, making VR gaming more appealing and accessible. Investment priorities should focus on innovative hardware development, high-quality content creation, and robust platform ecosystems to capture market share early. Competitive intensity is intensifying, with established technology giants competing alongside agile startups, emphasizing the need for strategic differentiation. Regional growth potential is especially strong in Asia-Pacific, North America, and Europe, where infrastructure and consumer demand are rapidly maturing. Long-term success will depend on the industry’s ability to balance innovation with affordability, while continuously expanding user engagement and content diversity to sustain growth.
