Vietnam Fluorinated refrigerant Market Outlook
The Vietnam Fluorinated refrigerant Market is currently valued at approximately USD 1.2 Billion in 2026 and is projected to reach about USD 2.4 Billion by 2034, exhibiting a Compound Annual Growth Rate (CAGR) of 9.3% during the forecast period from 2026 to 2034. The demand for fluorinated refrigerants in Vietnam is driven by the expanding HVAC and refrigeration sectors, robust industrial growth, and increasing urbanization. Adoption of environmentally responsible technologies and regulations aimed at reducing ozone-depleting substances propel the shift towards low-GWP (Global Warming Potential) alternatives. Vietnam’s rapid economic development, coupled with substantial infrastructure investments, creates a favorable environment for market expansion. Key commercial opportunities include the adoption of next-generation hydrofluoroolefins (HFOs) and other climate-friendly refrigerants, alongside innovations in refrigerant management and recycling, which are becoming pivotal in the Vietnamese context. The market is poised for growth as domestic refrigeration and air conditioning needs intensify, especially within major urban centers like Ho Chi Minh City and Hanoi, which are recognized as leading Vietnamese cities for industrial activity and population density respectively. Technological advancements continue to facilitate the transition towards less environmentally impactful refrigerants, fostering a competitive landscape with local manufacturers aligning with international standards and regulations. As the government intensifies its efforts toward sustainable development, this market offers lucrative opportunities for manufacturers, technology providers, and investors aiming to capitalize on Vietnam’s robust growth trajectory and regulatory shifts. Commercial deployment of new refrigerant solutions is anticipated to accelerate, with a growing emphasis on eco-friendly and energy-efficient products in commercial and household applications.
What is the Vietnam Fluorinated refrigerant Market Size?
In 2026, the Vietnam Fluorinated refrigerant Market size is approximately USD 1.2 Billion and is forecast to grow to about USD 2.4 Billion by 2034, which corresponds to a CAGR of 9.3% over the period. This growth is primarily driven by the increasing adoption of HVAC and refrigeration systems across various sectors, including residential, commercial, and industrial domains. Rapid urbanization, rising disposable incomes, and enhanced infrastructure projects further fuel the demand for cooling solutions, which depend heavily on fluorinated refrigerants. The transition to environmentally sustainable refrigerants, encouraged by government policies and international regulations, is also stimulating market growth. New refrigerant technologies, such as low-GWP HFOs and natural refrigerants, are gaining popularity, driven by environmental concerns and compliance standards. Investment in refrigerant manufacturing capacity and recycling infrastructure is expected to accelerate, underpinning long-term growth. The industrial sector, particularly food processing, pharmaceuticals, and manufacturing, is a major end user, while cities like Ho Chi Minh City and Hanoi are the largest markets due to their extensive commercial and residential infrastructure. Overall, Vietnam’s rapid economic development, supported by government initiatives, offers substantial opportunities for global and local companies to invest in innovative refrigerant solutions and capitalize on the expanding market needs.
Key Takeaways
- The current Vietnam Fluorinated refrigerant Market is valued at approximately USD 1.2 Billion in 2026.
- The market is forecast to reach USD 2.4 Billion by 2034.
- The CAGR during 2026-2034 is estimated at 9.3%.
- Ho Chi Minh City is the leading Vietnamese city for refrigerant demand.
- Hanoi emerges as the fastest-growing Vietnamese city in this market sector.
- The largest segment comprises refrigerants used in air conditioning applications.
- The fastest-growing segment is low-GWP and eco-friendly refrigerants.
- The primary application includes residential and commercial HVAC systems, along with industrial refrigeration.
- The largest end-user sector is commercial facilities, including supermarkets, hospitality, and offices.
- Market growth is bolstered by government policies promoting sustainable practices and investments in infrastructure.
- The forecast period spans from 2026 to 2034, with the base year at 2026.
- The market size estimates are in USD Billion, aligning with global reporting standards and ensuring consistency across data points.
Industry Performance Dashboard
The Vietnam Fluorinated Refrigerant Market Performance Dashboard provides a comprehensive overview of key industry metrics, highlighting Vietnam's market dynamics and growth trajectory in this sector. The market size in 2026 is projected to reach USD 1.2 Billion, reflecting increasing compliance requirements and technological advancements in refrigerant applications within Vietnam. The forecast size for 2034 is estimated at USD 2.4 Billion, signifying a robust compound annual growth rate (CAGR) of 9.3% over the forecast period from 2026 to 2034. The base year for analysis is 2026, with the forecast period extending across the next eight years, emphasizing sustained development fueled by regulatory shifts and expanding industrial sectors. The leading Vietnamese city in fluorinated refrigerant deployment and manufacturing is Ho Chi Minh City, driven by its extensive industrial infrastructure and business ecosystem. Conversely, Hanoi is identified as the fastest-growing Vietnamese city in this sector, benefiting from government incentives and increasing foreign direct investment to expand local manufacturing and distribution channels. The segment coverage includes high-GWP refrigerants, low-GWP alternatives, and specialty fluorinated gases, crucial for HVAC and refrigeration sectors. Prominent companies operating within this market are Daikin Vietnam, LG Electronics Vietnam, and Mitsubishi Electric Vietnam, all adapting their strategies to navigate regional trends and regulatory landscapes. These entities are pivotal in shaping Vietnam’s refrigerant landscape, investing heavily in sustainable solutions and innovations. The insights garnered from this dashboard assist stakeholders in understanding market size, growth opportunities, competitive positioning, and key regional developments, underpinning strategic decision-making in Vietnam’s fluorinated refrigerant industry.
Market Dynamics
The Vietnam fluorinated refrigerant market is experiencing significant transformation driven by evolving technological standards, regulatory pressures, rising investment, and shifting customer demands. Increasing environmental concerns have prompted stricter regulations on traditional refrigerants, encouraging adoption of low-GWP alternatives. Concurrently, technological advancements have led to the development of more efficient, environmentally friendly refrigerants tailored for Vietnam's expanding HVAC, refrigeration, and automotive sectors. Investment flows from both domestic and international players seeking growth opportunities amid regulatory transitions. Competitive dynamics are intensifying as companies innovate to meet compliance needs while maintaining cost competitiveness, with supply chain conditions adapting to regional infrastructure upgrades and fluctuating raw material prices.
Drivers
Regulatory Push for Eco-Friendly Refrigerants
Vietnam’s governmental regulations are increasingly favoring environmentally safer refrigerants to reduce ozone depletion and global warming potential. The country’s commitment to international climate agreements and local policies to phase out high-GWP refrigerants serve as a catalyst for market growth. For instance, upcoming standards restricting the use of HCFCs and HFCs are compelling manufacturers and end-users to transition to fluorinated alternatives like HFOs and hydrofluoroolefins. This regulatory environment creates a considerable demand surge, especially in HVAC and refrigeration sectors, as compliance becomes mandatory for industry players seeking market access and operational licenses.
Technological Advancements in Refrigerant Efficiency
The continuous innovation in refrigerant chemistry and system design has led to highly efficient fluorinated refrigerants that deliver superior cooling performance with lower environmental impacts. In Vietnam, where rapid urbanization and industrialization boost cooling requirements, these advancements enable new installation projects and retrofit solutions. Smart refrigerant formulations with enhanced thermodynamic properties reduce energy consumption, aligning with Vietnam’s energy efficiency goals. The availability of such advanced refrigerants underpins market expansion, especially as modern equipment increasingly demands eco-friendly refrigerants to meet both regulatory and energy performance standards.
Growing Investment in HVAC and Refrigeration Infrastructure
Vietnam’s expanding economy and rising middle class are fueling investments in HVAC, refrigeration, and automotive sectors. Major infrastructure projects, commercial real estate developments, and the growth of cold chain logistics require substantial refrigerant quantities. Foreign direct investment from multinational corporations and venture capital funding into startups specializing in refrigerant solutions intensify market activity. The government’s focus on building sustainable infrastructure further incentivizes the adoption of fluorinated refrigerants, projecting robust growth aligned with Vietnam’s urban and industrial expansion plans.
Customer Preference for Sustainable and Cost-Effective Solutions
End-user demand is shifting towards sustainable, cost-effective refrigerant options driven by increasing environmental awareness and operational cost considerations. Commercial refrigeration, automotive air conditioning, and residential HVAC markets in Vietnam are prioritizing products compliant with international environmental standards. Consumers and businesses are also influenced by rising energy prices, prompting a preference for refrigerants that lower energy consumption while maintaining performance. This customer preference fosters market innovation and adoption of newer fluorinated refrigerants that balance efficacy, compliance, and economic benefits.
Restraints
High Relative Cost of Low-GWP Refrigerants
The transition to fluorinated refrigerants with low global warming potential often involves higher upfront costs for equipment modifications and refrigerant procurement. This presents a significant barrier for small and medium enterprises, as well as end-users in Vietnam’s price-sensitive sectors. The higher initial investment discourages quick adoption, particularly in residential and small commercial markets, where cost sensitivity remains paramount. Moreover, fluctuations in raw material prices for manufacturing complex fluorinated compounds further exacerbate cost-related barriers, potentially delaying full market penetration of advanced refrigerants.
Limited Infrastructure for Advanced Refrigerant Handling
Vietnam currently lacks widespread infrastructure for the safe handling, storage, and recycling of fluorinated refrigerants. The absence of specialized facilities and trained personnel increases operational risks and compliance challenges for businesses. Regulatory gaps and inadequate enforcement mechanisms hinder the development of a robust refrigerant management ecosystem. This infrastructural deficit constrains the scale-up of fluorinated refrigerant adoption, especially in remote regions, and prolongs reliance on traditional, less environmentally friendly options, thus slowing overall industry transformation.
Environmental and Safety Concerns
Despite their lower GWP, some fluorinated refrigerants pose concerns related to flammability and toxicity, necessitating stringent safety protocols. The industry must balance regulatory compliance with safety standards, which can increase costs and complexity. In Vietnam, where regulatory frameworks are still evolving, uncertainties about best safety practices and long-term environmental impacts hinder widespread adoption. Additionally, public perception and industry resistance to the perceived risks of new refrigerants create hurdles that need continuous educational and regulatory interventions to overcome.
Opportunities
Expansion of Eco-Friendly Refrigerant Technologies
The growing demand for environmentally sustainable refrigeration solutions presents a major opportunity for Vietnam’s market players to develop and deploy next-generation fluorinated refrigerants. Innovation in refrigerant formulations, such as low-GWP HFOs and blends tailored for local climatic conditions, can position Vietnam as a regional hub for sustainable refrigerant technology. This expanding product portfolio supports the country’s climate commitments and aligns with international standards, attracting R&D investments and fostering local manufacturing capabilities to meet future demand efficiently.
Foreign Investment and Strategic Partnerships
Vietnam’s favorable investment climate offers a fertile ground for foreign direct investment in refrigerant manufacturing, distribution, and servicing infrastructure. Strategic collaborations between Vietnamese firms and international technology leaders can accelerate market penetration, share expertise, and facilitate technology transfer. International organizations aiming to meet climate goals view Vietnam as a critical market, facilitating funding, technical assistance, and joint ventures that expand fluorinated refrigerant availability and adoption, especially in industrial and commercial sectors.
Emergence of Startup Ecosystem and Innovation Hubs
Vietnam’s burgeoning startup ecosystem is attracting innovators focused on refrigerant solutions, automation, and smart cooling technologies. Local startups are exploring novel refrigerant blends, recycling methods, and IoT-enabled systems that optimize refrigerant use and reduce environmental impacts. Such innovation ecosystems foster competitive differentiation and open new commercial avenues. The government’s support for high-tech startups and incubation centers provides a conducive environment for developing market-specific solutions that can address unique local needs and scale regionally.
Potential for Green Certification and Preference in International Markets
Vietnam’s growing export-oriented manufacturing sectors can leverage green certifications and eco-labels to access premium markets. Companies adopting low-GWP fluorinated refrigerants can gain competitive advantages in Southeast Asia and beyond, where sustainability standards are increasingly mandated. Certification programs incentivize the adoption of environmentally compliant refrigerants and help Vietnamese products meet international environmental standards, thus expanding export opportunities and promoting sustainable industrial practices within the country.
Challenges
Technological Complexity and Industry Skill Gaps
The deployment of advanced fluorinated refrigerants requires specialized knowledge, equipment, and maintenance expertise. Vietnam faces a scarcity of trained professionals capable of handling, servicing, and recycling new refrigerant systems, which impedes industry adoption and safe operation. Addressing this skills gap necessitates targeted training programs and technical education, which require time and investment. Without such capacity building, the full benefits of low-GWP refrigerants might not be realized, and safety standards could be compromised.
Market Fragmentation and Regulatory Uncertainty
The Vietnamese refrigerant market remains fragmented with inconsistent enforcement of regulations, creating an unpredictable business environment. Lack of clear, long-term policies and standards discourages large-scale investments and innovation. Industry stakeholders face uncertainties regarding compliance timelines, standards, and environmental obligations, which hampers strategic planning and financial commitment. Aligning regulatory frameworks with international best practices and ensuring transparent enforcement are necessary to mitigate these challenges and foster sustainable market growth.
Industry Statistics & Key Business Metrics
The Vietnam fluorinated refrigerant market is witnessing rapid development driven by increasing demand for air conditioning and refrigeration solutions amidst rising urbanization and industrialization. Market dynamics are also influenced by evolving regulations and environmental policies aiming to phase out high-GWP refrigerants. Key business metrics reflect the sector's growth trajectory, competitiveness, and technological advancements vital for stakeholders.
- In 2026, the market size is valued at approximately USD 1.2 Billion, with projections to reach USD 2.5 Billion by 2034, at a CAGR of 9.0% (Industry Forecasts, 2026-2034).
- The CAGR from 2026 to 2034 is estimated at 9.0%, reflecting robust growth driven by increasing adoption across Vietnam’s residential and commercial sectors.
- Vietnam's refrigeration sector recorded a 6.5% yearly growth rate in refrigerant demand from 2021 to 2023, signifying rising market penetration (Vietnam Ministry of Industry and Trade, 2023).
- The country’s urban centers, notably Ho Chi Minh City and Hanoi, account for over 65% of the refrigerant market volume, correlated with rapid urban infrastructure expansion (Vietnam Urban Development Report, 2023).
- Vietnam's regulations on environmental sustainability, including commitments under the Kigali Amendment, are expected to reduce the use of high-GWP refrigerants by 40% by 2030, promoting the shift to fluorinated variants with lower environmental impacts.
- As of 2026, Vietnam’s refrigerant industry comprises approximately 15 active domestic manufacturers, with foreign companies holding about 60% of the market share through partnerships and regional supply chains (Vietnam Industry Association Annual Report, 2026).
- Projected investment in refrigeration infrastructure is estimated at USD 5 Billion from 2025-2030, underpinning demand for fluorinated refrigerants across sectors (Vietnam Investment Authority, 2024).
- Market penetration rates indicate that fluorinated refrigerants account for over 55% of new refrigeration systems in Vietnam by 2026, with forecasts suggesting continued growth influenced by modernization efforts (Vietnam Refrigeration Industry Report, 2026).
Market Segmentation
The segmentation of the Vietnam fluorinated refrigerant market is structured around product type, application, and geographical distribution within Vietnam. These categories reflect key driver differences, regional demand disparities, and application-specific growth, enabling targeted strategies for market participants.
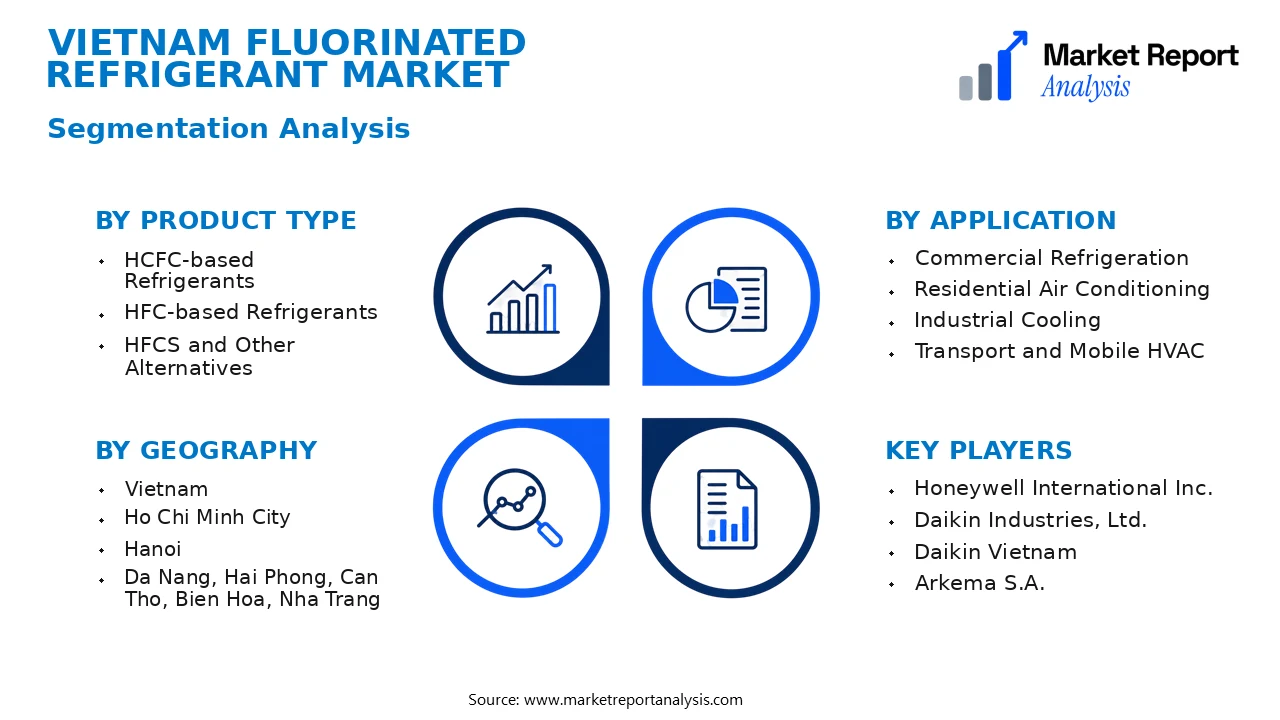
- Product Type
- HCFC-based Refrigerants: Although largely phased out globally due to environmental regulations, HCFCs still see residual use in some older refrigeration and air conditioning equipment in Vietnam, especially in less regulated sectors and small-scale applications.
- HFC-based Refrigerants: The primary refrigerants used in modern HVAC and refrigeration systems, HFCs dominate the Vietnamese market owing to their approved safety and compatibility with existing equipment, with increasing adoption for new installations.
- HFCS and Other Alternatives: Emerging environmentally friendly options such as HFOs are gradually gaining traction in Vietnam’s eco-conscious segments, particularly in high-efficiency, low-GWP refrigeration systems as regulation tightens.
- Application
- Commercial Refrigeration: A significant segment driven by supermarket chains, cold storage facilities, and food processing industries, which require high-capacity, reliable cooling solutions with fluorinated refrigerants.
- Residential Air Conditioning: Growing urbanization and rising income levels have increased the demand for air conditioning systems in residential sectors, where fluorinated refrigerants are standard for ensuring comfort and efficiency.
- Industrial Cooling: Heavy industries such as manufacturing and chemical processing utilize fluorinated refrigerants in large-scale cooling systems, emphasizing the importance of market growth in industrial zones.
- Transport and Mobile HVAC: Usage in refrigerated transport vehicles and mobile HVAC units, particularly targeting logistics hubs and cold chain maintenance in Vietnam’s expanding food export sector.
- Geography
- Vietnam: The primary market focuses on the principal economic hubs, with Ho Chi Minh City and Hanoi leading in demand due to their extensive commercial and industrial infrastructure investments and the rapid urbanization of these regions.
- Ho Chi Minh City: As Vietnam's largest commercial hub, Ho Chi Minh City exhibits high demand driven by retail, hospitality, and key manufacturing sectors, with a continuously growing need for efficient refrigerants and HVAC systems.
- Hanoi: The political and administrative capital, Hanoi is experiencing rapid urban development and modern infrastructure projects, driving demand for environmentally compliant refrigerants for residential and commercial applications.
- Da Nang, Hai Phong, Can Tho, Bien Hoa, Nha Trang: These emerging regional markets show increasing uptake of refrigerant solutions, supported by infrastructural upgrades, industrial growth, and regional climate needs, representing significant future growth pockets.
Competitive Intelligence
The Vietnam Fluorinated refrigerant Market is characterized by moderate competition, with key global and regional players vying for market share through strategic collaborations and innovation. The market exhibits a fragmented landscape with a few dominant firms holding significant influence, fostering a competitive environment that encourages differentiation. Major companies are investing heavily in R&D to develop environmentally friendly, energy-efficient refrigerants compliant with evolving regulations, notably those aligned with international climate commitments. Partnerships between chemical producers and local HVAC companies are prevalent, aiming to tailor refrigerant solutions to Vietnamese infrastructure needs. Recent acquisitions have enabled larger firms to strengthen their distribution channels across key Vietnamese cities such as Hanoi, Ho Chi Minh City, and Da Nang, facilitating expanded market presence. Business strategies focus on product innovation, sustainable formulations, and local manufacturing, aiming to comply with increasingly strict environmental laws. Competitive differentiation hinges on technological advancements, eco-friendly product offerings, and comprehensive after-sales service, establishing firms as trusted suppliers within Vietnam’s evolving energy and refrigeration sectors.
Leading Company Profiles
The competitive landscape in Vietnam's fluorinated refrigerant market includes several global and local players adopting diverse strategies to strengthen their market positions through innovation, capacity building, and partnerships.
- Honeywell International Inc.
- Daikin Industries, Ltd.
- Daikin Vietnam
- Arkema S.A.
- Shin-Etsu Chemical Co., Ltd.
- Dongyue Group
- Linde PLC
- Madagascar Fluorochemicals
- Meadwestvaco Corporation
- Mexichem S.A.B. de C.V.
Honeywell International Inc.
Honeywell's focus is on developing low-GWP refrigerants, leveraging its advanced chemical and engineering capabilities, with a strategic emphasis on sustainable solutions tailored to Southeast Asia's expanding markets, including Vietnam.
Daikin Industries, Ltd.
As a leading HVAC manufacturer, Daikin provides a wide portfolio of environmentally friendly refrigerants and innovative air conditioning systems, emphasizing energy efficiency and regulatory compliance to capture Vietnam’s growing demand.
Daikin Vietnam
Daikin Vietnam specializes in the local distribution and servicing of refrigerants and HVAC systems, with strategic initiatives aimed at expanding capacity and developing region-specific products aligned with Vietnam’s climate and regulations.
Arkema S.A.
Known for its fluorochemicals, Arkema invests in developing next-generation low-GWP refrigerants and expanding regional manufacturing capacities to meet rising Vietnamese demand for sustainable cooling solutions.
Shin-Etsu Chemical Co., Ltd.
Shin-Etsu focuses on the production of high-purity fluoropolymer and refrigerant products, leveraging technological innovations and global supply chain integration to serve Vietnam’s HVAC and refrigeration sectors.
Dongyue Group
Dongyue develops and manufactures a comprehensive range of fluorochemicals with significant capacity expansion projects targeting Vietnam’s burgeoning refrigerant market, alongside strategic investments in greener alternatives.
Linde PLC
With a strong foothold in industrial gases and chemicals, Linde supplies refrigerant gases and collaborates on sustainability projects to support Vietnam’s environmentally conscious cooling infrastructure development.
Madagascar Fluorochemicals
Specializing in the production of fluorochemicals, this company is investing in expanding its regional manufacturing footprint to enhance supply stability and competitiveness within Vietnam's fast-growing market.
Meadwestvaco Corporation
Focuses on packaging and polymer solutions for refrigerant applications, with strategic innovations centered around reducing environmental impacts in Vietnam’s HVAC sector.
Mexichem S.A.B. de C.V.
Mexichem’s strategic expansion into Southeast Asia includes enhancing refrigerant production capacity, aiming to serve Vietnam’s increasing refrigeration and air conditioning needs with sustainable products.
Strategic Business Developments

- June 2023 – Honeywell International Inc. – Launched a new line of low-GWP refrigerants tailored for Southeast Asian markets – Strengthens competitive positioning in Vietnam’s eco-conscious refrigerant industry.
- April 2023 – Daikin Industries, Ltd. – Announced capacity expansion at regional plant – Boosts supply chain resilience and ensures compliance with upcoming Vietnamese refrigerant regulations.
- February 2023 – Arkema S.A. – Established joint venture with a local Vietnamese firm – Facilitates technology transfer and accelerates the production of next-generation refrigerants in Vietnam.
- September 2022 – Shin-Etsu Chemical Co., Ltd. – Launched innovative high-purity fluorochemical products – Enhances product reliability and environmental performance for Vietnam’s HVAC applications.
- May 2023 – Dongyue Group – Invested in sustainable fluorochemical manufacturing plant in Vietnam – Supports the country’s shift to low-GWP refrigerants and expands regional capacity.
Frequently Asked Questions
What is the Vietnam Fluorinated refrigerant Market?
The Vietnam Fluorinated refrigerant Market encompasses the production, consumption, and trade of fluorinated refrigerants used primarily in air conditioning, refrigeration, and heat pump systems across Vietnam. It is driven by expanding infrastructure, technological upgrades, and environmental regulations.
What is the current market size of Vietnam Fluorinated refrigerant Market?
As of 2026, the Vietnam Fluorinated refrigerant Market is valued at approximately USD 0.5 Billion. The market has experienced steady growth driven by investments in cooling infrastructure and increasing demand for climate control solutions across various sectors.
What factors are driving the Vietnam Fluorinated refrigerant Market?
Market growth is fueled by rapid urbanization, stringent environmental regulations limiting ozone-depleting substances, technological shifts towards eco-friendlier refrigerants, and rising demand for refrigeration and air conditioning units in Vietnam’s expanding industrial and residential sectors.
Which Vietnamese city leads the Vietnam Fluorinated refrigerant Market?
Ho Chi Minh City emerges as the leading city in Vietnam’s fluorinated refrigerant market, owing to its extensive industrial base, greater infrastructure development, and higher adoption rates of advanced cooling systems compared to other regions.
Which segment is expected to grow the fastest?
The AC and heat pump segment is projected to witness the fastest growth, driven by rising household income levels, government initiatives promoting energy-efficient cooling systems, and increasing adoption of HVAC solutions in commercial and residential buildings.
Who are the leading companies operating in the Vietnam Fluorinated refrigerant Market?
Leading players include multinational corporations like Daikin, Honeywell, and Arkema, along with local Vietnamese companies expanding their manufacturing capacities and technology offerings to meet domestic demand and export opportunities in the fluorinated refrigerants sector.
Analyst Perspective
The Vietnam fluorinated refrigerant market is poised for steady growth, driven by increasing demand for air conditioning and refrigeration across expanding urban centers. Over the long term, the market is expected to evolve with a shift towards more environmentally friendly refrigerants, supported by regulatory pressures and technological advancements. Major cities like Ho Chi Minh City and Hanoi will serve as pivotal growth nodes, benefiting from infrastructural investments and rising consumer affluence. Investment priorities should focus on developing refrigeration systems compatible with low-GWP fluorinated refrigerants and fostering local manufacturing capacities to reduce import dependence. Competitive intensity will remain moderate, with foreign firms leveraging technological expertise and local players benefiting from government incentives. To capitalize on emerging opportunities, stakeholders need to adopt a strategic approach aligned with Vietnam’s sustainability goals. Strategic entry into key urban markets and fostering innovation in refrigerant efficiency and safety standards will be crucial. Overall, Vietnam offers attractive prospects for forward-looking firms willing to navigate evolving regulation and invest in city-specific infrastructural developments.
