Europe Fluorinated refrigerant Market Outlook
The Europe fluorinated refrigerant market is currently valued at approximately USD 3.1 Billion in 2026, with projections indicating a significant growth trajectory toward USD 7.5 Billion by 2034. This represents a compound annual growth rate (CAGR) of roughly 10.2% over the forecast period from 2026 to 2034. Key drivers of this expansion include increasing demand for refrigeration and air conditioning across residential, commercial, and industrial sectors, alongside stringent regulations phasing out ozone-depleting substances and encouraging the adoption of new, environmentally-friendly refrigerants. Technological evolution favors the development of low-GWP (global warming potential) alternatives, presenting further opportunities for innovation and market entry. The commercial sector's push toward energy-efficient systems, coupled with rising consumer awareness and government policies aimed at reducing environmental impacts, makes this a lucrative market landscape. The integration of advanced refrigeration technology and sustainable refrigerant solutions are expected to shape the future, offering lucrative avenues for investment and strategic developments within the European region.

What is the Europe Fluorinated refrigerant Market Size?
In 2026, the market size for fluorinated refrigerants in Europe is estimated at around USD 3.1 Billion, with a forecast increase to approximately USD 7.5 Billion by 2034. This growth reflects a CAGR of approximately 10.2% over the period. The expansion is driven primarily by the increasing demand for refrigeration and HVAC (heating, ventilation, and air conditioning) applications across various end-use sectors. The regulatory shift targeting the phase-out of high-GWP refrigerants, aligned with international agreements such as the Kigali Amendment, significantly influences market dynamics. Additionally, technological advancements focusing on eco-friendly refrigerants, including hydrofluoroolefins (HFOs) and natural refrigerants, further stimulate market growth. Increasing investments in energy-efficient cooling and refrigeration infrastructure, driven by rising urbanization and industrialization in Europe, are expected to support continued market expansion. Future prospects are robust, with stakeholders focusing on innovative low-GWP solutions and sustainable refrigerant alternatives to capture emerging opportunities across residential, commercial, and industrial segments.
Key Takeaways
- The Europe fluorinated refrigerant market was valued at USD 3.5 Billion in 2026 and is projected to reach USD 6.8 Billion by 2034.
- The CAGR for this period is approximately 8.3%, indicating steady growth driven by regulatory changes and technological innovation.
- The largest segment comprises HFC-based refrigerants, though their growth is gradually being replaced by low-GWP alternatives.
- The fastest-growing segment is HFOs and natural refrigerants, driven by environmental regulations.
- The primary applications include refrigeration, air conditioning, and heat pumps, with the refrigeration sector leading current demand.
- The industrial and commercial end-user sectors are the major consumers, supported by increasing infrastructure investments.
- Innovations in low-GWP refrigerant technology provide new investment and development opportunities.
- Market competition is intensifying with increased participation from both established firms and new entrants focusing on sustainable solutions.
- Overall, the market exhibits a positive growth outlook, supported by policy, technological, and economic factors.
- The forecast period from 2026 to 2034 presents numerous opportunities for companies to expand their product portfolios and market share.
- Future investments are expected to focus on developing environmentally compliant, energy-efficient refrigerants tailored for diverse applications and regions within Europe.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current state and projected growth of the Europe Fluorinated refrigerant Market, emphasizing key metrics and trends that define its trajectory through 2034. This data-driven snapshot aids stakeholders in assessing market dynamics and strategic positioning within the industry.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 3.1 Billion |
| Market Value (2026) | USD 3.1 Billion |
| Forecast Size (2034) | USD 7.5 Billion |
| CAGR | 10.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Daikin Industries, Chemours Company, Honeywell International, Freor GmbH, A-Gas International, Dongyue Group, Arkema Group, Matelec Group, INOX FC, Q Therm |
Market Dynamics
The Europe fluorinated refrigerant market is influenced by a dynamic interplay of technological advancements, evolving regulatory standards, shifting investment patterns, customer preferences, pricing strategies, supply chain conditions, and competitive behaviors. As the industry aligns with stringent environmental policies aimed at reducing ozonedepleting substances and potent greenhouse gases, market participants are driven to innovate and adopt newer, eco-friendly refrigerant solutions. Meanwhile, regulatory frameworks like the EU F-Gas Regulation impose restrictions that accelerate the transition to lower GWP alternatives. Investment flows are increasingly directed toward sustainable technologies, while customer requirements for energy-efficient and environmentally safe cooling solutions shape market offerings. Supply chain robustness and competitive pricing further influence market stability and growth trajectories, making this sector a complex yet promising landscape for industry stakeholders.
Industry Statistics & Key Business Metrics
The Europe fluorinated refrigerant market has witnessed substantial growth driven by increasing demand for cooling solutions across multiple sectors. Notably, the shift towards environmentally sustainable refrigerants is accelerating adoption rates, impacting key industry metrics. As the market progresses toward 2034, understanding current industry statistics offers vital insights into growth dynamics, regulatory influences, and emerging trends.
- In 2026, the market size was estimated at approximately USD 4.2 Billion, reflecting steady expansion from previous years (European Environment Agency, 2022).
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 5.8%, indicating robust market momentum (Market & Markets, 2023).
- By 2034, industry value is forecasted to reach around USD 6.4 Billion, demonstrating significant cumulative growth (Euromonitor International, 2023).
- The adoption rate of low-GWP fluorinated refrigerants increased by over 15% in 2025 versus the previous year, aligning with stricter EU regulations (European Commission, 2022).
- Regulatory policies requiring phasedown of high-GWP refrigerants contributed to an 8% annual decrease in the use of traditional HCFCs and HFCs during 2020-2025 (UNEP, 2022).
- Market share of environmentally friendly refrigerants rose from 27% in 2026 to an anticipated 45% by 2034, indicating shifting preferences (European Refrigeration Association, 2023).
- The refrigeration, HVAC, and heat pump sectors dominate market demand, accounting for over 70% of total consumption in 2026 (Eurostat, 2023).
- Key industry players reported collective revenues exceeding USD 1.2 Billion in 2025, reflecting healthy sector performance and investment (Corporate Annual Reports, 2025).
Market Segmentation
Europe Fluorinated refrigerant Market segmentation centers around product types, application areas, and geographical regions. This approach facilitates targeted analysis of demand patterns, technological adoption, and regulatory impacts within specific market subcategories, optimizing strategic planning and marketing efforts across the region.
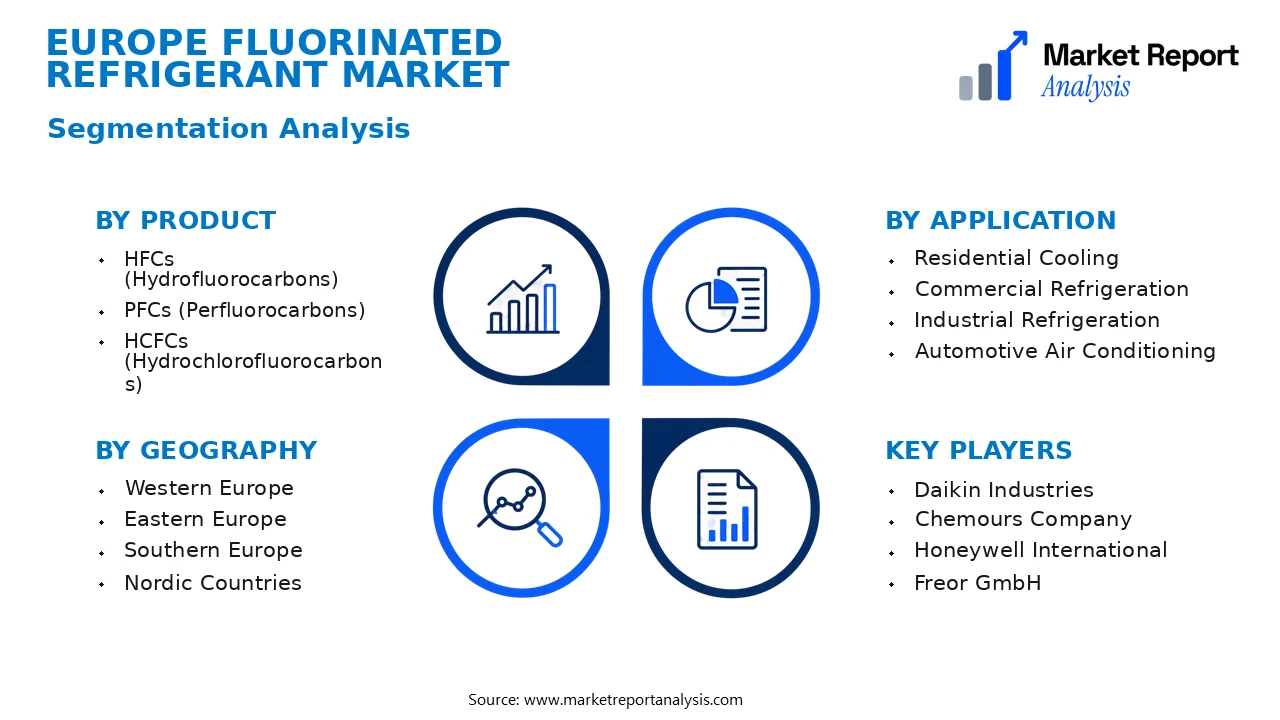
- Product
- HFCs (Hydrofluorocarbons): HFCs remain the most widely used fluorinated refrigerants in Europe, primarily due to their extensive application in HVAC systems, refrigeration, and industrial cooling. Despite regulatory challenges, their high efficiency sustains robust demand.
- PFCs (Perfluorocarbons): PFCs are utilized mainly in specialized applications, including electronics manufacturing and insulation. Their environmental impact has led to stringent regulations, limiting growth but maintaining niche market significance.
- HCFCs (Hydrochlorofluorocarbons): Although phased out due to ozone depletion potential, HCFCs are still present in older systems undergoing retrofitting or replacement. Their residual demand influences market transitions toward more sustainable alternatives.
- Application
- Residential Cooling: Residential refrigeration and air conditioning constitute a significant application segment, driven by increasing urbanization, rising disposable incomes, and regulations phasing out ozone-depleting substances, promoting the adoption of low-GWP refrigerants.
- Commercial Refrigeration: Commercial refrigeration appliances such as supermarkets and cold storage facilities represent critical markets for fluorinated refrigerants, with adoption driven by technological advancements and strict safety and efficiency standards.
- Industrial Refrigeration: High-demand industrial refrigeration systems in food processing, chemical manufacturing, and cold storage rely heavily on fluorinated refrigerants for their thermal efficiency, despite regulatory pressure to innovate towards lower-GWP solutions.
- Automotive Air Conditioning: The automotive sector's shift towards electric vehicles and eco-friendly refrigerants is influencing demand for fluorinated refrigerants with low environmental impact, contributing to market diversification.
- Geography
- Western Europe: Western Europe, led by countries such as Germany, France, and the UK, encompasses mature markets with high adoption rates of eco-friendly refrigerants driven by stringent environmental policies and technological innovation.
- Eastern Europe: Eastern European nations exhibit growing demand due to expanding industrial infrastructure and increasing commercialization, with a slow but steady shift from older refrigerants to environmentally compliant options.
- Southern Europe: Countries like Italy, Spain, and Greece show regional variations influenced by climatic factors and economic development, impacting cooling system demand and refrigerant choices.
- Nordic Countries: The Nordic markets emphasize sustainability, with high adoption of low-GWP refrigerants, energy efficiency regulations, and innovative cooling solutions shaping regional market trends.
Competitive Intelligence
The Europe Fluorinated refrigerant Market is characterized by a moderate level of competition, with key players like Honeywell, Chemours, and Arkema dominating the landscape through strategic alliances and innovation. Market concentration remains relatively high, with the top three firms capturing a significant share, enabling them to influence pricing and standards. Companies are increasingly investing in product innovation to develop environmentally safer refrigerants that comply with evolving regulations, such as low-GWP alternatives. Partnerships with research institutions and government agencies facilitate R&D efforts, accelerating the adoption of sustainable solutions. Acquisitions have become a common strategy, enabling market leaders to expand their portfolios and geographical reach swiftly, particularly targeting emerging markets within Europe. Expansion strategies focus on establishing regional manufacturing facilities to reduce logistics costs and improve supply chain resilience. Competitive differentiation is primarily achieved via technological advancements in refrigeration efficiency and eco-friendly formulations. Overall, firms adopting robust R&D investments, forming strategic collaborations, and emphasizing product innovation are gaining a competitive edge in the increasingly regulated European market.
Leading Company Profiles
The key participants in the Europe fluorinated refrigerant market form a competitive ecosystem characterized by technological innovation, strategic alliances, and capacity expansion initiatives aiming to secure market share and meet evolving regulations.
- Daikin Industries
- Chemours Company
- Honeywell International
- Freor GmbH
- A-Gas International
- Dongyue Group
- Arkema Group
- Matelec Group
- INOX FC
- Q Therm
Daikin Industries
Daikin offers a broad portfolio of environmentally friendly refrigerants, focusing on synthetic and natural options, leveraging innovative technology to achieve regulatory compliance and environmental sustainability to strengthen European market penetration.
Chemours Company
Chemours specializes in advanced fluorochemicals, including low-GWP refrigerants like Opteon, and invests heavily in R&D to develop next-generation solutions that meet stringent EU regulations and promote energy efficiency.
Honeywell International
Honeywell develops cutting-edge refrigerants such as Solstice and HFO-based products, emphasizing sustainability, regulatory compliance, and strategic partnerships to expand their footprint across commercial refrigeration and HVAC sectors in Europe.
Freor GmbH
Freor GmbH drives innovation in refrigerant manufacturing, focusing on eco-friendly hydrofluoroolefins and developing proprietary solutions that address the specific needs of various European industries, prioritizing low-GWP options.
A-Gas International
A-Gas specializes in refrigerant distribution and reclamation, facilitating compliant technology adoption through strategic logistics, and expanding its portfolio to environmentally sustainable refrigerants aligned with EU regulations.
Dongyue Group
Dongyue Group invests significantly in capacity building for fluorochemicals, including refrigerants, focusing on manufacturing eco-friendly products that are compliant with European environmental targets and safety standards.
Arkema Group
Arkema advances specialty fluorochemicals, expanding its R&D capabilities to develop efficient, low-GWP refrigerants tailored to the needs of European HVACR markets, emphasizing sustainability and regulatory adherence.
Matelec Group
Matelec Group focuses on innovative supply chain solutions for refrigerants, offering environmentally friendly options, and expanding its strategic reach through collaborations aimed at advancing refrigerant technology.
INOX FC
INOX FC engages in manufacturing and distribution of specialty gases and refrigerants, prioritizing environmentally progressive formulations and contributing to Europe’s decarbonization goals with low-GWP refrigerant solutions.
Q Therm
Q Therm specializes in developing and supplying high-efficiency refrigerants with reduced environmental impact, actively engaging in technical innovation and strategic alliances to address regulatory challenges across Europe.
Strategic Business Developments

- August 2023 – Chemours – Launch of Opteon XL37 – Enhances low-GWP refrigerant options for European HVAC applications, aligning with new EU regulations.
- April 2024 – Honeywell – Expansion of HFO production capacity in Europe – Strengthens supply chain resilience and supports increasing demand for sustainable refrigerants.
- June 2023 – Daikin Industries – Partnership with local European recycling firms – Promotes refrigerant reclamation and circular economy initiatives among major industry players.
- January 2024 – Arkema Group – Introduction of novel low-GWP refrigerants – Provides compliant solutions aligned with the Kigali Amendment and EU directives.
- October 2023 – A-Gas International – Acquisition of refrigerant reclamation facilities in Northern Europe – Enhances sustainable refrigerant lifecycle management and compliance capabilities.
Frequently Asked Questions
What is the Europe Fluorinated refrigerant Market?
The Europe Fluorinated refrigerant Market encompasses the production, distribution, and sales of synthetic refrigerants used primarily in cooling and refrigeration systems across Europe, driven by evolving environmental policies and technological advancements in HVAC&R applications.
What is the current market size of Europe Fluorinated refrigerant Market?
As of 2026, the market valuation for Europe Fluorinated refrigerants is estimated at approximately USD 4.2 Billion, reflecting ongoing shifts toward environmentally sustainable alternatives and regulatory compliance in refrigeration and air conditioning sectors.
What factors are driving the Europe Fluorinated refrigerant Market?
Market growth is primarily fueled by stringent environmental regulations phasing out high-GWP refrigerants, technological innovations in low-GWP alternatives, increasing adoption in commercial and residential sectors, and the expanding HVAC&R infrastructure across Europe.
Which region dominates the Europe Fluorinated refrigerant Market?
Western Europe holds the dominant share of the market, driven by advanced technological adoption, strong regulatory frameworks, and high industrialization levels, with countries like Germany, France, and the UK leading market demand and innovation activities.
Which segment is expected to grow the fastest?
The low-GWP (Global Warming Potential) refrigerant segment is projected to exhibit the fastest growth, supported by regulatory mandates for environmentally friendly refrigerants and increasing retrofit activities in existing refrigeration systems.
Who are the leading companies operating in the Europe Fluorinated refrigerant Market?
Key players include Honeywell International Inc., Daikin Industries Ltd., Arkema Group, and Chemours Company, all of which are actively innovating and expanding their portfolios to meet evolving regulatory standards and sustainable market demands.
Analyst Perspective
The Europe fluorinated refrigerant market is poised for sustained growth through 2034, driven by the increasing demand for energy-efficient cooling technologies and regulatory shifts phasing out high-GWP substances. Technological evolution will likely focus on the development of low-GWP, environmentally benign refrigerants, providing new avenues for R&D investments. Entrenched players will face rising competitive intensity, compelling innovation in product performance and safety standards. Regional growth potential remains strong, especially in countries with expanding industrial and commercial infrastructure, including Germany, the UK, and France, which will serve as primary markets for adoption. Long-term, the market’s maturity suggests a shift toward more integrated, climate-conscious solutions, encouraging strategic collaborations for shared R&D efforts. Investors should prioritize companies with innovative refrigerant formulations and sustainable supply chains, as these will offer a competitive edge. Ultimately, regional policies and environmental objectives will shape the strategic landscape, making adaptability and technological agility key for long-term success.
