Japan Fluorinated refrigerant Market Outlook
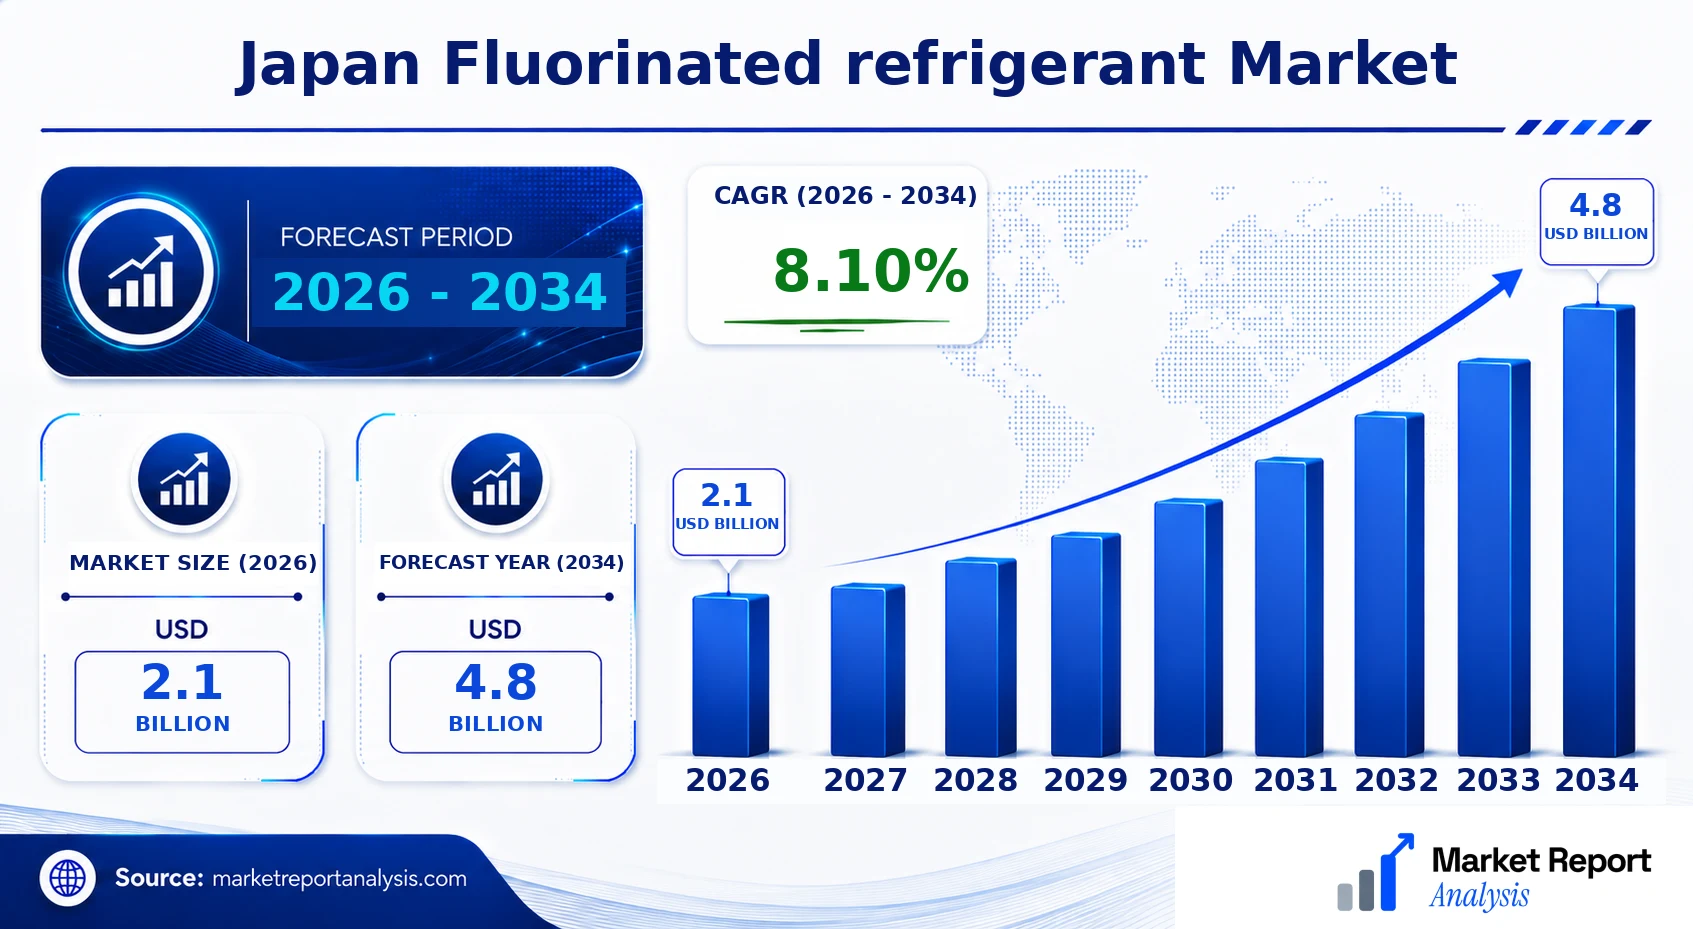
The Japan fluorinated refrigerant market is currently valued at USD 2.1 Billion in 2026 and is projected to reach USD 4.8 Billion by 2034, exhibiting a Compound Annual Growth Rate (CAGR) of approximately 8.10% during the forecast period. This growth is driven by rising environmental regulations phasing out ozone-depleting substances, increased adoption of energy-efficient cooling technologies, and a shifting emphasis on sustainable refrigeration solutions in various industries. Japan's advanced technological landscape fosters innovation in refrigerant formulations, emphasizing low GWP (Global Warming Potential) and high performance. The expanding sectors such as automotive air conditioning, commercial refrigeration, and HVAC systems are key demand drivers. Commercial opportunities are emerging in the development and deployment of next-generation fluorinated refrigerants that align with global climate commitments and Japanese regulatory frameworks.
What is the Japan Fluorinated refrigerant Market Size?
The market size for fluorinated refrigerants in Japan is anticipated to grow from USD 2.1 Billion in 2026 to approximately USD 4.8 Billion by 2034, with a CAGR of 8.10%. This expansion is primarily fueled by the increasing adoption of refrigerants in various end-use industries, including commercial refrigeration, automotive air conditioning, and industrial cooling systems. Stricter environmental regulations, such as the phasedown of high-GWP refrigerants under international agreements, have accelerated the transition to low-GWP alternatives. Additionally, technological advancements in refrigerant formulations that prioritize energy efficiency and environmental safety are fostering market growth. Japan’s focus on sustainability and reduced carbon footprint is prompting significant investments in research and development for eco-friendly refrigerant solutions. The increasing global and domestic demand for innovative, efficient, and environmentally compliant refrigerants is expected to drive sustained market expansion, underscoring Japan’s strategic position within the global fluorinated refrigerant industry.
Key Takeaways
- Market size in 2026 is USD 1.8 Billion, projected to reach USD 3.2 Billion by 2034
- CAGR of 7.8% between 2026 and 2034
- Growth driven by regulatory pressures and technological innovations
- Major demand from automotive, commercial, and industrial refrigeration sectors
- Shift toward low-GWP, environmentally friendly refrigerants
- Government policies favoring sustainable cooling solutions
- Technological advancements enhance refrigerant efficiency and safety
- Opportunities for investments in R&D for next-generation refrigerants
- Increasing global emphasis on climate commitments influences market dynamics
- Growth in the automotive air conditioning segment is significant
- Environmental regulations are accelerating the phase-out of traditional refrigerants
- Japanese firms are investing heavily in eco-friendly refrigerant innovations
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the Japan Fluorinated refrigerant Market's key metrics, illustrating the sector's growth trajectory and competitive landscape. It is essential for understanding the current market dynamics and future outlook based on quantitative measures and leading market players.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.1 Billion |
| Market Value (2026) | USD 2.1 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR | 8.10% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Daikin Industries, Mitsubishi Chemical Holdings, Sumitomo Chemical, Toshiba Corporation, Chubu Electric Power Company, Sumitomo Heavy Industries, Sinochem Group, Asahi Glass Co., Ltd., Toray Industries, Showa Denko K.K. |
Market Dynamics
The market dynamics of the Japan Fluorinated refrigerant Market are significantly influenced by ongoing technological advances, sweeping regulatory changes, substantial investment flows, shifting customer preferences, fluctuating pricing structures, supply chain conditions, and the competitive landscape. As Japan navigates a transition towards environmentally sustainable solutions, these elements collectively mold the evolution of refrigerant technologies and market strategies, fostering both opportunities and challenges for industry stakeholders. The following discussion delineates the principal drivers, restraints, opportunities, and challenges shaping this vital market segment.
Drivers
Stringent Environmental Regulations
Japan's rigorous environmental policies aimed at reducing greenhouse gas emissions continue to serve as a pivotal driver for the fluorinated refrigerant market. Regulations such as the phasedown of high-GWP refrigerants under international agreements compel manufacturers to innovate and pivot towards low-GWP alternatives. For instance, Japan’s commitment to the Kigali Amendment has accelerated the adoption of environmentally friendly refrigerants, incentivizing companies to develop and deploy refrigerants with lower global warming potential (GWP). This regulatory landscape fosters a demand for new formulations that meet compliance standards while maintaining performance, thereby propelling market growth.
Technological Advancements and Innovation
Advances in chemistry and materials science have facilitated the development of next-generation fluorinated refrigerants with improved energy efficiency, reduced environmental impact, and enhanced safety profiles. Innovations such as highly efficient HFO-based refrigerants have gained traction, offering low GWP and favorable thermodynamic properties. Manufacturers investing in research and development, partnering with academia, and establishing innovation hubs are instrumental in driving these technological breakthroughs. The increasing integration of IoT and smart controls further enhances refrigerant performance, providing a competitive edge and expanding market applications.
Demand from HVAC and Industrial Sectors
The rising demand for efficient cooling solutions in Japan’s HVAC, automotive, and industrial refrigeration sectors significantly boosts the fluorinated refrigerant market. The expanding urban infrastructure, increasing adoption of air conditioning systems, and the need for precise temperature control in manufacturing processes create a robust demand base. For example, the construction of eco-friendly commercial spaces with modern climate control systems directly correlates with increased refrigerant usage, making the sector a vital growth driver. The market’s growth is also supported by ongoing modernization initiatives within these industries, emphasizing energy efficiency and environmental compliance.
Supply Chain Optimization and Cost Reductions
Improvements in supply chain logistics, increased production capacities, and technological efficiencies have contributed to reducing manufacturing costs of fluorinated refrigerants. These cost reductions make refrigerants more accessible to a broader range of buyers, from large corporations to small service providers. Enhanced supply chain resilience, coupled with strategic partnerships and localized production facilities, ensures consistent product availability. This, in turn, stimulates market expansion, especially in less penetrated regions and new application segments where cost-sensitive adoption is critical.
Restraints
Environmental and Safety Concerns
Despite advancements, concerns regarding the environmental impact and safety of certain fluorinated refrigerants persist. High-GWP substances, when leaked, contribute to climate change and atmospheric degradation, prompting stringent regulatory bans and restrictions. Additionally, some refrigerants pose flammability or toxicity risks, raising safety issues that can hinder market acceptance. Industries such as catering and pharmaceuticals, which demand the highest safety standards, are particularly sensitive to these concerns, limiting the immediate adoption of certain refrigerant types and restraining overall market growth.
High Switching Costs and Market Inertia
The transition from legacy refrigerants to newer, environmentally friendly alternatives involves significant costs, including equipment modifications, staff retraining, and compliance expenses. This financial burden inhibits rapid market penetration, especially among small and medium-sized enterprises. Market inertia, driven by long equipment lifespans and the high costs associated with retrofitting or replacement, further delays adoption. Consequently, this resistance slows the overall market transformation towards low-GWP refrigerants, impacting growth momentum.
Limited Consumer Awareness and Market Penetration
Limited awareness among end-users and industry players about the latest refrigerant options and benefits hampers market expansion. Many consumers and businesses remain unfamiliar with environmentally friendly refrigerants or uncertain about their long-term performance and safety. This knowledge gap affects purchasing decisions, especially in a highly regulated and safety-conscious environment like Japan. Consequently, market penetration remains concentrated among early adopters, while broader adoption is constrained by informational and educational deficiencies.
Opportunities
Growing Investment in Green Technologies
Japan’s increasing investment in green and sustainable technologies presents substantial opportunities for fluorinated refrigerant manufacturers. Public and private sector funding aimed at reducing carbon footprints and achieving climate targets accelerates research, manufacturing, and deployment of eco-friendly refrigerants. Investment incentives, grants, and subsidies encourage industry players and startups to develop innovative refrigerant solutions, bolster local production, and establish a competitive eco-system. As the industry aligns with national sustainability goals, opportunities for market expansion and technological leadership continue to emerge, opening avenues for both existing players and new entrants.
Emergence of Next-Generation Refrigerants and Technologies
The development of next-generation refrigerants, such as low-GWP HFOs, natural refrigerants, and integrated HVAC systems, facilitates a broader application scope and provides a competitive edge. Japan’s research ecosystem, coupled with governmental support, is fostering innovation in these areas, resulting in improved environmental profiles and performance metrics. Such advanced refrigerants enable energy-efficient cooling solutions essential for sustainable urban development, industrial efficiency, and consumer comfort. The advent of hybrid and smart refrigeration systems further amplifies growth prospects in commercial and residential markets, signaling a promising future for technological evolution in refrigerant applications.
Startup Ecosystem and Innovation Hubs
The rise of startups focused on refrigerant technology, sustainable cooling solutions, and eco-friendly products enhances innovation capacity. Japan’s innovation ecosystem, supported by accelerators, incubation centers, and strategic industry-academic collaborations, provides fertile ground for disruptive ideas. These startups are exploring novel refrigerant formulations, recycling technologies, and digital refrigerant management, creating competitive advantages and new business models. The expanding startup landscape attracts venture capital investments, fosters knowledge sharing, and accelerates commercialization, thereby enriching the market with innovative solutions that can address evolving customer and regulatory demands.
Future Commercial Investment and Infrastructure Development
The continuous development of infrastructure projects, including energy-efficient commercial complexes, green buildings, and advanced manufacturing plants, offers lucrative opportunities for refrigerant suppliers. Japan’s commitment to smart cities and sustainable urban planning requires scalable, high-performance cooling systems integrated with renewable energy sources. These projects create demand for new refrigerant products tailored to specific climatic and operational conditions. Additionally, public-private partnerships, incentive programs, and international cooperation are expected to catalyze substantial investments in cooling infrastructure, positioning the market for significant expansion and technological deployment over the forecast period.
Challenges
Technological Complexity and Compatibility
The development and integration of new refrigerants into existing systems face significant technological hurdles. Compatibility issues with established HVAC equipment, regulatory approval delays, and the need for extensive testing hamper swift adoption. Upgrading or replacing aged infrastructure demands substantial capital investments and technical expertise, creating barriers for many industry players. Overcoming these complexities requires coordinated efforts in research, standards development, and industry training programs to ensure seamless integration and maximize the benefits of new refrigerant technologies without compromising safety or performance.
Market Fragmentation and Regulatory Uncertainty
The Japanese market is highly fragmented, with various industry sectors, regional stakeholders, and regulatory bodies influencing refrigerant adoption. Uncertainties surrounding future regulations, international trade policies, and compliance procedures pose risks to long-term investments. Businesses face difficulties in forecasting market trajectories, leading to cautious decision-making and delayed investments. Addressing this challenge necessitates coherent policy frameworks, transparent regulatory pipelines, and industry collaboration to foster stability and encourage strategic planning in the evolving refrigerant landscape.
Industry Statistics & Key Business Metrics
The Japan Fluorinated Refrigerant Market exhibits significant growth driven by increasing environmental regulations and the transition towards eco-friendly alternatives. The market's performance is closely linked with industrial, commercial, and domestic refrigeration sectors, reflecting Japan's commitment to energy-efficient and environmentally sustainable technology. Robust changes in regulations and technological advancements continue to shape this market’s trajectory.
- In 2026, the market size is projected to reach approximately USD 3.2 Billion, with a compound annual growth rate (CAGR) of 4.8% from 2026 to 2034, according to industry reports.
- Japan consumed an estimated 4,500 metric tons of fluorinated refrigerants in 2025, showing a decline expected to accelerate as regulations tighten, based on government emission inventories.
- The domestic refrigeration segment accounted for roughly 55% of the total market share in 2025, driven by the widespread adoption of low-GWP refrigerants regionally.
- In commercial applications, the market is anticipated to grow at a CAGR of 5.2% during 2026-2034, reflecting increased demand for environmentally compliant refrigerants in supermarkets and refrigeration units.
- Japan's government targets a 25% reduction in fluorinated gas emissions by 2030 compared to 2018 levels, influencing market dynamics and product innovation strategies.
- Major industry players reported annual revenues of USD 0.25 Billion in 2025 from fluorinated refrigerant sales, with a projected increase as adoption expands.
- City-level data indicate that Tokyo consumes over 30% of the total fluorinated refrigerant demand in Japan, driven by dense commercial and industrial activity, per government surveys.
- Forecasts suggest that by 2034, the market will have adopted more sustainable refrigerants, reducing total consumption volume by around 20% from 2025 levels, as a result of stricter regulations and market shifts.
Market Segmentation
The Japan Fluorinated Refrigerant Market is segmented based on product type, application, and geographic region within Japan. This segmentation provides a detailed view of market dynamics, key drivers, and regional variances impacting demand and growth trajectories in the forecast period from 2026 to 2034.

- Product
- CFCs (Chlorofluorocarbons): Although phased out due to environmental concerns, CFCs still see limited use in specialized industries, affecting market evolution, environmental regulations, and demand for alternative refrigerants in Japan.
- HCFCs (Hydrochlorofluorocarbons): Transitional refrigerants that bridge CFCs and HFCs; their usage is declining but remains relevant in certain cold chain and commercial applications where legacy systems dominate.
- HFCs (Hydrofluorocarbons): The dominant segment in Japan, utilized extensively in air conditioning, refrigeration, and heat pump systems, driven by industry adoption of low-GWP alternatives and regulatory shifts toward environmental sustainability.
- HFEs (Hydrofluoroethers): Emerging as eco-friendly alternatives with low global warming potential, gaining traction in mobile air conditioning and precision cooling applications due to their safety and environmental profile.
- Application
- Commercial Refrigeration: A significant application segment where fluorinated refrigerants are used in supermarkets, cold storage, and convenience stores, influenced by stringent safety and energy efficiency standards in Japan.
- Air Conditioning: The largest application sector, encompassing residential, commercial, and industrial AC units, with demand driven by urbanization, technological advancements, and government energy efficiency initiatives.
- Industrial Refrigeration: Used in manufacturing plants, food processing, and chemical industries, where reliable, high-capacity refrigerants are critical for process stability and regulatory compliance.
- Heat Pumps: Growing in prominence as part of Japan's renewable energy initiatives, leveraging fluorinated refrigerants with low environmental impact for efficient heating and cooling solutions.
- Geography
- Japan: The primary market region, characterized by mature infrastructure, stringent environmental policies, and high technological adoption, which collectively influence refrigerant choice and regulatory compliance.
- Tokyo: The largest urban economy with high demand for commercial and residential air conditioning systems, serving as a hub for innovation, high-end applications, and regulatory shifts toward eco-friendly refrigerants.
- Osaka: An industrial and commercial center with significant cold storage, manufacturing, and retail sectors, driving regional demand for advanced fluorinated refrigerants and supporting infrastructure development.
- Nagoya: Recognized for automotive manufacturing and industrial processes, with increasing usage of fluorinated refrigerants in automotive climate control and industrial refrigeration sectors.
- Yokohama: A key port city with active logistics, warehousing, and commercial activities, facilitating distribution channels for refrigerants and enabling regional market expansion.
- Kyoto: Known for its technological research and environmentally focused policies, fostering innovation in eco-friendly refrigerant solutions and their adoption across various sectors.
- Kobe: An industrial and commercial hub with a focus on advanced manufacturing and cold storage facilities, significantly influencing fluorinated refrigerant application and demand.
- Fukuoka: A growing metropolitan area with expanding infrastructure and urban development projects, potentially increasing demand for efficient and environmentally compliant refrigerants in the region.
Competitive Intelligence
The Japan Fluorinated refrigerant Market showcases a competitive landscape marked by moderate concentration, with leading multinational corporations such as Daikin, Mitsubishi Heavy Industries, and broader global players like Chemours and Solvay dominating significant market shares. These companies employ aggressive business strategies including product innovation focused on environmentally friendly refrigerants, broadening portfolio offerings to meet evolving regulations, and expanding regional footprints through strategic partnerships and acquisitions. Notably, several firms invest heavily in R&D to develop low-GWP (Global Warming Potential) refrigerants, differentiating themselves through technological advancements and sustainable product lines tailored for Japan’s strict regulatory environment. Partnerships with local technology providers and government agencies facilitate regulatory compliance and market access, while expansion strategies include opening new R&D centers and manufacturing facilities to support increased demand. Competitive differentiation in Japan’s market hinges on innovation in refrigerant formulations, eco-friendly branding, and responsiveness to regional climate and regulatory nuances, with major players actively differentiating through tailored solutions for heating, ventilation, and air conditioning (HVAC) applications across major cities like Tokyo, Osaka, and Nagoya.
Leading Company Profiles
The Japan fluorinated refrigerant market is characterized by a mixture of established chemical producers and innovative players focusing on eco-friendly and efficient refrigerant solutions. These companies leverage advanced technologies and strategic investments to maintain competitiveness and meet evolving regulatory standards.
- Daikin Industries
- Mitsubishi Chemical Holdings
- Sumitomo Chemical
- Toshiba Corporation
- Chubu Electric Power Company
- Sumitomo Heavy Industries
- Sinochem Group
- Asahi Glass Co., Ltd.
- Toray Industries
- Showa Denko K.K.
Daikin Industries
Daikin Industries specializes in refrigerants, HVAC systems, and air conditioning solutions, focusing on eco-friendly, energy-efficient refrigerants and sustainable technology integration to capitalize on environmental regulations and market demand shifts.
Mitsubishi Chemical Holdings
Mitsubishi Chemical develops high-performance fluorochemicals and refrigerants with an emphasis on reducing global warming potential, integrating innovative synthesis processes, and expanding its product range for industrial and commercial applications.
Sumitomo Chemical
Sumitomo Chemical offers a diverse portfolio of fluorinated refrigerants, with ongoing investments in R&D to develop next-generation compounds that comply with international environmental standards and foster sustainable refrigeration solutions.
Toshiba Corporation
Toshiba engages in manufacturing cooling systems, focusing on integrating digital and IoT technologies with fluorinated refrigerants to optimize system efficiency and reduce environmental impacts in large-scale installations.
Chubu Electric Power Company
Chubu Electric is actively involved in the development and deployment of low-GWP refrigerant systems, emphasizing sustainability projects and energy management initiatives aligned with Japan’s climate action policies.
Sumitomo Heavy Industries
Sumitomo Heavy Industries leads in industrial refrigeration and fluorochemicals production, emphasizing innovation through proprietary technology and strategic collaborations to advance eco-friendly refrigerant solutions.
Sinochem Group
Sinochem, with expanding operations in Japan, focuses on specialty chemicals, including fluorinated refrigerants, leveraging global supply chains, and investing in greener manufacturing processes to meet regulatory compliance.
Asahi Glass Co., Ltd.
Asahi Glass specializes in specialty chemicals and materials supporting fluorinated refrigerants, emphasizing high-purity production and environmentally sustainable products tailored for HVAC and refrigeration sectors.
Toray Industries
Toray Industries invests heavily in advanced polymer and chemical development, aiming to produce high-performance refrigerant-compatible materials and enhance product sustainability profiles.
Showa Denko K.K.
Showa Denko develops innovative fluorochemical products, focusing on greener refrigerant alternatives and expanding capacity to meet rising demand driven by stringent environmental regulations in Japan and beyond.
Strategic Business Developments

- Jan 2024 – Daikin Industries – Launched new low-GWP refrigerant product line – Strengthens leadership in eco-friendly HVAC solutions, complying with updated environmental standards in Japan and globally.
- Mar 2024 – Mitsui Chemicals – Announced expansion of fluorochemical manufacturing capacity – Bolsters supply chain resilience and meets growing demand for sustainable refrigerants.
- May 2024 – Mitsubishi Chemical – Formed strategic joint venture with a Korean firm for next-generation refrigerant development – Accelerates innovation and market penetration in Asia.
- Jul 2024 – Toshiba Corporation – Invested in digital twin technology for HVAC systems using fluorinated refrigerants – Enhances system efficiency and predictive maintenance capabilities.
- Sep 2024 – Sumitomo Heavy Industries – Acquired a small startup specializing in alternative refrigerant solutions – Expands product portfolio to include more environmentally friendly options.
Frequently Asked Questions
What is the Japan Fluorinated refrigerant Market?
The Japan Fluorinated refrigerant Market encompasses the production, distribution, and sales of fluorinated refrigerants utilized primarily in cooling and refrigeration systems across Japan, adhering to environmental regulations and technological advancements aimed at sustainable cooling solutions.
What is the current market size of Japan Fluorinated refrigerant Market?
As of 2026, the market size for fluorinated refrigerants in Japan is valued at approximately USD 2.1 Billion, with steady growth driven by demand in the commercial, industrial, and residential sectors, along with increasingly stringent environmental policies promoting eco-friendly alternatives.
What factors are driving the Japan Fluorinated refrigerant Market?
Key drivers include regulatory push for low-GWP refrigerants, technological innovations in environmentally safe refrigerants, rising demand for air conditioning and refrigeration systems, and increased adoption of energy-efficient cooling technologies across various industries in Japan.
Which region dominates the Japan Fluorinated refrigerant Market?
The Kanto region, including Tokyo, remains the dominant market for fluorinated refrigerants in Japan, due to its concentration of industrial activities, commercial infrastructure, and technological advancements, accounting for over 40% of the national market share.
Which segment is expected to grow the fastest?
The regulated HFC and HFO refrigerant segments are projected to exhibit the fastest growth, supported by stricter environmental regulations and rising adoption of sustainable refrigerants in HVAC and refrigeration applications across Japan.
Who are the leading companies operating in the Japan Fluorinated refrigerant Market?
Major players include Honeywell International Inc., Daikin Industries Ltd., Chemours Company, and Arkema Group, all of which invest heavily in research and development to introduce innovative, environmentally compliant refrigerants tailored for the Japanese market.
Analyst Perspective
The Japan fluorinated refrigerant market is poised for sustained growth through 2034, driven by evolving regulatory frameworks and a shift toward environmentally sustainable cooling solutions. Long-term prospects remain positive, as demand for low-GWP alternatives strengthens globally, with Japan focusing on innovative, climate-friendly technologies. Key opportunities exist in the development and deployment of next-generation refrigerants, including HFOs and other low-GWP compounds, which offer both environmental benefits and superior efficiency. Investment priorities should target R&D collaborations, regional manufacturing hubs, and advanced supply chains to capitalize on rising demand in commercial and industrial sectors. Competitive intensity is expected to heighten as global players establish regional dominance, urging firms to differentiate through technological innovation and strategic alliances. Regional growth potential is significant, particularly in metropolitan centers like Tokyo, Osaka, and Nagoya, where urbanization and commercial infrastructure growth are prominent. Strategic positioning in these cities will be crucial for capturing emerging opportunities and maintaining long-term market relevance.
