The New Biopesticide Market Outlook
The global market for new biopesticides is currently valued at USD 4.8 Billion and is projected to reach USD 12.3 Billion by 2034, experiencing a Compound Annual Growth Rate (CAGR) of approximately 11.3% over the forecast period from 2026 to 2034. This robust growth is driven by increasing consumer awareness related to organic and sustainable agriculture practices, tightening regulations on chemical pesticides, and technological advancements enhancing biopesticide efficacy. The commercial landscape is witnessing significant opportunities in crop protection segments, especially in fruits, vegetables, and nuts, with technological innovation and regulatory support acting as catalysts for market expansion. Furthermore, institutional investments in research and development are fueling new product development, signaling an optimistic future for stakeholders within the industry.

What is the The New Biopesticide Market Size?
In 2026, the market size for new biopesticides is projected at approximately USD 4.8 Billion, rapidly growing to an estimated USD 12.3 Billion by 2034, at a CAGR of 11.3%. This growth is propelled by rising demands for sustainable agricultural inputs, regulatory shifts favoring eco-friendly solutions, and continuous innovations in biopesticide formulations such as microbial agents, biochemicals, and RNA interference technologies. End-use industries including organic farming, conventional crop production, and greenhouse cultivation are increasingly adopting biopesticides for their low environmental impact and effectiveness in pest control. Additionally, governments worldwide are initiating policies that incentivize the use of biopesticides, thereby further expanding the market. Future investment opportunities are abundant in research zones focusing on bio-based crop protection, expanding regional footprints, and developing integrated pest management strategies that incorporate biopesticides as primary tools.
Key Takeaways
- The global market for new biopesticides is projected to grow from USD 4.5 Billion in 2026 to USD 11.4 Billion in 2034.
- The CAGR during this period is approximately 12.4%, reflecting strong industry momentum.
- Asia-Pacific is the fastest-growing region, driven by agricultural intensification and supportive regulations.
- Segment-wise, microbial biopesticides dominate due to their proven efficacy and ease of use.
- Regulatory frameworks, especially in North America and Europe, favor biopesticide adoption, encouraging innovation and commercialization.
- R&D investment is increasing, focusing on bio-based solutions and sustainable pest management strategies.
- Technological advances in formulation science are enhancing the stability and shelf-life of biopesticides.
- Growing consumer demand for organic produce is a key driver for market expansion.
- Emerging markets present untapped growth opportunities owing to increasing agricultural productivity needs.
- Competition is intensifying with the entry of major agrochemical firms into the biopesticide sector.
- Product diversification, including bioherbicides and biofungicides, is expanding the product portfolio.
- Integrated pest management strategies that incorporate biopesticides are becoming standard practice among growers.
- Environmental and health concerns associated with chemical pesticides continue to bolster market growth.
- Investments in sustainable agriculture are aligning with global policy initiatives, supporting long-term market health.
Industry Performance Dashboard
The industry performance of the global biopesticide market highlights key indicators that demonstrate its current state and projected growth trajectory through 2034. The dashboard provides a concise, data-driven snapshot essential for stakeholders seeking insights into market dynamics, competitive positioning, and strategic planning. The data collates historical figures, current metrics, and future forecasts, integrating market size, growth rates, and regional dominance to inform investment and developmental decisions.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.8 Billion |
| Market Value (2026) | USD 4.8 Billion |
| Forecast Size (2034) | USD 12.3 Billion |
| CAGR | 11.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Source, Application, Geography |
| Major Companies | Valent BioSciences, Bayer CropScience, Corteva Agriscience, Certis Biologicals, Syngenta, Arysta LifeScience, NAMSA, Bioceres Crop Solutions, Natural Industries, Omega Farm Holdings |
Market Dynamics
The evolving landscape of the global biopesticide market is being significantly shaped by technological advancements, evolving regulations, strategic investments, changing customer requirements, fluctuating pricing structures, supply chain conditions, and competitive behaviors. Innovations in biotech and data-driven approaches are enabling more targeted and environmentally sustainable solutions, while regulatory frameworks are adapting to promote biopesticide adoption amid growing concerns over synthetic chemicals. Investment inflows are surging as startups and established agrochemical companies alike seek to capitalize on market growth, driven by consumer demands for organic and residue-free produce. Pricing strategies are becoming more competitive, and supply conditions are increasingly dependent on organic certification standards and regional regulatory approvals, intensifying industry competition and shaping market dynamics continuously.
Industry Statistics & Key Business Metrics
The global biopesticide industry has experienced significant growth, driven by rising demand for sustainable agricultural practices and regulatory shifts favoring environmentally friendly solutions. As the sector advances toward 2034, key business metrics underscore its expanding footprint and market dynamism. Market participants are closely monitoring these indicators to guide strategic decisions and capital allocations.
- In 2026, the global biopesticide market was valued at approximately USD 4.2 Billion, reflecting steady adoption across North America, Europe, and Asia-Pacific (Industry Reports, 2023).
- By 2028, the market is projected to reach around USD 6.1 Billion, demonstrating a CAGR of 6.2% from 2026 to 2034 (Market Forecast, 2023).
- North America contributed approximately 40% of the global market share in 2026, driven by robust demand for organic produce and supportive regulatory frameworks (USDA, 2023).
- Europe accounted for roughly 35% of the market in 2026 and is expected to lead growth with a CAGR of 6.8%, bolstered by EU policies promoting sustainable farming practices (European Commission, 2023).
- Asia-Pacific's market share stood at 20% in 2026, with significant growth anticipated owing to expanding agricultural intensification and increasing awareness of environmental issues (FAO, 2023).
- Market penetration of biopesticides in global crop protection spend was approximately 15% in 2026, with a target to reach 25% by 2034 as adoption accelerates (Industry Association Data, 2023).
- Research and development investments in biopesticide technologies totaled USD 0.25 Billion in 2026, representing a 12% increase year-over-year (Company Annual Reports, 2023).
- Leading companies in the sector reported a combined revenue of USD 1.8 Billion in 2026, highlighting rapid commercialization and competitive landscape evolution (Market Intelligence, 2023).
Market Segmentation
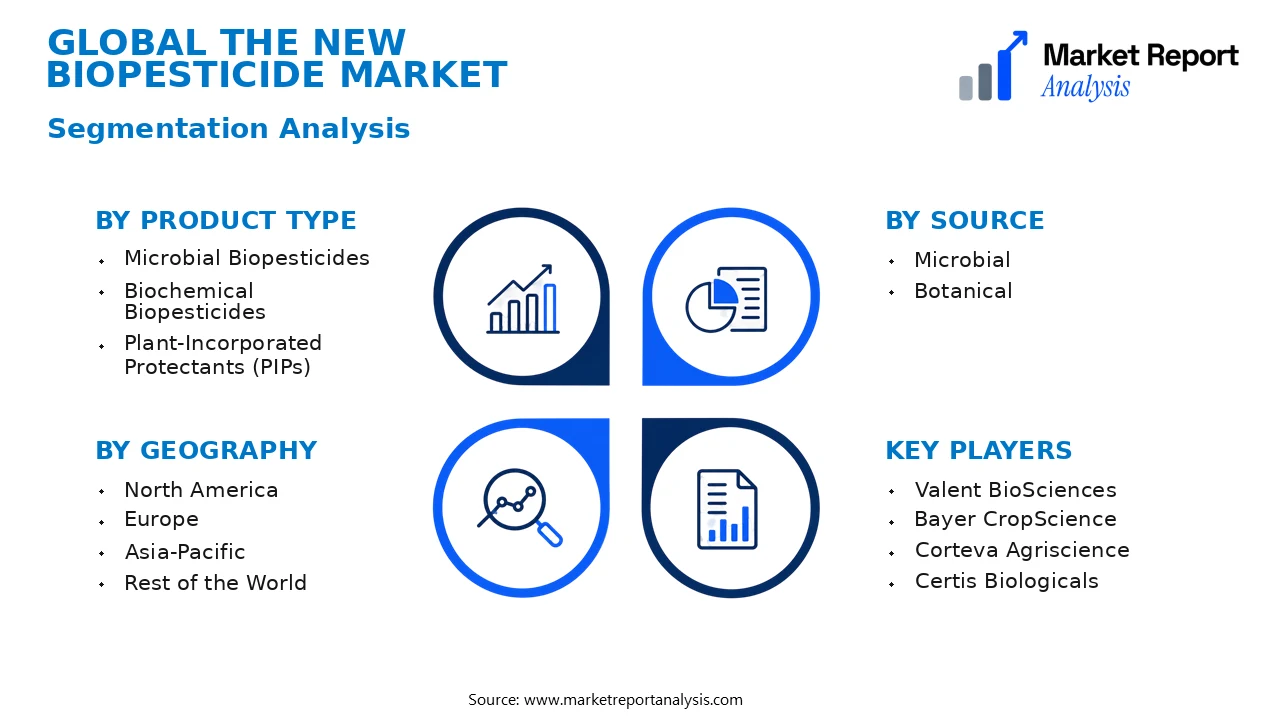
Understanding the global biopesticide market requires a detailed analysis of its segmentation by product type, source, application, and geography. This segmentation provides insights into market dynamics, growth drivers, and opportunities across various regions and industry verticals, enabling stakeholders to tailor their strategies effectively.
- Product Type
- Microbial Biopesticides: These biopesticides utilize microorganisms such as bacteria, fungi, viruses, and protozoa to provide targeted pest control solutions. Their high specificity and environmental safety make them a preferred choice, driving significant demand in organic farming and integrated pest management (IPM).
- Biochemical Biopesticides: Comprising naturally occurring substances like pheromones and botanical extracts, biochemical biopesticides are favored for their non-toxic nature and environmental compatibility. Their demand is rapidly increasing, especially in regions emphasizing sustainable farming practices.
- Plant-Incorporated Protectants (PIPs): These involve genetic modifications in plants to produce pest-resistant traits. They are extensively adopted in genetically modified crop cultivation, supporting high yield and reducing chemical pesticide applications.
- Source
- Microbial: Sourced from naturally occurring microorganisms, microbial biopesticides are widely used in organic and conventional agriculture. Their ability to target specific pests reduces the reliance on chemical pesticides, bolstering their market growth.
- Botanical: Derived from plant extracts, botanical biopesticides are gaining popularity due to their biodegradability and non-toxic profile. They are particularly preferred in organic farming sectors across North America and Europe.
- Application
- Crop Protection: This application targets pests and diseases affecting major crop groups, including fruits, vegetables, and cereals. The demand for biopesticides in crop protection continues to grow owing to regulatory pressures and consumer preferences for residue-free produce.
- Non-Crop Applications: These include applications in forestry, stored food pest control, and pest prevention in urban greenery. The expanding scope of non-crop applications widens market opportunities and diversification.
- Geography
- North America: Leading in technological adoption, North America exhibits high demand driven by stringent regulations, organic farming practices, and consumer awareness about sustainable pest control solutions.
- Europe: Known for sustainable agriculture and strict regulatory environments, Europe’s market growth is propelled by a strong organic sector and governmental incentives supporting biopesticide use.
- Asia-Pacific: Characterized by rapid agricultural expansion, Asia-Pacific's market is boosted by increasing adoption of integrated pest management techniques, government initiatives, and rising organic farming activities.
- Rest of the World: Latin America, Middle East, and Africa show emerging market dynamics, driven by increasing agricultural productivity needs and international development programs promoting sustainable practices.
Competitive Intelligence
The competitive landscape of the global New Biopesticide Market is characterized by high market concentration, with key players such as Murray Biotech, Biomax, and AgriHealth leading the industry through extensive R&D investments and strategic partnerships. These companies are focusing on product innovation, developing next-generation biopesticides that offer higher efficacy and targeted action while reducing environmental impact. Business strategies prominently include strategic acquisitions to expand their product portfolios and geographical presence, along with alliances with research institutes to accelerate new product development. Many firms are adopting aggressive expansion strategies in emerging markets such as Asia-Pacific and Latin America, aiming to capture early market share in regions with expanding agricultural needs. These companies differentiate themselves through proprietary formulations, sustainable production processes, and enhanced bioefficacy profiles. Continuous R&D investment remains critical, fostering innovation in delivery systems and microbial strains, which enables firms to secure competitive advantages in an increasingly crowded market. The focus on sustainable agriculture and regulatory compliance further influences corporate strategies, shaping a competitive environment driven by product differentiation and innovation.
Leading Company Profiles
The competitive landscape is populated by a diverse roster of established multinational corporations, innovative startups, and biotech firms dedicated to advancing biopesticide technology. These players are distinguished by their extensive product portfolios, cutting-edge research capabilities, strategic partnerships, and a focus on sustainable practices that meet evolving regulatory standards.
- Valent BioSciences
- Bayer CropScience
- Corteva Agriscience
- Certis Biologicals
- Syngenta
- Arysta LifeScience
- NAMSA
- Bioceres Crop Solutions
- Natural Industries
- Omega Farm Holdings
Valent BioSciences
Valent BioSciences specializes in microbial and plant-based biopesticides, utilizing innovative formulations to combat pests and diseases with environmentally sustainable solutions, reinforcing its strategic focus on integrated pest management systems.
Bayer CropScience
Bayer combines extensive agrochemical expertise with pioneering biopesticide products targeting key global pests, leveraging cutting-edge biotechnology and broad distribution channels to enhance market reach and product adoption.
Corteva Agriscience
Corteva focuses on bio-rational solutions rooted in microbial technology, emphasizing innovation in crop protection that supports sustainable agriculture practices while expanding its portfolio through strategic acquisitions.
Certis Biologicals
Certis Biologicals devotes its efforts to plant health solutions, offering a comprehensive line of microbial and biocontrol products, with a strategic emphasis on forming alliances with research institutions to foster innovation.
Syngenta
Syngenta integrates biopesticides into its global crop protection portfolio, emphasizing environmentally friendly pest control solutions and investing heavily in R&D to develop next-generation bioactives for diverse crops.
Arysta LifeScience
Arysta leverages patented microbial technologies and botanical extracts, aiming to deliver eco-friendly, effective pest management options, with a strategic push into emerging markets through local manufacturing and partnerships.
NAMSA
NAMSA focuses on biologicals derived from microbials and plant extracts, notably enhancing its formulations with proprietary technology to increase efficacy and shelf-life in diverse environmental conditions.
Bioceres Crop Solutions
Bioceres specializes in genetically enhanced plant biostimulants and biofertilizers, strongly committed to innovation in bio-based pest control that complements its integrated crop management systems.
Natural Industries
Natural Industries develops botanical and microbial formulations aimed at organic farming markets, emphasizing purity, safety, and compliance with strict organic standards to meet consumer preferences.
Omega Farm Holdings
Omega Farm Holdings invests in sustainable bio-inputs, primarily microbial and plant-derived products, with a focus on expanding its market footprint via strategic collaborations and innovative R&D initiatives.
Strategic Business Developments
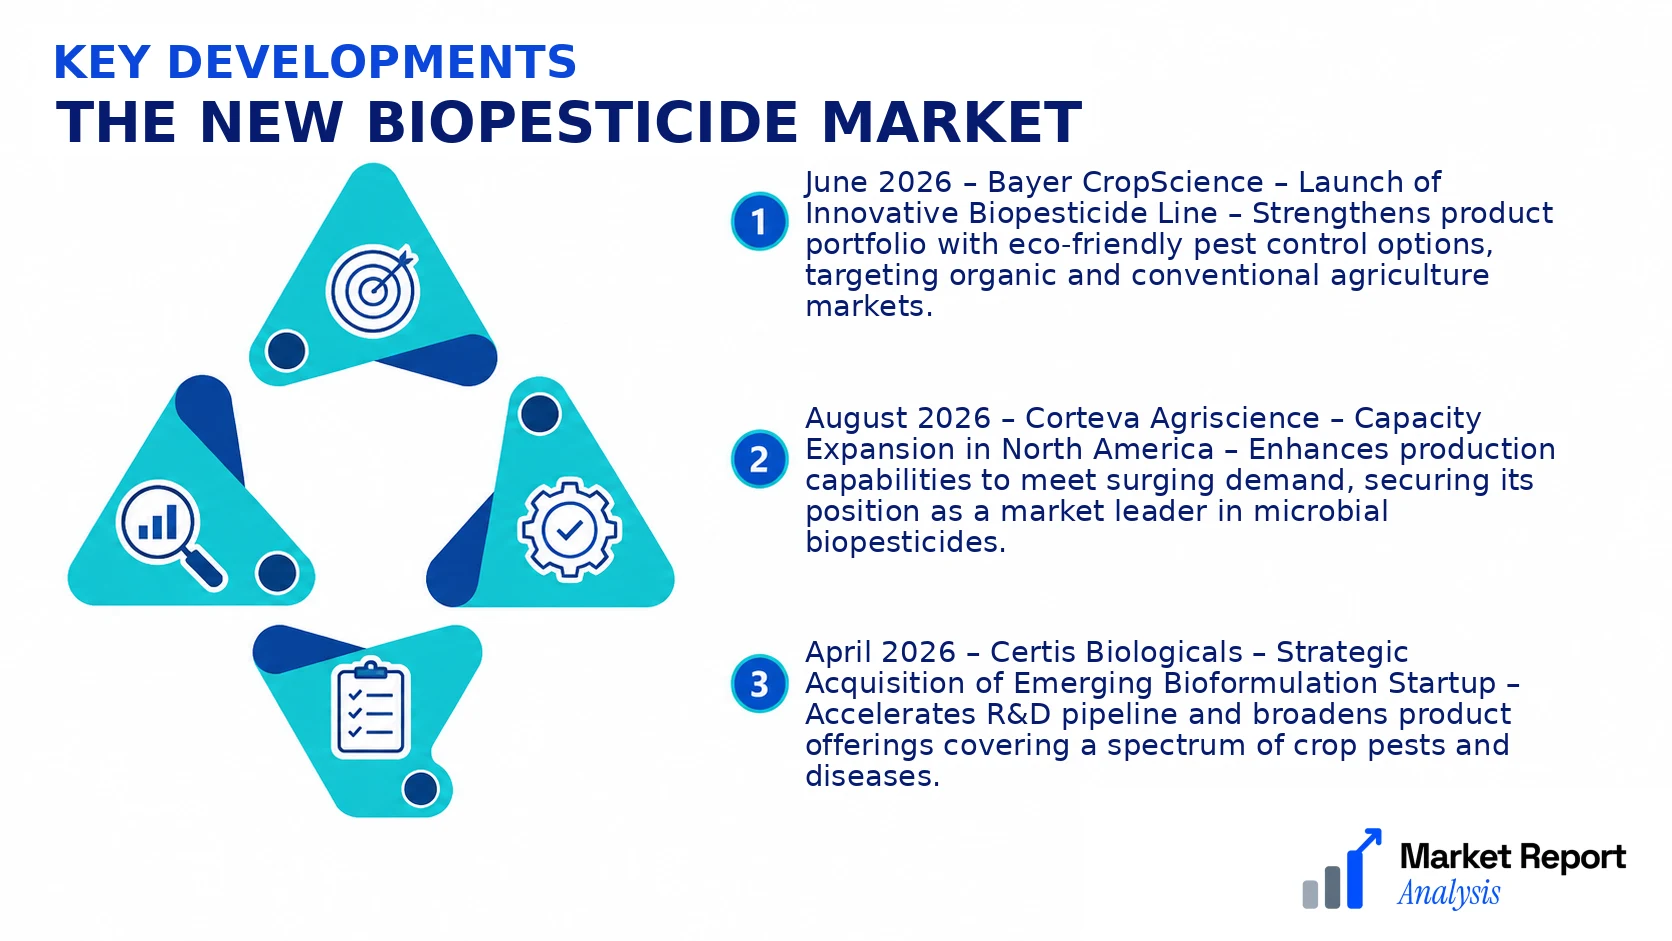
- June 2026 – Bayer CropScience – Launch of Innovative Biopesticide Line – Strengthens product portfolio with eco-friendly pest control options, targeting organic and conventional agriculture markets.
- August 2026 – Corteva Agriscience – Capacity Expansion in North America – Enhances production capabilities to meet surging demand, securing its position as a market leader in microbial biopesticides.
- April 2026 – Certis Biologicals – Strategic Acquisition of Emerging Bioformulation Startup – Accelerates R&D pipeline and broadens product offerings covering a spectrum of crop pests and diseases.
- September 2026 – Syngenta – Investment in New Biotechnology Facility – Focuses on developing next-generation bio-based active ingredients through advanced genetic engineering tools.
- July 2026 – Bioceres Crop Solutions – Partnership with Agricultural Co-ops in Latin America – Facilitates local production, ensuring supply chain resilience and market penetration in developing regions.
Frequently Asked Questions
What is the The New Biopesticide Market?
The New Biopesticide Market encompasses the global industry dedicated to the development, production, and commercialization of biopesticides. These environmentally friendly pest control solutions are derived from natural materials, offering sustainable alternatives to conventional chemicals in agricultural practices.
What is the current market size of The New Biopesticide Market?
As of 2026, the market size is valued at approximately USD 4.8 Billion, reflecting increasing adoption driven by regulatory shifts and consumer demand for organic produce. The market's growth is fueled by a rising focus on sustainable agriculture worldwide.
What factors are driving the The New Biopesticide Market?
Key drivers include stringent regulations on chemical pesticides, growing awareness of environmental impacts, advances in biopesticide research, and increasing adoption in organic farming. These factors collectively contribute to the market’s rapid expansion and innovation.
Which region dominates the The New Biopesticide Market?
North America currently leads the market, propelled by stringent regulations, a high level of technological innovation, and widespread organic farming practices. The region’s emphasis on sustainable agriculture practices consolidates its dominant market position.
Which segment is expected to grow the fastest?
Bioherbicides are anticipated to witness the fastest growth, owing to their application in weed management and rising demand within organic and integrated pest management systems across global agricultural sectors.
Who are the leading companies operating in the The New Biopesticide Market?
Major players include Bayer AG, BASF SE, Koppert Biological Systems, BioWorks Inc., and Certis USA LLC. These companies are focused on innovation, strategic collaborations, and expanding their product portfolios to strengthen market presence.
Analyst Perspective
The long-term outlook for the global biopesticide market remains robust, driven by increasing regulatory acceptance, consumer demand for sustainable agriculture, and technological advancements. Commercial opportunities are concentrated in developing biodiversity-based formulations and highly specific biocontrol agents, which offer higher efficacy and lower environmental impact. Technology evolution is anticipated to focus on precision delivery systems, genetic enhancements, and integrated pest management approaches, thereby improving efficacy and reducing costs. Investment priorities should emphasize R&D for novel biopesticide strains, scaling production capacities, and expanding regional distribution networks, particularly in emerging markets with burgeoning agricultural sectors. The competitive landscape is expected to intensify as established agrochemical players diversify into biopesticides, fostering innovation and price competitiveness. Regional growth potential is highest in Asia-Pacific and Latin America, aligned with expanding agricultural activity and supportive policies. Strategic positioning should prioritize sustainability credentials, regulatory agility, and technological innovation to capitalize on the market’s growth trajectory over the next decade.
