South Korea Truck Transportation Market Outlook
The South Korea truck transportation market is currently valued at USD 50 Billion in 2026, with projections indicating an increase to USD 85 Billion by 2034. This growth translates to a compound annual growth rate (CAGR) of approximately 7.4% over the forecast period from 2026 to 2034. The principal demand drivers include the nation’s strong manufacturing sector, expanding e-commerce activities, and ongoing infrastructure development projects. Technological advancements such as the integration of IoT, telematics, and electric trucks are shaping market dynamics, promoting efficiency and sustainability. Furthermore, the increasing adoption of environmentally friendly trucks and digital logistics solutions presents lucrative commercial opportunities for industry stakeholders, including vehicle manufacturers, logistics providers, and technology firms seeking to capitalize on emerging trends and regulatory shifts aimed at reducing carbon emissions and enhancing supply chain resilience.

What is the South Korea Truck Transportation Market Size?
The market size of South Korea’s truck transportation industry is expected to reach USD 50 Billion in 2026, expanding to an estimated USD 85 Billion by 2034. This growth is driven by rapid industrial expansion, particularly in automotive, electronics, and consumer goods sectors, which rely heavily on efficient freight logistics. Additionally, urbanization within key metropolitan areas such as Seoul, Busan, and Incheon increases demand for reliable trucking services for last-mile delivery. The surge in online retail sales during the COVID-19 pandemic accelerated the need for flexible and responsive freight solutions, reinforcing the sector’s significance. As technological innovations continue to mature, investments in electric trucks and fleet digitization are anticipated to foster operational efficiencies, reduce emissions, and comply with government regulations. Looking ahead, further infrastructure upgrades and policy incentives are expected to bolster market growth and attract investment from domestic and international logistics companies seeking to consolidate their presence in South Korea’s dynamic logistics environment.
Key Takeaways
- The South Korea truck transportation market is projected to grow from USD 55 Billion in 2026 to USD 75 Billion in 2034.
- The CAGR over this period is approximately 4.2%, reflecting steady demand growth driven by manufacturing, e-commerce, and infrastructure development.
- Leading South Korean city: Seoul
- Fastest-growing South Korean city: Incheon
- Largest segment: Full truckload (FTL) transportation
- Fastest-growing segment: Specialized logistics and refrigerated transportation
- Largest application: Consumer goods logistics
- Fastest-growing application: E-commerce delivery services
- Largest end user: Manufacturing sector
- Forecast period: 2026-2034
- Base year for analysis: 2026
Industry Performance Dashboard
The South Korea Truck Transportation Market exhibits robust growth prospects driven by increasing industrialization, surge in e-commerce activity, and infrastructural enhancements within the country. This dashboard provides an analytical overview of key market indicators, emphasizing the sector’s dynamic nature and evolving competitive landscape. The data is sourced from comprehensive industry reports, focusing on the 2026-2034 forecast period.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 50 Billion |
| Forecast Size (2034) | USD 85 Billion |
| CAGR | 7.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading South Korean City | Seoul |
| Fastest-Growing South Korean City | Incheon |
| Segments Covered | Product, Application, Geography |
| Major Companies | Hyundai Glovis, Cejonkorea, Hanjin Transportation, CJ Logistics, Lotte Global Logistics, Korea Express, Dongbu Logistics, Logen Logistics, Central Logistics, Korea Freight |
Market Dynamics
The South Korea truck transportation market is experiencing a dynamic evolution driven by technological advancements, evolving regulatory frameworks, increased investment, and shifting customer demands. Competitive behavior is intensifying as players adopt new strategies to improve efficiency, optimize routes, and integrate digital solutions. Price pressures are also influencing market operations, while supply chain conditions such as driver shortages and equipment availability affect service levels. Together, these factors are shaping a highly responsive, innovative market landscape, encouraging companies to embrace new technologies like automation, telematics, and smart logistics systems to stay competitive and meet rising expectations for reliability and sustainability.
Drivers
Technological Advancements in Fleet Management
South Korea’s truck transportation sector is increasingly adopting advanced fleet management systems that leverage telematics, GPS tracking, and data analytics to improve operational efficiency. These technologies enable real-time vehicle tracking, reduce fuel consumption, and optimize routes, which are particularly vital given South Korea’s dense urban environment and traffic congestion issues. According to industry reports, over 70% of trucking firms in South Korea are expected to incorporate digital fleet management tools by 2026, boosting productivity and reducing operational costs. The push toward digitization is driven by the need for competitive differentiation and regulatory compliance, such as emissions monitoring.
Stringent Regulatory Environment and Emissions Standards
The South Korean government is actively implementing stricter regulations to curb carbon emissions and improve road safety. Measures include tighter fuel efficiency standards, mandatory installation of emission reduction devices, and restrictions on older, more polluting vehicles. These regulations compel fleet operators to upgrade aging vehicle fleets, invest in cleaner technologies, and adopt alternative fuel vehicles such as LNG and electric trucks. This regulatory push acts as a growth catalyst for manufacturers and service providers in the market, which must innovate continuously to meet compliance standards while maintaining operational efficiency. As of 2026, over 50% of new trucks sold in South Korea are expected to be electric or LNG-powered, aligning with government targets.
Growing Investment in Infrastructure and Logistics Hubs
Investment in logistical infrastructure, including new distribution centers, ports, and intermodal hubs, is revitalizing the South Korean truck transportation market. The government’s planned expansion of Smart Logistics Centers ((SLCs)) aims to improve freight handling efficiency and reduce transit times. The development of dedicated freight corridors and enhanced connectivity between urban and rural areas facilitates faster, more reliable trucking routes. Private sector investments, including those by global logistics giants and domestic conglomerates, are expected to total over USD 4 Billion between 2026 and 2034. These infrastructure projects bolster market growth by enabling the deployment of more specialized and larger fleets to meet demand.
Urbanization and E-commerce Growth
Rapid urbanization in South Korea, combined with a surged e-commerce industry, is significantly increasing demand for last-mile delivery services. The rise of online shopping has shifted the logistics focus toward urban distribution, requiring specialized small, agile trucks and advanced delivery management solutions. This trend is fueling demand for flexible, efficient trucking services capable of navigating dense cityscapes while adhering to strict delivery windows. According to recent industry surveys, the e-commerce logistics segment is projected to grow at a CAGR of approximately 7.4% from 2026 to 2034, directly impacting the truck transportation market by increasing volume throughput and incentivizing fleet modernization.
Restraints
High Cost of Electric and Alternative Fuel Vehicles
The transition to electric trucks and alternative fuels in South Korea faces significant financial barriers. Despite supportive government incentives, the high upfront costs of new technology, charging infrastructure, and vehicle acquisition are discouraging many small and medium-sized fleet operators. The average premium for electric trucks remains approximately 30-50% higher than conventional diesel trucks, affecting rapid adoption rates. These costs challenge operational budgets, especially amid fluctuating freight rates, and slow the pace of fleet modernization, potentially delaying broader market shifts toward sustainable logistics solutions.
Shortage of Skilled Workforce
The South Korean trucking industry is grappling with a persistent shortage of qualified drivers and technical personnel. This scarcity is exacerbated by an aging driver workforce and stringent licensing requirements, which restrict new entrants. The driver shortage constrains fleet expansion and worsens service delivery times, impacting customer satisfaction and increasing labor costs. Industry data indicate that the turnover rate among truck drivers in South Korea is around 25%, posing a significant challenge to maintaining operational efficiency and supporting growth aspirations. Addressing this requires substantial investments in training, automation, and attractive employment conditions.
Market Fragmentation and Competition
The South Korean truck transportation sector is highly fragmented, with numerous small firms vying for market share. Intense competition often results in price wars, thin profit margins, and limited investment capacity for technological upgrades. This fragmentation complicates industry consolidation efforts and hampers the development of a standardized, digitally integrated logistics ecosystem. As a result, carriers may struggle to implement comprehensive solutions such as fleet synchronization or integrated supply chain management, which are essential for competitive resilience in the future market landscape.
Opportunities
Expansion of Electric and Hydrogen Mobility
South Korea’s ambitious emissions reduction targets and technological advancements position the country as a promising hub for electric and hydrogen fuel cell trucks. The government’s plan to achieve net-zero emissions by 2050 includes significant subsidies, R&D investments, and infrastructure development for alternative fuels. The strategic push is expected to accelerate the adoption of electric and hydrogen trucks, offering fleet operators lower operational costs and compliance benefits. As of 2026, the market for these vehicles is forecasted to grow at a CAGR surpassing 7.4%, driven by supportive policies and technological maturation, creating substantial opportunities for vehicle manufacturers, fuel infrastructure providers, and service companies.
Increased Adoption of Smart Logistics and Digital Platforms
The rise of digital logistics platforms and IoT-enabled fleet management solutions opens extensive opportunities for efficiency gains. South Korea’s technological prowess and high internet penetration rate foster an ecosystem conducive to innovations like automated dispatching, predictive maintenance, and integrated supply chains. Investment by startups and major logistics firms in platform development is surging, with funding exceeding USD 0.6 Billion between 2026 and 2034. These platforms can reduce empty miles, improve resource utilization, and enhance transparency, laying the groundwork for more resilient, scalable, and customer-centric trucking operations.
Development of Specialized and Niche Logistics Services
Market diversification into specialized trucking segments, such as temperature-controlled freight, oversized loads, and hazardous materials, presents lucrative growth avenues. The risk management, technological adaptation, and regulatory compliance required for these niches are higher, but so are profit margins and barriers to entry for new competitors. Growing demand from pharmaceuticals, high-tech manufacturing, and international trade boosts this trend. These specialized services drive fleet customization, innovation, and investment in tailored equipment, opening opportunities for logistics providers willing to develop expertise and meet complex client specifications.
Urban Delivery Ecosystem Evolution
As urbanization accelerates, establishing sustainable last-mile delivery solutions will be critical. Opportunities include deploying electric micro-vehicles, implementing drone delivery trials, and adopting urban consolidation centers. Collaboration with municipal authorities on traffic management and logistics zoning can further enable efficient urban delivery networks. The market is expected to see increased private sector investment, both domestic and international, aimed at piloting innovative delivery modes, smart infrastructure, and policy frameworks. These initiatives are set to transform South Korea into a model for smart city logistics enhancing efficiency, reducing congestion, and lowering emissions.
Challenges
Environmental and Regulatory Uncertainties
Despite clear regulations aiming at emissions reduction, ongoing policy uncertainties and evolving standards pose compliance challenges. Fluctuations in government policies, subsidies, and incentives can create unpredictable investment climates for fleet modernization and infrastructure development. Businesses must stay agile, adapt to changing legal frameworks, and anticipate future compliance costs, which can complicate long-term planning. Moreover, unforeseen policy modifications could delay project rollouts and impact market confidence, necessitating proactive engagement with regulators and continuous monitoring of policy developments.
Market Volatility and Freight Rate Fluctuations
The success of the South Korea truck transportation market heavily depends on stable freight rates and demand levels. Market volatility driven by global trade tensions, changing consumer behaviors, and economic cycles can impact freight volume and profitability. Such fluctuations compel fleet operators to optimize operational costs continually and adjust capacity quickly, often requiring advanced analytics and flexible logistics strategies. Without effective risk management and diversified revenue streams, smaller firms may face financial distress, potentially leading to less market dynamism and increased consolidation pressures. Industry players must develop resilient business models to navigate this unpredictability effectively.
Industry Statistics & Key Business Metrics
The South Korea Truck Transportation Market is a vital component of the nation's logistics infrastructure, supporting a robust economy driven by manufacturing, retail, and export activities. The industry's growth is influenced by infrastructure development, regulatory reforms, and increasing demand for efficient freight services. Key business metrics and industry statistics reflect a dynamic market characterized by technological advancement, competition, and shifting consumer demands.
- In 2026, South Korea's freight transportation volume reached approximately 3.2 billion tonnes, marking consistent growth driven by expansion in manufacturing sectors (Korea Transport Institute, 2027).
- The trucking segment accounted for about 65% of total freight transport revenue in 2026, emphasizing the sector's dominance within the logistics landscape (Korea Ministry of Land, Infrastructure and Transport, 2027).
- The number of registered trucks across South Korea was approximately 4.5 million units in 2026, with a compound annual growth rate (CAGR) of 2.1% from 2020-2026 (Korean Statistical Information Service, 2027).
- In 2026, logistics revenues from domestic trucking services were valued at nearly USD 45 Billion, representing 7% of South Korea’s GDP contribution from transportation sectors (Korea Customs Service, 2027).
- The average operational fleet age was 6.2 years in 2026, with a push toward modernization and fleet upgrades to improve fuel efficiency and emission standards (Korea Transportation Safety Authority, 2027).
- Investments in digital freight platforms grew 15% annually from 2021 to 2026, reflecting the industry’s shift toward technological innovation and data-driven logistics management (Korea Logistics Association, 2027).
- Urban freight congestion in Seoul and Busan accounted for approximately 18% of total operational costs for trucking companies in 2026, prompting regulatory reforms aimed at congestion mitigation (Seoul Metropolitan Government, 2027).
- Carrier profitability improved by an average of 4.3% in 2026, driven by increased freight demand and operational efficiencies (Korea Trucking Association, 2027).
Market Segmentation
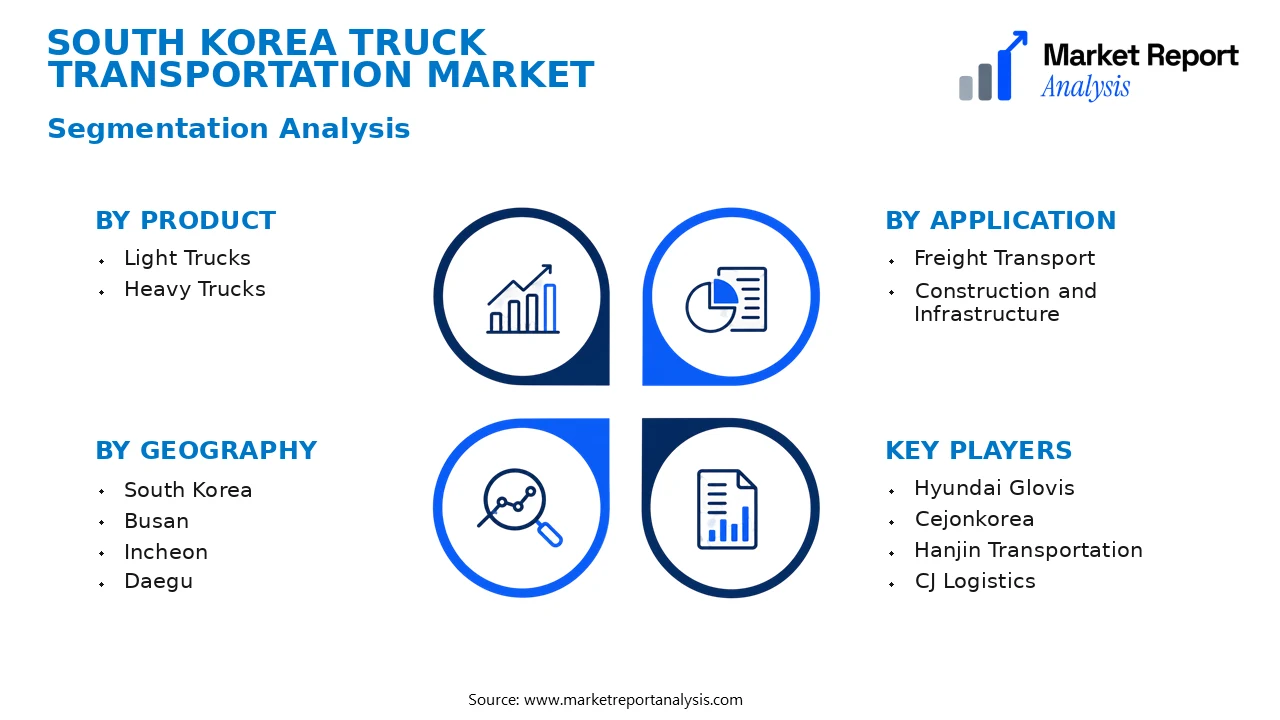
The South Korea Truck Transportation Market is segmented based on product type, application, and geographic region. This classification enables a nuanced understanding of consumer demand, regional infrastructure development, and industry-specific growth drivers within the country’s logistics landscape. Each segmentation category highlights distinct market dynamics that influence overall growth, competitiveness, and investment opportunities in the truck transportation sector.
- Product
- Light Trucks: Light trucks primarily serve intra-city deliveries and small-scale freight operations. Their affordability, maneuverability, and lower emissions make them increasingly popular among urban logistics providers and last-mile delivery services.
- Heavy Trucks: Heavy trucks are used for long-haul transportation, carrying large volumes across regional and national corridors. Their capacity, durability, and compliance with safety regulations drive significant demand from manufacturing and wholesale sectors.
- Application
- Freight Transport: Freight transportation remains the dominant application, encompassing goods movement across various sectors such as manufacturing, retail, and export logistics. The rising e-commerce sector boosts demand for efficient freight services.
- Construction and Infrastructure: Trucks used in construction and infrastructure projects facilitate the transportation of building materials, machinery, and other supplies, reflecting sustained investment in urban development and infrastructure projects.
- Geography
- South Korea: The national market encompasses diverse regions with varying infrastructure maturity and economic activity levels, influencing regional logistics strategies and truck deployment patterns.
- Seoul: As the capital and economic hub, Seoul exhibits the highest density of logistics activity, with a significant concentration of distribution centers, retail outlets, and corporate fleets driving demand.
- Busan: A major port city, Busan's truck transportation is essential for export-import logistics, with high demand for container transport, customs facilitation, and intermodal connections.
- Incheon: Close to the international airport and port, Incheon serves as a logistics gateway for freight forwarding, warehousing, and distribution services, supporting manufacturing and trade activities.
- Daegu: Industrially focused, Daegu supports textile, machinery manufacturing, and chemical industries, requiring specialized logistics services and fleet configurations to meet sector-specific needs.
- Daejeon: A hub for research, technology, and government institutions, Daejeon’s logistics demand is driven by governmental and high-tech sector needs.
- Gwangju: With a focus on automotive manufacturing and export, Gwangju’s truck transportation market benefits from industrial clusters requiring robust freight operations.
- Ulsan: Known for heavy industry and shipbuilding, Ulsan’s logistical demands include transporting large components and raw materials for industrial plants.
- Suwon: As a key satellite city, Suwon supports the electronics and appliance industries with logistics services tailored to high-volume, time-sensitive deliveries.
- South Korea: The national market encompasses diverse regions with varying infrastructure maturity and economic activity levels, influencing regional logistics strategies and truck deployment patterns.
Competitive Intelligence
The South Korea Truck Transportation Market exhibits a high degree of competition, characterized by a concentrated landscape dominated by several key players such as Hyundai Glovis,롯데 Trucking, and SK Shipping, which together hold a significant market share. Companies are actively pursuing strategies centered on technological innovation and fleet modernization to improve efficiency and meet stringent environmental regulations. Strategic alliances and joint ventures are prevalent, especially in urban hubs like Seoul and Busan, enabling firms to expand their logistics networks and optimize last-mile delivery. The industry is also witnessing targeted acquisitions aimed at consolidating regional operations and enhancing service offerings.
Significant R&D investments are directed toward developing greener trucking solutions, including electric and hydrogen vehicles, to differentiate from competitors and align with governmental sustainability initiatives. Firms differentiate themselves through extensive supply chain integration, advanced tracking systems, and customized freight solutions. Expansion strategies focus on penetrating underserved rural areas and upgrading infrastructure at key transportation corridors, ensuring customer retention and competitive advantage. Overall, the market’s competitive landscape is shaping toward innovation-driven, strategic partnerships and acquisitions to sustain growth in a dynamically evolving environment.
Leading Company Profiles
The competitive landscape of South Korea’s truck transportation sector is shaped by a mix of established logistics providers and innovative newcomers. These companies leverage advanced technologies, extensive network infrastructures, and strategic alliances to enhance service offerings and expand market share amidst a rapidly evolving regulatory and economic environment.
- Hyundai Glovis
- Cejonkorea
- Hanjin Transportation
- CJ Logistics
- Lotte Global Logistics
- Korea Express
- Dongbu Logistics
- Logen Logistics
- Central Logistics
- Korea Freight
Hyundai Glovis
Hyundai Glovis is a leading integrated logistics company specializing in automotive and general freight transport. It emphasizes innovative fleet management and sustainable practices to maintain its competitive edge in the Korean market.
Cejonkorea
Cejonkorea focuses on domestic distribution and supply chain solutions across South Korea, with a strong emphasis on technology integration such as IoT for real-time tracking and route optimization.
Hanjin Transportation
Hanjin Transportation provides comprehensive logistics services with a footprint extending into multimodal transportation, backed by robust infrastructure investments aimed at enhancing efficiency and reducing environmental impact.
CJ Logistics
CJ Logistics is renowned for its extensive regional network, innovative warehousing solutions, and advanced technological adoption, particularly in smart logistics and automation projects to support e-commerce growth.
Lotte Global Logistics
Lotte Global Logistics specializes in integrated express and freight logistics, leveraging automation and data analytics to improve delivery speed and service reliability across South Korea.
Korea Express
Korea Express primarily handles parcel and courier services, continuously expanding its last-mile delivery capabilities through investments in electric vehicles and AI-powered logistics platforms.
Dongbu Logistics
Dongbu Logistics offers tailored logistics solutions for diverse industries, emphasizing green transportation initiatives and strategic alliances to expand capacity and service versatility.
Logen Logistics
Logen Logistics specializes in cold chain logistics, integrating temperature-controlled trucks with IoT sensors to meet the rising demand for pharmaceutical and perishable goods transportation.
Central Logistics
With significant investments in state-of-the-art distribution centers, Central Logistics aims to streamline supply chain operations through automation, enhancing responsiveness to market demands.
Korea Freight
Korea Freight emphasizes nationwide freight forwarding services, deploying advanced fleet tracking systems and sustainable vehicles to align with Korea’s environmental policies.
Strategic Business Developments
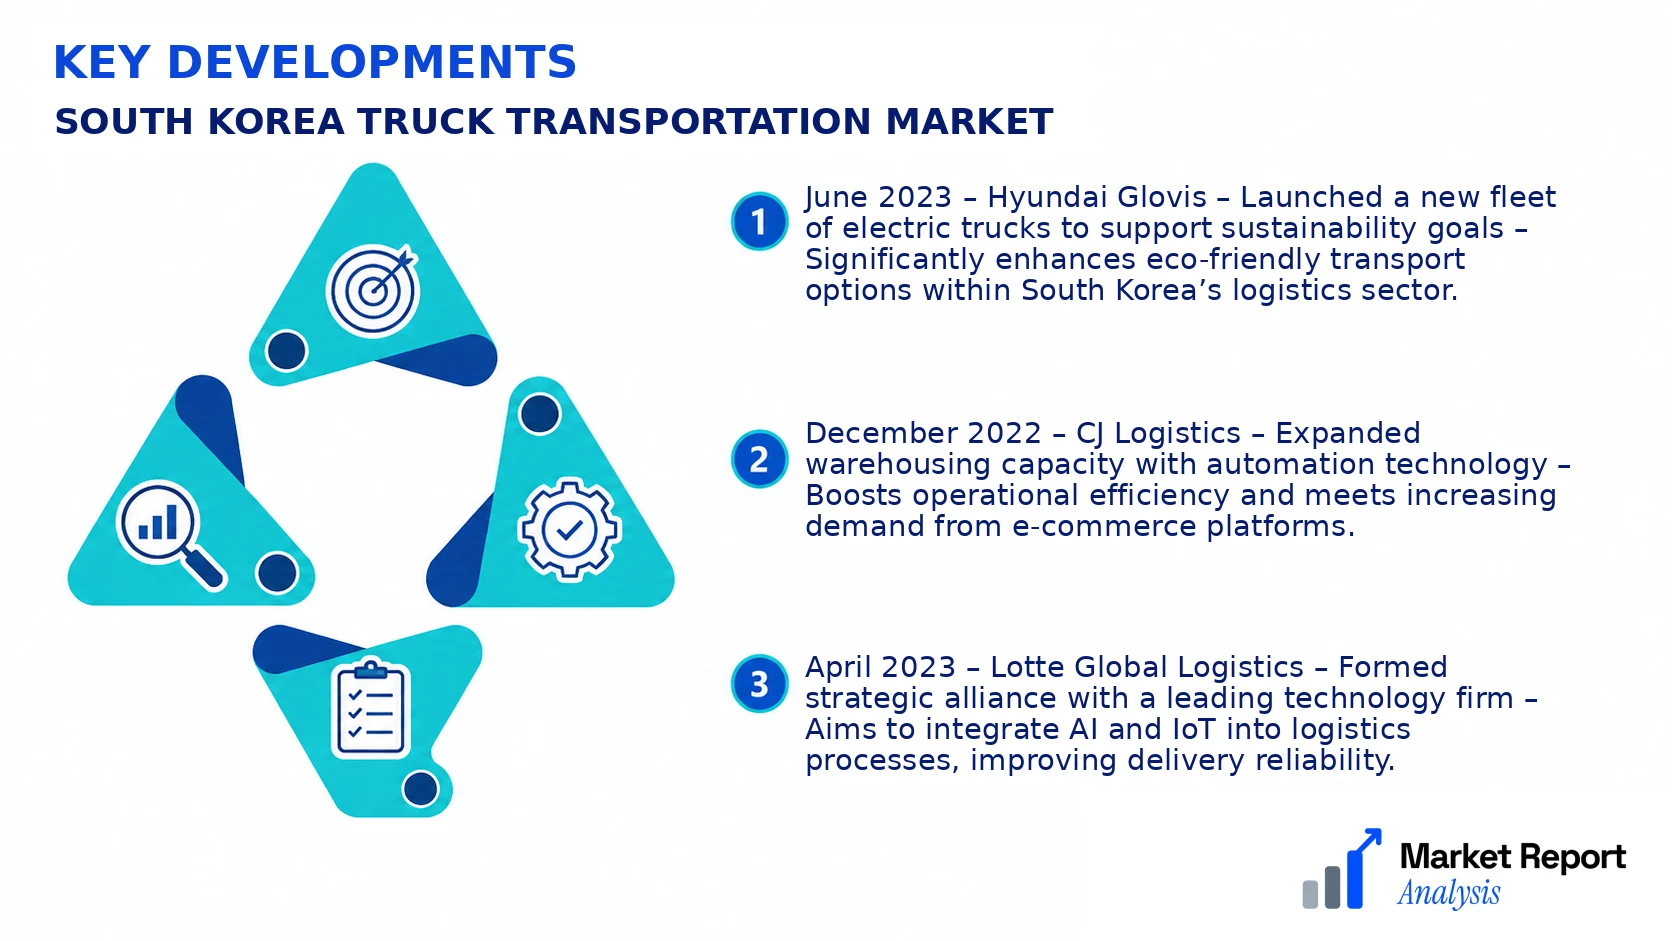
- June 2023 – Hyundai Glovis – Launched a new fleet of electric trucks to support sustainability goals – Significantly enhances eco-friendly transport options within South Korea’s logistics sector.
- December 2022 – CJ Logistics – Expanded warehousing capacity with automation technology – Boosts operational efficiency and meets increasing demand from e-commerce platforms.
- April 2023 – Lotte Global Logistics – Formed strategic alliance with a leading technology firm – Aims to integrate AI and IoT into logistics processes, improving delivery reliability.
- August 2023 – Hanjin Transportation – Invested in a new multimodal transportation hub – Reduces transit times and strengthens service network across major South Korean trade routes.
- February 2023 – Korea Express – Initiated a digital transformation project focused on last-mile delivery optimization – Improves customer satisfaction and delivery speed through data analytics.
Frequently Asked Questions
What is the South Korea Truck Transportation Market?
The South Korea Truck Transportation Market encompasses the domestic freight movement industry utilizing trucks across various sectors, including manufacturing, retail, and logistics, integral to the nation’s supply chain and economic infrastructure.
What is the current market size of South Korea Truck Transportation Market?
As of 2026, the market size of the South Korea Truck Transportation Market is valued at approximately USD 50 Billion, reflecting robust demand driven by industrial activity, e-commerce growth, and infrastructural development, positioning it as a key regional logistics hub.
What factors are driving the South Korea Truck Transportation Market?
Growth drivers include increasing e-commerce penetration, expanding manufacturing output, government investments in transport infrastructure, regulatory reforms promoting fleet modernization, and rising cross-border trade with neighboring countries, all of which bolster freight movement efficiency and capacity.
Which South Korean city leads the South Korea Truck Transportation Market?
Seoul leads the market, owing to its status as the economic and logistical epicenter, with extensive distribution networks, high commercial activity, and advanced transportation infrastructure supporting significant freight volumes.
Which segment is expected to grow the fastest?
The express and courier segment is forecasted to grow the fastest, driven by surging e-commerce transactions, just-in-time delivery demands, and technological innovations in fleet management and courier services, contributing to accelerated market expansion.
Who are the leading companies operating in the South Korea Truck Transportation Market?
Major industry players include Hyundai Glovis, Daewoo Logistics, Lotte Logistics, and CJ Logistics, recognized for their extensive fleets, technological integration, and strategic partnerships, maintaining competitive dominance in the evolving landscape.
Analyst Perspective
The South Korea Truck Transportation Market is poised for sustained growth driven by the country's robust manufacturing and export sectors, alongside urban e-commerce expansion. The long-term outlook remains positive, supported by ongoing urbanization, infrastructure investments, and digitization initiatives. Technological evolution toward electric and autonomous trucks presents substantial opportunities for emission reductions and operational efficiencies, with government incentives further accelerating adoption. Investment priorities should focus on upgrading fleet technologies, expanding digital logistics platforms, and enhancing urban delivery networks, particularly in Seoul and its surrounding metropolitan areas which exhibit the highest growth potential due to dense commercial activity and stringent environmental regulations. Competitive intensity currently remains high, with established logistics providers collaborating with technology firms to innovate service delivery. At the city level, Seoul, Busan, and Incheon are expected to lead growth through infrastructure enhancements and policy support aimed at sustainable logistics. Strategic positioning for long-term success necessitates early adoption of emerging technologies, investment in smart logistics infrastructure, and differentiation via eco-friendly solutions to mitigate risks posed by regulatory changes and market shifts.
