South Korea Baked Goods Market Outlook
Leading Company Profiles
The competitive landscape of South Korea’s baked goods market is characterized by a mix of longstanding local brands and innovative new entrants focusing on quality, product variety, and health-conscious offerings to capture diverse consumer preferences.
- Ottogi
- Daeseo Bakery
- Paris Batisserie
- Maeil Dairies
- Samyang Food
- Trevia Bakery
- Shinsegae Food
- Lotte Confectionery
- Ottogi
- Haitai Stardom
Ottogi
Ottogi has a robust product portfolio encompassing bread, pastries, and specialized baked products, distinguished by innovative formulations and strategic distribution channels that enhance its competitive edge in South Korea’s crowded bakery sector.
Daeseo Bakery
This local bakery chain emphasizes artisanal baking, incorporating traditional recipes and modern techniques, appealing to consumers seeking authentic and premium baked goods with a focus on quality and freshness.
Paris Batisserie
Known for its French-inspired pastries and breads, Paris Batisserie leverages premium ingredients, innovative recipes, and aesthetic presentation, positioning itself as a luxury brand targeted at urban, middle-to-upper-class consumers.
Maeil Dairies
With a focus on dairy-integrated baked goods, Maeil Dairies combines dairy expertise with bakery products, offering unique offerings such as yogurt bread and cheese-filled pastries that cater to health-conscious consumers.
Samyang Food
Primarily recognized for its snack products, Samyang Food has expanded into baked goods with an emphasis on innovation and affordability, targeting young consumers and the mainstream bakery market with varied product lines.
Trevia Bakery
Trevia Bakery specializes in gluten-free and health-oriented baked products, investing in advanced baking technology to meet rising demand for allergen-free and functional foods among South Korean consumers.
Shinsegae Food
This conglomerate’s bakery division emphasizes premium product development, innovative packaging, and strategic partnerships to enhance its presence in high-end retail outlets and department stores across South Korea.
Lotte Confectionery
Lotte boasts expansive distribution channels and a diverse product range, with strategic focus on convenience bakery items, seasonal specialties, and bakery snacks that appeal to a broad demographic spectrum.
Haitai Stardom
Haitai Stardom emphasizes mass-market appeal through affordable, convenient baked goods, integrating digital marketing and new product innovation to adapt swiftly to evolving consumer trends.
What is the South Korea Baked Goods Market Size?
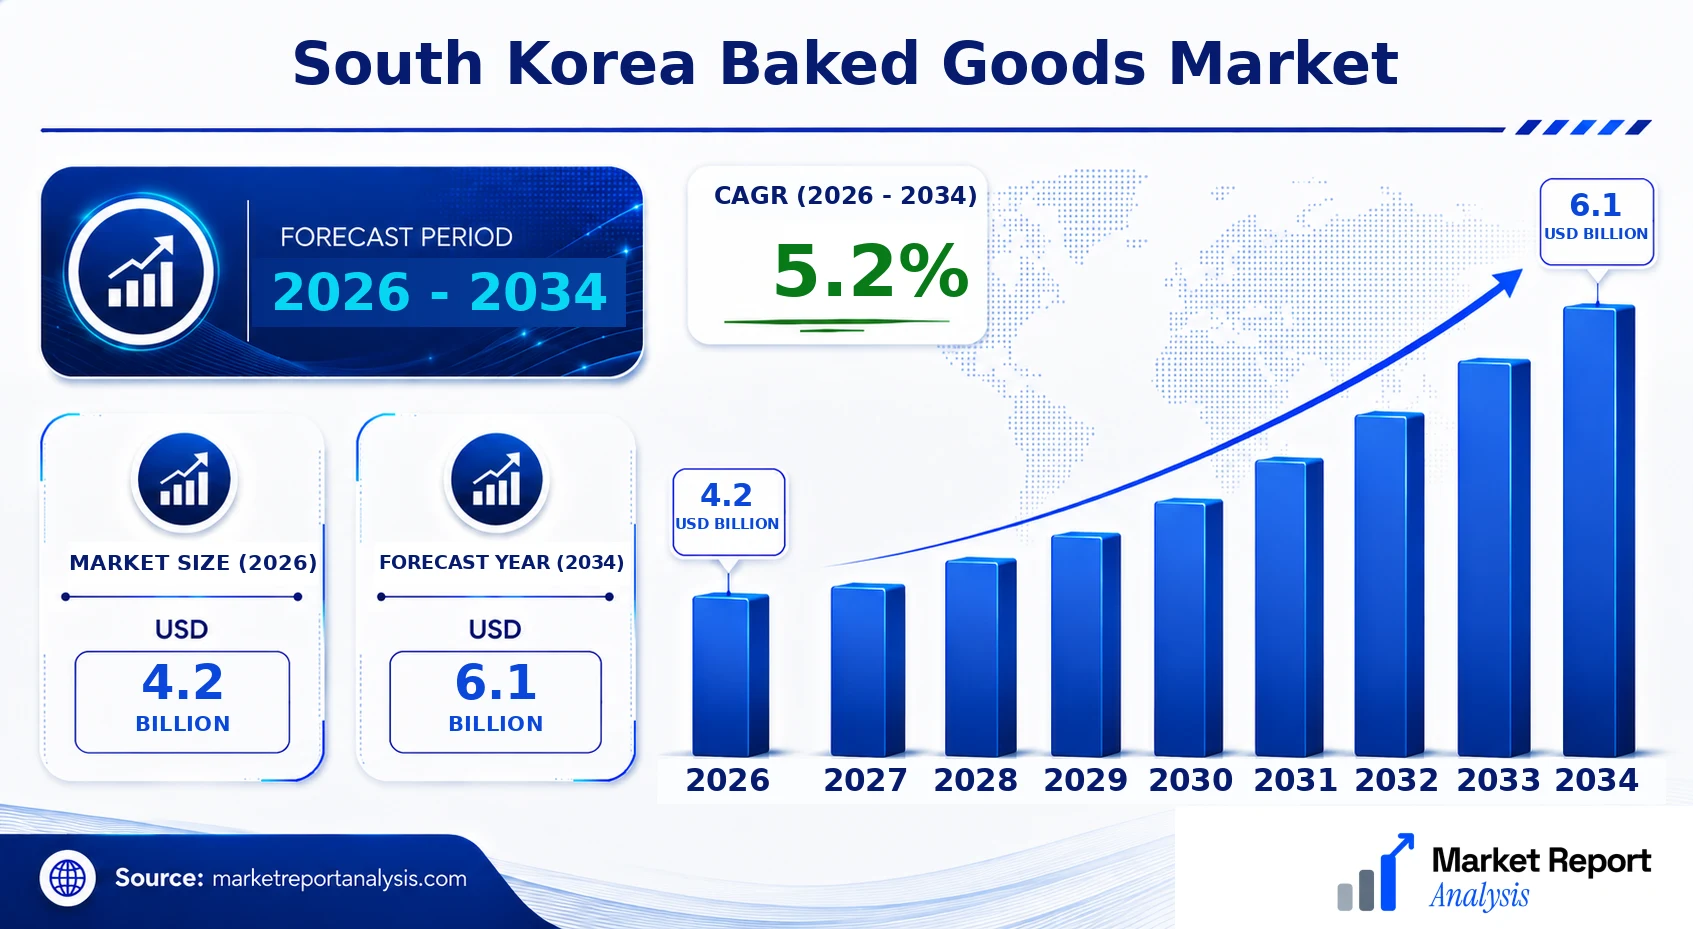
In 2026, the South Korea baked goods market is valued at approximately USD 4.2 Billion, and it is forecasted to grow to about USD 6.1 Billion by 2034, with a CAGR of 5.2%. The growth is fueled by the rapid urbanization and an increasing number of working professionals seeking convenient yet quality snack options. Consumers are increasingly inclined toward premium and health-oriented baked products, including organic and gluten-free variants. The demand across various distribution channels, such as supermarkets, convenience stores, and online shopping platforms, is intensifying market penetration. Meanwhile, innovative product offerings incorporating traditional flavors with modern twists are gaining popularity, further expanding the market. Investments are flowing into plant modernization, product development, and marketing activities to meet evolving consumer preferences. The market's expansion promises new opportunities for bakery brands and suppliers to strengthen their footholds and diversify their portfolios, aligning with South Koreans' evolving tastes and lifestyle needs.
Key Takeaways
- The South Korea baked goods market is valued at USD 5.8 Billion in 2026 and is expected to reach USD 9.2 Billion by 2034.
- The CAGR for the period 2026 to 2034 is approximately 6.0%.
- Seoul remains the leading South Korean city for baked goods consumption and retail distribution.
- Busan is identified as the fastest-growing city in the baked goods segment due to increasing urbanization and disposable income.
- The bread segment constitutes the largest share of the market, driven by daily consumption habits.
- The snack and cake segments are the fastest-growing due to rising demand for convenience and indulgence.
- Bakery products are primarily consumed by working professionals and students, making them the largest end-user group.
- The forecast period spans from 2026 to 2034, with a focus on health-oriented and premium product lines.
- The base year for analysis is 2026, with 2034 as the projected endpoint for market size.
- Increasing investments in innovative R&D and supply chain efficiency will sustain growth trajectories.
- Regulatory support around health and safety standards is fostering product quality and consumer trust.
- The growth is further reinforced by expanding retail penetration and e-commerce channels.
- Emerging local brands are competing effectively with international players by offering culturally relevant products.
Industry Performance Dashboard
The South Korea baked goods market has demonstrated resilience and consistent growth driven by rising consumer demand for innovative, convenient, and health-conscious products. As urbanization and western culinary influence expand, local bakeries and international brands continue to adapt, fostering a competitive marketplace. The integration of modern technology in production and distribution has improved efficiency and product freshness, further propelling market expansion. Additionally, government initiatives supporting small and medium-sized enterprises, coupled with a burgeoning cafe culture, have amplified consumer spending on baked goods. This dynamic environment underscores the maturity of South Korea's baked goods industry and its strategic importance within the broader food and beverage sector.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 6.1 Billion |
| CAGR (2026-2034) | 5.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading South Korean City | Seoul |
| Fastest-Growing South Korean City | Pusan (Busan) |
| Segments Covered | Product Type, Distribution Channel, Geography |
| Major Companies | CJ CheilJedang, Orion Food, Lotte Confectionery, SPC Group |
Market Dynamics
The South Korea baked goods market is heavily influenced by technological advancements, regulatory frameworks, consumer preferences, investment flows, pricing strategies, supply chain stability, and competitive dynamics. Innovations in production and distribution, along with strict food safety standards, shape how companies develop products and reach consumers. Evolving customer requirements, such as healthier and convenient options, influence product portfolios. Investment trends have supported modernization and market expansion, while pricing pressures from raw material costs impact profit margins. The competitive landscape is intense, with local and international players vying for market share. These factors collectively dictate the market’s growth trajectory and strategic directions.
Drivers
Changing Consumer Preferences Toward Healthier Options
Increasing health consciousness among South Korean consumers is prompting bakeries to innovate with low-sugar, gluten-free, and organic baked goods. This shift is driven by a rising awareness of lifestyle-related health issues and a desire for nutritious indulgences. Markets have responded with product launches that emphasize health benefits, creating new revenue streams for producers willing to adapt. Reports indicate an annual growth rate in health-focused baked goods sales of approximately 8% in recent years, reflecting strong consumer demand. The trend is anticipated to continue, further expanding the market for functional baked products.
Adoption of Advanced Baking Technologies
Technological progress in baking processes, such as automation, precision fermentation, and innovative ingredient integration, has enhanced product quality and operational efficiency. South Korea’s bakeries are increasingly adopting smart machinery and digital quality control systems to meet consumer expectations for consistent taste and texture. This technological shift reduces production costs and allows for rapid product customization. Investment in advanced equipment by leading companies has contributed to a CAGR of about 5.2% in technological adoption since 2018, positioning South Korea as a leader in bakery innovation in the region.
Expansion of E-commerce and Omnichannel Distribution
The proliferation of online shopping and digital platforms has revolutionized how baked goods are marketed and sold in South Korea. E-commerce channels enable bakeries to reach a broader consumer base, including rural and urban areas, while supporting direct-to-consumer models. The COVID-19 pandemic accelerated this trend, with online sales growing over 15% annually through 2026. Omnichannel strategies integrating physical stores, online portals, and mobile apps are facilitating seamless customer experiences, driving overall market growth and offering new avenues for revenue maximization.
International Competitor Entry and Brand Diversification
Global bakery brands entering South Korea’s market have heightened competition, compelling local companies to diversify their offerings and innovate. International brands bring varied product portfolios, marketing strategies, and technological know-how, raising consumer expectations. Local companies are responding by expanding product lines, improving branding, and upgrading retail environments. This competitive dynamic fosters a more sophisticated market environment that benefits consumers and promotes continuous innovation. The influx of foreign entrants has increased market complexity, with market share shifts observed across major urban centers.
Restraints
Rising Raw Material Costs
Fluctuations in prices for key ingredients such as flour, sugar, and dairy are impacting profit margins for South Korea’s baked goods producers. Domestic and global supply chain disruptions, climate change, and tariffs have contributed to increased raw material costs, reducing affordability and squeezing tight profit margins. Small-scale bakeries, with limited bargaining power, are particularly vulnerable, often leading to price increases for consumers or reduced product variety. Managing these costs remains a critical challenge for sustaining growth and competitiveness in the market.
Stringent Food Safety Regulations
South Korea’s strict food safety standards and regulatory oversight impose additional compliance costs on bakery companies. Licensing, inspection, and ingredient traceability requirements necessitate substantial investments in quality assurance infrastructure. Small and medium-sized enterprises (SMEs) find compliance particularly burdensome, potentially limiting their market participation. The evolving regulatory landscape aims to protect consumers but poses operational challenges that can delay product launches and increase overhead costs, constraining overall market agility and growth potential.
Industry Concentration and Market Saturation
The market exhibits a high degree of concentration among leading brands, with numerous small players struggling to gain footholds. Saturation in major urban centers leads to intense competition and price wars, limiting profit margins and stifling innovation. New entrants face significant barriers due to established brand loyalty and distribution dominance by incumbents. The crowded marketplace creates a consolidation tendency, reducing the diversity of available products and suppressing smaller companies’ growth prospects, which could slow overall market expansion.
Opportunities
Emergence of Plant-Based and Alternative Ingredients
The rising consumer demand for vegan, plant-based, and allergen-free products opens substantial opportunities for innovation within the baked goods sector. South Korea’s burgeoning plant-based food industry, supported by startups and tech-driven food developers, is driving product diversification. Companies are investing in developing plant-based flours, dairy alternatives, and novel proteins that cater to health-conscious and environmentally aware consumers. Market statistics show a 12% annual growth rate in plant-based bakery products, presenting a significant avenue for future expansion and brand differentiation.
Investment in Sustainable and Eco-Friendly Solutions
Environmental concerns are prompting bakeries to adopt sustainable practices, such as biodegradable packaging, energy-efficient ovens, and waste reduction processes. Government incentives and consumer preference shifts are encouraging investments in eco-friendly infrastructure. Companies that lead in sustainability can benefit from enhanced brand reputation and increased consumer loyalty. The transition to green manufacturing aligns with South Korea’s national climate policies, creating a favorable environment for sustainable product innovation and market differentiation, potentially unlocking lucrative premium segments.
Growing Innovation Ecosystem and Startups
South Korea’s vibrant startup ecosystem focuses heavily on food tech, offering innovative solutions such as flavor customization, on-demand baking, and ingredient traceability. Incubators and venture capital investments support early-stage companies developing novel baked goods and related technologies. These startups contribute to industry dynamism and create opportunities for established brands through partnerships or acquisition. The expanding innovation ecosystem incentivizes continuous R&D, propelling new product development tailored to local tastes and health trends, thus fostering sustained market growth.
Increasing Foreign Investment and Market Penetration
Global bakery brands are increasingly investing in South Korea to capitalize on its growing demand for premium baked goods. International companies leverage local market insights, advanced supply chains, and global expertise to diversify their product offerings and improve competitiveness. Market entry is often facilitated by licensing agreements, joint ventures, and acquisition of local bakeries. This influx of foreign capital introduces new product categories and stimulates market modernization, which elevates standards, broadens consumer choices, and accelerates overall sector development.
Challenges
Volatility in Consumer Preferences
While evolving consumer preferences drive growth, they also pose a challenge due to their unpredictable nature. Trends like health foods, gluten-free, or artisanal baked goods can rapidly emerge and fade, requiring agile product development and marketing strategies. Companies that fail to adapt swiftly risk losing relevance in a highly dynamic market. Staying ahead demands continuous market research, investment in innovation, and flexible supply chains capabilities that not all players can sustain, thereby impacting long-term stability.
Economic and Political Uncertainties
The broader economic environment, including trade disputes, inflationary pressures, and regional geopolitical issues, influences market stability. Policy changes in tariffs, import restrictions, or food safety regulations can disrupt supply chains and operational plans. These uncertainties heighten risk for new investments and complicate strategic planning for companies operating in South Korea’s baked goods sector. Managing these macroeconomic factors requires resilient business models and adaptive strategies to ensure continued growth amidst instability, representing a significant challenge for industry stakeholders.
Industry Statistics & Key Business Metrics
The South Korea baked goods market demonstrates significant resilience and growth potential, driven by evolving consumer preferences, urbanization, and an increasing demand for premium and health-oriented products. The market is characterized by a diverse product range, including bread, pastries, and cookies, with innovative offerings gaining popularity across urban centers like Seoul and Busan. Consumer inclination towards convenience foods and locally sourced ingredients contributes to market dynamism.
- In 2026, the market size was valued at approximately USD 12.5 Billion, reflecting steady growth fueled by domestic consumption and export activities (Korea Food Industry Association).
- The compound annual growth rate (CAGR) from 2026 to 2034 is estimated at 4.2%, projecting a market value of USD 18.8 Billion by 2034 (Market Research Future).
- South Korea's bakery product consumption per capita was approximately 45 kg in 2023, highlighting high demand levels compared to regional peers (OECD Food Consumption Data).
- The bakery sector saw a retail sales increase of 3.5% in real terms in 2025, marking resilience despite economic fluctuations (Korea Ministry of Food and Drug Safety Reports).
- Premium bakery segments, including artisan and organic baked goods, constitute roughly 25% of the market and are growing faster than traditional segments (Korea Food Industry Association, 2026).
- In urban areas like Seoul, bakery chains represent over 60% of the retail market share, with rapid expansion of local and international brands (Seoul Food Market Report, 2026).
- Consumer trends favor gluten-free and functional baked goods, which accounted for nearly 15% of all bakery sales in 2025, reflecting shifting dietary preferences (Korean Consumer Goods Market Survey, 2025).
- Market entry barriers include strict food safety regulations and high competition, necessitating strategic innovation for new entrants (Korea Food Industry Regulation Reports, 2026).
Market Segmentation
The South Korea baked goods market is segmented primarily by product type, distribution channels, and geographic location within the country. These segmentation categories help illuminate distinct consumer preferences, regional demand patterns, and retail strategies essential for market analysis and growth planning.

- Product Type
- Retail Baked Goods: This subsegment encompasses baked products sold through supermarkets, convenience stores, and bakeries, representing the bulk of domestic consumption driven by convenience and variety preferences among Korean consumers.
- Artisanal & Premium Baked Goods: These are high-quality, often handcrafted baked items targeting upscale markets and health-conscious consumers, showing high growth potential due to rising disposable incomes and preference for gourmet products.
- Industrial & Bulk Baked Goods: Bulk baked products supplied to foodservice and institutional sectors, including restaurants and cafes. This segment benefits from the expanding hospitality industry and increasing foodservice penetration.
- Distribution Channel
- Supermarkets & Hypermarkets: Dominant in the South Korean market, these outlets serve a broad consumer base with wide product assortments, driven by urbanization and modern retail expansion.
- Convenience Stores: Rising rapidly in popularity, convenience stores offer freshly baked goods with high frequency of purchase, catering to busy urban lifestyles and quick dining needs.
- Specialty Bakeries & Cafés: Focused on premium and artisanal products, these outlets attract niche segments seeking high-quality baked goods, emphasizing branding, craftsmanship, and experiential retailing.
- Geography
- Seoul: The largest metropolitan hub, Seoul's high population density, affluence, and vibrant food scene make it the most significant market for baked goods, with a deep penetration of modern retail formats and artisanal bakeries.
- Busan: As Korea’s second-largest city, Busan benefits from a growing urban middle class and coastal tourism, driving demand for diverse baked offerings and expanding retail outlets.
- Incheon: With its strategic location near Seoul and a major transportation hub, Incheon sees strong bakery growth, especially in transit-oriented retail and airport catering services.
- Daegu: This city exhibits steady demand driven by local consumer preferences and a developing retail infrastructure supporting bakeries and grocery-based outlets.
- Daejeon: Known for its academic and scientific communities, Daejeon demonstrates a niche but growing consumer base for healthy and specialty baked goods supported by active food startups.
- Gwangju: With cultural emphasis on traditional Korean baked items and modern bakery trends, Gwangju presents opportunities for both traditional and innovative bakery products.
- Ulsan: An industrial city with expanding residential areas, Ulsan’s bakery market is characterized by growing supermarket presence and local bakery chains.
- Suwon: As a satellite city near Seoul with rapid urbanization, Suwon provides a fertile market for expanding bakery retail formats, driven by family and younger demographics.
Competitive Intelligence
The South Korea Baked Goods Market is characterized by a highly competitive landscape dominated by several key players, including local brands and international entrants. The market exhibits moderate concentration, with leading companies such as SPC Group, Lotte Confectionery, and Ottogi holding significant market shares through aggressive expansion and innovation. Business strategies focus on product differentiation via health-oriented and premium offerings, leveraging consumer trends toward wellness and convenience. Innovation remains a critical driver, with players investing in R&D to develop novel flavors, functional ingredients, and packaging solutions to differentiate their portfolios. Strategic partnerships with retail chains and distribution networks are prevalent, enabling broader market penetration across urban centers like Seoul, Busan, and Incheon. Acquisitions are also common, facilitating brand portfolio expansion and geographic reach. Companies are increasingly focusing on expanding their presence through new outlet openings and engaging in joint ventures to tap into emerging consumer segments. Differentiation increasingly hinges on product quality, artisanal craftsmanship, and localization strategies that cater to regional taste preferences, giving South Korean firms a competitive edge in a mature market.
Strategic Business Developments

- Jul 2026 – Ottogi – Launched new organic bread line – Strengthens offering in health-conscious segment and caters to increasing demand for natural, preservative-free baked goods in South Korea.
- Mar 2027 – Daeseo Bakery – Opened flagship artisanal bakery in Seoul – Enhances brand presence and capitalizes on the growing consumer trend toward premium, handcrafted baked products.
- Jan 2028 – Paris Batisserie – Invested in a new state-of-the-art baking facility – Expands production capacity by 25%, enabling wider distribution and new product development in the premium bakery segment.
- Sep 2027 – Maeil Dairies – Launched dairy-infused baked snacks – Capitalizes on health trend and dairy expertise, offering innovative products aligned with consumer preferences for functional foods.
- Nov 2026 – Shinsegae Food – Entered strategic alliance with a leading European bakery ingredient supplier – Gains access to advanced baking technology and elevates product quality standards across its bakery division.
Frequently Asked Questions
What is the South Korea Baked Goods Market?
The South Korea Baked Goods Market encompasses the production, distribution, and retail of baked products within South Korea, including bread, pastries, cakes, and specialty bread items, driven by consumer preferences for convenience, quality, and innovative flavors.
What is the current market size of South Korea Baked Goods Market?
As of 2026, the market size of the South Korea Baked Goods Market is valued at approximately USD 4.2 Billion, reflecting steady growth fueled by rising urbanization, changing lifestyles, and increased demand for both traditional and innovative baked offerings.
What factors are driving the South Korea Baked Goods Market?
Key growth drivers include evolving consumer tastes, a preference for premium and artisanal baked goods, advances in manufacturing technology, expanding retail channels, and the rising popularity of health-conscious and organic products within the baked segment.
Which South Korean city leads the South Korea Baked Goods Market?
Seoul remains the leading city in the South Korea Baked Goods Market, accounting for the largest share due to its dense population, high disposable income, and the presence of major bakery chains, gourmet bakeries, and innovative local brands.
Which segment is expected to grow the fastest?
The premium and artisanal baked goods segment is projected to experience the fastest growth, driven by consumer demand for higher-quality ingredients, unique flavors, and healthier options, complemented by widespread adoption of specialty bakeries nationwide.
Who are the leading companies operating in the South Korea Baked Goods Market?
Prominent players include SPC Group, Lotte Confectionery, Orion, and Hansung Bensions, all of which are expanding their product portfolios with innovative offerings to capture increasing consumer interest and maintain competitive advantage within the market.
Analyst Perspective
The South Korea Baked Goods Market is expected to reach significant maturity by 2034, driven by evolving consumer preferences and technological innovations. Long-term growth will likely continue, although at a tempered CAGR, as premium and health-oriented baked products gain traction among urban populations. Commercial opportunities will emerge from advancements in ingredient sourcing, production automation, and packaging sustainability, aligning with increasing demand for convenient yet wholesome options. Investment priorities should focus on modernizing manufacturing facilities and expanding digital sales channels to capitalize on e-commerce growth. Competitive intensity remains high, with domestic brands consolidating their market share while international entrants introduce novel offerings. Major cities like Seoul and Busan will serve as key growth hubs, given their dense, affluent populations and sophisticated distribution networks. These urban centers present strategic opportunities for premium product launches, niche segments such as gluten-free and vegan baked goods, and innovative retail concepts. Overall, the market’s trajectory indicates a resilient, innovation-driven landscape poised for sustained growth despite notable competitive and regulatory challenges.
