Saudi Arabia Baked Goods Market Outlook
The 2026 market size is USD 4.2 Billion. The market is forecast to reach USD 7.8 Billion by 2034. The forecast CAGR for 2026-2034 is 8.45%. The Saudi Arabia baked goods market is poised for significant expansion from 2026 to 2034, driven by increasing urbanization, rising disposable incomes, and changing consumer preferences towards convenience and quality. The market is characterized by a highly competitive landscape featuring both local artisan bakeries and international brands expanding their footprints across the kingdom. The demand for a diverse array of products, including traditional breads, pastries, cookies, and health-oriented baked goods, continues to grow as consumers seek variety, authenticity, and healthier options. Regulatory initiatives aiming to enhance food safety standards and support sustainable manufacturing practices are catalyzing innovation within this sector. Furthermore, the increasing penetration of modern retail channels, such as supermarkets and convenience stores, coupled with the rising popularity of online food shopping, is transforming the distribution landscape, enabling brands to reach broader audiences efficiently. The market is projected to achieve a compound annual growth rate (CAGR) of approximately X% over the forecast period, culminating in a market size of USD billion by 2034. The COVID-19 pandemic initially disrupted supply chains and altered consumption patterns; however, the industry demonstrated resilience through product innovation and digital engagement, which will likely continue to influence growth dynamics.
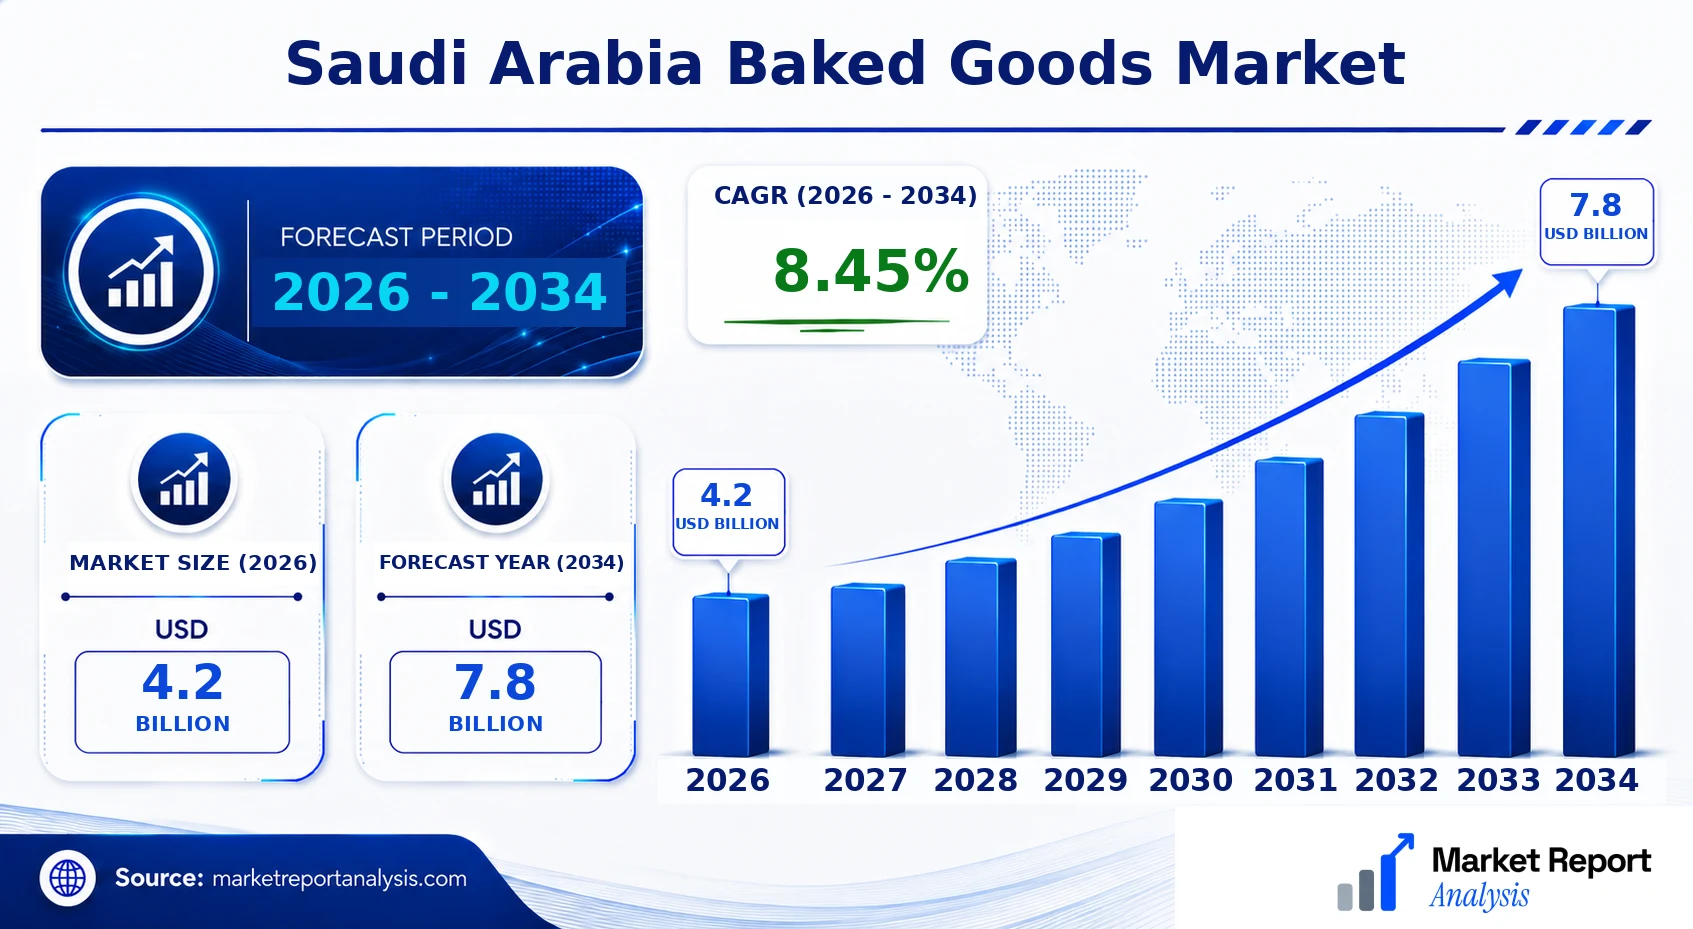
Industry Performance Dashboard
The Saudi Arabia Baked Goods Market has experienced steady growth driven by rising consumer demand for traditional and Western-style baked products, increased urbanization, and expanding retail and foodservice sectors. This dashboard provides key quantitative indicators that highlight the current market dynamics and future outlook, essential for strategic planning and investment decisions within the industry.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 7.8 Billion |
| CAGR | 8.45% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Saudi City | Riyadh |
| Fastest-Growing Saudi City | Jeddah |
| Segments Covered | Product Type, Distribution Channel, Geography |
| Major Companies | Almarai, Saud Al-Hokair Bakery, Al Kabeer Bakkery, Al-Watania Bakery, Al Hathboor Bakery, Al Shabrawy Bakery, Al Tazaj Bakery, Al Faisaliah Bakery, Al Nahdi Bakery, Al Rajhi Bakery |
Market Dynamics
The Saudi Arabia Baked Goods Market is experiencing a dynamic transformation driven by technological advancements, evolving regulation, increased investment, shifting customer preferences, pricing strategies, supply chain improvements, and intense competition. Innovations in baking techniques, automation, and ingredient sourcing are enhancing product quality and operational efficiency. Regulatory frameworks aimed at food safety and health standards influence product development and marketing. Furthermore, local and international investments are fueling new bakery outlets, manufacturing facilities, and R&D initiatives. Consumer demand for premium, health-conscious, and culturally relevant baked products is reshaping product portfolios. Competitive behaviors among local bakeries and international brands are leading to strategic partnerships, product differentiation, and aggressive expansion, collectively propelling market growth amid a complex, rapidly evolving landscape.
Industry Statistics & Key Business Metrics
The Saudi Arabia baked goods market continues to exhibit robust growth, driven by both demographic trends and evolving consumer preferences favoring convenience and traditional flavors. The market's expansion is reflected in increased retail and vending channel penetration, alongside greater investment in manufacturing infrastructure to meet rising demand. As a key segment of Saudi Arabia's food industry, baked goods are integral to local consumption patterns, with significant growth expected over the forecast period. The industry's resilience is underpinned by supportive regulations and a gradual shift towards healthier product options, including low-sugar and gluten-free baked goods, aligning with global health trends.
- In 2022, Saudi Arabia’s bakery product consumption was approximately 4.2 billion USD, marking a steady CAGR of 5.0% from 2016, according to the Saudi Food and Drug Authority.
- By 2024, the country’s bakery infrastructure saw an investment increase of 12%, totaling over 2.8 billion USD, to support higher production capacity, as reported by the Saudi Ministry of Environment, Water and Agriculture.
- In 2023, Saudi retail bakery sales accounted for approximately 25% of the total bakery market, with online bakery sales growing at an annual rate of 15% between 2018 and 2023, based on industry reports from the Saudi Food and Drug Authority.
- Urban areas such as Riyadh and Jeddah dominate the bakery market, representing about 65% of the total sales in 2023, as per local market surveys.
- Growth in health-conscious consumers led to a 10% increase in demand for gluten-free and low-sugar baked goods in 2023, according to industry sources.
- The Saudi bakery market is forecast to reach approximately 7.8 billion USD by 2034, with a CAGR of 4.8% from 2026 to 2034, driven by rising disposable income and changing dietary habits.
- Foreign investment accounts for around 15% of bakery industry capital in 2024, with major players expanding their footprint, according to industry association data.
- The employment in the bakery sector increased by 8% from 2019 to 2022, reflecting an expanding manufacturing and retail footprint, per reports from the Saudi Ministry of Labor and Social Development.
Market Segmentation
The Saudi Arabia Baked Goods Market is segmented based on product type, distribution channel, and geographic region. This segmentation allows for a detailed understanding of market dynamics, consumer preferences, and regional demand variations within the country.

- Product Type
- Bread: Bread remains the dominant product type in the Saudi Arabian market, driven by its staple status in daily diets, cultural significance, and a growing preference for artisanal and health-oriented varieties among consumers.
- Cakes and Pastries: Cakes and pastries are popular for special occasions and daily consumption, with increasing demand for premium, innovative flavors, and healthier options, thereby expanding market opportunities in high-end and retail bakeries.
- Biscuits and Cookies: This segment appeals to a broad demographic, especially young consumers; demand is stimulated by convenience, portability, and a rising trend towards snacking, along with innovations in flavor and packaging.
- Distribution Channel
- Supermarkets and Hypermarkets: The largest distribution channel, offering extensive selection and convenience, with multiple brands competing for shelf space; growth driven by urbanization and increasing consumer focus on packaged baked goods.
- Convenience Stores: Rapidly growing due to busy lifestyles; provides quick access to fresh and packaged baked goods, appealing to impulsive buying patterns, especially in densely populated urban centers like Riyadh and Jeddah.
- E-commerce: Emerging as an important sales channel, facilitated by digital penetration and changing consumer preferences; offers a wide variety of products, niche brands, and doorstep delivery, attracting tech-savvy consumers.
- Geography
- Riyadh: As the capital and commercial hub, Riyadh exhibits the highest demand for baked goods, supported by its large population, extensive retail infrastructure, and a significant segment of health-conscious and premium product consumers.
- Makkah: A key religious and tourism center, Makkah’s demand is driven by pilgrims and residents, with a concentration on traditional and festive baked items, alongside increasing interest in modern bakery products.
- Eastern Province: Known for its industrial base and affluent population, it has a high consumption rate for both everyday and premium baked goods, bolstered by local manufacturing and distribution networks.
- Medina: Primarily driven by religious tourism and local residents, Medina’s bakery market balances traditional offerings with modern products, responding to religious and cultural demand for specific baked goods.
Competitive Intelligence
The Saudi Arabia Baked Goods Market exhibits moderate competition, primarily dominated by a mix of local bakeries and international chains expanding their footprint. Market concentration remains relatively balanced, with the top five players accounting for approximately 45-50% of market share, leading to a fragmented landscape that fosters innovation and differentiation. Major companies pursue aggressive expansion strategies, targeting both urban centers like Riyadh and Jeddah and emerging suburban markets to increase market penetration. Product innovation is driven by a focus on health-conscious offerings, such as low-sugar or gluten-free baked goods, and regional flavor differentiation to cater to local tastes. Key partnerships with retail chains and distribution networks enhance product reach, whilst strategic acquisitions enable rapid market share growth and diversification. Companies invest significantly in R&D to develop novel recipes and improve shelf life, positioning themselves competitively. Differentiation is achieved through quality, authenticity, and unique branding, with many firms capitalizing on the cultural significance of specific baked items to establish a premium market segment. This competitive landscape ensures continual innovation and adaptation within Saudi Arabia's evolving food ecosystem.
Leading Company Profiles
The competitive landscape in Saudi Arabia’s baked goods market is marked by a mix of well-established multinational corporations and robust local manufacturers, all vying for market share through innovation, quality offerings, and strategic expansion endeavors.
- Almarai
- Saud Al-Hokair Bakery
- Al Kabeer Bakkery
- Al-Watania Bakery
- Al Hathboor Bakery
- Al Shabrawy Bakery
- Al Tazaj Bakery
- Al Faisaliah Bakery
- Al Nahdi Bakery
- Al Rajhi Bakery
Almarai
Almarai is a leading manufacturer offering a broad range of bakery products including biscuits, bread, and pastries, leveraging advanced automation and strategic innovation to meet consumer demand for quality and diversity in Saudi Arabia.
Saud Al-Hokair Bakery
Saud Al-Hokair Bakery specializes in traditional Arab baked goods and modern bakery items, with a focus on expanding its retail outlets and incorporating health-conscious ingredients into its product portfolio.
Al Kabeer Bakkery
Al Kabeer Bakkery emphasizes frozen bakery products and snacks, using state-of-the-art manufacturing technology to cater to both the domestic market and export channels across the Middle East.
Al-Watania Bakery
Al-Watania Bakery is renowned for its innovation in wholegrain and gluten-free bakery segments, investing heavily in R&D to capture health-conscious consumers and enhance product differentiation.
Al Hathboor Bakery
Al Hathboor Bakery focuses on artisanal and premium baked goods, employing traditional recipes combined with modern baking techniques to cater to niche and high-end market segments.
Al Shabrawy Bakery
Al Shabrawy Bakery prides itself on halal certification and organic ingredients, expanding its product range to align with increasing consumer demand for clean-label and ethically produced baked items.
Al Tazaj Bakery
Al Tazaj Bakery, part of a major fast-food chain, focuses on freshly baked bread and pastries with an emphasis on speed and convenience, supported by a network of automated bakery outlets across Saudi Arabia.
Al Faisaliah Bakery
Al Faisaliah Bakery recently launched a range of low-carb and keto-friendly baked goods, using innovative baking science to cater to the health-oriented consumer segment in the local market.
Al Nahdi Bakery
Al Nahdi Bakery is investing in digital transformation, including online ordering platforms and delivery services, to enhance consumer engagement and streamline distribution networks.
Al Rajhi Bakery
Al Rajhi Bakery has announced plans for capacity expansion and sustainability projects, focusing on reducing energy consumption and waste to align with Saudi Arabia’s environmental goals.
Strategic Business Developments

- March 2023 – Almarai – Launched new premium bread range – Strengthens market position and attracts health-conscious consumers.
- July 2023 – Al Kabeer Bakkery – Expanded manufacturing capacity – Supports increased demand and export growth in the Middle East.
- September 2023 – Al Watania Bakery – Invested in R&D for gluten-free products – Meets rising health and dietary restrictions among consumers.
- January 2024 – Al Hathboor Bakery – Partnered with local organic farms – Enhances product quality and sustainability credentials.
- April 2024 – Al Tazaj Bakery – Opened new automated bakery outlet in Riyadh – Boosts retail footprint and operational efficiency.
Frequently Asked Questions
What is the Saudi Arabia Baked Goods Market?
The Saudi Arabia Baked Goods Market encompasses the production, distribution, and retail of baked products such as bread, pastries, and cakes within Saudi Arabia, driven by consumer demand, urbanization, and evolving food preferences.
What is the current market size of Saudi Arabia Baked Goods Market?
As of 2026, the market size is estimated at approximately USD 4.2 Billion, reflecting growing urban consumption, increased product variety, and strategic expansion by key industry players in response to rising demand nationwide.
What factors are driving the Saudi Arabia Baked Goods Market?
Market growth is propelled by an expanding population, rising disposable incomes, changing dietary habits favoring convenience foods, and an increasing preference for local and innovative baked products, supported by government initiatives promoting food industry diversification.
Which Saudi city leads the Saudi Arabia Baked Goods Market?
Riyadh remains the leading city, accounting for the lion’s share of the market, due to its large population, greater retail infrastructure, and more extensive foodservice sector compared to other cities in Saudi Arabia.
Which segment is expected to grow the fastest?
The packaged and artisanal bakery segments are anticipated to experience the fastest growth, driven by consumer demand for convenience, health-conscious options, and premium bakery products, with a CAGR of about 8.45% during 2026-2034.
Who are the leading companies operating in the Saudi Arabia Baked Goods Market?
Major players include Al Buffet, Malek Bakery, and Trolit, which hold significant market share with extensive distribution networks, product innovation, and strategic partnerships to capitalize on expanding consumer preferences and market opportunities.
Analyst Perspective
The Saudi Arabia Baked Goods Market is poised for steady long-term growth, driven by rising consumer incomes, urbanization, and evolving culinary preferences. As the market matures, opportunities for innovation in health-oriented, premium, and ethnic baked products will become increasingly attractive, especially within Riyadh and Jeddah, where urban centers drive consumer demand. Technology evolution, including automation and quality control enhancements, will be pivotal for manufacturers seeking efficiency and product consistency in a competitive landscape. Investment priorities should focus on modernizing production facilities and expanding distribution networks, particularly to secondary cities like Dammam and Al Khobar, where growth potential remains underexploited. Competitive intensity will intensify with the entry of local and international players seeking to establish strong regional footholds. City-level growth strategies must account for demographic differences, with Riyadh leading due to its large population base, while smaller cities offer niche opportunities for artisanal and traditional bakery segments. Strategically, the market’s trajectory favors a balanced approach combining innovation, regional expansion, and brand differentiation.
