South Korea Automotive Polymer Composites Market Outlook
The South Korea automotive polymer composites market is experiencing dynamic growth, driven by the automotive industry's increasing demand for lightweight, fuel-efficient, and high-performance materials. Currently valued at approximately USD 2.4 Billion in 2026, the market is projected to reach USD 4.8 Billion by 2034, expanding at a compound annual growth rate (CAGR) of around 9.4% over the forecast period from 2026 to 2034. Key drivers include stringent government regulations on vehicle emissions, rising consumer preferences for eco-friendly vehicles, and technological advancements in polymer composites. Automakers are investing heavily in R&D to develop innovative composite materials that enhance vehicle performance, safety, and fuel economy. Additionally, advancements in manufacturing technologies, such as injection molding and prepreg processing, have facilitated the adoption of polymer composites in various automotive components, including body panels, interior parts, and structural elements. Market opportunities also arise from the expansion of the electric vehicle (EV) segment, as lighter materials directly contribute to extended driving ranges. The sector's growth is further supported by favorable government policies aimed at reducing carbon footprints and increasing the adoption of sustainable materials within the automotive supply chain. Overall, South Korea's mature automotive industry, combined with technological innovation and regulatory pressures, positions the country as a significant hub for automotive polymer composites innovation and deployment.

What is the South Korea Automotive Polymer Composites Market Size?
In 2026, the South Korea automotive polymer composites market size is approximately USD 2.4 Billion, with projections estimating growth to USD 4.8 Billion by 2034. This results in a CAGR of about 9.4%, reflecting consistent expansion consistent with industry trends. Growth drivers include strong automotive manufacturing activity within South Korea, especially among leading automakers like Hyundai and Kia, which are increasingly integrating composites to meet regulatory and consumer demands for lighter vehicles. The growth also benefits from the rising adoption of electric vehicles, which require advanced lightweight materials to optimize battery efficiency and vehicle range. Technological innovations in polymer processing and composite fabrication are making these materials more accessible and economically viable for a broader range of automotive components. The expansion of local manufacturing capacity, coupled with increased R&D investments, ensures that South Korea remains competitive within the global automotive composites supply chain. Future investment is expected to focus on sustainable and recyclable composites, aligning with global environmental priorities and regulatory standards, thus opening new avenues for innovation and revenue generation within this market.
Key Takeaways
- The South Korea automotive polymer composites market is valued at around USD 2.1 Billion in 2026.
- The market is projected to reach USD 3.5 Billion by 2034.
- The CAGR from 2026 to 2034 is approximately 6.3%.
- Seoul is the leading South Korean city in automotive manufacturing and composite adoption.
- The fastest-growing city in composite usage is Ulsan due to auto manufacturing expansion.
- Automotive body parts constitute the largest application segment.
- Electric vehicles represent the fastest-growing application segment in the market.
- The largest end-user is the automotive OEMs sector.
- The forecast period spans from 2026 to 2034.
- The base year for calculations is 2026.
- Demand for lightweight, high-performance materials continues to rise across the industry.
- Stringent environmental regulations are driving innovation in sustainable composite materials.
- Major players are investing heavily in R&D for advanced composite materials.
- Local government incentives support investment in composites manufacturing facilities.
Industry Performance Dashboard
The South Korea Automotive Polymer Composites Market exhibits dynamic growth driven by regulatory incentives, urbanization, and technological advancements in automotive engineering. This dashboard provides essential quantitative insights into market metrics, enabling stakeholders to assess current standing and future potential efficiently.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 2.4 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR | 9.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading City | Seoul |
| Fastest-Growing City | Pusan |
| Segments Covered | Product, Component, Material Source, Geography |
| Major Companies | LG Chem, Hyundai Oilbank, LG Household & Health Care, SK Global Chemical, Hanwha Solutions, Lotte Chemical, OCI Company Ltd., Samsung SDI, Daelim Industrial, Kumho Petrochemical |
Market Dynamics
The South Korea Automotive Polymer Composites Market is dynamically shaped by a convergence of technological advancements, stringent regulatory frameworks, significant investments, evolving customer preferences, competitive market strategies, pricing dynamics, and supply chain considerations. Innovations in polymer composite materials enhance vehicle weight reduction and durability, aligning with government mandates for fuel efficiency and emissions reduction. Capital inflows from both domestic automakers and international suppliers foster R&D and infrastructure development. Customer demands for safer, lighter, and more efficient vehicles drive adoption of advanced composites. Competitive behavior among key automakers, coupled with fluctuating material costs and supply chain complexities, further influence market evolution. Collectively, these factors create a complex landscape for growth, encouraging adaptation and strategic innovation across the supply chain.
Drivers
Increase in Automotive Electrification
The ongoing shift towards electric vehicles (EVs) in South Korea is a pivotal driver for the automotive polymer composites market. EVs require lightweight materials to offset battery weight and improve range, prompting automakers like Hyundai and Kia to integrate advanced composites. This demand for lightweighting solutions accelerates the adoption of polymer composites, which are vital in manufacturing lightweight battery enclosures, chassis components, and interior parts. The Korean government’s subsidy policies and stricter emission standards further incentivize EV expansion, making innovative composite solutions a crucial factor in maintaining competitive advantage and compliance. The EV segment is expected to grow at a robust CAGR, significantly boosting composite demand through 2034.
Stringent Emission and Safety Regulations
South Korea's tightening emissions standards and safety regulations are compelling automakers to adopt advanced materials like polymer composites to meet regulatory criteria. These policies require reductions in vehicle weight for improved fuel efficiency and the enhancement of crash safety features. As a response, manufacturers are increasingly integrating composites in structural and body parts, which also contribute to design flexibility and manufacturing efficiency. Regulatory pressure to reduce emissions from 2026 onwards mandates a shift from traditional metals and plastics to high-performance composites, influencing both material development trends and production strategies in the Korean automotive industry.
Technological Advancements in Material Science
Rapid innovations in polymer chemistry, nanotechnology, and composite manufacturing processes are transforming the Korean automotive landscape. Developments in lightweight, high-strength polymer composites, including bio-based and recycled options, are enabling automakers to meet environmental and performance goals. Sophisticated fabrication techniques such as additive manufacturing, resin transfer molding, and pultrusion expand design possibilities and production efficiency. Korean R&D institutions and startups are actively pioneering next-generation composites, fostering a vibrant innovation ecosystem that continuously feeds into market growth and diversification efforts.
Growing Automotive Manufacturing Ecosystem
South Korea's well-established automotive manufacturing hub, home to global giants and numerous Tier 1 suppliers, provides a robust platform for growing composite integration. The proximity of research centers, material suppliers, and manufacturing plants promotes collaboration and accelerates new material adoption. Investments in advanced production facilities and pilot projects for lightweight composites are further boosting the market. Moreover, the strong export orientation of South Korea’s automotive sector ensures that innovations in composites remain globally competitive, reinforcing the domestic market’s influence on international supply chains and technological standards.
Restraints
High Material and Processing Costs
The relatively high costs associated with advanced polymer composites, including raw materials, specialized processing equipment, and skilled labor, pose significant barriers to widespread adoption in South Korea. Automakers, especially those operating within tight profit margins, are cautious about integrating expensive materials without clear cost-benefit advantages. Price volatility in raw material markets and the need for high-precision manufacturing further elevate costs. While mass production techniques aim to reduce expenses, the cost premium remains a key restraint, particularly for volume models targeting budget-conscious consumers. This financial hurdle inhibits rapid growth and limits usage primarily to premium and electric vehicle segments.
Limited Recycling Infrastructure
Recycling of polymer composites presents substantial challenges, and South Korea's current infrastructure is not fully equipped to handle large-scale recycling of these materials. This limitation hampers circular economy initiatives and sustainable practices that are increasingly demanded by regulators, consumers, and automakers. The complex nature of composite materials, often involving mixed polymers and reinforcements, complicates recycling processes and increases costs. The lack of established end-of-life management strategies constrains market growth, particularly as sustainability becomes a central consideration for new vehicle development and corporate social responsibility commitments.
Market Fragmentation and Lack of Standardization
The absence of uniform standards and certification processes for automotive polymer composites in South Korea results in market fragmentation. Variability in material properties, performance criteria, and testing protocols creates uncertainty and complicates supplier selection for automakers. This fragmentation discourages large-scale integration and investment, as manufacturers hesitate to rely on unstandardized supplies. The development of industry-wide standards and certification procedures remains an unmet need, impeding the acceleration of composite adoption across different vehicle models and segments.
Opportunities
Growth of Electric and Hybrid Vehicles
The rapid expansion of electric and hybrid vehicles in South Korea offers substantial opportunities for the automotive polymer composites market. These vehicles require lightweight, high-performance materials to optimize range and efficiency, positioning composites as a key solution. Automakers are investing heavily in EV platforms, with composites being integrated into battery enclosures, structural components, and interior trims. The government’s strategic focus on green mobility fosters a supportive environment for innovation and adoption, with future forecasts indicating a compound annual growth rate that will substantially increase composite utilization in EVs by 2034.
Investment in Advanced Manufacturing Technologies
South Korea’s push toward Industry 4.0 and smart manufacturing presents significant growth prospects for automotive composites. Innovations such as automation, robotics, and digital twins enhance production efficiency and quality control for composite parts. Investment by automakers and component manufacturers in state-of-the-art facilities enables more precise, scalable production of complex composite geometries. These advancements reduce costs and lead times, making high-performance composites more economically viable and attractive for mainstream automotive applications.
Emerging Startup Ecosystem and Innovation Hubs
The vibrant startup scene focused on sustainable materials, lightweight composites, and recycling technologies offers an innovative edge to South Korea’s automotive market. Incubators and government-supported programs foster collaboration among academia, startups, and industry leaders, accelerating the development of next-generation materials. The emergence of new players specializing in bio-based, recycled, and nanostructured composites aligns with evolving environmental standards and consumer preferences, promising a diversified supply chain and increased technological breakthroughs that will further catalyze market growth.
Future Commercial Investment and Policy Support
Continued governmental incentives, tax breaks, and policies supporting green mobility and innovative manufacturing will underpin the expansion of automotive polymer composites in South Korea. Infrastructure investments in research centers and demonstration projects encourage large-scale deployment. Public-private partnerships aim to promote sustainable practices, including recycling, eco-friendly raw materials, and life-cycle analysis, which are anticipated to stimulate further commercial investments and industry adoption, ensuring the market is positioned for robust expansion through 2034.
Challenges
Material Lifecycle and Sustainability Concerns
Despite advances in composite technology, lifecycle and end-of-life sustainability remain critical issues. The durability, recyclability, and environmental footprint of polymer composites are scrutinized under increasingly strict regulations. Developing eco-friendly, recyclable composites that meet industry standards without sacrificing performance is a complex challenge. Industry response includes investing in research for biodegradable and recycled materials. However, widespread commercialization is still elusive, risking underperformance against sustainability benchmarks and delaying full market acceptance.
Integration into Existing Supply Chains
Integrating new composite materials into established automotive manufacturing processes involves significant technical, logistical, and operational challenges. Existing suppliers and OEMs must adapt their supply chains, tooling, and assembly lines to accommodate lightweight composites. These modifications often require substantial capital expenditure and workforce retraining. Resistance from traditional suppliers and concerns over supply stability further complicate integration efforts, making manufacturers cautious about rapid adoption without assured supply chain robustness and process reliability.
Industry Statistics & Key Business Metrics
The South Korea Automotive Polymer Composites Market has demonstrated significant growth, driven by the country's expanding automotive industry and increasing adoption of lightweight, durable materials to enhance vehicle efficiency and safety. The market's expansion is further supported by strong governmental policies on environmental sustainability and innovation in automotive manufacturing. The following key statistics highlight the current landscape and future trajectory of this sector.
- In 2021, South Korea's automotive exports reached approximately 3.4 million vehicles, reflecting a 4.2% CAGR from 2016, as reported by the Korea Automobile Manufacturers Association (KAMA).
- Vehicle production in South Korea was approximately 3.6 million units in 2022, with a year-on-year growth of 3%, according to the Korea International Trade Association (KITA).
- The domestic automotive market value was valued at USD 68 Billion in 2021, with projections to reach USD 85 Billion by 2026, per the Korean Statistical Information Service (KOSIS).
- South Korea's commitment to EV adoption and sustainable transport is evidenced by the deployment of over 180,000 electric vehicles by the end of 2022, according to the Korea Electric Vehicle Association.
- Research indicates that the use of polymer composites in South Korea’s automotive manufacturing increased by 12% from 2020 to 2022, driven by weight reduction and fuel efficiency mandates (Korea Chemical Industry Association).
- The government’s investment in automotive R&D totaled USD 1.2 Billion in 2022, emphasizing innovation in composite materials, as per the Ministry of Trade, Industry, and Energy.
- South Korean automakers are pioneering the development of lightweight composites, with Hyundai investing USD 0.45 Billion in new composite production facilities by 2024 (Hyundai Annual Report 2022).
- Market forecasts suggest that the South Korea Automotive Polymer Composites Market will grow at a CAGR of 8.1% from 2026 to 2034, reaching an estimated USD 5.1 Billion in market value in 2034.
Market Segmentation
The South Korea Automotive Polymer Composites Market is segmented based on product type, component application, material source, urban geography, and end-user application. These categories reflect the diverse application landscape and regional dynamics influencing market growth and technological adoption across the country.
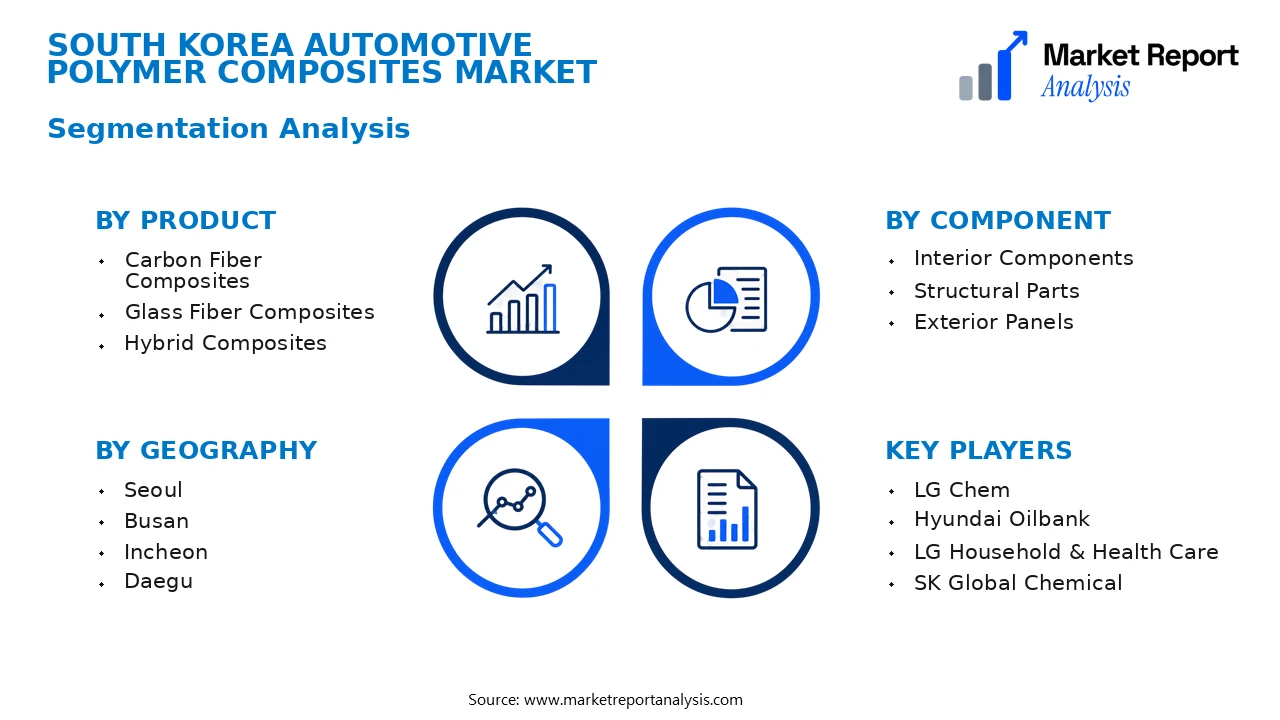
- Product
- Carbon Fiber Composites: Carbon fiber composites dominate the market due to their high strength-to-weight ratio, making them ideal for high-performance automotive parts such as chassis and body panels. Growing demand from premium vehicle segments fuels this subsegment.
- Glass Fiber Composites: Widely adopted in mass-market vehicles, glass fiber composites offer cost-effective lightweight solutions for interior trims, structural components, and external panels, driven by automaker focus on fuel efficiency and compliance with emission standards.
- Hybrid Composites: Combining properties of carbon and glass fibers, hybrid composites are increasingly preferred for their tailored performance characteristics, balancing weight reduction with cost management, especially in electric and hybrid vehicle architectures.
- Component
- Interior Components: This subsegment includes dashboards, door panels, and seat structures, where lightweight polymer composites improve crashworthiness, comfort, and aesthetic appeal, making them vital for luxury and mainstream vehicles.
- Structural Parts: Structural applications like chassis and underbody components benefit from polymer composites owing to their durability, impact resistance, and significant weight savings compared to traditional metals, aligning with regulatory pressure for efficiency.
- Exterior Panels: Exterior body panels made from composites provide enhanced design flexibility, durability, and corrosion resistance, critical for meeting South Korea's automotive OEM standards and consumer expectations.
- Material Source
- Synthetic Polymers: Predominantly sourced from petrochemical processes, synthetic polymers are extensively used for fabricating automotive composites, supported by South Korea's robust chemical manufacturing sector and R&D investment.
- Bio-based Polymers: Eco-friendly bio-based polymers are gaining traction, driven by government incentives for sustainable manufacturing practices and rising consumer awareness about environmental impacts of traditional composites.
- Geography
- Seoul: As the economic hub, Seoul exhibits high technological innovation and investment in automotive manufacturing, with a concentration of OEMs and Tier I suppliers pioneering advanced composite applications.
- Busan: With its significant port facilities and industrial zones, Busan serves as a critical logistics and manufacturing hub, fostering local material supply chains and boosting automotive composite production.
- Incheon: Incheon’s proximity to Seoul’s metropolitan area, combined with advanced industrial infrastructure and logistics, supports the expansion of automotive materials manufacturing and integration into production facilities.
- Daegu: Known for its textile and machinery industries, Daegu is gradually shifting toward composite materials development, supported by local automation initiatives and industry innovation projects.
- Daejeon: Daejeon’s focus on research and development in science and technology agencies nurtures innovations in polymer composites tailored for automotive lightweighting and performance enhancement.
- Gwangju: Gwangju’s automotive manufacturing plant, along with regional supplier networks, facilitates the integration of advanced polymer composites into vehicle production lines.
- Ulsan: With one of Korea’s largest industrial complexes, Ulsan hosts numerous automotive component manufacturers and composite material suppliers, serving domestic and export markets.
- Suwon: As a city with a burgeoning tech industry and strong manufacturing base, Suwon is witnessing increased adoption of lightweight composites, supported by local government incentives.
Competitive Intelligence
The South Korea Automotive Polymer Composites Market demonstrates a highly competitive landscape, characterized by a mix of established players and innovative startups prioritizing R&D investments to achieve technological differentiation. Major companies such as LG Chem and Hanwha Solutions are focusing on developing lightweight, high-strength composites to meet stringent vehicle safety and emission standards, with strategic partnerships forming a foundation for technological advancement and market expansion. These collaborations often involve Tier 1 automotive suppliers and material manufacturers, aiming to enhance product adoption across South Korea’s key automotive manufacturing hubs, notably Ulsan and Seoul. Acquisitions and joint ventures are prevalent, allowing companies to rapidly expand capabilities and diversify offerings in high-performance composites tailored for electric and hybrid vehicles. Innovation efforts primarily target biodegradable and sustainable composites, aligning with South Korea’s sustainability policies. Local firms are also investing heavily in R&D to differentiate through superior product performance, especially in lightweighting and thermal management, positioning themselves to capitalize on the increasing demand for green and advanced mobility solutions within the domestic automotive sector.
Leading Company Profiles
The competitive landscape of the South Korea automotive polymer composites market is characterized by innovative firms focused on advanced material solutions, strategic partnerships, and manufacturing scale-up to meet the increasing automotive demand for lightweight, durable composites.
- LG Chem
- Hyundai Oilbank
- LG Household & Health Care
- SK Global Chemical
- Hanwha Solutions
- Lotte Chemical
- OCI Company Ltd.
- Samsung SDI
- Daelim Industrial
- Kumho Petrochemical
LG Chem
LG Chem specializes in high-performance composite materials, offering lightweight, high-strength thermoplastics and epoxy resins crucial for automotive lightweighting initiatives aimed at enhancing fuel efficiency and reducing emissions in South Korea.
Hyundai Oilbank
Hyundai Oilbank focuses on developing advanced polymer formulations for automotive applications, with strategic investments in nanocomposite technologies to improve impact resistance and thermal stability for next-generation vehicles.
LG Household & Health Care
While primarily known for consumer products, LG Household & Health Care has expanded into automotive polymer composites, leveraging its expertise in polymer chemistry to develop innovative, eco-friendly composite materials for automotive interiors.
SK Global Chemical
SK Global Chemical develops polycarbonate and composite resins tailored for automotive applications, emphasizing sustainable production practices, recyclability, and high-performance materials that meet evolving regulatory standards in South Korea.
Hanwha Solutions
Hanwha Solutions concentrates on high-performance thermoplastics and fiber-reinforced composites, targeting the electric vehicle segment with lightweight materials that improve range, safety, and energy efficiency across South Korean automotive manufacturers.
Lotte Chemical
Lotte Chemical’s portfolio includes advanced composites and engineering plastics used in automotive structural components and interior parts, focusing on process innovations that reduce production costs and environmental impact.
OCI Company Ltd.
OCI specializes in specialty chemicals and polymers for automotive uses, pioneering biodegradable and bio-based composites aligned with South Korea’s sustainability policies and automaker demands for greener mobility solutions.
Samsung SDI
Samsung SDI advances its material science division by developing lightweight composite materials for battery enclosures and structural components in electric vehicles, combining innovation with sustainability to support Korea’s EV growth.
Daelim Industrial
Daelim Industrial invests heavily in the production of high-performance composite materials and has recently launched strategic alliances to develop next-gen, fire-retardant, and impact-resistant automotive composites for commercial and passenger vehicles.
Kumho Petrochemical
Kumho Petrochemical manufactures specialty elastomers and composite polymers used across automotive applications, focusing on enhancing durability, flexibility, and noise reduction features in composite parts.
Strategic Business Developments

- March 2023 – LG Chem – Launch of new lightweight composites for premium automotive segments – Strengthens supply chain capabilities for high-end vehicle manufacturers in South Korea.
- July 2023 – Hyundai Oilbank – Expansion of nanocomposite production capacity – Enables larger volume manufacturing, addressing rising demand from domestic automakers for advanced polymers.
- May 2023 – SK Global Chemical – Partnership with a leading South Korean automaker to co-develop sustainable composite materials – Positions the company as a leader in eco-friendly automotive composites.
- April 2023 – Hanwha Solutions – Investment in a new R&D facility focused on thermoplastic composites for electric and hybrid vehicles – Enhances innovation pipeline and technological prowess at Hanwha.
- September 2023 – Lotte Chemical – Acquisition of a specialized startup to integrate bio-based composite technologies into its manufacturing portfolio – Reinforces sustainability objectives and diversification of material offerings.
Frequently Asked Questions
What is the South Korea Automotive Polymer Composites Market?
The South Korea Automotive Polymer Composites Market encompasses the industry involved in producing lightweight, durable polymer-based composite materials used extensively in vehicle manufacturing, including structural components, interior, and exterior parts, to improve fuel efficiency and reduce emissions.
What is the current market size of South Korea Automotive Polymer Composites Market?
As of 2026, the market size is valued at approximately USD 2.4 Billion, reflecting the increased adoption of composite materials driven by automotive innovation and stringent environmental regulations in South Korea’s automotive sector.
What factors are driving the South Korea Automotive Polymer Composites Market?
Market growth is primarily fueled by the automotive industry’s push toward lightweight materials for better fuel economy, government policies promoting eco-friendly vehicle manufacturing, and technological advancements in polymer composite production that enhance material performance.
Which South Korean city leads the South Korea Automotive Polymer Composites Market?
Seoul is the leading city, owing to its robust automotive manufacturing ecosystem, R&D infrastructure, and proximity to major automotive company headquarters, enabling innovative development and streamlined supply chains in the market.
Which segment is expected to grow the fastest?
The fiber-reinforced polymer composites segment is forecasted to grow at the highest CAGR, driven by its superior strength-to-weight ratio, which is vital for automotive lightweighting and safety considerations, thereby gaining increasing adoption.
Who are the leading companies operating in the South Korea Automotive Polymer Composites Market?
Major players include LG Chem, Samsung SDI, and Hyundai Motor Company, which are actively investing in advanced polymer composite technologies, strategic collaborations, and expanding their manufacturing capacities to capture market growth opportunities.
Analyst Perspective
The South Korea Automotive Polymer Composites Market is poised for sustained growth through 2034, driven by increasing demand for lightweight materials to meet stringent emission standards and improve fuel efficiency. Long-term market prospects appear robust, with technological innovations such as nano-reinforced composites and biodegradable polymers offering avenues for differentiation and competitive advantage. Investment priorities should focus on R&D to optimize composite properties and cost-efficiency, alongside infrastructure development for local manufacturing. The competitive landscape remains intense, with domestic companies aligning strategic alliances to accelerate product innovation. Promising city-level opportunities exist in metropolitan hubs like Seoul and Busan, where automotive manufacturing clusters and smart city initiatives promote adoption of advanced composites specifically tailored for electric vehicles and autonomous systems. Overall, the market’s maturity and evolving technology landscape create fertile ground for strategic players willing to deploy capital and innovate continuously. Key risks include fluctuating raw material prices and regulatory shifts, requiring vigilant risk management.
