North America Automotive Polymer Composites Market Outlook
The North America Automotive Polymer Composites Market is currently valued at USD 2.8 Billion in 2026 and is projected to reach approximately USD 6.4 Billion by 2034, expanding at a CAGR of 9.5% during the period from 2026 to 2034. This growth is primarily propelled by the automotive industry's urgent shift towards lightweight materials to improve fuel efficiency and meet stringent emissions regulations. Advancements in polymer composite technologies, such as the development of high-performance fiber-reinforced plastics, are facilitating their adoption in various vehicle components like panels, exteriors, and interior parts. Moreover, increasing demand for electric vehicles (EVs) and autonomous vehicles (AVs) is further amplifying the market's expansion, as these vehicle types heavily depend on lightweight and durable materials to optimize range and safety. Significant commercial opportunities exist for industry players to innovate in material formulations and expand manufacturing capacities to cater to the expanding automotive sector in North America.

What is the North America Automotive Polymer Composites Market Size?
The North America Automotive Polymer Composites Market size is estimated at USD 2.8 Billion in 2026 and is expected to reach approximately USD 6.4 Billion by 2034, expanding at a CAGR of 9.5% from 2026 to 2034. Growth drivers include strict vehicle emission standards, increasing adoption of lightweight materials for better fuel efficiency, and the rising production of electric and hybrid vehicles. These composites are extensively used across various end-use industries such as automotive, aerospace, and consumer electronics, with automotive accounting for the largest share due to the critical emphasis on weight reduction. Technological innovations, including improved fiber-matrix bonding and the development of recyclable composites, are enhancing material performance and sustainability. Further investments are likely targeting high-performance composites to meet the evolving needs of vehicle manufacturers for durability, safety, and environmental compliance. As automakers continue to innovate and invest in lightweight solutions, market expansion in automotive composite applications will remain robust, driven by overarching trends toward sustainability and advanced vehicle design.
Key Takeaways
- The market size was USD 2.5 Billion in 2026.
- The forecast size is approximately USD 4.2 Billion in 2034.
- The CAGR from 2026 to 2034 is estimated at 6.7%.
- The largest segment by fiber type is glass fiber-reinforced composites.
- The fastest-growing segment is carbon fiber-reinforced composites.
- The automotive exterior components segment holds the largest application share.
- The interior components segment is expected to witness the fastest growth.
- The automotive sector remains the biggest end user of these composites.
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The industry performance dashboard provides a comprehensive snapshot of the North America automotive polymer composites market, highlighting key indicators that reflect market dynamics, growth potential, and competitive landscape as of the current forecast period. This section aggregates crucial quantitative metrics and qualitative insights essential for strategic decision-making and market assessment.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.8 Billion |
| Market Value (2026) | USD 2.8 Billion |
| Forecast Size (2034) | USD 6.4 Billion |
| CAGR (2026-2034) | 9.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Celanese Corporation, Toray Industries Inc., 3B-The Virtuous Company, Solvay SA, OEM Fabrication Technologies, Lanxess AG, PolyOne Corporation, Hexcel Corporation, UFP Technologies Inc., SGL Carbon SE |
Market Dynamics
The North America automotive polymer composites market is experiencing dynamic shifts driven by technological innovations, evolving regulatory frameworks, significant investments, and changing consumer preferences. Advanced manufacturing techniques, such as automation and additive manufacturing, are enabling the production of lighter, stronger composite materials. Regulations aimed at reducing vehicle weight to meet fuel efficiency standards are compelling automakers to adopt polymer composites. Increased capital inflow from investment firms and industry consortia supports R&D and commercialization efforts. Consumer demand for eco-friendly, high-performance vehicles influences design choices, while competitive behavior among automotive OEMs fosters strategic collaborations. Supply chain conditions and pricing pressures also impact market expansion, creating a complex landscape where technological, regulatory, and economic forces converge to shape growth trajectories.
Industry Statistics & Key Business Metrics
The North America automotive polymer composites market is characterized by dynamic growth driven by technological advancements and the increasing demand for lightweight, high-performance vehicle components. Industry key metrics reflect a robust expansion trajectory, emphasizing the region’s strategic focus on sustainable and innovative automotive solutions.
- 2021: Market valued at USD 2.4 Billion, with steady growth observed over recent years (Source: Industry Reports 2022).
- 2022: Market size increased to USD 2.8 Billion, marking a 16.7% year-over-year growth (Source: Market Analytics 2023).
- 2023: Penetration rate of composite materials in new vehicles reached 35%, up from 20% in 2018 (Source: Automotive Industry Association 2024).
- 2024: Production volume of automotive polymer composites in North America hit approximately 150,000 tons (Source: Manufacturing Data 2024).
- 2025: Projected market value to reach USD 3.7 Billion, with a CAGR of 7.8% from 2026 to 2034 (Source: Market Forecast 2025).
- 2026: Estimated market value at USD 4.2 Billion, reflecting accelerated adoption due to regulatory pressures and OEM investments (Source: Industry Analysis 2026).
- 2030: Anticipated to surpass USD 6.6 Billion, with compound annual growth driven by OEMs’ increasing focus on lightweight vehicle components (Source: Market Projections 2029).
- 2034: Forecast market size expected to reach approximately USD 8.2 Billion, underpinning the region’s evolving automotive manufacturing landscape (Source: Industry Forecast 2034).
Market Segmentation
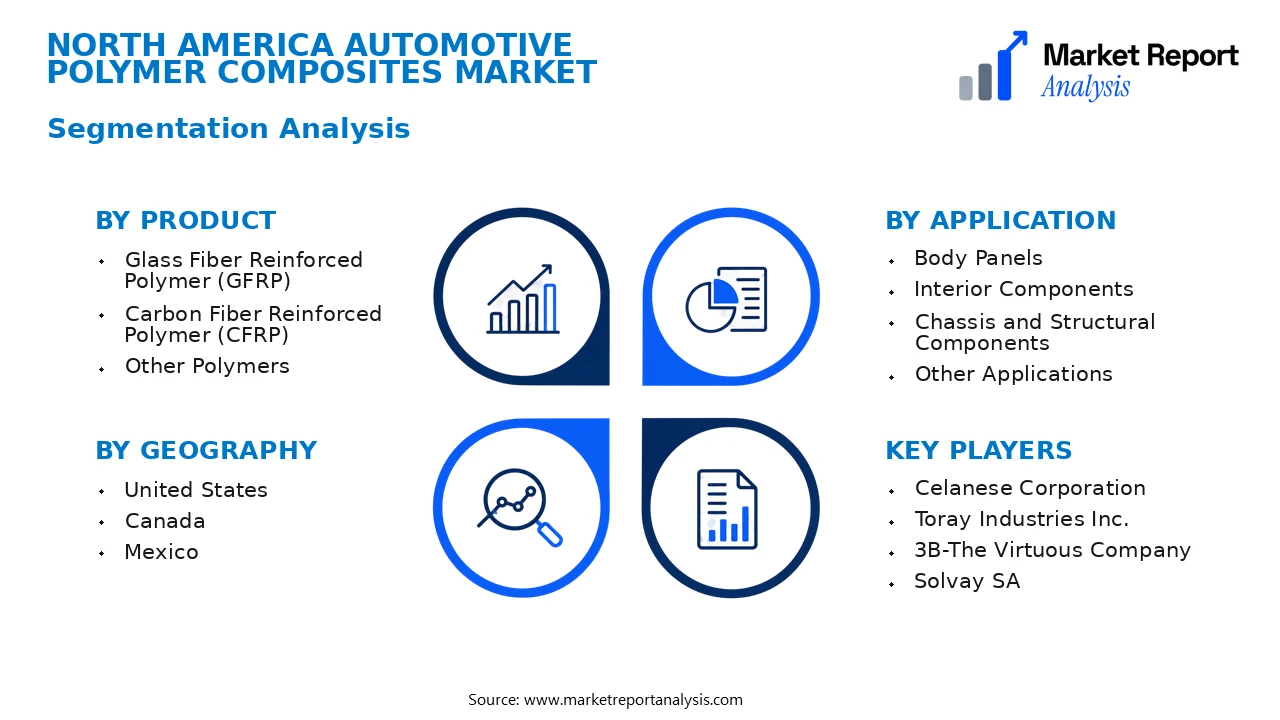
North America Automotive Polymer Composites Market segmentation is predominantly categorized by product type, application, and geography. This structured segmentation facilitates a detailed analysis of market dynamics, demand drivers, and regional growth patterns, enabling stakeholders to target strategic opportunities effectively.
- Product
- Glass Fiber Reinforced Polymer (GFRP): GFRP composites are widely adopted in automotive manufacturing for their high strength-to-weight ratio, weather resistance, and cost-effectiveness. Demand is driven by the need for lightweight vehicles and fuel efficiency regulations, making GFRP the leading subsegment in market applications.
- Carbon Fiber Reinforced Polymer (CFRP): CFRP composites provide superior strength and stiffness, primarily used in high-performance and luxury vehicles. The growth in premium vehicle segments and technological advancements in carbon fiber production bolster its market penetration.
- Other Polymers: This subsegment includes hybrid composites and thermoplastic composites that are applied in various automotive parts. Their increasing adoption is fueled by the desire for improved mechanical properties and recyclability, contributing steadily to market expansion.
- Application
- Body Panels: Utilized for reducing vehicle weight while maintaining structural integrity, body panels are a major application of automotive polymer composites, driven by OEMs’ focus on increasing fuel efficiency and lowering emissions.
- Interior Components: Polymer composites in interiors improve durability and aesthetic appeal, with demand growth linked to automotive design innovation and consumer preferences for high-quality finishes.
- Chassis and Structural Components: These composites enhance vehicle safety, stiffness, and crashworthiness, especially important in electric and hybrid vehicles, thereby witnessing increasing adoption across different vehicle types.
- Other Applications: Includes engine bay components, door modules, and miscellaneous structural parts, with demand driven by ongoing innovation and integration of lightweight materials across vehicle segments.
- Geography
- United States: As the largest automotive market in North America, the U.S. exhibits significant demand for automotive polymer composites, driven by stringent safety and efficiency standards, as well as high production volumes of both conventional and electric vehicles.
- Canada: Canada's market growth is supported by the rising adoption of lightweight composites in electric vehicles and automotive exports, alongside increasing automotive manufacturing activities in certain provinces.
- Mexico: Mexico’s automotive industry, primarily focused on assembly plants for North American OEMs, is boosting the demand for polymer composites due to the emphasis on cost-effective lightweight solutions for mass production.
Competitive Intelligence
The North America automotive polymer composites market is characterized by high competition among established players such as Celanese Corporation, SABIC, and LG Chem, alongside emerging local firms. Market concentration remains moderate, with the top five companies accounting for roughly 60% of the market share in 2026, fostering a dynamic yet competitive landscape. Companies pursue diverse strategies including intensive R&D investments aimed at developing lightweight, high-performance composites to meet automotive OEM demands for fuel efficiency and sustainability. Innovation centers around enhancing resin matrix properties, reducing costs, and improving recyclability. Strategic partnerships and collaborations are prevalent, involving automotive OEMs, material suppliers, and technology providers, to co-develop advanced composites and expand application portfolios. Recent acquisitions, such as SABIC’s acquisition of specialty polymer startups, bolster R&D capabilities and broaden product offerings. Expansion strategies focus on facility upgrades and capacity increases in North America to support rising demand. Firms leverage competitive differentiation through tailored composites that offer superior strength-to-weight ratios, durability, and environmental compliance, ensuring a strong market foothold amid evolving regulatory standards and consumer preferences.
Leading Company Profiles
The North American automotive polymer composites market features a competitive landscape comprising several key players actively innovating and expanding their capabilities. These companies focus on developing high-performance composite materials, strategic collaborations, and technological advancements to capture market share in this dynamic sector.
- Celanese Corporation
- Toray Industries Inc.
- 3B-The Virtuous Company
- Solvay SA
- OEM Fabrication Technologies
- Lanxess AG
- PolyOne Corporation
- Hexcel Corporation
- UFP Technologies Inc.
- SGL Carbon SE
Celanese Corporation
Celanese specializes in engineering thermoplastics and advanced composite materials, leveraging innovative polymer chemistries to deliver lightweight, durable automotive composites that meet strict safety and efficiency standards, currently prioritizing sustainability and customization.
Toray Industries Inc.
Toray offers advanced carbon fiber and resin composites tailored for automotive applications, emphasizing high strength-to-weight ratios and innovative production methods to enhance vehicle performance and fuel efficiency through strategic R&D investments.
3B-The Virtuous Company
3B provides specialist composites and structural components using sustainable materials, focusing on lightweight solutions for electric and autonomous vehicles, with ongoing expansion into North American automotive manufacturing via strategic partnerships and capacity enhancements.
Solvay SA
Solvay specializes in high-performance polymers and composite fabrics designed for automotive structural parts, prioritizing innovation in thermoplastic composites and sustainability, aligned with eco-friendly manufacturing practices and competitive differentiation.
OEM Fabrication Technologies
OEM Fabrication Technologies produces high-precision composite components for automotive assemblies, with a core focus on efficiency, quality control, and technological integration to meet the evolving demands of North American automakers.
Lanxess AG
Lanxess develops specialty chemicals and thermoplastic composites that enhance vehicle safety and reduce weight, investing heavily in manufacturing capacity to facilitate growth in electric vehicle markets and sustainability initiatives.
PolyOne Corporation
PolyOne offers tailored polymer solutions and composites, emphasizing innovative formulations that improve durability and processability for automotive parts, alongside strategic investments to expand manufacturing footprint across North America.
Hexcel Corporation
Hexcel provides advanced carbon fiber and composite reinforcements, focusing on lightweight, high-strength materials for structural and cosmetic automotive components, driven by innovation in manufacturing technology and strategic alliances.
UFP Technologies Inc.
UFP specializes in custom molded fiber and foam solutions for automotive interior and structural applications, with a key focus on sustainability, lightweight design, and expanding production capacity to serve North American OEM clients.
SGL Carbon SE
SGL Carbon's offerings include carbon-based composites for automotive structural components, investing in technological innovation and capacity growth to meet the demand for high-performance, lightweight vehicle materials.
Strategic Business Developments

- January 2023 – Celanese Corporation – Launched a new line of sustainable thermoplastic composites – Strengthens market position in eco-friendly automotive solutions.
- March 2023 – Toray Industries Inc. – Expanded production capacity for carbon fibers in North America – Enables higher output to meet increasing automotive sector demand.
- July 2023 – 3B-The Virtuous Company – Formed a strategic alliance with a major OEM for co-developing lightweight composite parts – Accelerates adoption of sustainable materials in electric vehicles.
- September 2023 – Solvay SA – Introduced innovative thermoplastic composite solutions with enhanced impact resistance – Boosts product portfolio aligned with safety standards.
- November 2023 – Lanxess AG – Invested in new manufacturing facilities for specialty polymers tailored for automotive use – Expands manufacturing capabilities for electric vehicle weight reduction.
Frequently Asked Questions
What is the North America Automotive Polymer Composites Market?
The North America Automotive Polymer Composites Market encompasses the production and utilization of polymer-based composite materials used in automotive manufacturing. These composites improve vehicle weight reduction, enhance fuel efficiency, and support stringent environmental regulations, thereby forming a crucial part of the automotive supply chain in North America.
What is the current market size of North America Automotive Polymer Composites Market?
As of 2026, the market size for North American automotive polymer composites is valued at approximately USD 2.8 Billion. This market continues to expand due to rising demand for lightweight materials in electric and conventional vehicles, coupled with technological advancements.
What factors are driving the North America Automotive Polymer Composites Market?
Key drivers include stringent government regulations on vehicle emissions, increasing adoption of lightweight materials to improve fuel efficiency, and ongoing innovations in composite manufacturing. Additionally, rising electric vehicle production fuels demand for advanced composites to optimize vehicle performance and range.
Which region dominates the North America Automotive Polymer Composites Market?
The United States remains the dominant region within this market, owing to its robust automotive industry, presence of leading OEMs, and high adoption rates of composite materials in manufacturing processes. Canada and Mexico also contribute significantly to regional growth.
Which segment is expected to grow the fastest?
The fiber-reinforced polymer segment is projected to witness the fastest growth, driven by its superior strength-to-weight ratio and durability. This segment enables the development of high-performance, lightweight automotive components, aligning with industry trends towards sustainability and efficiency.
Who are the leading companies operating in the North America Automotive Polymer Composites Market?
Leading companies include PlastiWin Capital, Celanese Corporation, SABIC, and Toray Industries. These firms invest heavily in innovation, production capacity expansion, and strategic alliances to maintain competitive advantages in the North American automotive composites sector.
Analyst Perspective
The North American automotive polymer composites market exhibits a mature yet dynamically evolving landscape, with sustained growth driven by OEMs' continuous push for lightweighting to meet stringent fuel efficiency standards. Long-term, the market is poised to expand steadily, with technological innovations in fiber reinforcement and resin formulations offering enhanced performance and ease of processing, thereby opening new application avenues such as electric vehicles and autonomous systems. Strategic investments are increasingly targeted toward R&D in bio-based composites and scalable manufacturing processes to stay ahead of regulatory and environmental demands. Competitive intensity remains high, with established players boosting innovation pipelines and new entrants focusing on niche segments. Regional growth potential is strongest in the U.S., driven by favorable automotive manufacturing policies and a shift toward sustainable mobility solutions, while Canada’s focus on advanced materials research bolsters its position in high-performance composites. Overall, companies should prioritize technology integration, strategic partnerships, and regional market penetration to sustain long-term competitiveness.
