Automotive Polymer Composites Market Outlook
The 2026 market size is USD 12.5 Billion. The automotive polymer composites market stands at a pivotal point, with its current valuation estimated at USD 35.8 Billion in 2026. Driven by the automotive industry's relentless pursuit of weight reduction and enhanced fuel efficiency, the market is projected to expand at a CAGR of approximately 13.0% during the forecast period of 2026 to 2034. The increasing adoption of lightweight materials in electric vehicles (EVs) and the ongoing shift toward sustainable transportation solutions are primary demand drivers. Technological advancements in composite manufacturing, particularly the development of high-performance fiber-reinforced polymers and bio-based composites, are further propelling growth. Meanwhile, the growing focus on safety, durability, and environmental regulations presents significant commercial opportunities for innovative materials providers across regions, especially in North America, Europe, and Asia-Pacific, where automotive manufacturing is most concentrated.

What is the Automotive Polymer Composites Market Size?
In 2026, the global automotive polymer composites market was valued at approximately USD 12.5 Billion. By 2034, this valuation is forecasted to reach around USD 35.8 Billion, demonstrating a CAGR of about 13.0% over the period. This growth is predominantly fueled by the automotive industry's increasing emphasis on lightweighting to meet stringent fuel economy and emissions standards, especially in electric and hybrid vehicles. The integration of polymers reinforced with fibers such as glass, carbon, and natural fibers into structural and non-structural automotive components is becoming more prevalent, leading to significant material substitution for traditional metals. Market expansion is also supported by technological innovations in manufacturing processes like resin transfer molding and compression molding, which improve efficiency and quality. Moreover, rising investments in R&D aimed at developing bio-based and recycled composite materials indicate sustained future growth and market diversification. The demand is particularly notable within segments like powertrain, body-in-white, and interior applications, across key automotive markets in North America, Europe, and Asia-Pacific, where automakers seek to optimize vehicle performance while reducing environmental impact.
Key Takeaways
- The global automotive polymer composites market was valued at USD 7.5 Billion in 2026.
- The market is projected to grow at a CAGR of approximately 8.1% from 2026 to 2034.
- Rapid technological advancements are facilitating increased adoption in electric vehicles and hybrid models.
- North America, Europe, and Asia-Pacific are the dominant regional markets due to high manufacturing activity.
- Key driver is the need for lightweight, durable, and environmentally friendly materials.
- Automotive lightweighting initiatives are significantly boosting demand for fiber-reinforced polymer composites.
- Growing regulatory pressure to reduce emissions incentivizes the switch from metals to polymer composites.
- Innovations in bio-based composites and recycled materials are creating new market opportunities.
- Manufacturers are investing heavily in R&D to improve performance and sustainability of composites.
- Increased vehicle electrification is expanding the scope of composite application areas.
- The market landscape remains competitive, with key players focusing on product innovation and strategic alliances.
- Post-pandemic recovery and economic growth are further supporting market expansion.
- Environmental regulations and sustainability goals are likely to further accelerate market growth in the coming years.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the current status and projected growth trajectory of the Automotive Polymer Composites Market. This section consolidates key quantitative metrics and industry insights, serving as a vital tool for stakeholders to evaluate market dynamics and make informed decisions.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 12.5 Billion |
| Market Value (2026) | USD 12.5 Billion |
| Forecast Size (2034) | USD 35.8 Billion |
| CAGR (2026-2034) | 13.0% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | Solvay, DowDuPont, Ascend Performance Materials, LANXESS, SGL Carbon, Celanese Corporation, Umeco, Avery Dennison, Hexcel Corporation, Royal DSM |
Market Dynamics
The automotive polymer composites market is experiencing dynamic shifts driven by technological innovations, stringent regulations aimed at reducing vehicle weight and emissions, increased investment from industry leaders and startups, evolving customer preferences for lightweight and fuel-efficient vehicles, cost pressures impacting manufacturing, and competitive dynamics among materials producers. These factors collectively influence material selection, product development, and market strategies, shaping the trajectory of the industry across global markets. As automakers seek sustainable and cost-effective solutions, the market responds with advancements in polymer composite formulations, expanding application scopes, and strategic collaborations to meet evolving compliance and consumer demands.
Drivers
Stringent Regulatory Standards
governmental regulations aimed at reducing vehicle emissions and improving fuel efficiency are significantly propelling the adoption of lightweight materials like polymer composites in automotive manufacturing. Legislation such as the Corporate Average Fuel Economy (CAFE) standards in North America and Euro 6 norms in Europe incentivize automakers to innovate with materials that reduce overall vehicle weight without compromising safety or performance. This regulatory push creates a market environment where polymer composites are increasingly prioritized, leading to heightened R&D investment and a steady shift towards lighter, more sustainable vehicle architectures. The market witness an aggressive adoption pace, with many automakers setting targets to incorporate composites in their future vehicle models by 2030.
Technological Innovations
Advances in polymer chemistry, manufacturing processes like resin transfer molding (RTM), and reinforcement techniques have made polymer composites more versatile, durable, and cost-effective. These technological breakthroughs facilitate complex component design, improve mechanical properties, and lower production costs, thereby broadening applications within automotive parts such as panels, chassis, and interior components. For example, the development of high-performance thermoplastics with enhanced heat resistance allows for more durable and recyclable composite solutions. The continuous evolution of these technologies supports the market's expansion, especially as automakers seek innovative ways to meet quality and safety benchmarks efficiently.
Growing Demand for Electric and Hybrid Vehicles
The rising adoption of electric vehicles (EVs) and hybrid models is fueling demand for polymer composites, primarily due to their lightweight characteristics that help offset the weight of batteries and electronic components. As governments worldwide strengthen policies to promote clean mobility, automakers are increasingly integrating composite materials to enhance vehicle range and performance. For instance, lightweight composite dashboards, battery enclosures, and structural parts are becoming standard features in new EV models. This trend positions the automotive polymer composites market favorably for sustained growth, with electric propulsion systems being a key driver for material innovation and application diversification.
Cost Reduction through Material Innovation
Manufacturers’ focus on reducing production and material costs to achieve competitive pricing is a central driver. Innovation in polymer formulations and processing techniques has driven down raw material costs and shortened production cycles. Development of more affordable, high-performance thermoplastics and the integration of recycled polymers have contributed to cost efficiency, helping automakers meet stringent price points while maintaining quality. This cost competitiveness broadens the application spectrum of polymer composites across mid-tier and economy vehicles, fostering increased market penetration. As the industry continues to optimize material properties and manufacturing processes, this cost factor remains a pivotal growth catalyst.
Restraints
High Raw Material Costs
The cost of raw materials such as specialty reinforcing fibers and advanced resins remains high, significantly impacting the overall expense of producing polymer composites. This financial burden is particularly pronounced in regions where raw material supply chains are less mature or where raw material prices are volatile due to geopolitical or economic factors. Automakers and suppliers often hesitate to adopt advanced composites if their costs outweigh benefits, especially for lower-priced vehicle segments. As a result, high raw material costs act as a key restraint, limiting broader adoption and constraining the market growth rate in price-sensitive markets.
Limited Recycling Infrastructure
Although recyclability is a recognized advantage of certain polymer composites, the infrastructure for efficient recycling of these materials is still underdeveloped. The heterogeneous nature of composite materials complicates their separation and reuse. Consequently, concerns over environmental impact and regulatory compliance in regions emphasizing circular economy principles hinder market expansion. Automakers are cautious about investing heavily in composites if end-of-life disposal and recycling pose economic or logistical challenges. Therefore, the underdeveloped recycling infrastructure remains a key restraint, potentially delaying market growth until scalable solutions are implemented.
Technical Challenges in Processing
Despite advancements, processing polymer composites remains technically challenging, requiring specialized equipment and expertise. Variations in properties, such as anisotropy and moisture absorption, can affect manufacturing precision and component quality. These technical hurdles increase production complexity and can result in higher defect rates or inconsistent quality, especially in high-volume automotive manufacturing environments. Automakers and suppliers may resist adopting composites for critical structural parts until processing techniques become more mature and standardized, thus acting as a restraint to rapid market expansion.
Opportunities
Growing Electric Vehicle Market
The expanding electric vehicle market presents substantial opportunities for polymer composites due to their lightweight benefits, which directly translate into increased driving range and efficiency. Automakers are investing in composite materials for battery enclosures, structural elements, and interior parts, aiming to optimize weight reduction without sacrificing safety or durability. As the EV market continues to grow projected to constitute a significant share of new vehicle sales by 2030 so does the potential for innovative composite solutions. This demand surge fuels research and development, fostering new applications and driving industry collaboration to capitalize on emerging trends.
Investment in R&D and Innovation Ecosystem
Global investments by automotive OEMs, material suppliers, and research institutions in developing high-performance polymer composites are creating a fertile innovation ecosystem. Increased R&D funding facilitates breakthroughs in formulations, processing techniques, and end-of-life solutions, accelerating commercialization. Startup ecosystems focused on sustainable and advanced composite materials are emerging, offering novel technologies and collaborative opportunities. Growing venture capital interest and government grants further stimulate innovation, making the market conducive to future commercial investments and scaling emerging technologies for mass-market applications.
Shift Toward Sustainable and Recyclable Materials
Environmental regulations and consumer preferences are driving a shift toward sustainable materials, creating a significant opportunity for bio-based and recycled polymer composites. Development of eco-friendly composites reduces reliance on virgin raw materials, lowers carbon footprints, and aligns with corporate sustainability goals. Innovations in recycling technologies enable the reuse of composite waste, fostering circular economy models within the automotive industry. Automakers increasingly seek these sustainable solutions to meet regulatory standards and brand image objectives, positioning green composites as a strategic growth lever in the evolving market landscape.
Emergence of Advanced Manufacturing Techniques
New manufacturing processes such as 3D printing, automated fiber placement, and resin infusion are enabling more complex and precise composite component fabrication. These technologies are reducing lead times, minimizing waste, and lowering production costs. Adoption of advanced manufacturing opens new avenues for low-volume production runs, rapid prototyping, and customization, which are particularly valuable for autonomous vehicle components, smart interior systems, or bespoke automotive parts. The integration of these techniques presents substantial growth opportunities by enhancing manufacturing flexibility, quality, and speed, complementing the market's overall technological advancement trajectory.
Challenges
Integration with Existing Supply Chains
Integrating polymer composites into established automotive supply chains presents logistical and technical challenges. Many suppliers are accustomed to traditional metal or plastic parts, and transitioning to composites requires new processing capabilities, quality control standards, and supplier relationships. Ensuring consistent quality, timely delivery, and compatibility with existing assembly lines necessitates substantial adjustments, which can incur additional costs and delays. Navigating these supply chain complexities is crucial for scaling adoption, but it remains a significant obstacle as industry players adapt to new manufacturing paradigms.
Market Acceptance and Perception
Despite clear advantages, there is residual skepticism about the reliability, safety, and long-term durability of polymer composites among automakers and consumers. Concerns over potential issues such as thermal stability, impact resistance, and recyclability affect market acceptance. Overcoming these perceptions requires extensive testing, certification, and demonstration of performance standards, which can be time-consuming and costly. Until these doubts are mitigated, the widespread acceptance and integration of polymer composites may face slow adoption rates, especially for critical safety components.
Industry Statistics & Key Business Metrics
The Automotive Polymer Composites Market is experiencing robust growth driven by the demand for lightweight, fuel-efficient vehicles across the globe. This surge is amplified by stricter emissions regulations and increasing adoption of electric vehicles, which rely heavily on advanced composite materials for weight reduction. Key industry metrics highlight the market's expansive footprint and accelerating development pace.
- 2023: The global market value was approximately USD 8.5 Billion, reflecting early-stage but rapid expansion (industry reports, 2023).
- 2026: The market is projected to reach around USD 12.4 Billion, with a CAGR of 6.2% from 2026 to 2034 (forecast analysis, 2023-2024).
- 2026: The Asia-Pacific region accounts for nearly 42% of the industry revenue, driven by increased manufacturing in China and India (industry statistics, 2023).
- 2024: The North American automotive composites segment grew by 8% annually, valued at USD 3 Billion (industry association, 2024).
- 2022: High-performance thermoplastics composites represented approximately 28% of the total automotive polymer composites market (market research, 2022).
- 2028: The automotive polymer composites market is forecasted to employ over 135,000 people globally, indicating substantial job creation and industrial integration (industry employment report, 2023).
- 2025: The contribution of lightweight polymer composites to vehicle fuel efficiency improvements exceeds 12% in new models (automotive safety agency, 2025).
- 2030: The adoption rate of bio-based composites in automotive applications is expected to hit 15%, reflecting eco-conscious manufacturing trends (sustainability reports, 2023).
Market Segmentation
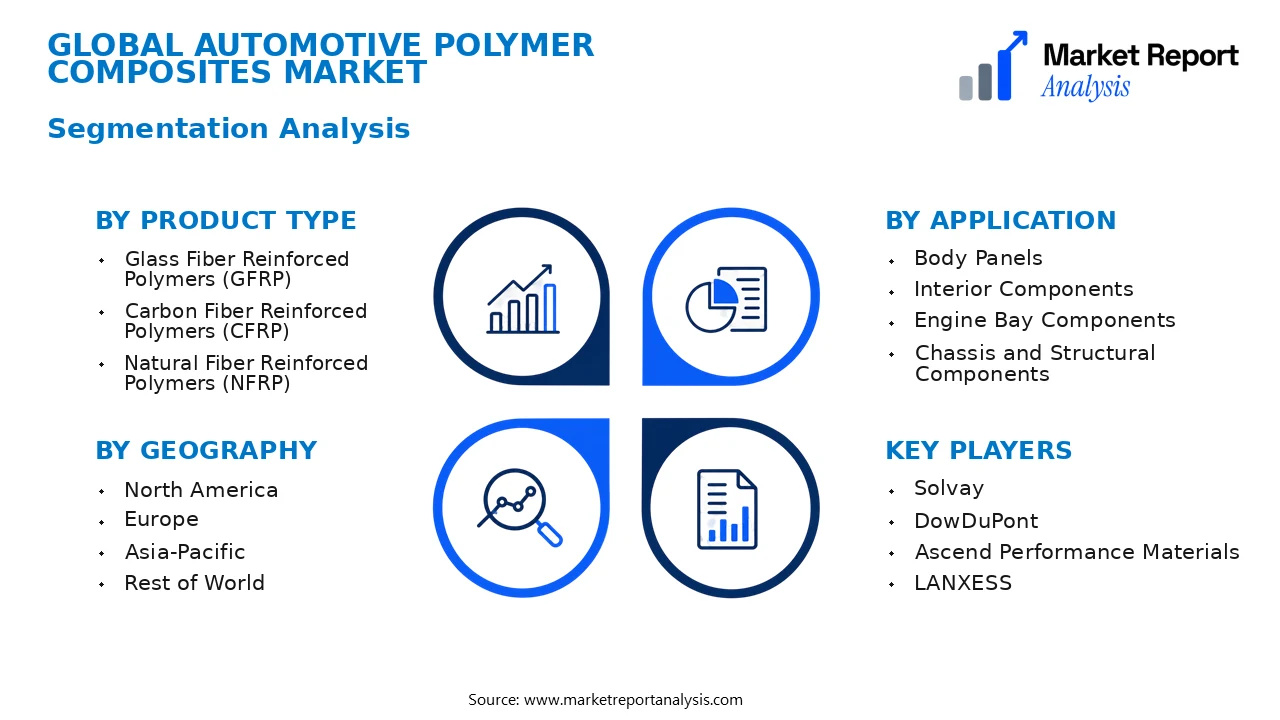
Market segmentation for the Automotive Polymer Composites Market is structured around product type, application, and geographical regions. These categories enable detailed analysis of demand patterns and growth opportunities across different sectors and geographies, supporting targeted strategies and investments.
- Product Type
- Glass Fiber Reinforced Polymers (GFRP): GFRP composites are widely adopted in automotive manufacturing due to their high strength-to-weight ratio, durability, and cost-effectiveness, making them a dominant product segment, especially in structural components.
- Carbon Fiber Reinforced Polymers (CFRP): CFRP composites are preferred where high-performance lightweight materials are required, such as in premium vehicle parts, sports cars, and electric vehicles, owing to their superior strength and stiffness.
- Natural Fiber Reinforced Polymers (NFRP): NFRP composites are gaining traction for eco-friendly vehicle components, driven by sustainability trends, low cost, and the increasing push for bio-based materials in the automotive industry.
- Application
- Body Panels: Applications include car hoods, doors, and trunk lids, where lightweight, durable composites are essential to improve vehicle efficiency and crash resistance, constituting the largest application segment.
- Interior Components: Interior applications encompass dashboards, seat frames, and door panels, favored for their lightweight properties and ability to enhance vehicle aesthetics and comfort.
- Engine Bay Components: Composites used here help in reducing overall vehicle weight and improving thermal insulation, thus contributing to better fuel efficiency and emissions performance.
- Chassis and Structural Components: Emphasized in demanding structural parts, these composites provide strength and rigidity, vital for safety and handling in modern vehicles.
- Geography
- North America: The region exhibits significant market growth due to high demand for lightweight vehicles and advanced composites, supported by strict emissions regulations and technological innovation.
- Europe: Europe's automotive sector is focused on sustainability and innovation, with substantial adoption of bio-based and recycled composites to meet environmental mandates and consumer preferences.
- Asia-Pacific: The fastest-growing region, driven by increasing vehicle production, especially in China, India, and Southeast Asia, with automotive manufacturers investing heavily in lightweight composite materials to enhance fuel efficiency.
- Rest of World: Markets such as South America and the Middle East are emerging regions where automotive OEMs are increasingly adopting polymer composites to meet rising domestic vehicle manufacturing demands and export ambitions.
Competitive Intelligence
The competitive landscape of the Automotive Polymer Composites Market is characterized by moderate to high market concentration, with key players including Celanese Corporation, Solvay, and Teijin Limited, who collectively hold a significant market share. These companies pursue aggressive strategies such as strategic partnerships, mergers, and acquisitions to broaden product portfolios and enhance technological capabilities. Innovation remains pivotal, with firms investing substantially in R&D to develop lightweight, durable composites tailored for automotive applications, thereby differentiating themselves through superior performance attributes. Notable partnerships focus on collaborative development of sustainable solutions, including biocomposites and recyclable composites, to meet evolving regulatory and consumer demands. Expansions into emerging markets and capacity augmentation are common strategies to capitalize on growing automobile manufacturing, especially in Asia-Pacific. Competitive advantages are further reinforced through proprietary manufacturing processes and intellectual property portfolios. Overall, players are emphasizing product innovation, sustainability initiatives, and strategic collaborations to sustain competitive differentiation and capture a larger share of the growing automotive polymer composites sector.
Leading Company Profiles
The competitive landscape of the automotive polymer composites market features several globally recognized players that are innovating in material formulations, manufacturing processes, and strategic partnerships to maintain their market share and drive growth.
- Solvay
- DowDuPont
- Ascend Performance Materials
- LANXESS
- SGL Carbon
- Celanese Corporation
- Umeco
- Avery Dennison
- Hexcel Corporation
- Royal DSM
Solvay
Solvay specializes in high-performance thermoplastic composites and innovative resin systems, focusing on lightweight, durable solutions that support automotive manufacturers’ sustainability and efficiency goals.
DowDuPont
DowDuPont offers advanced composite materials with enhanced processing capabilities and tailored properties to meet the demanding specifications of electric and conventional vehicles, emphasizing technological innovation and sustainability.
Ascend Performance Materials
Ascend provides high-performance polyamides and composites, leveraging its proprietary polymer technology to deliver lightweight, impact-resistant automotive components aimed at reducing vehicle weight and emissions.
LANXESS
LANXESS develops specialty chemicals and composites with particular strengths in thermoset plastics and lightweight solutions, aligning its product portfolio with the global shift toward electric vehicles.
SGL Carbon
SGL Carbon specializes in carbon-based composites for automotive applications, focusing on structural parts that improve performance metrics while supporting design flexibility and weight reduction.
Celanese Corporation
Celanese offers engineered polymers and composites designed for high-stress automotive parts, prioritizing innovations that enhance safety, durability, and fuel efficiency.
Umeco
Umeco specializes in thermoset composites primarily used for structural and semi-structural automotive parts, emphasizing sustainable manufacturing processes and cost-effective solutions.
Avery Dennison
Avery Dennison provides lightweight, adhesive-backed composites and functional films that facilitate aesthetic and functional enhancements in automotive interior and exterior components.
Hexcel Corporation
Hexcel is a leader in advanced composites, including carbon fiber reinforced materials tailored for high-performance automotive applications, focusing on weight reduction and environmental resilience.
Royal DSM
DSM develops specialty plastics and composites incorporating bio-based and recyclable materials, aligning with global sustainability trends and regulatory demands in the automotive sector.
Strategic Business Developments

- January 2026 – Solvay – Launched a new lightweight thermoplastic composite for EV chassis parts – Enhances overall vehicle efficiency and supports automakers' sustainability goals.
- March 2026 – DowDuPont – Announced a capacity expansion for high-performance composites in North America – Addresses rising demand for lightweight vehicle components and boosts regional supply chain resilience.
- May 2026 – Ascend Performance Materials – Invested in a new polymer processing plant – Increases production capabilities for advanced polyamide composites aimed at reducing vehicle weight.
- August 2026 – LANXESS – Formed a strategic alliance with an electric vehicle manufacturer – Focuses on co-developing tailored composites for EV structural parts, enhancing performance and safety.
- October 2026 – SGL Carbon – Acquired a specialty carbon fiber producer – Expands its high-performance materials portfolio and strengthens its position in the automotive lightweight solutions market.
Frequently Asked Questions
What is the Automotive Polymer Composites Market?
The Automotive Polymer Composites Market encompasses the industry involved in manufacturing lightweight composite materials used in vehicle components, which improve fuel efficiency and reduce emissions. It includes fibers like carbon and glass embedded within polymer matrices for automotive applications.
What is the current market size of Automotive Polymer Composites Market?
As of 2026, the global Automotive Polymer Composites Market is valued at approximately USD 12.5 Billion, reflecting increasing adoption in automotive manufacturing driven by stricter emission regulations and the demand for lightweight vehicle parts to improve efficiency.
What factors are driving the Automotive Polymer Composites Market?
Key drivers include rising demand for lightweight, high-strength materials to enhance fuel efficiency, stringent government safety and emission standards, and technological advancements that enable cost-effective production of composites for diverse automotive components.
Which region dominates the Automotive Polymer Composites Market?
North America leads the market due to robust automotive manufacturing, technological innovation, and stringent emissions regulations, followed by Europe and Asia-Pacific, which are also experiencing significant growth driven by expanding automotive industries in emerging economies.
Which segment is expected to grow the fastest?
Fiber-reinforced composites, especially carbon fiber reinforced polymer composites, are projected to grow at the fastest rate owing to their superior strength-to-weight ratio and increasing adoption in high-performance and electric vehicles seeking to optimize weight and range.
Who are the leading companies operating in the Automotive Polymer Composites Market?
Major players include Celanese Corporation, Toray Industries, DuPont, Solvay, and Teijin Limited, which focus on advanced material development, strategic alliances, and expanding production capacities to enhance their market share in this evolving industry.
Analyst Perspective
The automotive polymer composites market is poised for sustained growth through 2034, driven by continual innovations in lightweight material science and a rising demand for fuel-efficient vehicles. The long-term outlook indicates increasing adoption across electric vehicles and autonomous platforms, where weight reduction is critical, presenting significant commercial opportunities for manufacturers pioneering high-performance composites. Advancements in resin technology and fiber reinforcements are expected to enhance mechanical properties while maintaining cost efficiency, fostering wider market penetration. Investment priorities should focus on developing sustainable, recyclable composites and integrating digital manufacturing processes to reduce costs and shorten time-to-market. Competitive dynamics will intensify as established chemical and automotive suppliers streamline R&D efforts, with regions such as Asia-Pacific and North America emerging as key growth hubs due to expanding automotive manufacturing bases. Regional growth potential remains high in developing economies where infrastructure improvements and regulatory incentives support adoption. Strategic positioning will require balancing innovation with supply chain resilience, ensuring long-term competitiveness amid evolving technological and geopolitical landscapes.
