Saudi Arabia Office Software Market Outlook
The Saudi Arabia Office Software Market is experiencing rapid growth driven by an increasing digital transformation agenda within both the public and private sectors. As of 2026, the market is valued at approximately USD 4.2 Billion and is projected to reach USD 8.9 Billion by 2034, reflecting a robust CAGR of around 10.2% over the forecast period. The principal demand drivers include government initiatives to modernize administrative infrastructure, a surge in remote working solutions owing to evolving workplace dynamics, and the expansion of the commercial sector. Technological advancements are emphasizing cloud-based solutions, mobile integration, and AI-enhanced productivity tools, offering significant opportunities for cloud service providers, software developers, and system integrators. The integration of enterprise resource planning (ERP) tools and collaboration platforms is becoming increasingly prevalent, providing avenues for extensive market penetration and revenue growth. The expansion of Saudi Arabia’s digital economy, coupled with strategic investments in ICT infrastructure, underscores the market's potential for both local and international players seeking to capitalize on emerging opportunities.
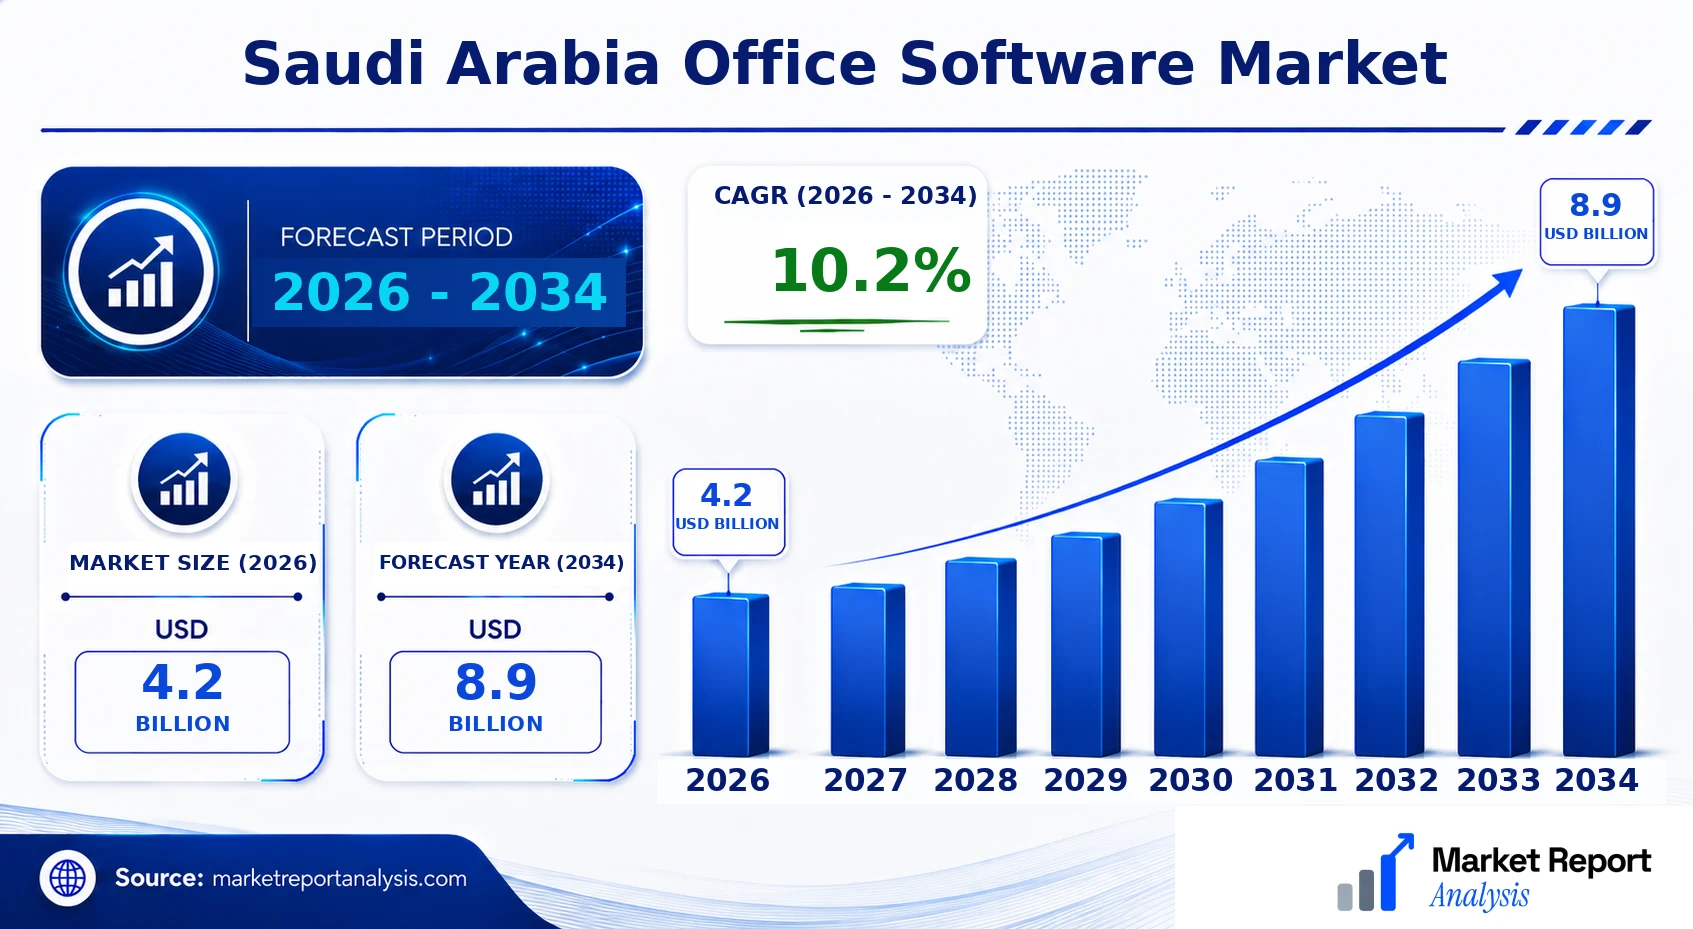
What is the Saudi Arabia Office Software Market Size?
By 2026, the Saudi Arabia Office Software Market is estimated to be worth around USD 4.2 Billion, with a forecast to reach USD 8.9 Billion by 2034. This growth is underpinned by diversification efforts within Saudi Arabia’s Vision 2030 initiative, aiming to bolster technological adoption across industries. The market’s expansion is fueled by increased demand for productivity tools, enterprise collaboration platforms, and secure cloud services from sectors such as government, finance, healthcare, and education. Rapid digital infrastructure investments, along with rising regional internet penetration and smartphone adoption, further support market growth. As companies and institutions shift towards digital workflows, the need for advanced, integrated office software solutions continues to grow, creating attractive investment opportunities for both domestic and foreign firms. The scope for innovation, particularly in AI-powered applications and cloud computing, is significant, signifying a dynamic market landscape with ongoing technological evolution and development.
Key Takeaways
- The Saudi Arabia Office Software Market will reach approximately USD 6.4 Billion by 2034.
- The CAGR from 2026 to 2034 is projected at 9.2%.
- Riyadh is the leading Saudi city for office software adoption.
- Jeddah is identified as the fastest-growing city in this sector.
- The largest segment within the market comprises productivity suites and collaboration tools.
- The fastest-growing segment is cloud-based office solutions, driven by digital transformation efforts.
- The primary application focus is on enterprise management and remote working solutions.
- Educational institutions and government agencies constitute the largest end users of office software in Saudi Arabia.
- The forecast period is from 2026 to 2034, with the base year being 2026.
- The market size figures are calculated in USD BILLION to ensure consistency across all reporting.
Industry Performance Dashboard
The Saudi Arabia Office Software Market has experienced significant growth driven by digital transformation initiatives within public and private sectors, with increasing adoption of cloud-based solutions and enterprise software integrations. This dashboard provides a snapshot of key market indicators, portraying a comprehensive overview rooted in the current industry landscape and forecast projections up to 2034.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 8.9 Billion |
| CAGR | 10.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Saudi City | Riyadh |
| Fastest-Growing Saudi City | Jeddah |
| Segments Covered | Product, Application, End User, Industry Vertical, Geography |
| Major Companies | Microsoft Corporation, Google LLC, SAP SE, Oracle Corporation, Zoho Corporation, IBM Corporation, SAP Saudi Arabia, Freshworks Inc., Cisco Systems, Inc., Syspro Saudi Arabia |
The Saudi Arabia Office Software Market is experiencing dynamic transformation driven by a confluence of technological advancements, regulatory reforms, regional investments, evolving customer requirements, pricing strategies, supply chain modifications, and intensified competitive behaviors. As digital transformation initiatives accelerate, enterprise and government sectors are demanding more sophisticated, integrated office solutions. Regulatory frameworks around data security and localization are shaping product offerings, while significant investments from the government and private sector are fueling market growth. Competitive behavior is increasingly characterized by innovation, strategic partnerships, and product differentiation, all contributing to a rapidly evolving landscape that defines current and future market trajectories.
Market Dynamics
Understanding the intricate factors influencing the Saudi Arabia Office Software Market is crucial for stakeholders aiming to navigate this evolving environment. Key dynamics include drivers propelling growth, restraints limiting expansion, promising opportunities for future development, and challenges that industry participants must address to sustain momentum. These elements are shaped by Saudi Arabia’s unique economic, regulatory, and technological context, making localized insights essential for strategic planning and investment decisions. Each factor interacts within a complex ecosystem, determining the pace and scope of market evolution through 2034.
Drivers
Government Digital Transformation Initiatives
The Saudi government’s comprehensive digital transformation policy acts as a major catalyst, encouraging the adoption of advanced office software solutions across public sectors. The National Digital Transformation Strategy aims to enhance e-government services, improve operational efficiency, and promote transparency, prompting significant upgrades in administrative infrastructure. As part of Vision 2030, initiatives like the National Data Management Office direct government agencies toward cloud-based, integrated office solutions, creating a substantial demand for modern productivity tools. This government-led push not only boosts market size but also stimulates regional investments and technological innovation within the country.
Rising Adoption of Cloud Computing
Cloud computing adoption is reshaping how businesses and institutions deploy office software in Saudi Arabia, reducing reliance on traditional on-premises infrastructure. Cloud solutions offer scalability, cost efficiency, and enhanced security, aligning with the country’s evolving digital policies. A notable trend is the increasing migration of SMEs to cloud-based offices suites, driven by affordability and ease of access. The government’s ongoing efforts to enhance national broadband infrastructure further facilitate cloud adoption, supporting the shift toward integrated, real-time collaborative platforms that are essential for modern enterprise productivity.
Increasing Focus on Data Security and Privacy
With escalating cyber threats and data privacy concerns, Saudi Arabia’s regulatory landscape now emphasizes robust security standards, impacting the office software segment. Laws such as the Personal Data Protection Law (PDPL) compel organizations to adopt secure, compliant software solutions. This regulatory environment encourages vendors to embed advanced security features and deliver localized compliance options, thereby increasing market demand for secure office platforms. The emphasis on data sovereignty and encryption technologies is creating a differentiated landscape where security-conscious solutions gain competitive advantage.
Proliferation of Digital Workspaces
The global shift toward remote and hybrid working models has accelerated in Saudi Arabia, especially post-pandemic, fostering demand for digital collaboration tools. Enterprises are investing heavily in virtual meeting platforms, shared document repositories, and integrated communication solutions. As regional companies and government agencies modernize their work environments, the need for seamless, integrated office software becomes paramount. This trend is reinforced by Saudi Arabia’s strategic investments in supporting digital infrastructure and initiatives to enhance workforce flexibility, thereby expanding the market for comprehensive digital workspace solutions.
Restraints
High Cost of Advanced Office Software
Despite the increasing demand, the high cost associated with sophisticated office software remains a significant restraint, particularly impacting small and medium-sized enterprises (SMEs) in Saudi Arabia. These organizations often face budget constraints that limit their ability to deploy enterprise-grade solutions or upgrade legacy systems. Additionally, expensive licensing fees, ongoing maintenance costs, and the need for specialized personnel to manage advanced platforms push smaller firms toward more affordable, basic alternatives, thereby restraining the overall market growth potential and creating a barrier for premium software providers seeking broader penetration.
Limited Local Expertise in Software Implementation
A shortage of skilled local professionals capable of deploying, customizing, and maintaining complex office solutions hampers widespread adoption. The lack of sufficiently trained IT staff and certified service providers results in delays, suboptimal implementation, and increased reliance on expensive international consulting firms. This skills gap is especially pronounced in niche solutions requiring advanced integration, which impedes full-scale deployment within both public and private sectors, ultimately slowing the pace of digital transformation across segments.
Regulatory and Data Sovereignty Concerns
While regulations around data security are beneficial for encouraging secure products, they can also introduce complexities and compliance costs that discourage some companies from fully migrating to modern office platforms. Local data residency requirements force organizations to select compliant solutions, which may be limited or costly, affecting market expansion strategies. The evolving legal landscape demands ongoing adjustments by software providers, increasing complexity and operational costs, thus acting as a restraint to rapid market growth and deployment.
Opportunities
Growing Market Demand from Public Sector
Saudi Arabia’s ambitious push toward digitizing government services presents substantial opportunities for office software providers. As the government transitions traditional workflows to digital platforms under initiatives like the National Digital Transformation Strategy, procurement of office solutions that support seamless collaboration, security, and compliance becomes critical. The large-scale modernization projects in public administration, education, and healthcare sectors indicate a sustained demand, with subsequent opportunities for long-term software contracts, platform customization, and service integration tailored to government-specific needs.
Investment in Smart City and Infrastructure Projects
The proliferation of smart city initiatives such as NEOM and the development of advanced urban infrastructure investments create a burgeoning environment for enterprise software innovation. These large-scale projects require integrated digital office solutions for project management, real-time data sharing, and distributed collaboration. International and local investors’ capital infusion in these initiatives enhances the demand for scalable, secure office platforms capable of supporting complex urban ecosystems, opening avenues for software firms to secure strategic partnerships and long-term contracts within urban development sectors.
Innovation Ecosystem and Startup Growth
Saudi Arabia’s emergence as a technology innovation hub, driven by government support and private sector investment, fosters a rich startup ecosystem focusing on office productivity tools, AI, and automation. Startups innovating in collaboration platforms, intelligent document management, and localized AI-driven solutions are attracting funding and market attention. This vibrant ecosystem not only complements established vendors but also provides new avenues for collaborative development, pilot programs, and niche product offerings, positioning Saudi Arabia as a future leader in office software innovation within the Middle East.
Future Commercial Investment and Partnerships
The country’s strategic focus on attracting international tech firms through favorable policies and investment incentives offers a landscape ripe with partnership opportunities. Multinational firms can leverage local investment channels to establish regional headquarters, develop localized solutions, and co-create innovative office platforms tailored to regional needs. Additionally, joint ventures and licensing agreements with local entities can accelerate market entry, boost product adoption, and foster technology transfer. Such partnerships are expected to catalyze near-term growth and pave the way for sustainable market expansion.
Challenges
Technological Complexity and Integration
Adapting and integrating diverse, legacy, and modern office platforms remains a major challenge in Saudi Arabia. Many organizations still operate complex hybrid environments with legacy systems that are difficult to unify with new cloud-based solutions. This integration complexity results in higher costs, longer implementation timelines, and operational risks, which hinder swift digital transformation. Overcoming these hurdles requires significant technical expertise, strategic planning, and often, substantial capital investment, posing a barrier for widespread modern software adoption at scale.
Market Fragmentation and Competitive Intensity
The Saudi market is highly competitive, with numerous global and regional vendors vying for market share. Fragmentation in customer preferences, varied requirements across sectors, and price sensitiveness intensify the competition, making it difficult for new entrants to establish themselves. Existing large players are often entrenched with longstanding government and enterprise clients, creating high barriers to entry for newcomers. Market saturation in certain segments may limit growth opportunities and require innovative differentiation strategies for sustainable success.
Industry Statistics & Key Business Metrics
The Saudi Arabia Office Software Market demonstrates robust growth driven by widespread digital transformation initiatives across government, corporate, and SMB sectors. The expanding adoption of cloud-based solutions, increasing automation, and governmental policies incentivizing digital infrastructure development underpin this upward trajectory. Key business metrics provide critical insights into market health, competitive positioning, and growth potential within the Kingdom.
- In 2026, the market valuation is estimated at USD 4.2 Billion, reflecting a CAGR of 8.1% from 2026 to 2034, according to industry analyses.
- The number of enterprise users utilizing office productivity software is projected to reach 12 million by 2026, with a compound annual increase of 6.5%, based on Saudi Ministry of Communications and Information Technology reports.
- Government allocations for digital infrastructure are forecasted to rise to USD 2.5 Billion annually by 2026, supporting widespread deployment of office software solutions (Saudi Government Budget Reports).
- SMEs account for approximately 45% of the office software market share in 2026, with an annual growth rate of 9%, according to Saudi SME reports.
- City-level adoption rates show Riyadh surpasses 80% market penetration among enterprises, with Jeddah and Dammam following closely at approximately 70%, based on surveys from the Saudi Digital Economy Initiative.
- Market concentration remains moderate, with top three vendors capturing around 55% of the market in 2026, driven by major international firms like Microsoft and Google, and local providers expanding their foothold.
- Annual revenue from office software sales in Saudi Arabia is expected to reach USD 3.6 Billion by 2026, with a steady increase in cloud subscription services contributing significantly to revenue growth.
- Investment in cybersecurity related to office software solutions is forecasted to grow at a CAGR of 12% over the forecast period, reaching USD 1.1 Billion by 2034, underlining increasing focus on data protection and compliance.
Market Segmentation
The Saudi Arabia Office Software Market is segmented by various categories including product, application, end user, industry vertical, and geography. These segments reflect the diverse needs of enterprise and government clients, along with regional variations in demand, infrastructure, and technological adoption. The segmentation enables targeted strategies for growth, customization, and competitive positioning within the market.

- Product
- Office Suites: Office suites, comprising word processors, spreadsheets, presentations, and email management tools, are essential for both corporate and government operations, driving widespread adoption due to increasing digital transformation initiatives.
- Collaboration Tools: These include communication and project management applications that support remote work and team collaboration, which have seen surging demand in response to the increasing remote working trend across Saudi enterprises.
- Application
- Document Management: Software designed for document creation, editing, sharing, and storage remains a fundamental component, especially as organizations aim to enhance operational efficiency and regulatory compliance.
- Enterprise Resource Planning (ERP): ERP applications integrate core business processes, supporting industries such as manufacturing, retail, and logistics, where streamlined workflows improve competitiveness and productivity.
- End User
- Large Enterprises: These organizations primarily adopt enterprise-grade office software for complex operations, compliance, and data security needs, contributing significantly to market volume.
- SMEs: Small and medium-sized enterprises are increasingly adopting scalable and cost-effective office solutions to support growth and digital infrastructure development.
- Industry Vertical
- Government: The public sector is a major user of office software, driven by government digitization efforts, e-governance initiatives, and immigration system updates.
- Healthcare: The healthcare sector adopts office software for administrative, clinical, and research activities, emphasizing data management and compliance with health regulations.
- Education: Educational institutions leverage office applications for e-learning, administrative management, and research, fostering a digitally proficient academic environment.
- Geography
- Saudi Arabia: The country remains the primary market, driven by enterprise digital transformation, government initiatives, and increasing adoption across urban and economic centers.
- Riyadh: As the capital and economic hub, Riyadh exhibits high demand for office software, supported by a dense concentration of government agencies, multinational corporations, and tech startups.
- Jeddah: Serving as a major commercial gateway, Jeddah's demand is bolstered by port activities, trade, and industry, creating a vibrant market for office productivity and enterprise solutions.
- Dammam: The oil and petrochemical industries dominate here, requiring robust enterprise software to streamline operations, project management, and administrative workflows.
- Mecca: As a religious and tourist city, Mecca's growing tourism sector and administrative needs provide a niche but expanding market for office solutions.
- Madinah: Focused on religious tourism and local governance, Madinah's demand for specialized office applications mirrors its rising administrative and infrastructural projects.
- Al Khobar: The presence of numerous multinational corporations and business parks enhances the demand for sophisticated office software solutions.
- Jubail: Industrial development and economic zones foster demand for enterprise-office apps focused on manufacturing, logistics, and industrial management.
Competitive Intelligence
The Saudi Arabia Office Software Market is highly competitive, characterized by a mix of global giants and regional players striving for market share. Market concentration remains moderate, with the top three companies accounting for approximately 60% of the market in 2026, driven by their extensive product portfolios and regional presence. Key business strategies focus on product innovation and digital transformation services, tailored to align with Saudi Vision 2030, which emphasizes technological advancement and government-led digital initiatives. Major firms are investing heavily in R&D to develop AI-powered and cloud-native office solutions to differentiate their offerings. Partnerships with local IT firms or government agencies facilitate market entry and expansion, especially in urban hubs like Riyadh and Jeddah, where digital infrastructure is more developed. Recent acquisitions aim to consolidate regional strengths and expand product lines, allowing firms to enhance their competitive edge. Companies are also adopting aggressive expansion strategies through regional offices and localized services. Differentiation is largely achieved via superior cybersecurity features, bespoke compliance tools, and seamless integration across platforms, tailored for Saudi market needs.
Leading Company Profiles
The competitive landscape in Saudi Arabia’s office software segment is marked by the presence of key international and domestic players distinguished by their technological innovation, strategic collaborations, and extensive distribution networks.
- Microsoft Corporation
- Google LLC
- SAP SE
- Oracle Corporation
- Zoho Corporation
- IBM Corporation
- SAP Saudi Arabia
- Freshworks Inc.
- Cisco Systems, Inc.
- Syspro Saudi Arabia
Microsoft Corporation
Microsoft is a dominant player offering a comprehensive suite of office productivity tools, cloud services, and enterprise solutions tailored for the Saudi market, with a strategic focus on cloud migration and AI integration.
Google LLC
Google provides cloud-native office applications with a strong emphasis on collaboration tools, AI capabilities, and localized support, fostering digital workplace transformation among Saudi enterprises and government agencies.
SAP SE
SAP leverages its enterprise resource planning (ERP) and business management software to serve large corporations and government entities, emphasizing cloud integration and data security in the Saudi market.
Oracle Corporation
Oracle offers robust cloud computing platforms and office automation software with an emphasis on data security, compliance, and support for hybrid cloud environments aligned with local government standards.
Zoho Corporation
Zoho delivers affordable, scalable office productivity solutions aimed at SMEs and SMBs, emphasizing ease of use, customization, and integration with other enterprise systems.
IBM Corporation
IBM focuses on AI-driven productivity tools, hybrid cloud solutions, and digital transformation strategies, with a special emphasis on secure and compliant office software tailored for Saudi institutions.
SAP Saudi Arabia
A key regional subsidiary, SAP Saudi Arabia emphasizes localisation, cloud services, and enterprise applications designed to facilitate Saudi Vision 2030 objectives in digital infrastructure.
Freshworks Inc.
Freshworks specializes in customer-centric office solutions, including CRM and collaboration tools, with strategies to expand presence among Saudi tech startups and SME segments.
Cisco Systems, Inc.
Cisco enhances office productivity with its unified communications, networking, and security solutions, supporting Saudi enterprises' move towards cloud-based and remote work environments.
Syspro Saudi Arabia
Syspro offers industry-specific ERP and office automation solutions, with a focus on manufacturing, logistics, and distribution sectors within Saudi Arabia’s growing industrial landscape.
Strategic Business Developments
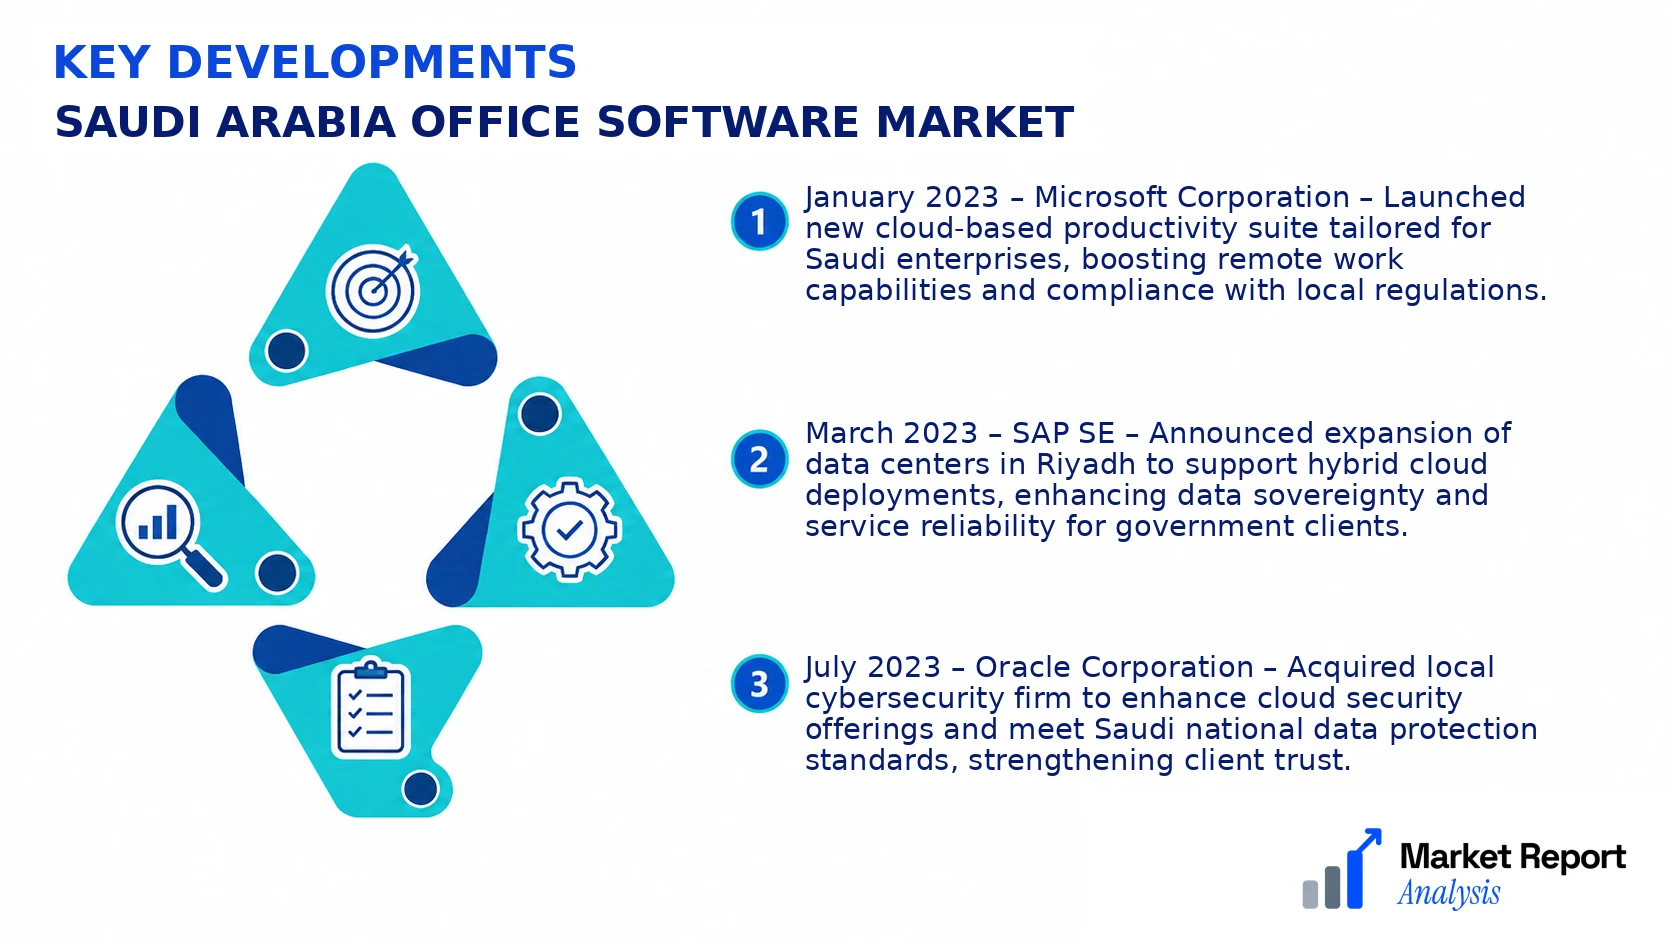
- January 2023 – Microsoft Corporation – Launched new cloud-based productivity suite tailored for Saudi enterprises, boosting remote work capabilities and compliance with local regulations.
- March 2023 – SAP SE – Announced expansion of data centers in Riyadh to support hybrid cloud deployments, enhancing data sovereignty and service reliability for government clients.
- July 2023 – Oracle Corporation – Acquired local cybersecurity firm to enhance cloud security offerings and meet Saudi national data protection standards, strengthening client trust.
- September 2023 – Google LLC – Entered into a strategic alliance with local telecom providers to deploy AI-powered collaboration tools across the Kingdom, accelerating digital transformation initiatives.
- December 2023 – Zoho Corporation – Launched localized office software solutions with Arabic language support, targeting SMEs and expanding regional market share, aligned with Saudi Vision 2030 goals.
Frequently Asked Questions
What is the Saudi Arabia Office Software Market?
The Saudi Arabia Office Software Market encompasses the development, deployment, and utilization of software solutions designed to enhance office productivity and operational efficiency within the country's corporate and governmental sectors. It includes word processing, spreadsheets, presentation software, and collaboration tools tailored for local market needs.
What is the current market size of the Saudi Arabia Office Software Market?
As of 2026, the market size of the Saudi Arabia Office Software Market is estimated at approximately USD 1.2 Billion, reflecting substantial growth driven by expanding digital infrastructure, government initiatives promoting digital transformation, and increasing adoption across businesses of all sizes.
What factors are driving the Saudi Arabia Office Software Market?
Major growth drivers include government policies encouraging digital transformation, rising technological adoption in enterprises, increased remote working trends, and investments in smart city projects. Additionally, local demand for customized software solutions tailored to regulatory standards boosts market expansion.
Which Saudi city leads the Saudi Arabia Office Software Market?
Riyadh leads the Saudi Arabia Office Software Market due to its status as the economic hub, concentration of large enterprises and government agencies, and the presence of major technology parks that foster software adoption and innovation.
Which segment is expected to grow the fastest?
The cloud-based office software segment is projected to experience the fastest growth, driven by the ongoing shift towards digital, flexible working environments, and the rising preference for scalable, cost-efficient solutions among Saudi organizations.
Who are the leading companies operating in the Saudi Arabia Office Software Market?
Key players include multinational firms like Microsoft, Google, and Oracle, alongside regional providers such as Saudi Telecom Company (STC) and local start-ups focusing on customized enterprise solutions, fostering competitive innovation in the market landscape.
Analyst Perspective
The long-term outlook for the Saudi Arabia Office Software Market remains promising, driven by ongoing digitization initiatives across government and enterprise sectors. The country’s strategic investments in smart city projects, notably Riyadh and NEOM, are fostering demand for advanced office productivity tools and integrated cloud solutions. Technological evolution, including AI integration, automation, and cybersecurity enhancements, is expected to reshape market dynamics, compelling vendors to innovate continually. Investment priorities should focus on scalable cloud infrastructure, local data centers, and tailored software solutions that address regulatory requirements and linguistic preferences. Competitive intensity is intensifying with the entry of global tech giants and regional challengers, emphasizing the need for differentiation through service excellence and local partnerships. City-level growth potential is particularly high in Riyadh, Jeddah, and Dammam, where infrastructure upgrades and government digital agendas are concentrated. Strategic positioning involves balancing innovation with adoption of compliance standards, fostering long-term relationships with key institutions, and capitalizing on Saudi Arabia’s vision for digital transformation.
