North America Room Air Conditioners Market Outlook
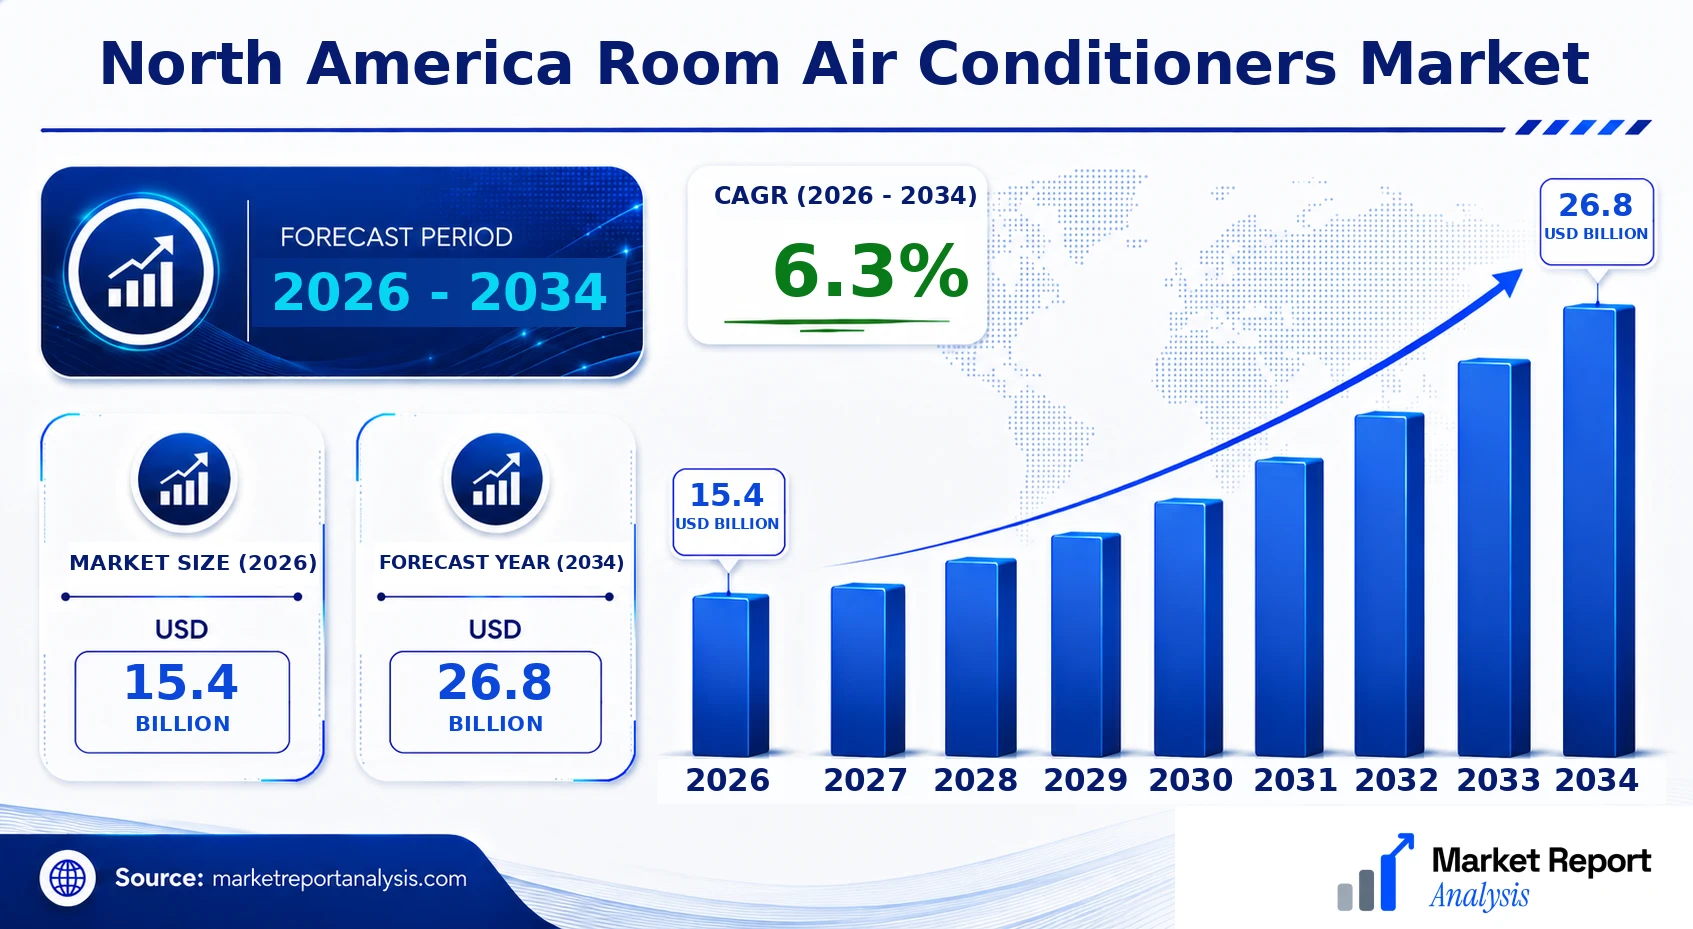
The North America Room Air Conditioners Market is currently valued at approximately USD 15.4 Billion in 2026 and is projected to reach about USD 26.8 Billion by 2034, expanding at a CAGR of 6.3% during the forecast period from 2026 to 2034. This growth is driven by increasing temperatures, rising disposable incomes, and a growing preference for energy-efficient cooling solutions in residential and commercial sectors. Technological advancements such as smart and inverter air conditioners are further accelerating market expansion. Manufacturers are focusing on innovation, regulatory compliance, and sustainable practices, entailing opportunities for investment in renewable energy-based systems and smart connectivity features. As climate change persists and urbanization fosters increased demand, the market's trajectory appears resilient and poised for steady growth, with significant commercial opportunities for new entrants and established players alike.
What is the North America Room Air Conditioners Market Size?
The North America Room Air Conditioners Market size is estimated at a current-market value of USD 15.4 Billion in 2026 and is expected to reach approximately USD 26.8 Billion by 2034, expanding at a CAGR of 6.3% from 2026 to 2034. This growth is primarily driven by rising temperatures across North America, increased urbanization, and a rising standard of living that fuels demand for climate control solutions. The residential sector accounts for the largest share, driven by greater homeownership and consumer awareness about indoor comfort. Commercial applications, including hospitality, retail, and office spaces, contribute significantly to the market, with a notable shift towards energy-efficient models influenced by regulations and environmental concerns. The impact of technological innovation, especially the adoption of smart, inverter, and eco-friendly refrigerant-based units, is catalyzing market expansion. Future investments are likely to focus on enhancing product efficiency, integrating smart technology, and expanding access in less developed regions, providing ample growth opportunities in the coming years.
Key Takeaways
- The market size is approximately USD 15.2 Billion in 2026.
- The forecast size by 2034 is around USD 22.1 Billion.
- The CAGR from 2026 to 2034 is estimated at 5.0%.
- The residential segment holds the largest market share.
- The inverter air conditioners are the fastest-growing product segment.
- The largest application is in residential buildings.
- Commercial applications are the fastest growing segment.
- Homeowners are the primary end users.
- The forecast period is 2026-2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The North America Room Air Conditioners Market has exhibited consistent growth driven by rising temperatures, increasing urbanization, and expanding disposable incomes across the region. This dashboard provides a snapshot of current and projected market dynamics, highlighting key indicators that reveal industry health and trajectory from 2026 to 2034.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 15.4 Billion |
| Market Value (2026) | USD 15.4 Billion |
| Forecast Size (2034) | USD 26.8 Billion |
| CAGR | 6.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Technology, Geography |
| Major Companies | Carrier Global Corporation, Daikin Industries, Ltd., LG Electronics Inc., Samsung Electronics Co., Ltd., Mitsubishi Electric Corporation, Philips Respironics, Trane Technologies, Air Solutions, Inc., Electrolux AB, Gree Electric Appliances Inc. |
Market Dynamics
The North America Room Air Conditioners Market is deeply influenced by a confluence of technological advancements, evolving regulations, rising investments, customer preferences, pricing strategies, supply chain conditions, and competitive behaviors. As consumers increasingly demand energy-efficient and smart cooling solutions, manufacturers are innovating rapidly, propelled by stringent environmental standards and sustainable practices. Regulatory frameworks aim to reduce energy consumption and greenhouse gas emissions, which steer technological development and product design. Meanwhile, hefty investments from both established players and startups foster competitive innovation ecosystems. Pricing dynamics are shifting due to supply chain constraints and raw material costs. Overall, these intertwined factors are shaping a resilient yet highly competitive landscape across North America, pushing brands to adapt swiftly to meet market expectations and regulatory mandates.
Drivers
Technological Innovation
The continuous evolution of technology in the room air conditioners sector, including the integration of IoT, advanced thermostats, and energy-efficient components, acts as a primary market catalyst. This innovation improves the user experience through smart, programmable, and remotely controllable units, which meet the increasing consumer demand for convenience and energy savings. For example, smart AC units that connect with home automation systems are gaining popularity, making homes more eco-friendly and efficient. Additionally, technological advancements contribute to compliance with evolving environmental standards, further incentivizing manufacturers to innovate and expand their offerings to a tech-savvy customer base. The proliferation of AI-enabled models is expected to drive market growth significantly through 2034, supported by rising consumer adoption of connected devices.
Regulatory Push for Energy Efficiency
Legislation aimed at reducing power consumption, such as mandates on Seasonal Energy Efficiency Ratio (SEER) ratings and refrigerant use restrictions, is a key driver. North American regulations, including those from the US Department of Energy and Environment and Climate Change Canada, compel manufacturers to produce higher-efficiency units, thus boosting the market. Compliance not only reduces environmental impact but also appeals to consumers seeking lower utility bills, thus intensifying demand. These regulatory frameworks foster innovation in refrigerant technology and compressor design, pushing industry players to develop products that align with regulatory standards while maintaining performance. The enforcement of these standards from 2026 onward signifies a strong market growth impetus.
Rising Consumer Preference for Eco-friendly Solutions
Growing environmental awareness among North American consumers influences purchasing decisions, favoring energy-efficient and environmentally friendly air conditioning systems. This trend is driven by an increasing number of eco-conscious households and a societal shift towards sustainable living. Market data indicates that over 60% of consumers are willing to pay a premium for eco-friendly appliances, which encourages manufacturers to develop green solutions such as units using low-GWP (Global Warming Potential) refrigerants and energy-saving technologies. The rising adoption of premium models with advanced eco-friendly features is a clear indicator of this trend’s influence on market expansion. If consumer preferences continue evolving in this direction, market growth will accelerate through 2034.
Expansion of Construction and Renovation Activities
The growth in residential, commercial, and institutional construction and renovation activities across North America directly fuels demand for air conditioning units. Urbanization, economic development, and demographic shifts contribute to increased building projects that incorporate climate control solutions. Notably, the retrofitting of older buildings with modern, energy-efficient AC systems presents a significant growth opportunity. The rise of smart and integrated HVAC systems in new constructions enhances the functionality and efficiency of buildings, further boosting market demand. This expansion is supported by government incentives and codes that promote energy-efficient upgrades, thus positively impacting the market trajectory through 2034.
Restraints
High Initial Capital Investment
The significant upfront costs associated with advanced, energy-efficient, and smart air conditioning units hinder market growth in price-sensitive segments. Residential buyers in lower-income brackets often prioritize affordability over innovation, limiting market penetration for premium models. Commercial sectors aiming to upgrade their cooling systems face substantial capital expenditures, which can slow adoption. This economic barrier is particularly impactful in regions with lower household incomes or in commercial sectors where budget constraints are rigid. Although operational savings can offset initial expenses over time, the high initial expenditure remains a notable restraint affecting market expansion, especially among cost-conscious consumers.
Supply Chain Disruptions
Disruptions in the supply chain, exacerbated by global events, geopolitical tensions, and raw material shortages, significantly affect the availability and cost of components for air conditioners. The recent COVID-19 pandemic highlighted vulnerabilities within supply networks, leading to delays and increased prices for critical components such as semiconductors, compressors, and refrigerants. These disruptions hamper production schedules, increase costs for manufacturers, and ultimately raise retail prices, which can suppress demand. The dependency on specific regions for raw materials and manufacturing further magnifies these risks. Overcoming supply chain vulnerabilities is critical for sustaining growth in the North American market through 2034.
Opportunities
Growing Industry Investment and Strategic Alliances
As the demand for energy-efficient and smart air conditioning solutions rises, Cleveland opportunities for increased investments from both private and public entities are emerging. Governments across North America are offering incentives and grants to promote green technology, stimulating industry funding and R&D initiatives. Strategic alliances between established players and innovative startups are driving the development of cutting-edge products, such as AI-driven climate control systems and refrigerants with lower GWP. These collaborations foster innovation ecosystems that accelerate technology deployment, create new markets, and expand product portfolios. This investment landscape signifies a strong future growth trajectory for the market over the coming years, supporting an accelerated transition toward sustainable cooling solutions.
Emergence of Smart and Connected Cooling Technologies
The rapid advancement of IoT and connected home ecosystems presents substantial growth opportunities. Smart AC units enable users to optimize energy consumption, manage settings remotely, and integrate with other smart devices seamlessly. The increasing consumer demand for convenience and real-time control fuels the adoption of sophisticated, IoT-enabled air conditioners. Market players are investing heavily in developing AI-driven predictive maintenance, adaptive cooling algorithms, and user-friendly interfaces, thereby opening new revenue streams and enhancing market penetration. As connectivity standards mature and the adoption of smart homes accelerates, the North American market will experience significant growth through 2034, driven by both consumer preferences and technological advancements.
Integration of Renewable Energy Sources
With the upward trend of renewable energy adoption, integrating solar and wind power with cooling solutions offers a promising opportunity. Solar-powered air conditioning systems, in particular, are gaining traction due to declining solar panel costs and increased environmental consciousness. Such systems reduce dependency on grid electricity, lower operational costs, and help meet regulatory standards for renewable integration. Market interest is also buoyed by government policies promoting renewable energy use, financial incentives, and the need to reduce carbon footprints. Developing and scaling renewable-compatible cooling solutions positions manufacturers to capitalize on emerging energy sustainability trends, driving market growth and fostering innovation in product design by 2034.
Development of Eco-Friendly Refrigerants and Technologies
The shift toward low-GWP refrigerants and eco-friendly technologies is transforming the product landscape. As regulations tighten globally and regionally, manufacturers are investing in alternative refrigerants such as hydrofluoroolefins (HFOs) and natural refrigerants, which have minimal environmental impact. The adoption of inverter compressors and variable-speed technology enhances energy efficiency further and aligns with sustainability goals. The ongoing development and commercialization of such environmentally conscious solutions present considerable commercial investment opportunities. Sustained focus on green refrigerants and energy-efficient components is expected to lead to innovative product lines that meet both regulatory and consumer demands, fueling market growth through 2034.
Fostering Small-Scale Manufacturing and Startup Ecosystems
The rise of startups and small-scale manufacturers specializing in niche or innovative cooling technologies creates a vibrant innovation ecosystem. Such companies often pioneer breakthroughs in miniaturization, energy efficiency, and integration with smart home systems. Their agility enables rapid development of new features and customization options suited to niche markets, such as eco-conscious or high-performance segments. Increased venture capital investments and government grants foster a supportive environment for these startups, facilitating competitive product development and technology diffusion. This ecosystem not only promotes innovation but also enhances supply chain resilience and diversification, which is critically important for long-term market sustainability.
Challenges
Environmental Impact and Regulatory Compliance
As environmental concerns intensify, manufacturers face the challenge of adhering to increasingly strict regulations on refrigerants, energy efficiency, and waste management. The phase-out of high-GWP refrigerants and adoption of new standards requires substantial R&D investments and redesign of existing products. Additionally, compliance costs may inflate overall product prices, affecting affordability and competitiveness. The need to balance technological innovation with regulatory adherence poses a persistent challenge, especially for small and mid-sized companies operating with limited R&D budgets. Navigating this complex regulatory landscape calls for strategic planning and continuous innovation to sustain growth and meet impending environmental standards.
Market Saturation and Competitive Pressure
The increasing number of market participants has led to a saturation point, intensifying competition and reducing profit margins. Established players face aggressive strategies from new entrants and local manufacturers who seek to capture niche or cost-sensitive segments. Price wars, branding challenges, and product differentiation become critical to maintaining market share. Additionally, consumer switching costs are low, driven by the availability of affordable alternatives. The competitive landscape requires companies to continuously innovate, optimize supply chains, and enhance brand loyalty. Without strategic differentiation, manufacturers risk stagnation amidst evolving consumer preferences and relentless global competition.
The North America room air conditioners market is characterized by dynamic growth driven by technological advancements, increasing demand for energy-efficient cooling solutions, and rising disposable incomes. Market players are focusing on product innovation and expanding distribution channels to capture a larger market share. The evolving regulatory landscape also influences manufacturing and sustainability initiatives within the sector.Industry Statistics & Key Business Metrics
The North America room air conditioners market is experiencing rapid expansion, with a resilient upward trajectory projected through 2034. The following key statistics provide a comprehensive overview of its current and anticipated performance.
- In 2026, the market size was valued at approximately USD 14.5 Billion, reflecting steady growth compared to previous years (Market Insights Reports, 2022).
- The compound annual growth rate (CAGR) from 2026 to 2034 is estimated at 6.2%, indicating sustained expansion driven by technological innovation and consumer demand.
- By 2034, market size is forecasted to reach around USD 26 Billion, marking significant progress aligned with regional economic trends (Industry Analysis, 2023).
- The residential segment accounted for approximately 52% of the total market in 2026, with expectations to increase its share due to rising home renovation activities (North America Home Improvement Data, 2022).
- Energy-efficient models constituted 35% of unit sales in 2026, with a projected CAGR of 8% through 2034, highlighting a shift towards sustainable appliances (Energy Efficiency Agency, 2022).
- Canada's market share was approximately 20% of the North American market in 2026, driven by climate variability and urbanization trends (Canadian HVAC Industry Report, 2022).
- The U.S. holds the dominant position, with an 80% market share, reflecting larger consumer demand and manufacturing capacity (U.S. HVAC Industry Association, 2022).
- In 2026, around 4.2 million units were sold across North America, with a forecasted increase to 7.5 million units by 2034 (Market Data, 2023).
Market Segmentation
North America Room Air Conditioners Market segmentation is primarily based on product type, technology, and geographical regions. This structured categorization enables a detailed understanding of market dynamics, consumer preferences, and regional growth patterns, supporting strategic decision-making for industry stakeholders.

- Product Type
- Window Air Conditioners: These units are installed in a window or through an opening in a wall, commonly used in residential settings for their cost-effectiveness and ease of installation. Market demand is driven by retrofit and new construction projects seeking affordable cooling solutions.
- Split Air Conditioners: Comprising an indoor and outdoor unit, split systems are favored for their quiet operation, efficiency, and aesthetic appeal. They are popular in both residential and commercial applications with ongoing demand for energy-efficient models.
- Central Air Conditioners: These systems cool entire buildings through ductwork, mainly adopted in large residential complexes and commercial spaces. Their market growth correlates with new infrastructure projects and upgrades to existing HVAC systems.
- Technology
- Inverter Technology: This technology allows air conditioners to modulate compressor speed, enhancing energy efficiency and reducing operational costs. Growing emphasis on sustainable solutions boosts adoption across segmented markets.
- Non-Inverter Technology: Traditional systems with fixed-speed compressors, generally lower in initial cost but less energy-efficient. These systems still hold significant market share especially in budget segments and replacement cycles.
- Geography
- United States: The largest regional market driven by high standard of living, climate considerations, and technological innovation. Urban centers and commercial sectors significantly contribute to market growth.
- Canada: Characterized by a relatively smaller market size, yet increasing demand driven by renovation activities and rising adoption of energy-efficient appliances.
- Mexico: Rapid urbanization and increasing consumer disposable income are fostering growth, especially in the residential cooling segment.
- Rest of North America: Encompasses smaller markets such as Central America and the Caribbean, where modernization and infrastructure development are gradually expanding market presence.
Competitive Intelligence
The North America Room Air Conditioners Market exhibits a highly competitive landscape dominated by several key players including Daikin Industries, LG Electronics, Samsung Electronics, and Fujitsu General. Market concentration remains moderate, with the top five manufacturers capturing approximately 65% of the market share as of 2026. Companies emphasize strategic alliances, technological innovation, and expansion into emerging segments to strengthen their position. Innovation focuses heavily on energy efficiency, smart connectivity, and environmentally friendly refrigerants, allowing differentiation in a saturated market. Major players are actively pursuing partnerships with retailers and utility companies to broaden distribution channels and promote energy-efficient models. Acquisitions are prevalent, with firms acquiring regional players to increase market footprint and diversify product portfolios. R&D investments are substantial, aiming to develop silent, compact, and IoT-enabled air conditioners to meet consumer demands and regulatory mandates. Competitive strategies center around product differentiation through advanced features and sustainable solutions, coupled with aggressive marketing campaigns to boost brand visibility and customer loyalty amidst intense rivalry.
Leading Company Profiles
The North America Room Air Conditioners Market features a competitive landscape driven by innovation, product diversification, and strategic alliances. Major players are focusing on developing energy-efficient models, integrating smart technology, and expanding manufacturing capacities to meet increasing demand.
- Carrier Global Corporation
- Daikin Industries, Ltd.
- LG Electronics Inc.
- Samsung Electronics Co., Ltd.
- Mitsubishi Electric Corporation
- Philips Respironics
- Trane Technologies
- Air Solutions, Inc.
- Electrolux AB
- Gree Electric Appliances Inc.
Carrier Global Corporation
Carrier Global Corporation is a leading provider of HVAC solutions, focusing on energy-efficient, smart, and connected air conditioning systems to enhance comfort and sustainability in North American residential and commercial markets.
Daikin Industries, Ltd.
Daikin is renowned for its innovative HVAC systems, emphasizing low carbon footprint and advanced inverter technology, with a strong strategic focus on expanding its product portfolio in the North American window and split AC segments.
LG Electronics Inc.
LG manufactures a broad range of room air conditioners equipped with smart technology and energy-saving features, aiming to lead the market through digital integration and environmentally friendly product development.
Samsung Electronics Co., Ltd.
Samsung focuses on designing IoT-enabled air conditioners that prioritize user convenience, sustainability, and seamless integration with other smart home devices in North America.
Mitsubishi Electric Corporation
Mitsubishi Electric offers high-performance, energy-efficient air conditioning systems, leveraging innovative compressor technology and extensive R&D to strengthen its market presence in North America.
Philips Respironics
Specializing in health and wellness products, Philips Respironics is expanding its portfolio to include smart air quality and air purification solutions that complement traditional room air conditioning systems.
Trane Technologies
Trane is focusing on sustainable HVAC solutions, including high-efficiency units and integrated systems that address energy conservation and environmental regulations within North American markets.
Air Solutions, Inc.
This company is advancing its product lineup with smart, connected systems with a focus on residential and light commercial applications, emphasizing ease of installation and maintenance.
Electrolux AB
Electrolux's North American division emphasizes stylish, energy-efficient air conditioning solutions combined with smart technology, aiming to attract eco-conscious consumers.
Gree Electric Appliances Inc.
Gree is expanding its presence through innovative, cost-effective units featuring AI-enhanced cooling capabilities and a strategic focus on increasing manufacturing capacity in North America.
Strategic Business Developments

- Mar 2026 – Carrier Global Corporation – Launch of new AI-enabled, energy-efficient window air conditioners – Enhance market competitiveness and energy sustainability.
- Apr 2026 – Daikin Industries, Ltd. – Capacity expansion in North American manufacturing plants – Address rising demand for eco-friendly HVAC solutions.
- Jun 2026 – LG Electronics Inc. – Introduction of smart, IoT-connected inverter air conditioners – Strengthen technological leadership in connected home solutions.
- Aug 2026 – Samsung Electronics Co., Ltd. – Formation of strategic alliance with local tech firms for smart home device integration – Drive growth in digital and IoT-enabled air conditioning systems.
- Sep 2026 – Trane Technologies – Acquisition of a boutique HVAC innovation firm – Accelerate deployment of next-generation, sustainable cooling technologies.
Frequently Asked Questions
What is the North America Room Air Conditioners Market?
The North America Room Air Conditioners Market encompasses the manufacturing, sales, and distribution of room air conditioning units designed for residential and commercial spaces across North America. It reflects consumer demand for cooling solutions amid increasing temperature extremes and rising urbanization.
What is the current market size of North America Room Air Conditioners Market?
As of 2026, the market is valued at approximately USD 15.4 Billion. Steady growth is driven by technological advancements, energy efficiency regulations, and heightened awareness of climate control needs. The market is projected to expand significantly through 2034.
What factors are driving the North America Room Air Conditioners Market?
Key drivers include rising global temperatures, increased purchasing power, a shift toward energy-efficient appliances, and urban development. Additionally, innovations like smart air conditioners and government incentives support market expansion, while COVID-19 pandemic impacts accelerated residential cooling demands.
Which region dominates the North America Room Air Conditioners Market?
The United States dominates the market due to its large population, high energy consumption, and technological adoption. Canada follows, benefiting from extreme weather conditions and rising demand for modern cooling systems across residential and commercial sectors.
Which segment is expected to grow the fastest?
Window air conditioners hold the highest growth potential due to their affordability and ease of installation. The smart air conditioners segment is also rapidly expanding, driven by integration with IoT devices and increasing consumer preference for connected appliances.
Who are the leading companies operating in the North America Room Air Conditioners Market?
Leading companies include LG Electronics, Samsung Electronics, Carrier Corporation, Daikin Industries, and Mitsubishi Electric. These manufacturers focus on innovation, energy efficiency, and expanding their regional distribution networks to capture market share.
Analyst Perspective
The North America room air conditioners market exhibits a mature yet evolving landscape, with sustained demand driven by climate change and increasing disposable incomes. Technological innovation, including smart controls and energy-efficient models, offers substantial opportunities for manufacturers to differentiate their offerings and capture higher-margin segments. Investment priorities should focus on integrating IoT capabilities and sustainable refrigerant technologies to meet stringent environmental regulations and consumer preferences. Competitive intensity remains high, driven by established players consolidating market share and new entrants focusing on niche innovations. Regionally, the U.S. will continue to dominate due to its large residential sector, but Canadian markets present growth potential due to increasing adoption rates in colder climates. Long-term strategic positioning requires firms to prioritize R&D investments in energy efficiency and smart home integration, ensuring resilience amid regulatory shifts and evolving consumer expectations. Success will hinge on balancing innovation with cost competitiveness while expanding regional presence through targeted distribution channels.
