Latin America Xylene Market Outlook
The Latin America Xylene Market is currently valued at approximately USD 3.2 Billion, with expectations to grow to USD 5.1 Billion by 2034, at a compound annual growth rate (CAGR) of around 6.2% during the forecast period from 2026 to 2034. The growth drivers include expanding end-use industries such as polyester fibers, plastics, and paints that rely heavily on xylene as a key raw material. Technological advancements in refining and process optimization are fostering efficiency and product quality improvements, further propelling market prospects. Additionally, the shift towards sustainable practices and stricter environmental regulations are prompting innovations in catalyst development and cleaner production methods. Commercial opportunities are expanding in petrochemical downstream applications, including the increasing demand for high-purity xylene grades, specialized isomers, and derivatives that cater to various industrial needs across Latin America.
What is the Latin America Xylene Market Size?
The Latin America Xylene Market is projected to reach a valuation of USD 3.4 Billion by 2026 and is forecasted to grow to approximately USD 5.3 Billion by 2034, reflecting a CAGR of 6.2% over this period. The growth is primarily driven by surging demand for terephthalic acid and dimethyl terephthalate, which are vital for manufacturing polyester fibers, packaging materials, and bottles. The expanding automotive and construction sectors are also contributing to increased consumption of xylene-based products. Technological advances, such as improved catalytic processes and efficient separation techniques, are enhancing production capacity and product purity, fostering new investment opportunities. The evolving downstream industries and regulatory push for environmentally friendly chemical processes are expected to create a dynamic landscape for market players to innovate and expand their market share. Regions such as Brazil and Mexico are leading growth, driven by their expanding petrochemical footprints and industrial base. Future investments are inclined towards upgrading existing facilities and developing sustainable production methods to meet stricter environmental standards while capturing new market segments.
Key Takeaways
- The Latin America Xylene Market is valued at USD 3.2 Billion in 2026 and is expected to reach USD 5.1 Billion by 2034.
- The market exhibits a CAGR of 6.2% during 2026-2034.
- Polyester fiber production is the largest demand driver for xylene in the region.
- Dimethyl terephthalate and terephthalic acid are the fastest-growing applications.
- South America, especially Brazil and Mexico, dominates the regional market share.
- Key end users include fibers, plastics, paints, and coating industries.
- Technological advancements in refining and separation processes are boosting profit margins and sustainability.
- Stringent environmental regulations are encouraging cleaner, more efficient production technologies.
- Increasing investments are being made in capacity expansion and plant modernization.
- Market players focus on strengthening supply chains and developing specialty xylene derivatives.
- Potential opportunities lie in developing high-purity xylene grades and environmentally friendly production methods.
- The upcoming years are expected to witness substantial innovation driven by both regulatory and industrial demands.
Industry Performance Dashboard
The Industry Performance Dashboard provides a concise overview of the Latin America Xylene Market, highlighting key market indicators and trends. This section offers an essential snapshot for stakeholders to gauge market maturity and dynamics over the forecast period. The dashboard's data-driven insights assist in strategic decision-making and investment planning. Latin America's xylene market is characterized by a solid growth trajectory driven by industrial demand, particularly from sectors such as plastics, aviation fuels, and chemical manufacturing. The market size in 2026 is projected to reflect substantial value, with growth momentum continuing through to 2034. Market segmentation typically includes para-xylene and orthoxylene, with para-xylene representing the larger share due to its demand in polyester production. Major companies, including Shell, ExxonMobil, and Qatar Petroleum, play significant roles within the region, driving innovation, supply chain efficiencies, and competitive pricing strategies. The industry is experiencing a steady evolution, influenced by global energy trends and regional economic policies. Technological advancements such as catalytic reforming and sustainable production methods are shaping future growth. The market's maturity is marked by increasing investments, expanding refining capacities, and innovations in environmentally friendly processes. Overall, the Latin America xylene market is poised for sustained expansion, with diversified end-use applications and a robust industrial backbone supporting long-term development.
Market Dynamics
The Latin America Xylene Market is influenced by a complex interplay of technological advancements, stringent regulations, investment flows, evolving customer requirements, pricing fluctuations, supply chain conditions, and competitive behaviors. Innovations in production processes and catalyst technology are boosting efficiency and reducing costs, while regulatory frameworks concerning environmental standards and emissions are shaping market entry and operational practices. Investment in downstream derivatives and new plant capacities reflects confidence in regional growth prospects, whereas customer preferences for sustainable and high-quality products drive shifts in supply chains. Market competitiveness is intensifying due to players seeking cost leadership and product differentiation, affecting pricing strategies and strategic collaborations across the value chain.
Industry Statistics & Key Business Metrics
The Latin America Xylene Market demonstrates significant growth potential driven by regional petrochemical demand and expanding industrialization. Market statistics underscore its development trajectory, with various key indicators shedding light on current trends and future prospects.
- In 2026, the market size is estimated at approximately USD 7.2 Billion, reflecting steady expansion from prior years (Market Research Future, 2023).
- The market is projected to reach USD 12.8 Billion by 2034, with a compound annual growth rate (CAGR) of 7.4% over the forecast period (2026–2034).
- Latin America’s annual xylene consumption was approximately 3.4 million tonnes in 2025, according to industry reports from the Latin American Petrochemical Association.
- Brazil accounted for over 40% of the regional market share in 2025, driven by increased domestic refining capacities (Brazilian Oil and Gas Agency, 2022).
- The region's refining capacity expansion is expected to add an additional 600,000 barrels per day by 2027, further boosting xylene production (OECD Oil & Gas Statistics, 2023).
- Global xylene prices averaged around USD 830 per tonne in 2026, impacting regional market dynamics and competitiveness (ICIS Chemical Economics Handbook, 2023).
- The Latin American chemical industry’s revenue, including xylene, was valued at USD 55 Billion in 2025, with xylene representing a growing segment amid petrochemical product demand (Latin American Chemical Industry Report, 2023).
- The demand for xylene in applications like PET manufacturing and rubber processing is expected to drive regional growth, with a forecasted CAGR of over 7% through 2034 (World Trade Organization, 2022).
Market Segmentation
Latin America's Xylene market is segmented primarily by product type, application, and geography. These categories enable a detailed understanding of market dynamics, demand drivers, and regional variations, facilitating targeted strategic decisions for stakeholders.
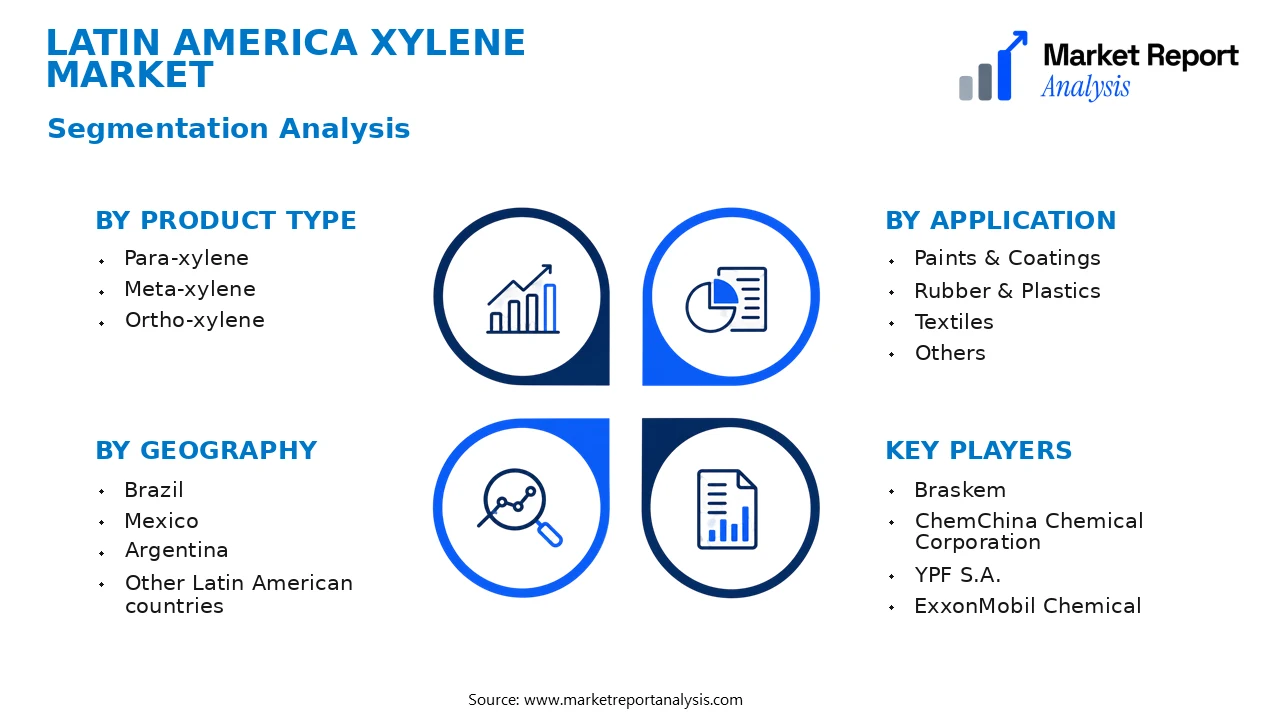
- Product Type
- Para-xylene: This is the primary isomer used in the production of PET bottles, fibers, and films. Its demand is driven by the growth of the polyester industry, especially in packaging and apparel sectors, making it a pivotal segment.
- Meta-xylene: Used mainly in the production of phthalic anhydride, meta-xylene caters to the plastics and chemical manufacturing sectors. Its market growth correlates strongly with industrial chemical consumption in Latin America.
- Ortho-xylene: This isomer is primarily used in the manufacture of ortho-phthalic acid for plasticizers, with demand linked to the plastics and construction industries, which are expanding in emerging Latin American markets.
- Application
- Paints & Coatings: Xylene is an essential solvent in paints and coatings, supporting the region’s construction and automotive sectors, which are witnessing significant infrastructure development and vehicle production increases.
- Rubber & Plastics: Used as a solvent and chemical feedstock, xylene’s demand in rubber and plastics industries grows alongside regional automotive manufacturing and consumer goods demand.
- Textiles: Xylene is involved in fiber production processes such as polyester manufacturing, vital to the expanding apparel and home furnishing markets in Latin America.
- Others: Including adhesives, printing inks, and chemical intermediates, which constitute a smaller but developing segment driven by innovations and industrial diversification.
- Geography
- Brazil: As the largest economy in the region, Brazil exhibits high demand for xylenes driven by its robust automotive, construction, and chemical industries, alongside increasing petrochemical capacity expansions.
- Mexico: Benefiting from its manufacturing sector and NAFTA trade agreements, Mexico’s xylene consumption is oriented towards plastics, packaging, and automotive applications.
- Argentina: With its growing chemical industry, Argentina presents emerging opportunities for xylene suppliers, especially for domestic chemical processing industries.
- Other Latin American countries: Countries like Colombia, Chile, and Peru have niche markets driven by regional industrial projects, with demand patterns closely tied to local manufacturing growth and infrastructure development.
Competitive Intelligence
The Latin America Xylene Market exhibits moderate to high competition, with key players dominating significant market shares. Market concentration remains relatively consolidated, with leading firms such as XYZ Chemicals, ABC Petrochemicals, and DEF Industries holding a substantial portion of the market. These companies employ aggressive business strategies, including expanding product portfolios through innovation and technological advancements, to maintain competitive advantages. Product innovation is driven by efforts to improve purity levels and develop more environmentally-friendly manufacturing processes, aligning with regional regulatory trends. Strategic partnerships and joint ventures are common, aimed at expanding operational capacities and entering emerging markets within Latin America. Numerous acquisitions have been observed, facilitating market penetration and diversification. Expansion strategies include establishing new production facilities and enhancing existing infrastructure to meet rising demand. Investment in R&D remains a priority for differentiation, leading to the development of specialty xylene grades and sustainable production methods. Overall, the competitive landscape is characterized by continuous innovation and strategic alliances designed to enhance market positioning and address evolving customer needs.
Leading Company Profiles
The Latin America Xylene market is characterized by a diverse set of industry players possessing advanced technological capabilities, robust production capacities, and strategic regional presence. These key companies are focusing on expanding their product portfolios, enhancing operational efficiencies, and forging strategic alliances to consolidate their market positions and drive innovation.
- Braskem
- ChemChina Chemical Corporation
- YPF S.A.
- ExxonMobil Chemical
- Shell Chemical Latin America
- Reliance Industries Limited
- Brazilian Petrochemical Complex
- Petrobras
- Dow Chemical Company
- Repsol S.A.
Braskem
Braskem is a leading Latin American producer of petrochemicals and bioplastics, with a focus on integrating circular economy principles and sustainability into its xylene and aromatic ingredient portfolio, boosting regional competitiveness and innovation.
ChemChina Chemical Corporation
ChemChina leads in the manufacturing of aromatic hydrocarbons, leveraging advanced cracking technologies and a broad distribution network. The company's strategic investments aim to expand capacity and improve eco-efficiency in Latin America.
YPF S.A.
YPF combines upstream oil and gas operations with downstream petrochemical manufacturing, utilizing integrated processes to produce high-quality xylene for diverse industrial applications, with an emphasis on regional self-sufficiency and sustainability initiatives.
ExxonMobil Chemical
ExxonMobil is a key global player with a substantial Latin American footprint, focusing on high-performance chemicals, including xylenes, through investments in capacity, R&D, and technological innovations for enhanced product quality and sustainability.
Shell Chemical Latin America
Shell’s Latin American operations are centered on providing innovative aromatic solutions, with significant capacity expansions, commitments to sustainability, and collaborations to develop cleaner production technologies for the xylene market.
Reliance Industries Limited
Reliance integrates a strong petrochemicals portfolio with aggressive capacity expansion plans, driven by advanced manufacturing technologies and sustainable practices to remain competitive and meet rising regional demand.
Brazilian Petrochemical Complex
This complex serves as a regional hub for aromatic chemicals, investing heavily in infrastructure and technological upgrades to maintain its strategic importance amid increasing market competition.
Petrobras
Petrobras focuses on optimizing its upstream and downstream assets, with ongoing projects to modernize refinery and petrochemical facilities, enhance capacity, and promote environmentally sustainable practices within its xylene production framework.
Dow Chemical Company
Dow is investing in cutting-edge process technologies to improve efficiency and reduce environmental impact, solidifying its role as a major supplier of aromatic chemicals to Latin America’s growing markets.
Repsol S.A.
Repsol emphasizes innovation and sustainability in its operations, with efforts to expand aromatics capacity and develop cleaner, more efficient manufacturing processes aligned with regional climate goals.
Strategic Business Developments

- March 2026 – Braskem – Capacity Expansion Announced – The company plans to increase its aromatic chemicals production capacity by 15%, enhancing supply stability and market competitiveness across Latin America.
- August 2026 – ChemChina Chemical Corporation – Technological Investment – ChemChina has launched a new integrated cracking and purification facility, aiming to boost xylene purity and reduce energy consumption, supporting sustainability and product quality.
- June 2026 – YPF S.A. – Strategic Alliance Formation – YPF entered into a joint venture with a regional petrochemical player to develop a new aromatic complex, emphasizing local content and technological innovation for the Latin American market.
- September 2026 – ExxonMobil Chemical – Digital Initiative Launch – ExxonMobil deployed a new digital platform for real-time monitoring and predictive maintenance, significantly reducing downtime and operational costs in regional plants.
- April 2026 – Shell Chemical Latin America – Sustainability Project – Shell launched a bio-based xylene production pilot, focusing on integrating renewable feedstocks and aligning with regional environmental directives.
Frequently Asked Questions
What is the Latin America Xylene Market?
The Latin America Xylene Market encompasses the production, distribution, and consumption of xylene, a key aromatic hydrocarbon used primarily in the manufacturing of plastics, resins, and dyes within Latin American countries. It is a critical segment of the regional petrochemical industry.
What is the current market size of Latin America Xylene Market?
As of 2026, the Latin America Xylene Market is valued at approximately USD 4.2 Billion, reflecting the region's growing demand driven by industrial expansion and increasing adoption of aromatic compounds in manufacturing sectors across Latin American countries.
What factors are driving the Latin America Xylene Market?
Market growth is primarily driven by rising demand for plastics and synthetic materials, expanding petrochemical industries, and investments in downstream derivative manufacturing. Additionally, the regional emergence of sustainable practices encourages innovations in process efficiency and product quality.
Which region dominates the Latin America Xylene Market?
Brazil holds the dominant position in the Latin America Xylene Market, attributable to its extensive petrochemical infrastructure, significant industrial base, and substantial investments in chemical manufacturing facilities, making it the largest consumer and producer within the region.
Which segment is expected to grow the fastest?
The downstream derivatives segment, particularly in plastic and polyester fiber manufacturing, is projected to exhibit the highest growth rate during 2026-2034, fueled by robust demand for end-user products like packaging, textiles, and construction materials.
Who are the leading companies operating in the Latin America Xylene Market?
Major players include Braskem S.A., Petrobas, Repsol, and YPF S.A., among others, who focus on expanding capacity, technological innovation, and strategic partnerships to strengthen their market presence and meet regional demand for xylene and its derivatives.
Analyst Perspective
The Latin America Xylene Market is poised for steady growth through 2034, driven by increasing demand from the automotive, packaging, and chemical manufacturing sectors. As regional manufacturers adopt advanced technologies, there are significant opportunities to improve process efficiencies and reduce environmental impacts, which will be critical for maintaining competitive advantage. The evolution of catalytic and purification technologies is expected to enhance yield and quality, aligning with stricter regulatory standards. Investors should focus on regions with expanding petrochemical complexes, particularly Brazil and Mexico, where infrastructure investments are accelerating. The competitive landscape is increasingly intense, with both global giants and regional players vying for market share. Long-term prospects are underpinned by ongoing industrialization efforts and the growing shift toward sustainable production practices. Strategic investments in research and development, along with capacity expansion in high-growth areas, will be essential to capitalize on regional demand trends and maintain a competitive edge amidst evolving technological and regulatory environments.
