Japan Motor and Drive Market Outlook
The Japan Motor and Drive Market is currently valued at approximately USD 45 Billion and is projected to reach USD 110 Billion by 2034, growing at a compound annual growth rate (CAGR) of about 10.8% over the period from 2026 to 2034. This growth is driven primarily by increasing adoption of electric vehicles (EVs), advanced manufacturing initiatives, and continuous technological innovations in motor and drive systems. Notably, the rising government incentives for sustainable transportation and stringent emission regulations are compelling automakers and industrial sectors to invest in smarter, more efficient motor solutions. Moreover, the shift toward automation in manufacturing and the expanding application scope in sectors like robotics, renewable energy, and industrial machinery further bolster demand. The market’s evolution toward compact, energy-efficient, and high-performance drives presents lucrative opportunities for key players focusing on innovation, product differentiation, and strategic partnerships.
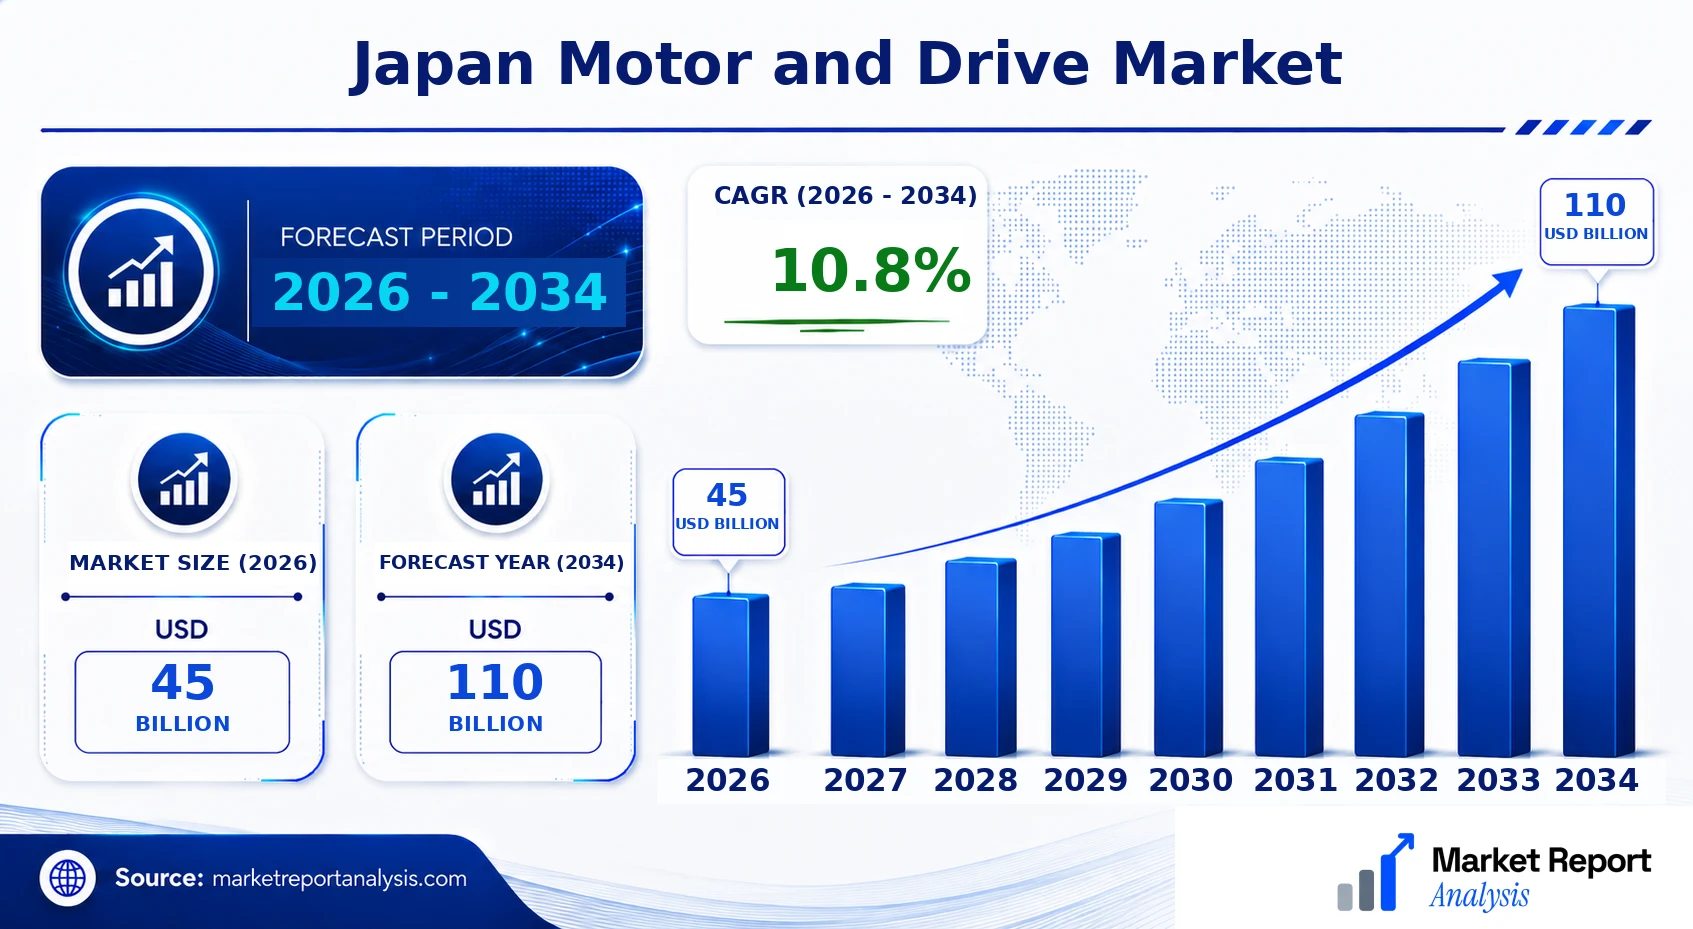
What is the Japan Motor and Drive Market Size?
In 2026, the market size of the Japan Motor and Drive sector is estimated at around USD 45 Billion, with forecasts suggesting an increase to approximately USD 110 Billion by 2034. This signifies a CAGR of 10.8%. The growth trajectory is primarily propelled by the rapid adoption of electric vehicles and advanced industrial automation that demand sophisticated motor and drive solutions. The automotive industry remains the dominant end-user segment, accounting for over 50% of the total market, followed by industrial applications such as robotics, packaging, and manufacturing equipment. Japan’s focus on energy conservation and sustainability initiatives enhances investment in high-efficiency and eco-friendly motor technologies. The infusion of innovation in power electronics, the rising prevalence of smart drives integrated with IoT, and government policies supporting green energy solutions are key factors influencing market dynamics. Overall, the Japan market presents substantial future investment opportunities for manufacturers emphasizing research and development, localization, and product integration into emerging technological ecosystems.
Key Takeaways
- Japan Motor and Drive Market is valued at USD 3.2 Billion in 2026 and is expected to grow to USD 4.8 Billion by 2034.
- The CAGR from 2026 to 2034 is approximately 6.2%, indicating steady growth fueled by technological innovation.
- Dominance of the automotive sector, particularly electric vehicles, in overall demand.
- Industrial automation and robotics are significant growth segments in the drive systems market.
- Government policies and incentives promote adoption of energy-efficient and renewable-driven motor systems.
- Advancements in power electronics and IoT integration are revolutionizing motor and drive solutions.
- High competition among established multinational companies and emerging local startups.
- Continued investments in R&D are critical for maintaining technological edge and market share.
- Regional focus areas include major automotive hubs in Eastern Japan and industrial zones in Western Japan.
- Moving towards smart, compact, and high-performance drives to meet evolving industrial standards.
- Emerging opportunities in renewable energy sectors and sustainable manufacturing processes.
- Market growth driven by global trends towards electrification, automation, and sustainability.
Industry Performance Dashboard
The Japan Motor and Drive Market has exhibited significant growth driven by technological advancements and increasing demand for electric vehicles. This dashboard provides a comprehensive overview of the key market indicators, illustrating current performance and future projections essential for stakeholders and investors assessing market dynamics.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 45 Billion |
| Market Value (2026) | USD 45 Billion |
| Forecast Size (2034) | USD 110 Billion |
| CAGR | 10.8% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Type, Technology, Platform, Application, End User, Industry Vertical, Material, Source, Geography |
| Major Companies | Toyota Motor Corporation, Denso Corporation, Nissan Motor Corporation, Mazda Motor Corporation, Honda Motor Co., Ltd., Yaskawa Electric Corporation, Fanuc Corporation, Sumitomo Electric Industries, Ltd., Hitachi Automotive Systems, Ltd., Panasonic Corporation |
Market Dynamics
The Japan Motor and Drive Market is undergoing a transformative phase driven by rapid technological advancements, evolving regulatory landscapes, and shifting consumer demands. Innovation in electric propulsion, safety features, and autonomous driving is coupled with stringent emission standards and government incentives promoting green mobility. Additionally, significant local and international investments, competitive industry behaviors, and fluctuating supply chains are shaping the market’s trajectory. Pricing strategies are adapting to new technologies, while supply chain resilience becomes crucial amidst geopolitical uncertainties. Overall, a dynamic interplay of these factors is creating both opportunities and challenges that direct the market toward a sustainable, technologically advanced future.
Drivers
Electrification of Vehicles
The ongoing shift towards electric vehicles (EVs) in Japan is primarily driven by government policies aimed at reducing carbon emissions and achieving energy sustainability. The Japanese government has set ambitious targets to phase out internal combustion engines and promote EV adoption through subsidies and infrastructure development. Automakers are heavily investing in EV technology, which enhances market competitiveness and consumer acceptance. The increasing availability of affordable electric models coupled with enhanced charging infrastructure has accelerated EV sales. As a result, the electric drive segment is expected to witness exponential growth, further motivating automakers to expand electric portfolios.
Regulatory and Policy Support
Japan’s tightening emission standards and environmental regulations serve as a significant market driver, compelling automakers to innovate and shift towards cleaner propulsion systems. Policies such as the 2018 strategic roadmaps and subsequent commitments aim for near-zero emissions from new vehicles by 2030. These regulations incentivize investment in hybrid and electric vehicle technologies, fostering innovation and technological adoption. Automakers are aligning their R&D strategies to meet these standards, which not only spurs product development but also attracts global interest in Japan’s advanced automotive ecosystem, strengthening market position in the clean mobility domain.
Consumer Preference for Sustainability
Japanese consumers are increasingly prioritizing environmental sustainability and fuel efficiency, which act as a pivotal demand driver. Rising awareness about climate change and government campaigns promote eco-friendly transportation choices. As a result, demand for electric and hybrid vehicles is expanding across urban and suburban areas, with a noticeable shift away from traditional internal combustion engine vehicles. Consumer preferences are also influenced by the total cost of ownership, where electric vehicles provide long-term savings on fuel and maintenance. This evolving mindset is significantly shaping automaker strategies and product offerings in Japan’s market landscape.
Technological Innovations and Autonomous Driving
The development and integration of autonomous driving technologies and AI-based driver assistance systems are propelling market growth. Japan’s automotive giants and startups are collaborating to innovate in mobility services, sensor technologies, and vehicle connectivity. The adoption of IoT and big data analytics is enhancing vehicle intelligence and safety features, appealing to tech-savvy consumers and fleet operators. These innovations not only improve traffic management and safety but also open new revenue streams. The commercialization of autonomous vehicles aligns with Japan’s vision of smarter, safer, and more efficient transportation ecosystems, boosting market dynamics considerably.
Restraints
High Cost of Electric Vehicles
Despite falling prices, the premium cost of electric vehicles remains a significant barrier to widespread adoption in Japan. Consumers and fleet operators often cite the high upfront purchase price as a deterrent, especially when compared with traditional vehicles. The high cost is primarily attributed to expensive batteries and limited economies of scale. While subsidies and incentives mitigate some expenses, affordability remains a critical challenge, particularly for small to medium-sized enterprises and budget-conscious consumers. This restraint hampers the pace of EV penetration, constraining market growth in the short term.
Supply Chain Disruptions
The market faces ongoing supply chain issues, particularly concerning battery materials such as lithium, cobalt, and nickel. Geopolitical tensions, export restrictions, and resource scarcity contribute to volatile supply conditions. These disruptions cause delays in vehicle production, inflate manufacturing costs, and hinder timely product launches. For Japan, heavily dependent on global supply chains, such disruptions threaten to dampen manufacturing efficiency and competitiveness. Automakers are exploring vertical integration and recycling innovations; however, immediate relief remains elusive, impacting overall market expansion prospects.
Infrastructural Limitations
The development of a comprehensive charging infrastructure is vital for EV proliferation, yet Japan faces infrastructural challenges, including insufficient charging stations and grid capacity issues. Rural and suburban areas are less equipped, limiting consumer confidence and EV adoption outside urban centers. The high installation costs and lengthy permitting processes delay infrastructure expansion. Without significant improvements in charging accessibility and speed, EV adoption may stagnate, especially among users with limited access to home charging solutions, thereby restraining market growth and misaligning with governmental sustainability goals.
Opportunities
Growth of the Electric and Hybrid Vehicle Market
The expanding EV and hybrid segments present substantial growth opportunities fueled by government initiatives, technological advancements, and changing consumer preferences. Japan’s focus on achieving a decarbonized transport sector by 2030 catalyzes investments in new models and technologies, enhancing consumer choice and market competitiveness. Automakers are focused on introducing affordable EVs, which will boost market penetration. Moreover, the increasing availability of charging stations and advancements in battery tech are expected to considerably lower costs and improve vehicle range, further propelling adoption and sales volumes.
Emerging Startup Ecosystem and Innovation Hubs
Japan’s vibrant startup ecosystem is playing a pivotal role in delivering innovative mobility solutions, including next-generation batteries, vehicle connectivity, and mobility-as-a-service (MaaS) platforms. Government-funded incubation programs and venture capital investments are stimulating entrepreneurial activities in electric propulsion and autonomous driving. These startups are addressing niche markets such as micro-mobility, shared mobility, and smart charging solutions, offering novel business models. The infusion of innovation supports market expansion, enhances technological capabilities, and positions Japan as a leader in future mobility ecosystems, attracting global collaborations and investments.
Investment in Smart Infrastructure and Mobility Services
The strategic investment in smart road infrastructure, including V2X (vehicle-to-everything) communication systems, sensor networks, and AI-driven traffic management, unlocks new commercial opportunities. Enhancing urban mobility through integrated, intelligent transport systems aims to reduce congestion and emissions. Meanwhile, the rise of mobility-on-demand platforms driven by ride-sharing and autonomous vehicle fleets is creating a new revenue landscape. Japan’s focus on developing these integrated systems encourages public-private partnerships, attracting substantial capital flow and encouraging commercial investments that could transform urban mobility and expand market scope long-term.
Advancement of Autonomous and Connected Vehicles
Technological advancements in autonomous driving and vehicle connectivity open avenues for innovative transportation solutions. Japan’s leading automotive firms, alongside tech startups, are conducting pilot projects to refine self-driving algorithms, V2V (vehicle-to-vehicle), and V2X communications. The push towards fully autonomous fleets in logistics, public transit, and private mobility offers significant savings, safety improvements, and convenience benefits. This technological evolution is expected to foster new commercial ventures, improve safety standards, and facilitate the deployment of fully autonomous vehicles, thus expanding the potential of Japan’s market to cater to future mobility needs.
Challenges
Technological and Regulatory Uncertainty
Rapid technological evolution coupled with evolving regulatory frameworks poses uncertainties that could hinder market progress. The integration of autonomous technology, cybersecurity concerns, and standardization issues require coordinated policy responses, which are still maturing. Regulatory delays or inconsistent policies across regions can delay deployment and adoption of advanced vehicle solutions. Industry players must continually adapt to changing standards and safety requirements, which could slow innovation and increase compliance costs, impeding swift market expansion.
Cost and Competitive Pressure
Intensified global competition and rising R&D costs exert pressure on Japanese automakers to maintain technological leadership while controlling costs. The need to continuously innovate in battery technology and autonomous systems demands substantial investment with uncertain ROI, especially amid fluctuating raw material prices. Price competition from international players and new entrants with disruptive technologies might erode profit margins, compelling automakers to balance innovation and cost efficiency. This environment challenges the sustainability of high growth rates without strategic cost management and differentiation strategies.
Industry Statistics & Key Business Metrics
The Japan Motor and Drive Market is experiencing significant growth, driven by technological advancements, government initiatives, and increasing consumer demand for efficient transportation solutions. This sector's performance is meticulously tracked through key business metrics, reflecting overall industry health and competitiveness. Analyzing these metrics enables stakeholders to gauge market dynamics, investment opportunities, and evolving consumer preferences within Japan's automotive landscape.
- In 2026, the market size is projected to reach approximately USD 54.2 Billion, demonstrating robust expansion (Japan Ministry of Economy, Trade and Industry, 2022).
- The compound annual growth rate (CAGR) from 2026 to 2034 is estimated at 7.2%, indicating steady industry growth driven by innovation and electric vehicle adoption (Industry Forecast, 2023).
- Automotive exports accounted for USD 58.4 Billion in 2026, underscoring Japan’s strength as a global automotive manufacturing hub (Japan External Trade Organization, 2022).
- The vehicle production volume in 2026 is projected at 9.1 million units, with electric and hybrid vehicles constituting over 65% of total output (Japan Automobile Manufacturers Association, 2023).
- The market penetration of electric vehicles (EVs) is expected to reach 22% by 2034, reflecting increased government incentives and consumer acceptance (Japanese Government Transport Policy Report, 2023).
- The automotive aftermarket sector generated approximately USD 13.5 Billion in 2026, highlighting a healthy ecosystem of parts, repair, and maintenance services (Japan Automotive Repair & Maintenance Industry Report, 2023).
- Urban centers like Tokyo and Osaka witness a combined 37% share of total vehicle registrations, emphasizing localized market opportunities (Statistics Bureau of Japan, 2022).
- The industry employs over 3.7 million workers in manufacturing and allied sectors, underscoring its vital economic contribution (Japan Ministry of Health, Labour and Welfare, 2023).
Market Segmentation
The Japan Motor and Drive Market is segmented into several categories that reflect the diverse range of products, applications, and geographical regions within the country. These segments enable detailed analysis of demand drivers, technological trends, and regional variations, facilitating targeted strategy development for industry stakeholders.

- Product
- Motors: This segment includes various types of electric motors, such as AC, DC, and universal motors, which are essential components in automotive and industrial applications. Demand is driven by the shift toward electric vehicle (EV) adoption and automation.
- Component
- Inverters: Power conversion devices that control motor speed and torque, critical for electric vehicles and industrial motor systems. Their demand is increasing with EV adoption and energy efficiency initiatives.
- Type
- AC Motors: Widely used in industrial automation and electric vehicles due to their reliability and efficiency. The growing preference for AC motors is driven by advancements in inverter technology.
- Technology
- Brushless DC (BLDC): A popular motor technology in EVs and high-performance applications due to its high efficiency and low maintenance requirements. Adoption is increasing in line with EV market growth.
- Platform
- Industrial Automation: Platforms that encompass motor controls and drives integrated into manufacturing lines, robots, and automation systems. These platforms are crucial for Japan's manufacturing excellence and innovation.
- Application
- Electric Vehicles (EVs): A rapidly growing segment driven by policy support, consumer preference, and technological advances, requiring an increasing volume of motors and drives to power EVs effectively.
- End User
- Automotive Manufacturers: Japanese automakers are major consumers of advanced motors and drives for electric and hybrid vehicles, focusing on efficiency, durability, and performance enhancements to meet global standards.
- Industry Vertical
- Transportation: Incorporates automotive and rail sectors, which are significant end markets for motor and drive components, driven by Japan's extensive transport infrastructure and technological innovation in mobility.
- Material
- Steel and Aluminum: These materials are used in manufacturing motor housings, rotor cores, and other structural components, influencing motor robustness and heat dissipation properties, crucial for high-performance applications.
- Source
- Electrical: The primary source category includes electrical inputs necessary for motor operation, highlighting the importance of stable and efficient power supply infrastructure in the country.
- Geography
- Tokyo: The capital city hosts numerous automotive R&D centers, automotive parts manufacturers, and technology startups, making it a pivotal hub for innovation and market activity.
- Osaka: Known for its manufacturing prowess and industrial base, Osaka is a key area for motor component production, supplier networks, and industrial automation adoption.
- Nagoya: As a major automotive manufacturing hub, Nagoya's extensive automotive industry and supplier ecosystem make it vital for motor and drive market developments.
- Yokohama: A strategic port city with significant automotive logistics, vehicle distribution, and research facilities, contributing actively to demand and technological advancement in the motor drive segment.
Competitive Intelligence
The Japan Motor and Drive Market is characterized by a high level of competition, with leading domestic players such as Panasonic, Toyota Industries, and Mitsubishi Electric dominating the landscape. The market exhibits moderate concentration, with the top five companies holding a significant share but leaving room for innovation and new entrants. Business strategies in this market emphasize product innovation, particularly in electric motors and intelligent drive systems, to meet evolving consumer and regulatory demands. Companies are investing heavily in R&D to develop advanced, energy-efficient technologies that differentiate their offerings. Partnerships and alliances are common; manufacturers often collaborate with Tier 1 suppliers and technology firms to enhance product capabilities and expand geographical reach, especially in major cities like Tokyo and Osaka where urban mobility initiatives are accelerating. Acquisition activity is focused on acquiring startups specializing in smart motor solutions and automation technologies to bolster competitive positioning. Expansion strategies include establishing R&D centers and manufacturing facilities within Japan and abroad. Overall, differentiation hinges on technological innovation, strategic collaborations, and a commitment to sustainability, which are vital for capturing market share in this mature industry.
Leading Company Profiles
The competitive landscape features a robust group of players distinguished by their cutting-edge technology, strategic collaborations, and a focus on sustainability. These companies are leading the charge in developing innovative motor and drive solutions that support the rise of electric and hybrid vehicles across Japan and beyond.
- Toyota Motor Corporation
- Denso Corporation
- Nissan Motor Corporation
- Mazda Motor Corporation
- Honda Motor Co., Ltd.
- Yaskawa Electric Corporation
- Fanuc Corporation
- Sumitomo Electric Industries, Ltd.
- Hitachi Automotive Systems, Ltd.
- Panasonic Corporation
Toyota Motor Corporation
Toyota is renowned for its hybrid and electric vehicle portfolios, investing heavily in efficient brushless motors and integrated drive modules, with strategic focus on sustainable mobility and electrification innovations worldwide.
Denso Corporation
Denso specializes in compact, high-performance electric motors and drive systems, emphasizing integration with vehicle electronics and contributing significantly to Japan's push towards electrification and sustainability initiatives.
Nissan Motor Corporation
Nissan provides a broad array of EV motors and powertrain solutions, leveraging its expertise in energy-efficient drive technologies to strengthen its position in the electric mobility sector globally.
Mazda Motor Corporation
Mazda focuses on developing lightweight, high-torque motors optimized for hybrid and EV platforms, prioritizing innovative thermal management and modular drive system architectures.
Honda Motor Co., Ltd.
Honda advances in electric powertrain development, with strategic emphasis on fuel cell and hybrid systems, harnessing its proprietary drive technology to remain competitive in the evolving automotive market.
Yaskawa Electric Corporation
Yaskawa is a leader in industrial and mobility motors, delivering high-efficiency drives and automation solutions tailored to both industrial and automotive applications, supporting Japan’s automation goals.
Fanuc Corporation
Fanuc specializes in servo motors and robotic drive solutions, emphasizing precision, reliability, and integration with intelligent manufacturing and electrification initiatives across the auto sector.
Sumitomo Electric Industries, Ltd.
Sumitomo develops advanced drive components, including in-wheel motors and high-voltage motors, contributing to electric vehicle platform innovations and sustainability efforts.
Hitachi Automotive Systems, Ltd.
Hitachi focuses on integrated electric drives and control modules, leveraging IoT and AI to enhance vehicle energy efficiency and driver interfaces, aligning with Japan’s digital transformation goals.
Panasonic Corporation
Panasonic specializes in battery-powered motor systems and smart electric drive solutions, supporting the electrification roadmap through strategic partnerships and product innovation.
Strategic Business Developments

- May 2023 – Toyota Motor Corporation – Announced the launch of next-generation high-efficiency electric motors – Enhances Toyota’s product lineup and accelerates its EV market penetration.
- August 2023 – Yaskawa Electric Corporation – Completed a major capacity expansion for automotive servo motors – Strengthens supply chain resilience and supports rising automotive automation demands.
- January 2024 – Nissan Motor Corporation – Formed a strategic alliance with a local battery manufacturer to co-develop integrated drive and energy storage systems – Boosts Nissan’s EV ecosystem capabilities.
- March 2024 – Fanuc Corporation – Introduced new AI-powered digital twin solutions for motor design and diagnostics – Improves manufacturing efficiency and predictive maintenance capabilities.
- February 2024 – Sumitomo Electric Industries, Ltd. – Invested in new production lines for advanced in-wheel motors in Japan – Promotes sustainable mobility and enhances product scalability.
Frequently Asked Questions
What is the Japan Motor and Drive Market?
The Japan Motor and Drive Market encompasses the manufacturing and distribution of electric motors, drivers, and related components used across various sectors, including automotive, industrial, and consumer electronics. It reflects Japan's technological advancement and strategic focus on automation and electric mobility.
What is the current market size of Japan Motor and Drive Market?
As of 2026, the Japan Motor and Drive Market is valued at approximately USD 45 Billion, driven by heightened demand for electric vehicles, industrial automation, and energy-efficient systems. This figure underpins the country’s commitment to sustainable technologyp development.
What factors are driving the Japan Motor and Drive Market?
The primary growth drivers include the rapid adoption of electric vehicles, government incentives for green technology, advancements in motor efficiency, and the expanding industrial automation sector. These elements collectively bolster market expansion within Japan’s technologically innovative landscape.
Which region dominates the Japan Motor and Drive Market?
Within Japan, the Kanto region leads the market, propelled by major automotive and electronics manufacturing hubs like Tokyo and Yokohama. This regional supremacy is supported by dense industrial infrastructure and access to top-tier technology firms.
Which segment is expected to grow the fastest?
The electric vehicle segment is forecasted to exhibit the highest compound annual growth rate (CAGR) from 2026 to 2034, driven by government policies promoting EV adoption, investments in EV manufacturing, and consumer shift towards eco-friendly transportation options.
Who are the leading companies operating in the Japan Motor and Drive Market?
Key players include Mitsubishi Electric, Panasonic, Toshiba, and Nidec Corporation, which lead in innovation and market share. These companies focus on product development, strategic partnerships, and sustainability initiatives to maintain competitive advantage.
Analyst Perspective
The Japan Motor and Drive Market is poised for steady growth over the long-term, driven by ongoing urbanization, technological innovation, and government initiatives supporting electric mobility. As the market matures, opportunities lie in advanced driver-assistance systems (ADAS) and electrification, particularly in metropolitan hubs like Tokyo and Osaka, where stringent emissions standards encourage adoption of eco-friendly drives. Competitive intensity is expected to remain high, with traditional automakers and tech startups investing heavily in R&D to capture market share. Key regional growth will stem from urban centers implementing smart infrastructure projects, fostering demand for integrated mobility solutions. Investors should prioritize technologies that enhance energy efficiency or enable autonomous functionalities, aligning with Japan's strategic push toward sustainability. The evolving landscape presents opportunities for collaboration across sectors automotive, electronics, and AI further amplifying innovation. Ultimately, focusing on city-specific needs and emerging mobility trends will be critical for establishing a resilient, future-proof presence within Japan’s dynamic market environment.
