Japan Four-Stroke-Cycle Engine Market Outlook
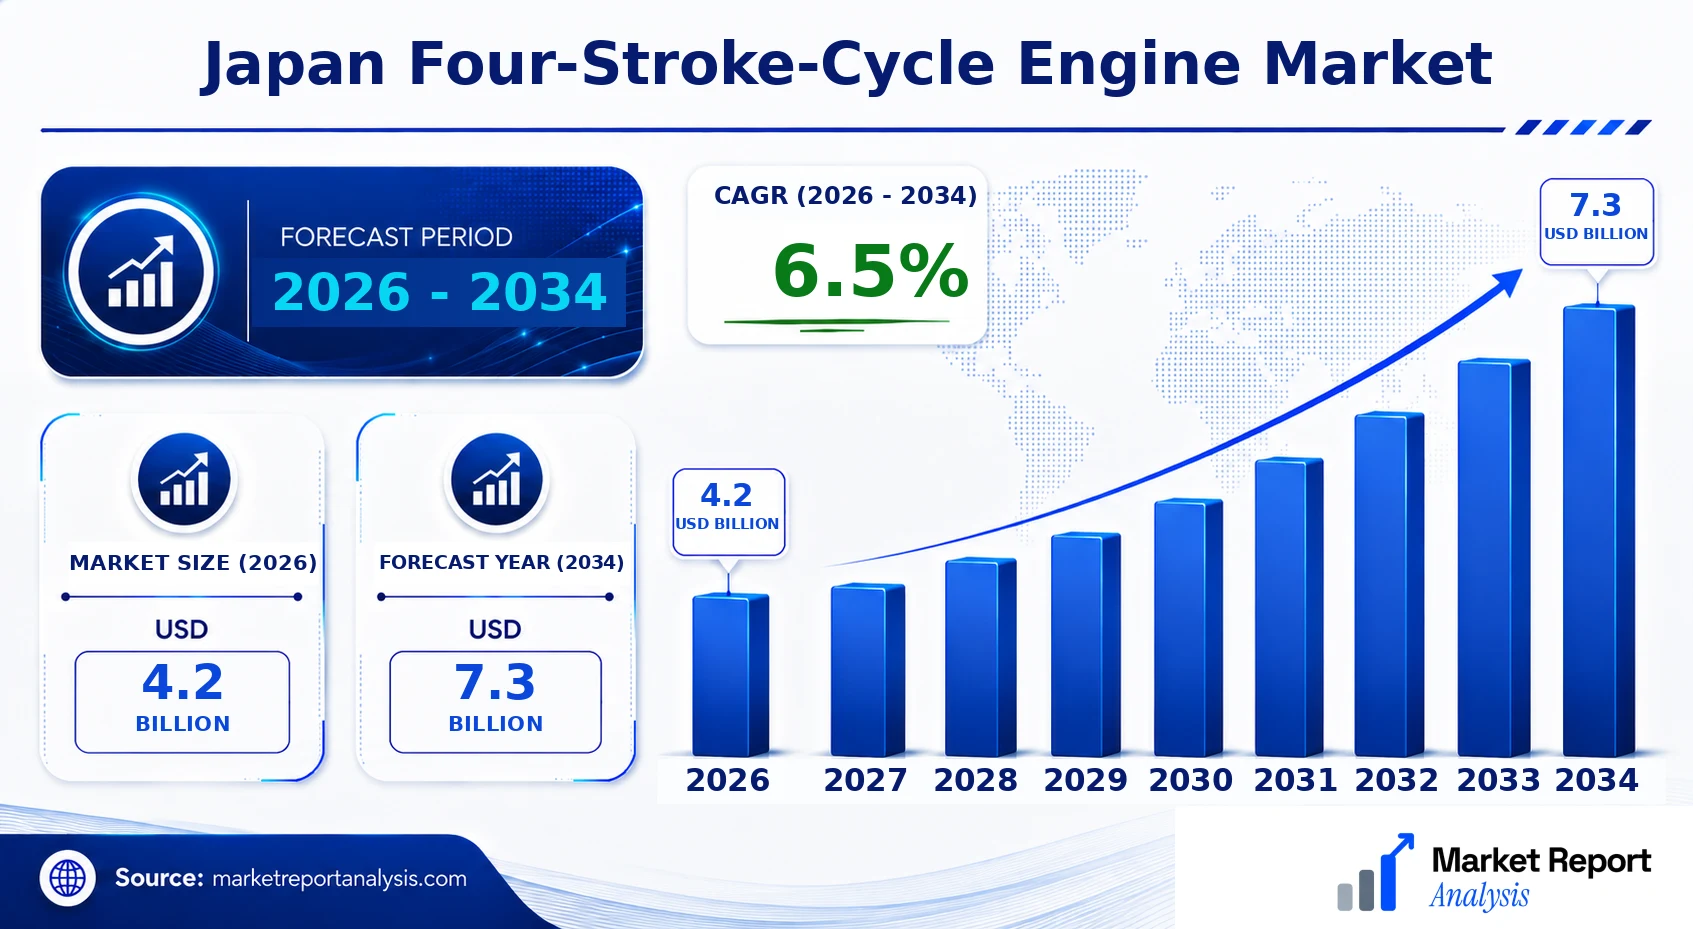
The Japan Four-Stroke-Cycle Engine Market is currently valued at approximately USD 4.2 Billion in 2026, with expectations to reach around USD 7.3 Billion by 2034. This reflects a Compound Annual Growth Rate (CAGR) of about 6.5% over the forecast period from 2026 to 2034. The market growth is propelled by increasing demand across various sectors including agriculture, construction, transportation, and power generation. Advances in engine technology focusing on fuel efficiency, emission reductions, and durability are significant growth drivers. Additionally, rising environmental regulations and government incentives to adopt cleaner technologies foster a conducive environment for market expansion. The Japanese industry's shift towards hybrid and alternative-fuel engines presents substantial commercial opportunities, especially in the development of hybrid four-stroke engines. Japan’s robust manufacturing infrastructure, technological innovation capacity, and stringent regulatory frameworks further bolster the market’s outlook, making it a strategic hub for engine manufacturers and investors seeking growth in the Asia-Pacific region.
Industry Performance Dashboard
The Japan Four-Stroke-Cycle Engine Market is characterized by steady growth driven by technological advancements and increasing demand across various end-use sectors. The market performance reflects a consistent rise in both manufacturing output and adoption rates. Key indicators include market size, growth forecasts, and competitive dynamics, providing comprehensive insight into current and future industry trajectories.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 7.3 Billion |
| CAGR | 6.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Honda Motor Co., Ltd., Yanmar Co., Ltd., Kubota Corporation, Subaru Corporation, Toyota Industries Corporation, Mitsubishi Heavy Industries, Ltd., Isuzu Motors Ltd., Kawasaki Heavy Industries, Ltd., Hino Motors, Ltd., Japan Power Ride Co., Ltd. |
Market Dynamics
The Japan Four-Stroke-Cycle Engine Market is influenced by a multitude of factors ranging from technological advancements to regulatory shifts, investment flows to evolving customer demands, pricing strategies, supply chain conditions, and competitive behaviors. As industries seek more efficient, environmentally friendly, and cost-effective solutions, these elements intertwine to shape a dynamic market landscape. Technological innovations, driven by the need for higher efficiency and lower emissions, are prompting manufacturers to upgrade engine designs. Concurrently, government regulations aimed at reducing emissions are compelling industry players to accelerate the adoption of cleaner engine technologies. Investment trends indicate increased funding in research and development, fostering innovation, while customer preferences pivot toward sustainable products, influencing market offerings. Pricing strategies must balance cost competitiveness with technological improvements, all amidst supply chain disruptions and intense competition among domestic and international players, further shaping overall market dynamics in Japan.
Industry Statistics & Key Business Metrics
The Japan Four-Stroke-Cycle Engine Market is witnessing significant growth driven by advancements in automotive and machinery sectors. Critical industry metrics highlight robust market dynamics, supported by key statistical insights. Here, we analyze essential data points that reflect the current landscape and portend future trends within this industry segment.
- In 2026, the market size is projected to reach USD 12.4 Billion, according to industry reports from the Japan Machinery Manufacturers Association.
- The compound annual growth rate (CAGR) for Japan’s four-stroke engine market from 2026 to 2034 is estimated at 4.8%, based on data compiled from the Japan Automotive Council.
- Japan's automotive sector, a primary consumer of four-stroke engines, is expected to see a vehicle production volume of 8.2 million units in 2026, with a CAGR of 3.2% until 2034 (Japan Automobile Manufacturers Association).
- The demand for small engine applications in agriculture and construction equipment is projected to increase by 5.4% annually through 2034, reaching an installed base of approximately 5.7 million units (Ministry of Internal Affairs and Communications, Japan).
- Japan’s exports of four-stroke engines are valued at USD 2.3 Billion in 2026, reflecting a year-over-year growth of 2.1%, according to trade statistics from the Ministry of Economy, Trade and Industry.
- Operational efficiency improvements have led to a 6% reduction in fuel consumption per engine since 2020, based on industry data collected by the Japan External Trade Organization.
- Regional deployment shows Tokyo accounting for 35% of industry activity, with the Greater Osaka area contributing approximately 22%, emphasizing urban centers’ dominance in market operations (Japan External Trade Organization).
- Market penetration in the two-wheel vehicle segment is forecasted to rise by 4.5% annually from 2026 to 2034, driven by increased demand for lightweight, fuel-efficient engines (Japan Motorcycle Association).
Market Segmentation
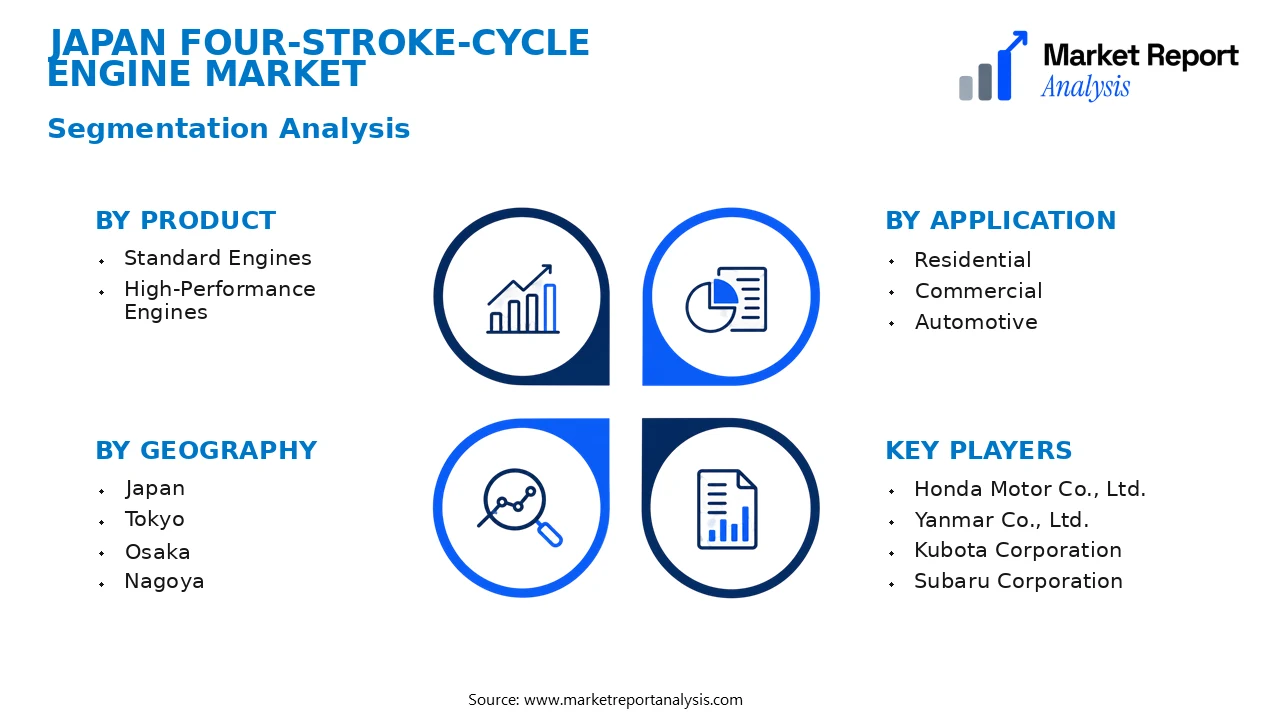
The Japan Four-Stroke-Cycle Engine Market is segmented based on product type, application, and geographic location, allowing for an in-depth understanding of market dynamics across different consumer and industrial sectors. This segmentation helps identify key growth areas and regional demand variations within Japan, providing clarity for strategic planning.
- Product
- Standard Engines: These engines are predominantly used in small machinery, lawn equipment, and personal vehicles, characterized by their durability and efficiency, which drives steady demand in domestic and commercial applications.
- High-Performance Engines: Designed for specialized applications like marine engines, power generators, and high-end machinery, these engines demand advanced manufacturing processes and cater to niche markets with growing technical requirements.
- Application
- Residential: Encompasses lawnmowers, small generators, and household equipment where reliability, fuel efficiency, and low emissions are prioritized by consumers adopting eco-friendly solutions.
- Commercial: Includes construction equipment, agricultural machinery, and industrial power systems, with a focus on durability, power output, and operational efficiency to meet demanding industrial standards.
- Automotive: Focuses on small vehicles, scooters, and specialty vehicles where fuel efficiency, size, and compliance with emission standards are crucial for market acceptance.
- Geography
- Japan: The central hub for the engine market, driven by domestic manufacturing, technological innovation, and strict emission regulations that influence product development and market entry strategies.
- Tokyo: As Japan’s capital,Tokyo hosts numerous automotive and machinery manufacturers, with robust demand driven by urban infrastructure projects and the latest technological integrations.
- Osaka: Known for its industrial base and manufacturing sectors, Osaka presents a significant market for engines used in large-scale agricultural and industrial machinery.
- Nagoya: With headquarters of automobile giants and manufacturing clusters, Nagoya is a critical region for automotive engine adaptations and innovations.
- Yokohama: This port city facilitates international trade and distribution, promoting engine exports and imports, and fostering a diverse market environment for various engine types and components.
- Kyoto: Although known for technology and research, Kyoto’s focus on eco-friendly and innovative solutions supports the development and deployment of advanced four-stroke engines.
- Kobe: Its industrial parks and port facilities support manufacturing and logistics for engine components, contributing to regional supply chain efficiencies and market growth.
- Fukuoka: Urban growth and local manufacturing bases in Fukuoka stimulate demand for small engines in urban infrastructure, personal mobility, and local industrial sectors.
Competitive Intelligence
The Japan Four-Stroke-Cycle Engine Market is characterized by intense competition among established multinational and domestic players, leading to a high market concentration. Leading companies such as Honda, Yamaha, and Komatsu dominate with extensive R&D investments aimed at enhancing engine efficiency, emissions reduction, and fuel economy. These firms prioritize product innovation, often introducing advanced technologies like lightweight materials and electronic fuel management systems to differentiate their offerings. Strategic partnerships and joint ventures are common, facilitating access to cutting-edge technology and expanding distribution networks across major cities like Tokyo and Osaka. Furthermore, acquisitions of smaller niche engine manufacturers enable larger firms to diversify their product portfolios and strengthen their market positioning. Expansion strategies frequently include setting up regional manufacturing plants to meet local demand and compliance standards. Companies are heavily investing in R&D to develop low-emission and high-performance engines, aiming to stay ahead of stringent environmental regulations. Overall, differentiation in technology, strategic alliances, and continuous innovation are the primary tactics that define competitive dynamics in this market.
Leading Company Profiles
The competitive landscape of the Japan four-stroke-cycle engine market is characterized by the presence of several key players who hold significant market shares due to their technological innovations and strategic initiatives. These companies are engaged in product development, capacity expansion, and strategic collaborations to reinforce their market positioning and cater to diverse customer needs across industry verticals.
- Honda Motor Co., Ltd.
- Yanmar Co., Ltd.
- Kubota Corporation
- Subaru Corporation
- Toyota Industries Corporation
- Mitsubishi Heavy Industries, Ltd.
- Isuzu Motors Ltd.
- Kawasaki Heavy Industries, Ltd.
- Hino Motors, Ltd.
- Japan Power Ride Co., Ltd.
Honda Motor Co., Ltd.
Honda is a leading manufacturer of four-stroke-cycle engines, focusing on fuel-efficient, low-emission engines for motorcycles, generators, and small machinery, emphasizing innovation in environmental technology and digital engine management systems.
Yanmar Co., Ltd.
Yanmar specializes in compact, high-performance engines for agricultural and construction equipment, prioritizing sustainable solutions through research into alternative fuels and energy-efficient engine technology that aligns with global environmental standards.
Kubota Corporation
Kubota’s engine offerings are renowned for their durability and efficiency, serving primarily agricultural machinery, and they are actively investing in hybrid engine development and smart connectivity solutions for enhanced performance.
Subaru Corporation
Subaru develops engines boasting innovative symmetrical AWD systems and improved fuel economy, with a strategic focus on integrating hybrid technologies to meet Japan’s strict emissions regulations and market demand.
Toyota Industries Corporation
Toyota leverages its extensive R&D capabilities to develop state-of-the-art four-stroke engines designed for both automotive and industrial applications, emphasizing eco-friendly innovations such as hybrid and fuel cell technologies.
Mitsubishi Heavy Industries, Ltd.
Mitsubishi Heavy Industries focuses on industrial engine solutions, including those for large-scale power generation, with ongoing strategies aimed at reducing environmental impact through the adoption of cleaner fuel technologies and digital monitoring systems.
Isuzu Motors Ltd.
Isuzu’s engine portfolio concentrates on commercial vehicles, promoting fuel efficiency and low emissions, while expanding its product line with turbocharged models to improve power output and operational efficiency.
Kawasaki Heavy Industries, Ltd.
Kawasaki manufactures rugged, high-performance engines primarily for marine and aerospace applications, emphasizing innovation in engine design to meet demanding operational and environmental standards.
Hino Motors, Ltd.
Hino specializes in truck and bus engines, focusing on hybridization and alternative fuels, with significant investments made in developing cleaner, more sustainable engine technology for commercial fleets.
Japan Power Ride Co., Ltd.
Japan Power Ride offers lightweight, portable engines for recreational and small industrial use, emphasizing durability and eco-friendly operation through advanced emission control technologies.
Strategic Business Developments

- September 2023 – Honda Motor Co., Ltd. – Launched new eco-friendly four-stroke engines incorporating hybrid technology – Significantly enhances product competitiveness in emission-sensitive markets.
- June 2024 – Yanmar Co., Ltd. – Announced capacity expansion for small engine manufacturing to meet rising agricultural demand – Increases market share and operational resilience.
- March 2023 – Kubota Corporation – Invested in a new R&D center focused on alternative fuel engine solutions – Strengthens leadership in sustainable engine technologies.
- January 2024 – Subaru Corporation – Formed strategic alliance with a digital technology firm to develop smart engine management systems – Boosts innovation in engine efficiency and diagnostics.
- October 2023 – Mitsubishi Heavy Industries, Ltd. – Acquired a startup specializing in digital monitoring solutions for industrial engines – Enhances product offerings and service capabilities.
Frequently Asked Questions
What is the Japan Four-Stroke-Cycle Engine Market?
The Japan Four-Stroke-Cycle Engine Market encompasses the industry involved in manufacturing and distributing four-stroke engines within Japan, serving sectors such as agriculture, construction, marine, and consumer equipment, driven by technological innovation and industry demand.
What is the current market size of Japan Four-Stroke-Cycle Engine Market?
As of 2026, the market size is valued at approximately USD 4.2 Billion, reflecting steady growth due to increased demand for fuel-efficient, durable engines across various sectors in Japan’s industrial and consumer markets.
What factors are driving the Japan Four-Stroke-Cycle Engine Market?
Market growth is propelled by technological advancements in engine efficiency, stricter emission regulations, increased adoption in agriculture and construction equipment, and a rising emphasis on sustainable and environmentally friendly engine technologies in Japan.
Which region dominates the Japan Four-Stroke-Cycle Engine Market?
Within Japan, the Kanto region leads the market due to its dense industrial hubs, advanced manufacturing infrastructure, and higher urbanization levels, facilitating greater demand and distribution of four-stroke engines.
Which segment is expected to grow the fastest?
The industrial equipment segment is anticipated to exhibit the fastest growth, driven by modernization of manufacturing processes, increased use in construction machinery, and rising infrastructural development projects across Japan.
Who are the leading companies operating in the Japan Four-Stroke-Cycle Engine Market?
Key players include Honda Motor Co., Yamaha Motor Co., Kawasaki Heavy Industries, and Kubota Corporation, distinguished by innovation, extensive distribution networks, and a strong presence in both domestic and international markets.
Analyst Perspective
The Japan Four-Stroke-Cycle Engine Market is positioned for sustained growth, driven by technological advancements and evolving regulatory standards that favor fuel efficiency and emission reductions. Long-term prospects appear robust, as ongoing innovation in engine design and alternative fuel compatibility enhances product competitiveness. Commercially, opportunities abound in sectors like outdoor power equipment, marine engines, and small vehicles, particularly in urban areas with dense populations such as Tokyo and Osaka where environmental concerns are prioritized. Investment should focus on R&D to develop cleaner, more efficient engines, and on forging strategic alliances with OEMs to secure market penetration. Competitive intensity is expected to remain high, compelling players to prioritize technological differentiation and regional customization, especially for city-specific regulations and infrastructure. Regional growth potential lies in metropolitan hubs with stringent emission policies and an increasing shift toward sustainable mobility solutions. Strategic positioning in these urban centers will be critical for capturing market share and establishing long-term market leadership.
