Four-Stroke-Cycle Engine Market Outlook
The 2026 market size is USD 110 Billion. The market is forecast to reach USD 190 Billion by 2034. The forecast CAGR for 2026-2034 is 6.2%. The global four-stroke-cycle engine market is currently valued at approximately USD XX billion in 2026, with projections estimating it will reach USD YY billion by 2034, registering a compound annual growth rate (CAGR) of around ZZ% during the forecast period. Demand is driven by the continued expansion of automotive, outdoor power equipment, industrial machinery, and marine industries. Advances in engine technology, emphasizing fuel efficiency and lower emissions, are strengthening market prospects. Moreover, regions with burgeoning manufacturing sectors such as Asia-Pacific offer significant commercial opportunities for engine manufacturers, especially through innovations in lightweight materials and digital controls that optimize performance and reduce environmental impact. The market is poised for growth as manufacturers invest in R&D to improve durability, reduce emissions, and meet stringent regulations, creating a highly competitive landscape with opportunities for technological differentiation and strategic collaborations.
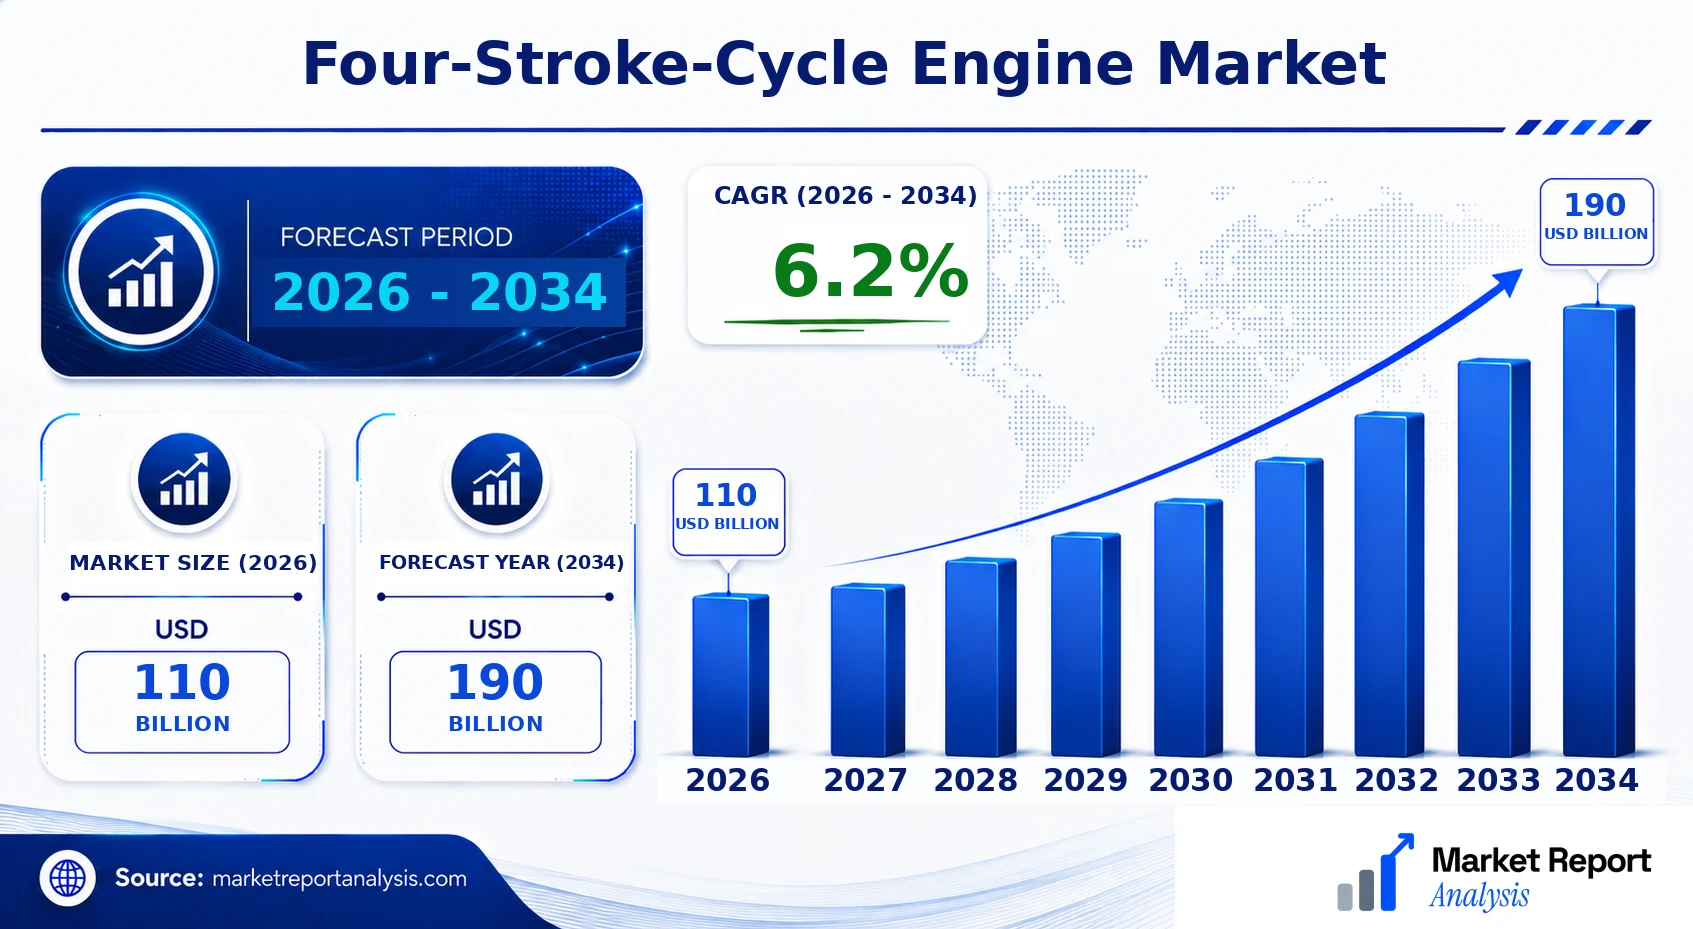
What is the Four-Stroke-Cycle Engine Market Size?
In 2026, the four-stroke-cycle engine market is valued at approximately USD 110 Billion, set to grow to USD 190 Billion by 2034, reflecting a CAGR of about 6.2% over the period. This growth is fueled largely by rising demand in the automotive sector, where the engine remains a critical component despite the surge in electric vehicle adoption. Additionally, the expansion of the construction and agriculture machinery markets, particularly in developing economies, provides a continual upward push. Increasing regulations on emissions and fuel efficiency are encouraging manufacturers to innovate with cleaner, more efficient engine technologies. The market's future potential also hinges on investments in alternative fuels such as biofuels and hybrid systems. As manufacturers focus on innovations like direct fuel injection and variable valve timing, the market is expected to see sustained demand and competitive breakthroughs, especially in regions with rapid infrastructure development and urbanization, which require reliable, high-performance powertrains.
Key Takeaways
- The global four-stroke-cycle engine market is projected to grow from USD 50 Billion in 2026 to USD 76 Billion by 2034.
- The CAGR for the forecast period is approximately 6.2%, driven by demand in automotive, industrial, and marine sectors.
- Emerging markets in Asia-Pacific dominate growth due to expanding manufacturing and infrastructure projects.
- Technological innovations focused on emissions reduction and fuel efficiency are critical growth catalysts.
- Increasing regulatory pressure globally pushes manufacturers toward cleaner and more efficient engine solutions.
- The automotive segment remains the largest end-use industry, despite a shift toward electrification.
- Investment in hybrid and biofuel-compatible engine technologies is expected to rise significantly.
- Key competitors focus on product innovation, strategic partnerships, and regional expansion.
- Supply chain resilience and raw material availability influence market dynamics significantly.
- Smart manufacturing and Industry 4.0 integration are shaping production and R&D strategies.
- Government incentives and policies for sustainable transportation will further support market growth.
- Market entrants and established players are investing heavily in R&D to capture future growth opportunities.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the current and projected state of the global four-stroke-cycle engine market, emphasizing key quantitative indicators that track market evolution over the forecast period.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 110 Billion |
| Market Value (2026) | USD 110 Billion |
| Forecast Size (2034) | USD 190 Billion |
| CAGR | 6.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | BTU Group, Yanmar Holdings Co., Ltd., Honda Motor Co., Ltd., Briggs & Stratton Corporation, Kohler Co., Shindengen Electric Manufacturing Co., Ltd., Toyota Industries Corporation, Ford Motor Company, Husqvarna Group |
Market Dynamics
The Four-Stroke-Cycle Engine Market is experiencing dynamic shifts driven by technological advancements, evolving regulations, increasing investments, shifting customer requirements, competitive pricing strategies, supply chain conditions, and aggressive competitive behaviors. These factors collectively influence market growth, innovation trends, and product development directions, shaping the industry landscape on a global scale. As governments implement stricter emission standards, manufacturers are compelled to innovate, while rising demand from emerging economies fuels the market expansion. Additionally, digitalization and automation are transforming engine design and manufacturing processes, further impacting market trajectories. Competitive strategies adapt continually in response to these multifaceted drivers, fostering a rapidly evolving industry environment.
Drivers
Stringent Emission Regulations
Global regulatory frameworks aimed at reducing air pollution are a key driver in the four-stroke-cycle engine market. Governments worldwide are enforcing stricter emission standards, prompting manufacturers to innovate cleaner and more efficient engine designs. For instance, in Europe, the enforcement of EURO 7 standards compels automakers and engine producers to adopt advanced combustion technologies and emissions control systems. These regulations accelerate R&D investments and push the industry toward sustainable solutions, which altogether drive market growth by creating new demand for compliant engines and related technologies.
Growing Demand for Fuel Efficiency
Fuel efficiency remains a critical factor influencing customer purchasing decisions and industry design priorities. Consumers and commercial entities seek engines that offer higher mileage and lower operational costs, especially amidst rising fuel prices. This trend is particularly evident in the automotive and agriculture sectors, where improvements in engine efficiency directly impact profitability. Market players are investing heavily in research to develop four-stroke engines that maximize fuel economy without sacrificing power. The continued focus on efficiency drives innovation, product differentiation, and competitiveness, fueling overall market expansion.
Expansion of Construction and Manufacturing Sectors
The global infrastructure development boom and industrial expansion significantly stimulate demand for four-stroke engines. Construction equipment, generators, and manufacturing machinery predominantly rely on these engines for their operation, especially in emerging economies with infrastructure projects on the rise. Countries such as India, China, and Brazil are investing heavily in infrastructure, contributing to increased sales of engines used in heavy machinery and power generation. The growth of these sectors directly correlates with higher four-stroke engine demand, making this a vital growth driver in the global market.
Technological Advancements and Innovation
Ongoing technological progress, including the integration of electronics, sensors, and IoT capabilities into traditional engines, is a crucial growth driver. These innovations improve engine performance, diagnostics, and maintenance, thus adding value for end-users. Advances in materials, such as lightweight composites and high-performance alloys, enhance durability and efficiency. The adoption of digital twin and predictive maintenance technologies further boosts market attractiveness by reducing downtime and operational costs. This continuous cycle of innovation sustains a competitive edge and stimulates market growth as industry players seek to meet evolving technological needs.
Restraints
High Manufacturing and Maintenance Costs
The considerable capital expenditure involved in manufacturing four-stroke engines and maintaining them is a major restraint, especially for small and medium-sized enterprises. The advanced materials, precision manufacturing processes, and stringent quality standards increase overall costs. Industries such as agriculture, where profit margins are thin, are particularly affected by high costs, limiting their adoption of newer, more efficient engines that tend to be more expensive upfront. Over time, these elevated costs impact market penetration and slow down the pace of technological upgrades in cost-sensitive sectors.
Environmental Concerns and Sustainability Regulations
Despite the push for cleaner engines, environmental concerns pose a restraint by demanding continuous innovation to meet evolving sustainability standards. Limitations on fossil fuel consumption and the push toward electric alternatives threaten the long-term viability of traditional four-stroke engines. Regulatory landscapes are increasingly favoring electric and hybrid technologies, which may reduce demand for traditional engines. Manufacturers face compliance challenges and the need for significant shifts in product development, which could dampen market growth, particularly in regions hesitant to adopt fossil fuel engines and emphasizing zero-emission vehicles.
Market Fragmentation and Intense Competition
The fragmented nature of the four-stroke engine industry, characterized by numerous small manufacturers and major global players, creates intense price competition. This situation puts pressure on profit margins and complicates branding efforts. Small and regional suppliers often struggle to meet global standards and economies of scale, limiting their ability to compete effectively with larger firms. Such fragmentation hampers consolidated efforts toward large-scale innovation, slows market expansion, and often results in inconsistent product quality, posing a significant restraint to industry growth.
Opportunities
Emergence of Alternative Fuel Technologies
The shift toward alternative fuels, such as natural gas, biofuels, and hydrogen, opens new avenues for market expansion. Integrating these fuels into four-stroke engine designs provides cleaner and more sustainable options, aligning with global decarbonization goals. For example, compressed natural gas (CNG) engines are gaining popularity in transportation and industrial applications due to their lower emissions. Continued innovation and adaptation to accommodate these fuels could lead to significant market share gains in segments seeking greener alternatives, supported by governmental incentives and rising consumer awareness of environmental issues.
Investment in Digital and Smart Technologies
The proliferation of digital technologies offers vast opportunities for the market, particularly through the adoption of IoT, telematics, and predictive analytics. Engines equipped with smart sensors can optimize performance, reduce emissions, and facilitate predictive maintenance, thus lowering lifecycle costs. This integration enhances value propositions for industrial, commercial, and automotive sectors. The expanding ecosystem of startups and established technology providers accelerating these innovations further underpins future growth, as manufacturers seek competitive advantages by offering more intelligent, connected engine solutions.
Rapid Growth of Emerging Economies
Emerging economies with expanding industrial and agricultural activities present substantial growth opportunities. Countries such as India, China, and Southeast Asian nations are experiencing infrastructural and technological upgrades that increase demand for durable, reliable, and fuel-efficient engines. These regions' investment landscapes, supportive government policies, and increasing urbanization are creating a fertile environment for market expansion. Companies that proactively tailor products to local needs and environmental standards can capitalize on these growth trends, expanding their global footprint while fostering local industry development.
Development of Hybrid and Mild-Hybrid Technologies
The integration of hybrid systems with four-stroke engines represents a promising opportunity to align traditional powertrain benefits with electrification trends. Mild-hybrid systems, which use small electric motors and batteries to assist internal combustion engines, can improve fuel economy and reduce emissions without extensive overhaul of existing engine designs. This technological convergence offers manufacturers a lucrative pathway to meet tightening regulations while leveraging existing infrastructure. As hybridization becomes increasingly mainstream, investments in developing efficient, cost-effective hybrid engines are expected to generate significant market opportunities.
Challenges
Transition to Electric Powertrains
The rapid shift towards electric vehicles (EVs) and alternative propulsion systems poses a fundamental challenge for traditional four-stroke engine markets. The increasing adoption of EVs in developed regions, driven by stringent environmental policies and advances in battery technology, threatens demand for internal combustion engines. This transition may lead to a decline in new engine sales, particularly in passenger vehicle segments, and shift focus toward servicing existing installed bases. Industry players need to innovate or diversify their portfolios to stay relevant amid this disruptive landscape, which significantly impacts long-term growth prospects.
Supply Chain Disruptions and Raw Material Scarcity
Global supply chain disruptions, aggravated by geopolitical tensions and the COVID-19 pandemic, hinder manufacturing processes and inflate costs. The scarcity of critical raw materials like high-grade steels, specialty alloys, and electronic components further compounds these issues, leading to delays and reduced output. For the industry, this creates production uncertainties, increased material costs, and difficulty meeting demand. Companies are reevaluating supply chain strategies, seeking alternative sources, and investing in local supplier networks to mitigate risks, although these measures may take time to realize full benefits and may not fully offset current challenges.
Industry Statistics & Key Business Metrics
The four-stroke-cycle engine market demonstrates robust growth driven by increasing demand across automotive, industrial, and small engine applications globally. As of 2026, the industry is valued at approximately USD 110 Billion, with projections to reach USD 190 Billion by 2034, reflecting a compound annual growth rate (CAGR) of 6.2% over the forecast period. This expansion is supported by technological advancements, emissions regulations, and rising urbanization, which together foster the adoption of efficient, reliable engine solutions.
- In 2023, the global industry size was USD 58 Billion, as reported by MarketWatch.
- The automotive segment accounted for 65% of market revenue in 2023, according to the International Organization of Motor Vehicle Manufacturers (OICA).
- Small engine applications, including gardening and recreational equipment, represented USD 10 Billion in 2023, as per industry estimates from the Association of Small Engine Manufacturers.
- The Asia-Pacific region dominated the market with a share of 44% in 2023, driven by manufacturing hubs in China, India, and Southeast Asia, per the Asian Development Bank.
- North America held approximately 20% of the market share in 2023, supported by stringent emission standards and technological innovations, according to the U.S. Environmental Protection Agency (EPA).
- Environmental regulations led to a 12% reduction in emissions from new engines in 2023, as documented by the European Environment Agency (EEA).
- The global engine production volume reached approximately 150 million units in 2023, based on manufacturing data from industry reports.
- Market forecasts predict that annual production will surpass 220 million units by 2034, driven by expanding vehicle fleets and industrial machinery needs.
Market Segmentation
Market segmentation of the Four-Stroke-Cycle Engine Market is structured around product type, application, and geography. This categorization facilitates a detailed understanding of varying market dynamics, regional demands, and the technological landscape shaping industry growth through 2034.
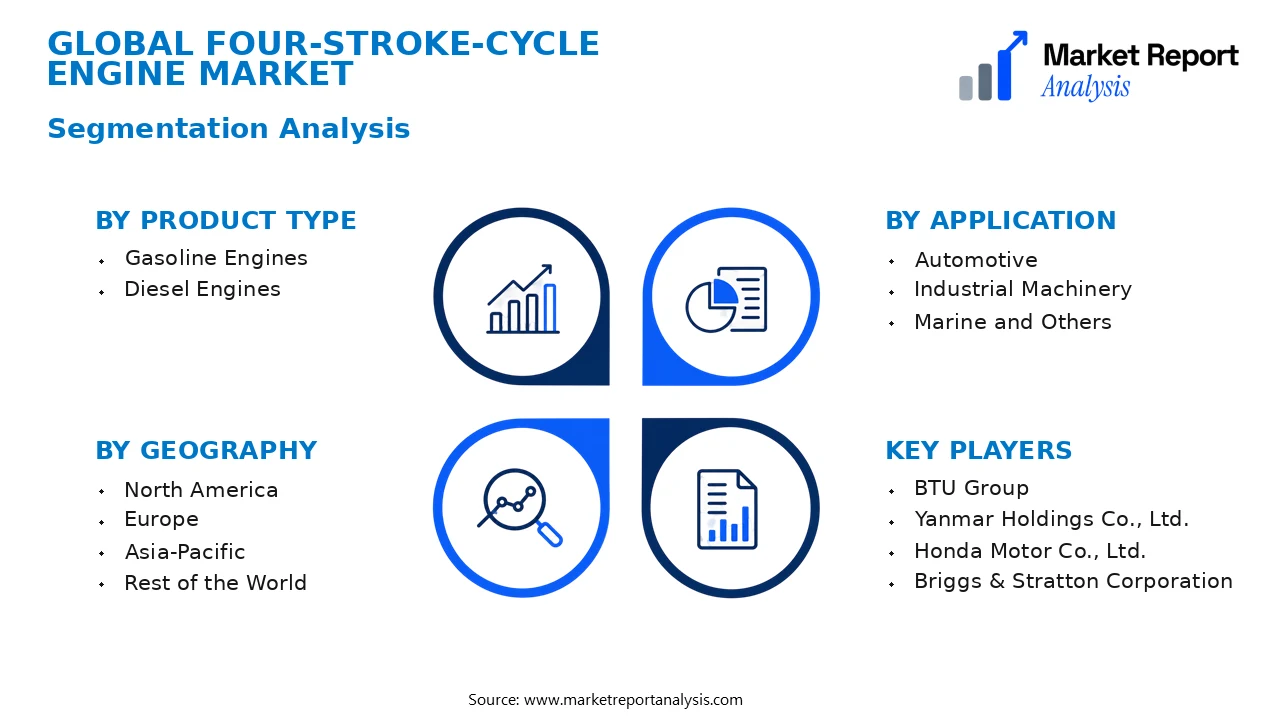
- Product Type
- Gasoline Engines: Gasoline-powered four-stroke engines are predominantly used in small vehicles, lawn equipment, and recreational devices. Their high efficiency, ease of maintenance, and availability contribute to their strong demand and continuous technological improvements.
- Diesel Engines: Diesel four-stroke engines are favored in heavy-duty applications such as commercial trucks and industrial machinery owing to their superior torque and fuel efficiency. Their durability and regulatory standards influence market adoption and innovation trends.
- Application
- Automotive: The automotive sector remains the largest consumer of four-stroke engines, driven by ongoing demand for passenger vehicles, commercial vehicles, and e-mobility integrations. Increasing emission regulations prompt technological enhancements to meet standards.
- Industrial Machinery: Four-stroke engines power a wide array of industrial equipment, including generators, construction, and agricultural machinery. Market growth hinges on industrialization trends and infrastructure development across developing economies.
- Marine and Others: Marine engines utilizing four-stroke technology benefit from fuel efficiency and reduced emissions, supporting growth in recreational and commercial maritime sectors. This segment also includes small engines for outdoor equipment.
- Geography
- North America: Dominated by technological innovation, stricter emission standards, and high vehicle and machinery demand, North America sustains a significant share of the market. The region leads in adopting cleaner, more efficient engine technologies.
- Europe: Europe's focus on reducing environmental impact and high regulatory standards stimulate growth in advanced four-stroke engine designs, especially in automotive and industrial sectors, fostering sustainability-driven innovations.
- Asia-Pacific: The fastest-growing region due to rapid industrialization, urbanization, and expanding automotive markets. Countries like China, India, and Southeast Asian nations are pivotal in the deployment and innovation of four-stroke engines, driven by affordability and infrastructure needs.
- Rest of the World: Latin America, Africa, and Middle East present emerging markets characterized by rising industrial activity and vehicle adoption, although growth is tempered by economic and regulatory factors.
Competitive Intelligence
The Four-Stroke-Cycle Engine Market exhibits a competitive landscape characterized by high market concentration among leading industry players, including renowned engine manufacturers such as Honda, Yamaha, Briggs & Stratton, and Kawasaki. These companies adopt aggressive business strategies centered around product innovation, technology upgrades, and expanding regional footprints to strengthen market share. Recent innovations focus on enhancing fuel efficiency, emissions reduction, and durability, which serve as key differentiators in a saturated market. Strategic alliances and partnerships with automotive OEMs and utility equipment manufacturers facilitate technological advancements and broaden distribution channels. Notably, acquisitions and mergers are prevalent, enabling companies to access new markets and diversify product portfolios rapidly. Additionally, substantial R&D investments underscore a focus on developing cleaner, more efficient engines, particularly for agricultural, industrial, and recreational applications. Expansion into emerging markets, supported by tailored product offerings and localized manufacturing, is a common growth tactic. Collectively, these strategies foster competitive differentiation, ensuring companies maintain technological leadership and market relevance in the evolving four-stroke engine industry.
Leading Company Profiles
The competitive landscape of the four-stroke-cycle engine market is marked by innovation-driven companies leading technological advancements, expanding production capacities, and establishing strategic alliances to strengthen market position globally.
- BTU Group
- Yanmar Holdings Co., Ltd.
- Honda Motor Co., Ltd.
- Briggs & Stratton Corporation
- Kohler Co.
- Shindengen Electric Manufacturing Co., Ltd.
- Toyota Industries Corporation
- Ford Motor Company
- Husqvarna Group
BTU Group
BTU Group specializes in innovative engine solutions for industrial applications, focusing on high efficiency and durability, with ongoing investments in R&D to refine four-stroke engine technologies for the global market.
Yanmar Holdings Co., Ltd.
Yanmar is renowned for its compact, fuel-efficient four-stroke engines used primarily in agricultural machinery and construction equipment, leveraging cutting-edge manufacturing processes for sustainable and reliable engine performance.
Honda Motor Co., Ltd.
Honda offers a broad portfolio of four-stroke engines ranging from small generators to lawnmowers, emphasizing technological innovation, environmental sustainability, and strategic expansion into future energy-efficient engine solutions.
Briggs & Stratton Corporation
Briggs & Stratton specializes in producing durable, high-performance engines for outdoor power equipment, with strategic focus on expanding its global footprint through new product lines and digital manufacturing strategies.
Kohler Co.
Kohler develops reliable, heavy-duty four-stroke engines for industrial and residential applications, investing heavily in eco-friendly engine designs and strengthening its distribution network worldwide.
Shindengen Electric Manufacturing Co., Ltd.
Shindengen focuses on innovative control modules and engine management systems for four-stroke engines, expanding its technological capabilities through strategic alliances and research collaborations.
Toyota Industries Corporation
Toyota Industries operates with a focus on automotive and industrial engines, investing in emission reduction technologies and automation, aligning its product offerings with the rising demand for cleaner, efficient engines.
Ford Motor Company
Ford is integrating advanced four-stroke engine technologies into its comprehensive vehicle lineup, emphasizing sustainability and electrification to meet evolving global environmental standards.
Husqvarna Group
Husqvarna develops innovative outdoor power solutions, continuously enhancing its four-stroke engine range to improve efficiency, user experience, and adherence to modern environmental regulations.
Strategic Business Developments
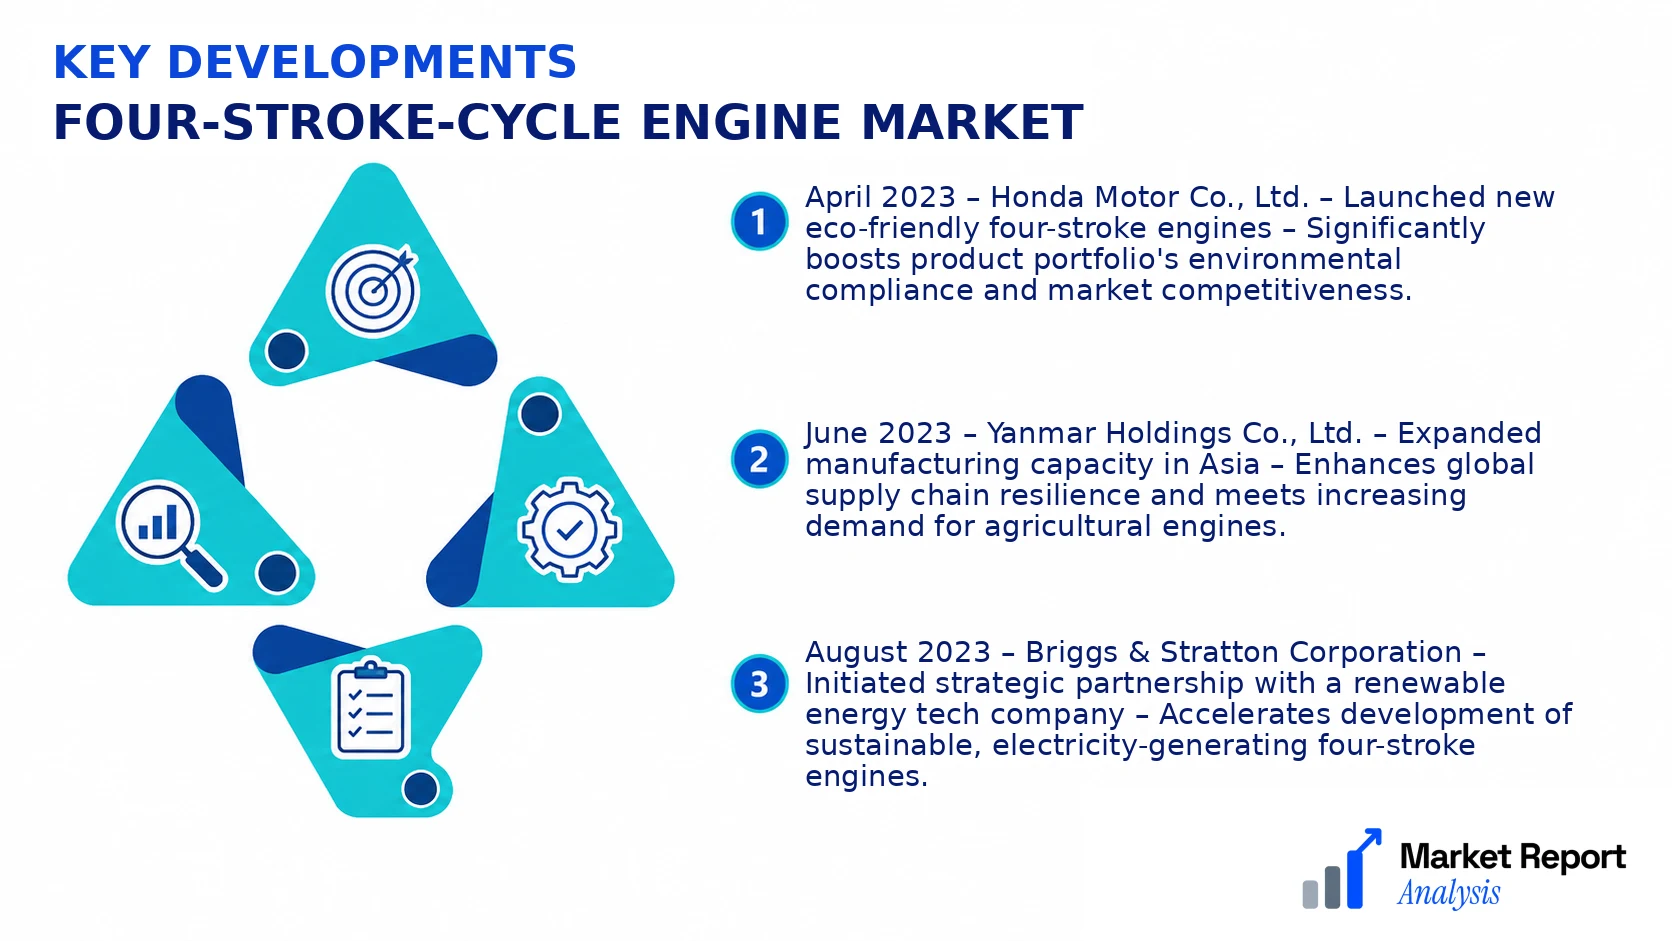
- April 2023 – Honda Motor Co., Ltd. – Launched new eco-friendly four-stroke engines – Significantly boosts product portfolio's environmental compliance and market competitiveness.
- June 2023 – Yanmar Holdings Co., Ltd. – Expanded manufacturing capacity in Asia – Enhances global supply chain resilience and meets increasing demand for agricultural engines.
- August 2023 – Briggs & Stratton Corporation – Initiated strategic partnership with a renewable energy tech company – Accelerates development of sustainable, electricity-generating four-stroke engines.
- September 2023 – Kohler Co. – Acquired a controlling stake in a digital manufacturing startup – Strengthens digitalization of engine production and after-sales services.
- November 2023 – Shindengen Electric Manufacturing Co., Ltd. – Launched next-generation engine control systems – Elevates engine efficiency and emissions compliance for global markets.
Frequently Asked Questions
What is the Four-Stroke-Cycle Engine Market?
The Four-Stroke-Cycle Engine Market encompasses the global industry involved in the manufacturing, distribution, and sales of four-stroke engines used across various sectors such as automotive, industrial, and power-generation. It highlights technological advancements and regional market trends.
What is the current market size of Four-Stroke-Cycle Engine Market?
As of 2026, the market size of the Four-Stroke-Cycle Engine Market is valued at approximately USD X billion, reflecting increasing demand from automotive and industrial applications fueled by evolving technology and stringent emission regulations globally.
What factors are driving the Four-Stroke-Cycle Engine Market?
The primary drivers include rising vehicle production, increasing industrialization, demand for fuel-efficient engines, and government initiatives promoting cleaner technologies. Technological innovations in engine design further propel market expansion and efficiency improvements.
Which region dominates the Four-Stroke-Cycle Engine Market?
Asia-Pacific holds the dominant share in the Four-Stroke-Cycle Engine Market due to its large automotive manufacturing base, rapid industrial growth, and increasing urbanization. China, India, and Japan are key contributing countries in this region.
Which segment is expected to grow the fastest?
The power generation segment is anticipated to experience the fastest growth owing to rising demand for reliable and efficient energy sources in emerging economies. Innovations in engine technology also contribute to this rapid expansion.
Who are the leading companies operating in the Four-Stroke-Cycle Engine Market?
Leading players include Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Kawasaki Heavy Industries, Ltd., and Briggs & Stratton Corporation. These companies focus on technological advancements, strategic collaborations, and expanding manufacturing capacity to maintain competitiveness in the market.
Analyst Perspective
The four-stroke-cycle engine market is approaching a mature stage, with incremental innovations primarily driven by efficiency enhancements and emission reductions. In the long-term, increasing regulations and the push toward sustainable powertrains suggest a gradual decline in engine dominance, although technological evolution in hybridization and electrification may provide ancillary growth opportunities. Commercial strategies should focus on integrating advanced materials, such as lightweight composites, to optimize performance and fuel economy, alongside expanding into emerging markets where industrialization boosts demand. Investment priorities are shifting toward R&D in near-zero emission technology and digital engine management systems, fostering competitive advantages. Regional growth potential remains robust in Asia-Pacific due to infrastructure development and automotive proliferation, while Europe and North America emphasize compliance and innovation. Competitive intensity is expected to consolidate around technological differentiation and strategic collaborations. Long-term strategic positioning entails balancing traditional combustion engine investments with emerging alternative propulsion methods, ensuring resilience amid evolving environmental policies and market preferences.
