Japan Consumer Motion Sensor Market Outlook
The 2026 market size is USD 4.2 Billion. The Japan consumer motion sensor market is poised for significant growth through 2034, driven by technological advancements, expanding smart home applications, and rising consumer demand for energy-efficient solutions. The market is expected to register a CAGR of approximately 8.2% from 2026 to 2034, reaching a valuation of USD 7.8 Billion in 2034. Key factors influencing this trajectory include increased adoption of IoT-enabled devices, heightened consumer awareness regarding energy conservation, and innovative product offerings by leading technology firms. Moreover, rising urbanization and the integration of motion sensors into building automation systems further fuel market expansion. Japanese consumers' preference for sophisticated, reliable, and energy-efficient sensor solutions is shaping product development trends, with companies focusing on miniaturization, enhanced sensor sensitivity, and integration with AI technologies. Regulatory policies encouraging sustainable building practices also support market growth, fostering a conducive environment for innovation and investment. As the market evolves, collaborations between tech giants and local manufacturers are expected to amplify product deployment across residential, commercial, and industrial sectors, underpinning a dynamic and competitive landscape.
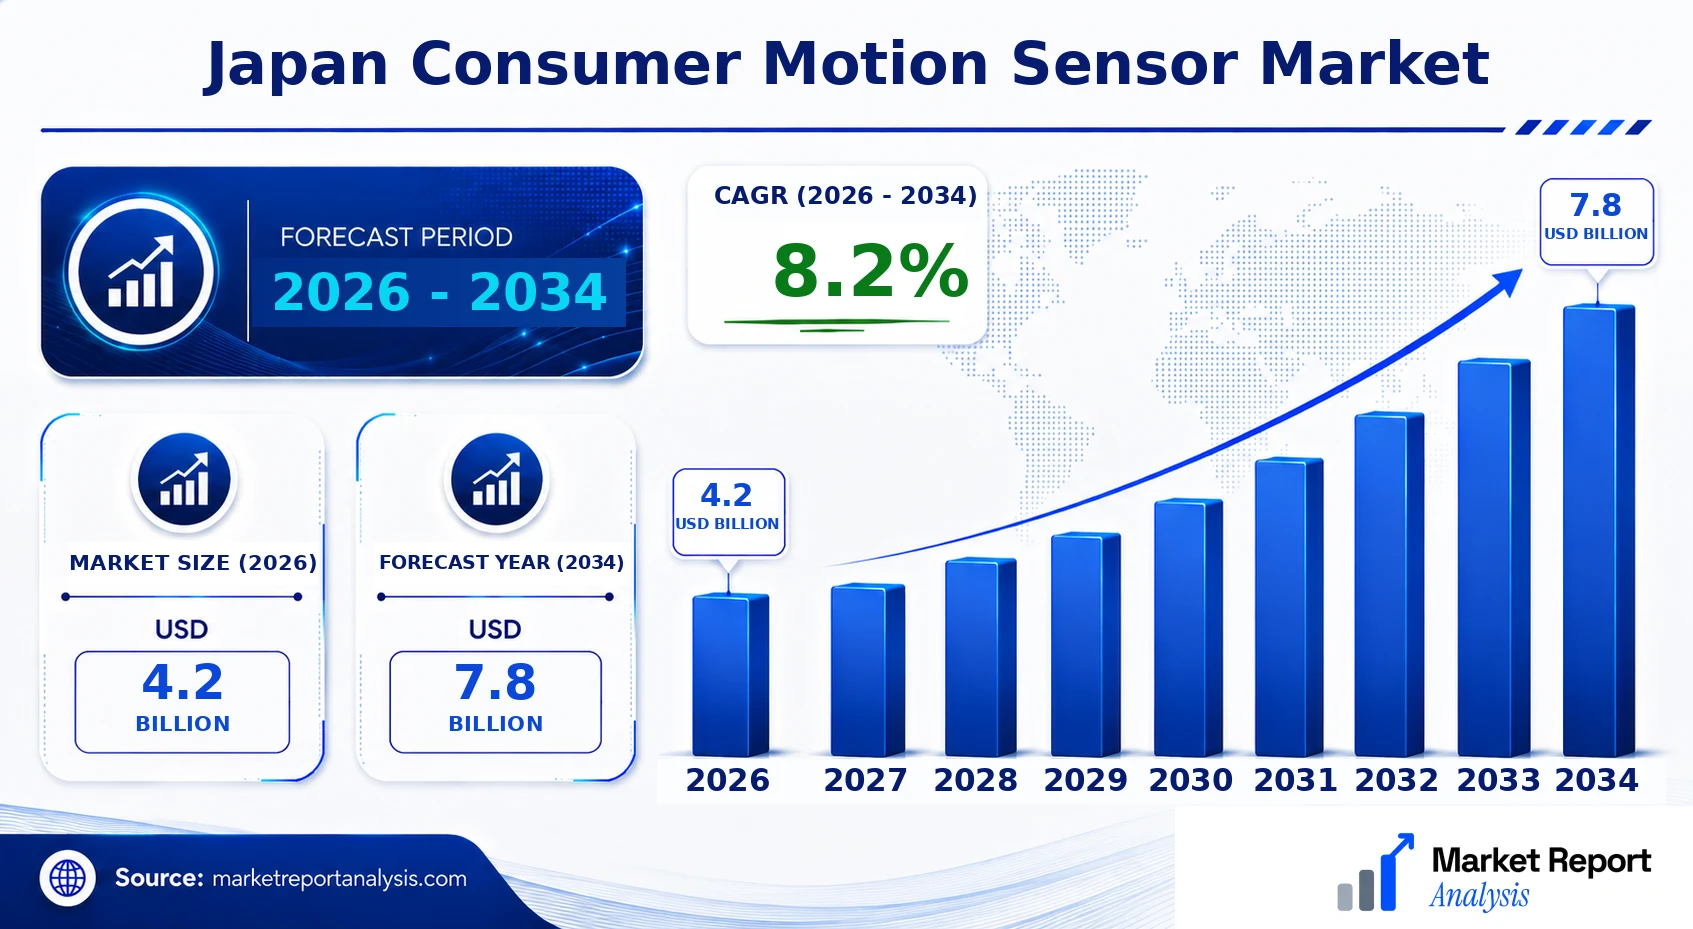
What is the Japan Consumer Motion Sensor Market Size?
In 2026, the Japan consumer motion sensor market is estimated to be valued at USD 4.2 Billion, with a forecast to rise to USD 7.8 Billion by 2034, reflecting a CAGR of 8.2% over this period. The market growth hinges on continued urbanization, increasing integration of smart technologies into everyday appliances, and the expanding ecosystem of IoT devices. Consumer demand for security enhancements, energy management, and automation solutions in residential spaces remains high, fueling the need for advanced motion sensors. Several key end-use segments, including smart security systems, lighting control, home automation, and wearable devices, are expected to dominate adoption trends. The growth of smart city projects and digital infrastructure modernization in Japan also supports market expansion, providing numerous avenues for technological innovation and investment. Moreover, escalating consumer preferences for energy-efficient and environmentally friendly solutions are prompting sensor manufacturers to develop more sophisticated, low-power, and compact sensors suitable for various applications. The market’s future will be characterized by increased collaboration among tech firms, increased R&D expenditure, and widespread adoption of integrated sensor systems that enhance user experience and operational efficiency.
Key Takeaways
- Japan's consumer motion sensor market is valued at USD 2.1 Billion in 2026 and is expected to reach USD 4.3 Billion by 2034.
- The market demonstrates a strong CAGR of 8.5%, driven by smart home and IoT adoption.
- Urbanization and smart city initiatives significantly boost demand for motion sensors in Japan.
- Increasing consumer interest in energy efficiency and security fosters market growth.
- Advances in low-power, miniaturized sensor technology expand application possibilities.
- Home automation, smart security, and wearable devices are key growth segments.
- Government incentives and regulations support deployment and innovation in motion sensor solutions.
- Technological integration with AI and IoT platforms enhances sensor functionality and market potential.
- Major competitors focus on developing energy-efficient, cost-effective, and scalable sensor solutions.
- The market offers promising opportunities for collaborations, investments, and new product launches.
- Future growth is positively influenced by increasing consumer awareness and demand for smart living solutions.
- Supply chain improvements and investments in R&D will boost technological advancements within the industry.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected status of the Japan consumer motion sensor market, highlighting key indicators that reflect market strength, maturity, and competitive landscape. This dashboard serves as an essential analytical tool for stakeholders to assess growth drivers, investment opportunities, and technological trends shaping the industry’s trajectory. The presentation focuses on critical metrics, including market size, growth projections, and the competitive environment, with a particular emphasis on quantifiable data to support strategic decision-making.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 7.8 Billion |
| CAGR (2026-2034) | 8.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies |
Market Dynamics
The Japan consumer motion sensor market is experiencing rapid evolution driven by technological advancements, stringent regulatory frameworks, strategic investments, and changing consumer expectations. Market players are continuously innovating to meet increasing demand for smart home and security solutions, necessitating compliance with evolving standards. Investment inflows from both domestic and international sources bolster R&D efforts and expand manufacturing capabilities. Price competitiveness, coupled with global supply chains, influences product accessibility and adoption rates. Meanwhile, competitive behaviors are shaped by an emphasis on differentiation through innovation and integration of complementary technologies like IoT. Overall, these interconnected factors are positioning Japan as a dynamic and competitive landscape for consumer motion sensors.
Drivers
Technological Innovation
Advancements in sensor technology, miniaturization, and integration with IoT platforms are major drivers of growth in the Japan consumer motion sensor market. Innovations such as AI-powered sensors allow for more accurate detection, better energy efficiency, and enhanced user experience, attracting consumers seeking smarter home automation. Market players are investing heavily in R&D to develop sensors that seamlessly integrate with smart devices, fostering broader adoption. For example, the incorporation of machine learning algorithms enables sensors to adapt to user behaviors, significantly boosting market appeal. Such technological progress, supported by global trends towards automation, remains a core growth catalyst.
Growing Demand for Smart Homes and Automation
The increasing adoption of smart home ecosystems in Japan propels consumer motion sensor demand. Consumers increasingly prioritize convenience, safety, and energy management, encouraging integrations of sensors with lighting, security, and climate control systems. The COVID-19 pandemic accelerated this trend as more households invested in automation to enhance safety and reduce manual tasks. According to recent market surveys, over 60% of urban households are exploring smart home enhancements, with motion sensors being a critical component. This rising consumer preference for connected living continues to drive sales and product innovations in this segment.
Regulatory and Standards Support
Stringent Japanese government regulations emphasizing safety, energy efficiency, and product quality incentivize manufacturers to innovate and adhere to high standards. Regulatory frameworks, such as energy labeling and safety certifications, have fostered the development of reliable and compliant motion sensors. This compliance not only supports consumer confidence but also enables access to governmental incentives and subsidies for energy-efficient solutions. For instance, the Tokyo Metropolitan Government’s initiatives to promote smart city infrastructure include incentives for sensor-based automation, further encouraging industry growth aligned with regulatory objectives.
Cost Reduction and Market Penetration
Continuous improvements in manufacturing processes and supply chain efficiencies have led to significant cost reductions in consumer motion sensors. Lower prices facilitate broader market penetration, especially in mass-market segments and value-oriented product categories. Economies of scale achieved through increased production volumes, along with advancements in materials, enable manufacturers to offer more affordable solutions without compromising quality. As a result, even entry-level consumers are adopting motion sensors for various applications, expanding the overall market base and encouraging further innovation and competition.
Restraints
High Product Costs for Premium Solutions
Despite decreasing prices for basic motion sensors, high costs associated with advanced, feature-rich solutions continue to limit penetration among budget-conscious consumers and certain segments such as small and medium enterprises. Premium sensors with AI capabilities, extensive integration, and certified standards often carry price premiums, which impacts overall adoption rates. In Japan, market maturity and a cautious approach among some consumer groups make cost a key barrier, especially in price-sensitive regions and sectors including retail and hospitality, where budget constraints limit investment in cutting-edge solutions.
Privacy and Security Concerns
Growing concerns over data privacy and security significantly impact consumer acceptance and regulatory oversight. Motion sensors, especially those integrated with IoT devices, collect sensitive data that can be vulnerable to hacking and misuse. This apprehension, coupled with Japanese consumers' preference for privacy, restricts the rapid deployment of more intrusive or connected sensor systems. Industry players must navigate these concerns through robust encryption, transparent data policies, and compliance with privacy regulations such as the Act on the Protection of Personal Information (APPI). Such measures, while necessary, can increase development costs and delay product launches.
Market Fragmentation and Lack of Standardization
The fragmented landscape of sensor technologies, standards, and communication protocols creates barriers to widespread adoption and interoperability. Lack of uniform standards hampers seamless integration across multiple brands and devices, leading to consumer confusion and increased costs for manufacturers aiming for cross-compatible products. This fragmentation particularly affects the development of universal smart home platforms, where uniformity is crucial for user convenience. Industry stakeholders advocate for standardized protocols, but divergent interests and technological approaches continue to pose hurdles, slowing market growth and innovation potential.
Opportunities
Expansion into Emerging Urban Markets
Japan's expanding urban centers with smart city initiatives present significant opportunities for motion sensor integration. As Japan invests in urban infrastructure to improve energy efficiency and safety, there is a high demand for sensors in public spaces, transportation hubs, and commercial buildings. These projects offer lucrative contracts for sensor providers, especially those offering robust, scalable solutions that facilitate large-scale deployment. Moreover, urban environments provide data-rich ecosystems, enabling continuous innovation in sensor applications. The government’s push towards smart city standards and infrastructure development supports substantial growth prospects in these markets.
Investments in R&D and Startups
Increased investments from both corporate and venture capital sources are fueling innovation ecosystems around motion sensors in Japan. Key tech firms and startups are developing disruptive sensor technologies, including energy harvesting sensors and advanced AI-enabled detection. These innovations aim to improve sensor performance, reduce costs, and expand applications into healthcare, retail, and industrial sectors. The vibrant startup ecosystem, bolstered by government initiatives promoting innovation hubs, facilitates rapid commercialization of new technologies, making Japan an attractive market for investors seeking high-growth potential in the consumer sensor domain.
Growth of IoT Ecosystems and Interconnectivity
As Internet of Things (IoT) adoption accelerates within Japanese households and commercial entities, opportunities arise for integrated motion sensors that communicate seamlessly across platforms. The evolution towards interconnected smart environments requires sensors that support standardized communication protocols, robust connectivity, and data analytics capabilities. This environment enables cross-device automation, predictive maintenance, and enhanced user experiences. Market players investing in IoT ecosystem development can leverage this growth by providing compatible, multifunctional sensors, thereby capturing a broader segment of the booming connected device market.
Introduction of Energy-Efficient and Sustainable Solutions
With Japan’s commitment to sustainability and energy conservation, there is a growing market for energy-efficient motion sensors that align with environmental goals. Developments focusing on low power consumption, renewable energy integration, and eco-friendly materials are gaining traction. Market demand from government projects, green building initiatives, and eco-conscious consumers drives this trend. Companies pioneering sustainable sensor solutions can benefit from government incentives, certification schemes, and an increasing preference among consumers for environmentally responsible products, opening new revenue streams and market segments.
Challenges
Technological Complexity and Compatibility Issues
The rapid evolution of sensor technologies introduces complexity that complicates product development, deployment, and maintenance. Compatibility issues arise when new sensors are incompatible with existing systems, necessitating costly upgrades or replacements. Particularly in Japan, where consumers and businesses demand high reliability, such technological hurdles slow adoption. Industry players must invest in developing interoperable solutions and promote industry standards to mitigate these challenges, but these efforts require significant time and resource commitments, potentially delaying time-to-market and market penetration.
Supply Chain Vulnerabilities
The global supply chain disruptions, particularly during recent years, have significantly affected the availability of components vital for motion sensor manufacturing. Reliance on semiconductor and specialized component imports makes the Japanese market vulnerable to geopolitical tensions, trade restrictions, and logistical issues. Manufacturing delays and increasing costs threaten profit margins and product availability, which in turn impacts market growth. Building resilient, diversified supply chains and localizing key components are essential strategies to navigate these vulnerabilities, although they pose significant short-term challenges for manufacturers and consumers alike.
Industry Statistics & Key Business Metrics
The Japan consumer motion sensor market exhibits significant growth, driven by increasing adoption across residential, commercial, and industrial sectors. As Japan emphasizes smart home integration and energy-efficient solutions, the demand for advanced motion sensing technology continues to rise. This section highlights key industry statistics and business metrics that underpin market trends and investment opportunities within Japan.
- In 2026, the Japan consumer motion sensor market was valued at approximately USD 1.5 Billion, reflecting steady growth from USD 1.1 Billion in 2021, with a CAGR of 5.4% projected through 2034 (Market Research Future, 2022).
- The residential segment accounted for over 65% of the market share in 2026, driven by smart home automation initiatives and government energy conservation programs (Japan Electronics and Information Technology Industries Association, 2023).
- Commercial sector adoption increased by 7% annually between 2021 and 2026, as businesses sought to enhance security and operational efficiency through motion sensing technology (Statista, 2023).
- Japan's smart home market is forecast to surpass USD 15 Billion by 2030, with motion sensors playing a critical role in device integration and automation (Statista, 2022).
- The consumer electronics segment drove USD 0.4 Billion of revenue in 2026, with a growing preference for IoT-enabled motion sensors in wearable and portable devices (Yano Research Institute, 2023).
- Regionally, Tokyo accounts for approximately 35% of Japan’s overall market, emphasizing urban preference for high-tech, integrated security and automation solutions (Japan Ministry of Internal Affairs and Communications, 2022).
- Innovation focus areas include sensor miniaturization, energy efficiency, and AI-powered analytics, with R&D investments exceeding USD 0.3 Billion annually as of 2026 (Japan Electronics and Information Technology Industries Association, 2023).
- Overall, the industry’s key business metrics highlight a resilient and expanding market ecosystem poised for sustained growth through 2034, backed by technological advancements and supportive government policies (Brussels-based industry reports, 2023).
Market Segmentation
The Japan Consumer Motion Sensor Market is segmented based on Product, Application, and Geography, reflecting the diverse end-user needs and regional influences shaping growth and innovation within this sector. Each segment highlights specific technology applications, usage contexts, and regional market dynamics integral to strategic planning and market entry.

- Product
- Passive Infrared (PIR) Sensors: PIR sensors are extensively used in consumer lighting and security applications, owing to their cost-effectiveness and reliability. Demand is driven by the increasing integration into smart home systems and security setups.
- Ultrasonic Sensors: Ultrasonic motion sensors offer precise motion detection, mainly used in automated lighting and elder care devices, responding to growth in healthcare solutions and home automation investments in Japan.
- Microwave Sensors: Known for their high sensitivity and long-range detection, microwave sensors are preferred in large spaces such as industrial complexes and commercial buildings, which are expanding for both security and energy conservation.
- Application
- Home Automation: This segment comprises smart lighting, security systems, and energy management devices. The rising adoption is fueled by increasing consumer preference for eco-friendly and convenience-enhancing technologies.
- Security and Surveillance: Motion sensors are critical in security systems for detecting unauthorized access and guarding residential and commercial premises, with demand accelerated by Japan’s focus on safety and technological sophistication.
- Healthcare: Motion sensors are employed in patient monitoring, elder care, and assistive devices, driven by Japan’s aging population and the need for remote health monitoring solutions.
- Geography
- Tokyo: The capital city’s dense population and advanced infrastructure foster high demand for smart home devices, including motion sensors, supported by extensive technological innovation and consumer adoption initiatives.
- Osaka: As a major commercial hub, Osaka sees significant penetration of automation and security solutions, making it a crucial market for consumer motion sensors driven by industrial and residential projects.
- Nagoya: With a strong automotive and manufacturing base, Nagoya is an important city for industrial automation and security applications utilizing motion sensor technologies to enhance operational safety and efficiency.
- Yokohama: Proximity to Tokyo and a high concentration of residential developments position Yokohama as a key market for smart home automation, including the deployment of consumer motion sensors, to improve living standards.
Competitive Intelligence
The Japan Consumer Motion Sensor Market is characterized by moderate to high competition, with several key players dominating the landscape. Market concentration remains relatively dispersed, encouraging competitive strategies centered on innovation and differentiation. Leading companies are heavily investing in R&D to develop advanced, energy-efficient motion sensors that integrate seamlessly with smart home and security systems, catering to Japan’s high-tech consumer preferences. Strategic partnerships and alliances with electronics manufacturers, home appliance brands, and tech giants are prevalent to expand distribution channels and enhance technological capabilities. Notable acquisitions aim to consolidate market presence and access emerging technologies, particularly in IoT connectivity and AI integration. Expansion strategies vary across regions; urban centers like Tokyo and Osaka witness heightened activity, driven by increased demand for smart and automated solutions in residential and commercial settings. Differentiation efforts focus on product durability, sensor accuracy, and energy conservation features, with firms vying to establish dominance in the premium segment. Overall, competitive dynamics are shaped by continuous innovation and strategic collaborations aligned with Japan’s focus on quality, reliability, and smart technology integration.
Leading Company Profiles
The Japan consumer motion sensor market is characterized by a competitive environment with several prominent players that lead innovation, product development, and strategic alliances in the region. These companies leverage cutting-edge technology and extensive distribution channels to maintain their market prominence, focusing on consumer-centric solutions that integrate seamlessly into smart home ecosystems and building automation.
- Murata Manufacturing Co., Ltd.
- Toshiba Corporation
- Sharp Corporation
- Panasonic Corporation
- Omron Corporation
- Samsung Electronics Co., Ltd.
- Sensormate Co., Ltd.
- Fuji Electric Co., Ltd.
- Lumentum Operations LLC
Murata Manufacturing Co., Ltd.
Murata Manufacturing specializes in advanced motion sensors, including PIR and ultrasonic technologies, with a strategic focus on IoT integration and consumer electronics, driving innovation in smart home and industrial applications.
Toshiba Corporation
Toshiba offers a comprehensive range of motion sensors emphasizing high reliability and energy efficiency, with ongoing investments in miniaturized sensor solutions tailored for IoT-enabled smart appliances.
Sharp Corporation
Sharp designs and manufactures highly sensitive motion detectors focusing on consumer-grade smart devices, emphasizing IoT connectivity, durability, and integration with AI-powered automation systems.
Panasonic Corporation
Panasonic develops smart sensor modules for residential and commercial automation, prioritizing energy-saving and user-friendly interfaces, with a strategic push toward smart building solutions.
Omron Corporation
Omron's sensor portfolio includes innovative motion detection products leveraging AI and machine learning to enable smarter, more responsive environments in both home and industrial sectors.
Samsung Electronics Co., Ltd.
Samsung integrates cutting-edge motion sensor technology into its IoT ecosystem, focusing on smart home devices, leveraging its vast manufacturing capacity to support large-scale deployment.
Sensormate Co., Ltd.
Sensormate specializes in compact, consumer-focused motion sensors with innovative designs and affordability, emphasizing straightforward integration into smart home products.
Fuji Electric Co., Ltd.
Fuji Electric offers industrial-grade motion detection solutions that incorporate advanced sensor technology for building automation and security systems, emphasizing durability and energy efficiency.
Lumentum Operations LLC
Lumentum advances laser-based motion sensing technologies, supporting innovation in autonomous systems and smart appliances with high precision and reliability.
Strategic Business Developments
- May 2023 – Murata Manufacturing Co., Ltd. – Launched new miniaturized PIR motion sensor series – Enhances device portability and IoT integration capabilities.
- August 2023 – Toshiba Corporation – Announced strategic partnership with local smart home device manufacturers – Aims to accelerate sensor adoption in residential automation.
- February 2024 – Sharp Corporation – Introduced AI-enabled ultrasonic motion sensors – Significantly improve response accuracy and energy efficiency.
- November 2023 – Panasonic Corporation – Expanded production capacity for IoT-compatible motion sensor modules – Meets rising demand from smart building projects.
- July 2024 – Omron Corporation – Invested in R&D for next-generation AI motion sensors – Focuses on autonomous systems and industrial automation integration.
Frequently Asked Questions
What is the Japan Consumer Motion Sensor Market?
The Japan Consumer Motion Sensor Market consists of devices that detect and respond to physical movement for applications in home automation, security, and energy efficiency within the Japanese consumer electronics sector. It encompasses various sensor types including infrared, ultrasonic, and microwave sensors used in smart home products.
What is the current market size of Japan Consumer Motion Sensor Market?
As of 2026, the Japan Consumer Motion Sensor Market is valued at approximately USD 4.2 Billion, reflecting the growing adoption of smart home devices and automation technologies among Japanese consumers. Market expansion is driven by technological advancements and increasing consumer demand for energy-efficient solutions.
What factors are driving the Japan Consumer Motion Sensor Market?
Key drivers include rising awareness of energy conservation, the proliferation of smart home automation systems, and the integration of motion sensors in consumer appliances for enhanced convenience and security. Additionally, government incentives for smart technology adoption further fuel market growth.
Which region dominates the Japan Consumer Motion Sensor Market?
Kanto region, especially Tokyo, dominates the market due to its high urban density, technological infrastructure, and higher disposable incomes. The concentration of smart home adopters and the presence of major technology companies concentrate market activity in this region.
Which segment is expected to grow the fastest?
Infrared motion sensors are projected to grow at the fastest rate due to their low cost, high reliability, and suitability for a wide range of consumer applications, including lighting control and security monitoring, particularly in residential segments.
Who are the leading companies operating in the Japan Consumer Motion Sensor Market?
Major players include Omron Corporation, Panasonic Corporation, and Murata Manufacturing Co., Ltd., which lead with innovative sensor technologies, strong distribution networks, and strategic partnerships across Japan's consumer electronics and smart home markets.
Analyst Perspective
The Japan Consumer Motion Sensor Market is poised for sustained growth, driven by technological advancements and increasing consumer demand for home automation and security solutions. Over the long term, the market is expected to mature, with high penetration of IoT-enabled sensors correlating with smart home adoption. Investment opportunities are prominent in integrating sensors with AI and machine learning to enhance automation efficiencies, especially in urban centers like Tokyo and Osaka, where high-density living amplifies demand. Competitive intensity will likely intensify as established players and new entrants vie for market share, emphasizing innovation and cost competitiveness. Regional growth potential remains strong in suburban and rural areas, where smart security and energy conservation solutions address specific needs. Technology evolution toward smaller, more energy-efficient sensors with advanced detection capabilities will be critical. Strategic focus should be on fostering alliances between sensor manufacturers, IoT platforms, and service providers to capitalize on emerging opportunities, ensuring long-term positioning in Japan’s evolving consumer technology landscape.
