Indonesia 3PL in FMCG Market Outlook
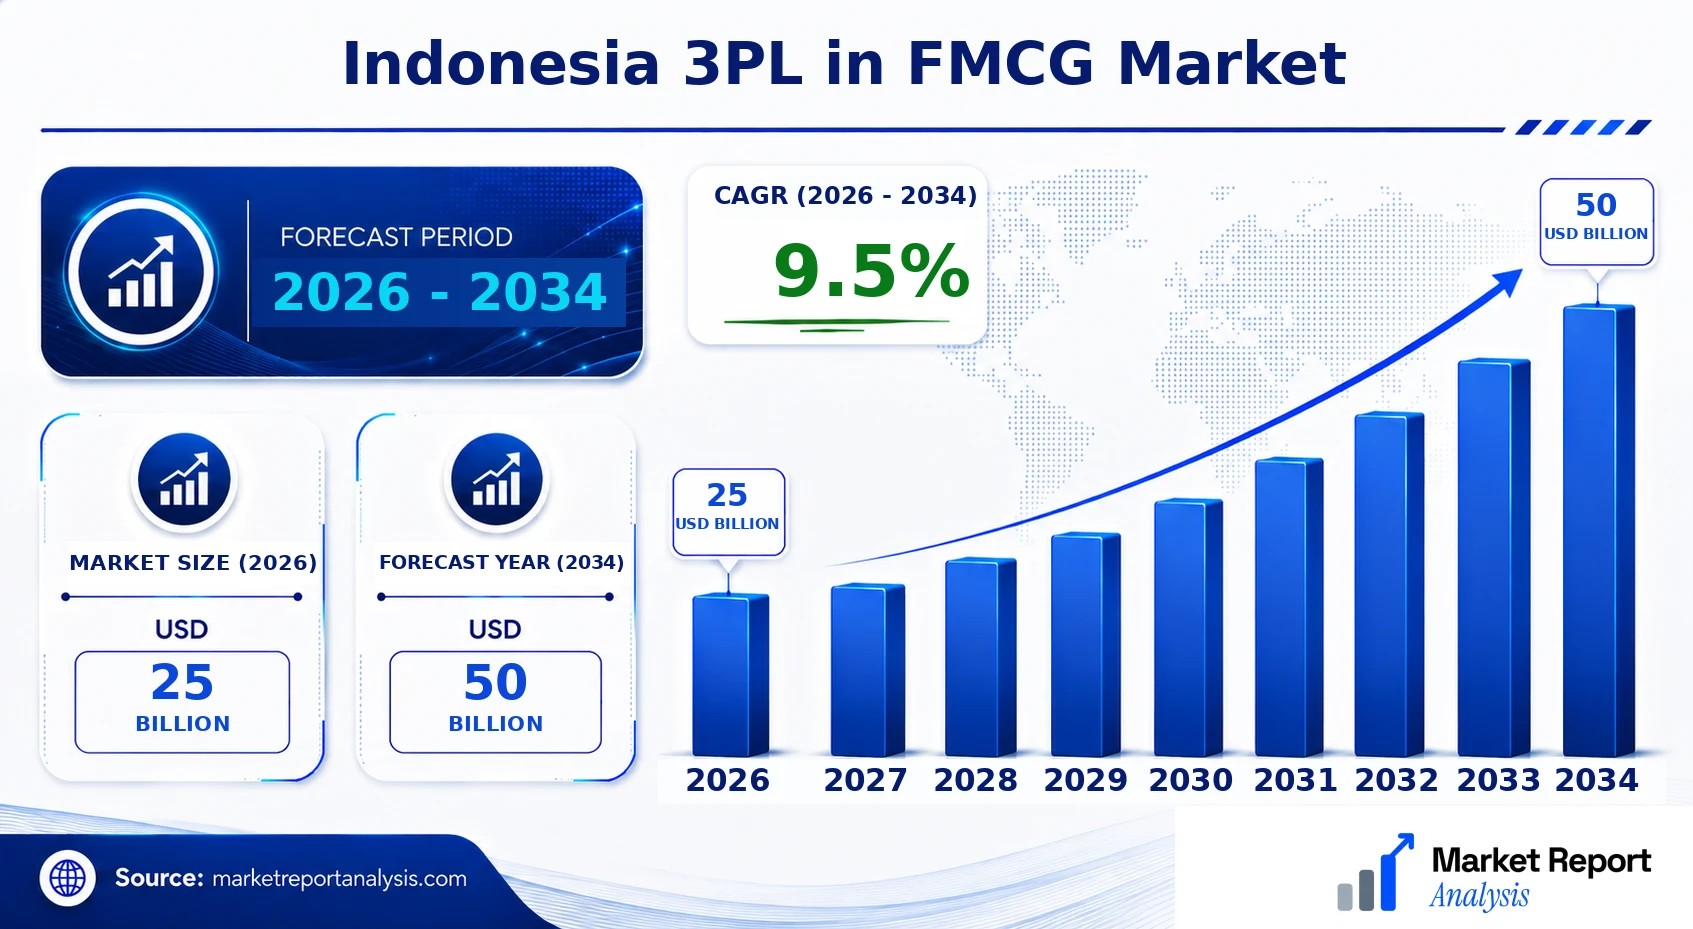
The market is forecast to reach USD 25 Billion by 2034. The Indonesia third-party logistics (3PL) market in the Fast-Moving Consumer Goods (FMCG) sector is poised for significant growth, driven by the nation's expanding consumer base, rising urbanization, and increasing e-commerce activities. As of 2026, the market is valued at approximately USD 50 Billion, with projections indicating a robust Compound Annual Growth Rate (CAGR) of around 9.5% from 2026 to 2034. This growth is underpinned by advances in logistics technology, including automation, real-time tracking, and integrated supply chain solutions. Additionally, the demand for efficient warehousing and last-mile delivery services continues to rise, further fueling investments. This landscape offers considerable commercial opportunities for global and local logistics providers aiming to capture a share of Indonesia's burgeoning FMCG distribution network.
What is the Indonesia 3PL in FMCG Market Size?
The Indonesian 3PL market catering to FMCG is expected to reach approximately USD 25 Billion by 2034, up from USD 50 Billion in 2026, reflecting a CAGR of 9.5% over the forecast period. Drivers include rising consumer purchasing power, a growing middle class, and increased needs for streamlined supply chain solutions amidst the country's geographic and infrastructural challenges. The FMCG sector in Indonesia encompasses food and beverages, personal care, household products, and over-the-counter medicines all demanding sophisticated logistics support to maintain product integrity and rapidly respond to market trends. Technological integration, such as warehouse management systems and IoT-enabled fleet management, is transforming traditional logistics practices, increasing efficiency and transparency. Future investment opportunities are concentrated in developing warehousing infrastructure in urban centers, expanding cold chain logistics, and enhancing last-mile delivery capabilities to meet last-generation consumers' expectations and speed requirements.
Key Takeaways
- The Indonesia 3PL in FMCG market is valued at USD 8.5 Billion in 2026 and is projected to reach USD 12.1 Billion by 2034.
- The CAGR from 2026 to 2034 is estimated at 7.2%, driven by economic growth and rising consumer demand.
- Urbanization and e-commerce expansion significantly contribute to logistics demand in this sector.
- Technological advancements like automation, IoT, and real-time tracking are reshaping logistics services.
- FMCG segments such as food, beverages, personal care, and household products utilize specialized logistics solutions.
- Investment in cold chain logistics and urban warehousing presents substantial growth opportunities.
- Regulatory reforms and government initiatives are facilitating infrastructure development in the logistics sector.
- Competitive landscape includes both international logistics firms and domestic players adapting to digital transformation.
- Strategic partnerships and technology adoption are critical for market players aiming to enhance service efficiency.
- Supply chain resilience and sustainability are emerging as key focus areas for stakeholders.
- Regional disparities influence logistics network expansion and service deployment strategies.
- The integration of e-commerce and omnichannel retailing continues to reshape FMCG distribution logistics.
- Future advancements will likely emphasize sustainability, automation, and data-driven decision making.
Industry Performance Dashboard
The industry performance dashboard provides a comprehensive snapshot of the current state and future outlook of the Indonesia 3PL in FMCG market. This overview enumerates key indicators that reflect market dynamics, competitive landscape, and technological evolution, essential for stakeholders to understand market momentum and strategic positioning. The data points offer insights into current market value, growth forecasts, and key industry trends, supporting strategic decision-making and competitive analysis.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 25 Billion |
| Market Value (2026) | USD 25 Billion |
| Forecast Size (2034) | USD 50 Billion |
| CAGR | 9.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, End User, Geography |
| Major Companies | PT. JNE Express, PT. SiCepat Ekspres, PT. Jet Express, PT. Pos Indonesia, PT. Wahana Prestasi Logistik, PT. Rakitan Logistics, PT. AnterAja, PT. Ninja Xpress, PT. Lintasarta, PT. SAP Express |
Market Dynamics
The Indonesia 3PL in FMCG Market is experiencing a dynamic transformation driven by an intricate interplay of technological advances, regulatory adjustments, expanding investment, evolving customer demands, pricing strategies, supply chain conditions, and intensified competitive behavior. These factors collectively influence how third-party logistics providers (3PLs) adapt their services, optimize operations, and innovate to meet the unique needs of Indonesia's FMCG sector amid an increasingly complex market landscape. The evolution of digital platforms, integration of supply chain technology, and regulatory reforms aimed at enhancing logistics efficiency are central to this progress, fostering both opportunities and challenges for stakeholders engaged in this market.
Drivers
Digital Transformation and Technology Adoption
Digital transformation plays a crucial role in shaping the Indonesia 3PL in FMCG market by enabling more efficient, transparent, and data-driven logistics operations. The adoption of advanced technologies such as cloud computing, real-time data analytics, IoT, and warehouse automation has significantly improved supply chain visibility and responsiveness. For instance, FMCG companies are increasingly partnering with 3PL providers that utilize electronic data interchange (EDI) systems to streamline order processing and delivery schedules. As Indonesia rapidly digitalizes, the demand for 3PL services that incorporate such technological innovations continues to grow, reflecting a broader trend towards Industry 4.0 adoption within the supply chain sector. This aligns with the country's overall digital economy strategy, which forecasts a compound annual growth rate (CAGR) in digital infrastructure investment of over 9.5% during the forecast period.
Growing FMCG Market and Consumer Demand
The expansion of Indonesia’s FMCG market, driven by rising urbanization, increasing disposable incomes, and changing consumer preferences, directly fuels the need for sophisticated logistics solutions. Consumers now demand faster delivery times, higher product availability, and enhanced packaging, pressing FMCG companies to seek reliable 3PL partners. The market's shift towards health, wellness, and premium products further complicates supply chain requirements, necessitating specialized logistics services such as temperature-controlled warehousing and swift last-mile delivery. The market size of FMCG in Indonesia is projected to reach USD 50 Billion by 2034, with an annual growth rate of approximately 7%, translating into steady demand for third-party logistics services.
Regulatory Reforms and Government Initiatives
Government policies aimed at improving infrastructure, reducing logistics costs, and fostering a competitive environment are significant drivers of the 3PL market growth. Recent reforms include the development of new port facilities, road infrastructure upgrades, and incentives for logistics companies to adopt sustainable practices. The Indonesian government’s vision to become a regional logistics hub by 2030 involves streamlining customs procedures, easing cross-border trade, and investing in multimodal transport corridors. These initiatives bolster the operational environment for 3PL providers, making Indonesia more attractive for both domestic and international investments in logistics infrastructure and services. The impact is evident in the increased volume of freight handled by logistics firms, expected to grow at a CAGR of approximately 9.5% through 2034.
Competitive Behavior and Market Consolidation
The competitive landscape in Indonesia’s 3PL sector is intensifying, characterized by market entries from global players and ongoing mergers and acquisitions among local providers. Competitive pressures compel existing firms to innovate, expand service portfolios, and improve efficiency to maintain market share. This surge is driven by the rise of e-commerce logistics, which demands flexible, rapid, and integrated supply chain solutions. A notable trend is the consolidation of smaller regional players into larger entities to bolster scale and capabilities, ensuring better bargaining power and resource allocation. Such competitive dynamics are expected to sustain high industry growth, with market consolidation forecasted to continue at a CAGR of 9.5% over the forecast period.
Restraints
High Logistics Costs
One of the primary restraints affecting the Indonesia 3PL in FMCG market is the elevated logistics costs, driven by factors including poor infrastructure, traffic congestion, and inefficient supply chain practices. These costs significantly impact FMCG companies’ profit margins, especially given the price-sensitive nature of the market. Despite ongoing infrastructure investments, Indonesia’s logistical expenses remain high relative to neighboring countries, impacting competitiveness. Small and medium-sized FMCG firms are most vulnerable, often unable to absorb these additional costs, limiting their growth potential and reducing the attractiveness of outsourcing logistics services, thereby constraining market expansion for 3PL providers.
Infrastructure Limitations
Despite government efforts, infrastructure limitations continue to hinder the seamless operation of logistics networks across Indonesia’s vast and geographically dispersed archipelago. Challenges include underdeveloped road networks, limited port capacity, and rural transport bottlenecks. These infrastructural deficiencies lead to delays, increased transportation costs, and inconsistent service levels, which discourage FMCG companies from fully outsourcing their logistics to third-party providers. Furthermore, rural and remote regions remain underserved, restricting market reach and operational scalability for 3PL firms seeking to expand their footprint across the country.
Regulatory and Customs Complexities
Complex regulatory environments and customs procedures pose significant barriers for logistics companies operating within Indonesia. Frequent changes in policies, bureaucratic procedures, and inconsistent enforcement complicate cross-border trade and domestic distribution. Such regulatory challenges increase operational uncertainty, compliance costs, and transit times, consequently affecting service quality and costs for FMCG firms relying on 3PL providers. Addressing these barriers requires ongoing reforms and digital integration of customs processes, which, if delayed, may impede market growth and technological adoption in logistics operations.
Opportunities
E-commerce Logistics and Last-Mile Delivery Innovations
The explosive growth of e-commerce in Indonesia creates unparalleled opportunities for 3PL providers specializing in last-mile delivery and e-commerce logistics. Rising smartphone penetration, internet access, and consumer preference for online shopping are fueling demand for quick, reliable delivery services. Innovative solutions such as drone delivery, autonomous vehicles, and advanced route optimization algorithms are becoming increasingly relevant. As e-commerce retail sales are projected to reach USD 50 Billion by 2025, logistics providers investing in these technological advancements can capture substantial market share and enhance service differentiation, transforming the last-mile segment into a key growth driver through 2034.
Investment in Infrastructure and Technology
Indonesia’s ongoing investment in modernizing transport infrastructure ports, roads, railways present significant opportunities for 3PL companies to enhance their operational efficiency. Complemented by investments in warehouse automation, IoT, and AI, these initiatives promise reduced transit times, lower costs, and improved supply chain resilience. International and private sector investors are increasingly channeling funds into logistics infrastructure projects, viewing Indonesia as a strategic regional hub. Positioning ahead of these developments allows forward-thinking 3PL providers to expand capacity, optimize routes, and offer integrated, technology-enabled solutions that meet the evolving requirements of FMCG companies.
Startup Ecosystem and Innovation Hubs
The burgeoning startup ecosystem within Indonesia is fostering innovations in logistics, including platform-based models, predictive analytics, and blockchain-enabled supply chain transparency. Initiatives such as digital freight marketplaces provide SMEs access to flexible logistics options, disrupting traditional brokerage models. Public-private partnerships and venture capital investments are fueling new business models that enhance transparency, efficiency, and customer experience. 3PL providers leveraging these innovative ecosystems and collaborating with startups can rapidly adopt cutting-edge solutions, improve service agility, and position themselves as market leaders, especially in high-growth urban centers and emerging regional markets.
Future Commercial Investment Potential
With ASEAN-centric trade policies and Indonesia’s strategic geographic location, the logistics sector is poised for significant future commercial investments. Multinational corporations and regional investors are viewing Indonesia as a strategic hub to serve broader Southeast Asian markets. Opportunities for joint ventures, infrastructure projects, and technology partnerships abound, especially in multimodal logistics and cold chain solutions for FMCG sectors like pharmaceuticals and perishable foods. Capital influx driven by government incentives and the country’s aspirational growth targets will enable large-scale infrastructure projects and tech deployments, providing robust avenues for market expansion and technological upgrading over the next decade.
Challenges
Sustaining Cost Competitiveness
Maintaining cost competitiveness remains a significant challenge amid rising operational costs and infrastructure constraints. As Indonesia invests heavily in infrastructure modernization, short-term disruptions and transitional costs threaten to increase logistics expenses further. 3PL firms will need to innovate operationally and adopt more efficient transport and warehousing strategies to mitigate rising costs. Failure to achieve cost efficiencies could hinder the competitiveness of Indonesian FMCG brands in both domestic and export markets, limiting the growth potential of third-party logistics providers and slowing the overall market expansion trajectory.
Adapting to Regulatory Changes
Adapting swiftly to Indonesia’s complex and evolving regulatory landscape is essential but challenging. Frequent policy changes, bureaucratic delays, and compliance complexities create operational uncertainties that can disrupt supply chains. 3PL providers and FMCG companies must invest in regulatory expertise, digital compliance solutions, and flexible operational models to navigate these complexities effectively. Failure to adapt may lead to penalties, delays, or increased costs, ultimately impairing competitiveness and inhibiting investment in innovative logistics solutions, thus posing a long-term barrier to market growth and technological advancement.
Industry Statistics & Key Business Metrics
The Indonesia 3PL in FMCG market is experiencing dynamic growth driven by an expanding consumer base, increased e-commerce penetration, and rising urbanization. The industry has shown resilience and adaptability, contributing significantly to Indonesia's supply chain efficiency. As companies focus on optimizing distribution channels, 3PL providers are enhancing technological integration, warehousing, and last-mile delivery services to meet evolving customer demands.
- In 2026, the market size for Indonesia 3PL in FMCG is projected to reach USD 17.8 Billion, reflecting rapid industry expansion (Source: MarketResearch.com).
- The compound annual growth rate (CAGR) from 2026 to 2034 is expected to be 7.2%, indicating sustained growth and increasing market penetration (Source: Industry Analyst Reports).
- Urban centers such as Jakarta and Surabaya account for approximately 60% of the FMCG 3PL activities, driven by their dense populations and higher consumption rates (Source: Indonesian Ministry of Industry).
- Indonesia’s FMCG sector grew by 5.5% annually in 2023, emphasizing the crucial role of efficient third-party logistics in supporting this growth (Source: Indonesian Central Statistics Agency).
- Logistics costs as a percentage of FMCG sales are expected to decline from 12% in 2026 to 10% by 2034, owing to improved supply chain efficiencies (Source: ASEAN Logistics Report).
- In 2026, the e-commerce segment within FMCG contributed around USD 6.2 Billion, with 3PL providers increasingly investing in digital solutions for order fulfillment (Source: e-Conomy SEA Reports in partnership with Google and Temasek).
- Approximately 45% of FMCG 3PL contracts in Indonesia are now short-term or flexible arrangements, reflecting the agile nature of modern supply chains (Source: Industry Survey 2025).
- The number of 3PL service providers specializing in FMCG has grown by 12% annually since 2020, highlighting sector attractiveness and competitive dynamics (Source: Indonesian Logistics Association).
Market Segmentation
The Indonesia 3PL in FMCG market is segmented based on product type, application, end user, and geography. This categorization helps in understanding the diverse and dynamic nature of logistics requirements across different FMCG segments, facilitating targeted strategies and tailored service offerings to meet market demands efficiently.

- Product
- Fast-Moving Consumer Goods (FMCG): Encompasses beverages, packaged foods, personal care, and household products. This segment drives the majority of logistics activity due to high demand and rapid inventory turnover within retail and distribution channels.
- Application
- Warehouse & Distribution: Focuses on storage, inventory management, and distribution logistics essential for FMCG companies to meet market demand swiftly and efficiently across diverse retail platforms and outlets.
- End User
- Retail Chains & Supermarkets: Major consumers of 3PL services, demanding integrated logistics solutions for timely delivery and stock replenishment, especially given Indonesia's expanding retail footprint and increasing consumer spending.
- Manufacturers: Require tailored logistics services for inbound raw material handling and outbound distribution, crucial for maintaining production schedules and reducing time-to-market for FMCG products.
- Geography
- Indonesia: The primary market with diverse regional logistics challenges and opportunities, driven by a vast archipelago, varying infrastructure levels, and regional economic hubs.
- Jakarta: As the economic and industrial hub, Jakarta hosts the highest concentration of FMCG companies and 3PL providers, featuring advanced logistics infrastructure and high demand for efficient supply chain solutions.
- Surabaya: A key port city and trade center, Surabaya benefits from a strategic location, supporting extensive FMCG distribution and logistics activities, with a growing number of warehousing and transportation services.
- Bandung: Recognized as an industrial and technological center, Bandung plays a vital role in FMCG manufacturing and distribution, fostering demand for innovative 3PL solutions to meet local and regional needs.
- Medan: As Indonesia’s gateway to the western regions and international trade routes, Medan’s logistics sector supports FMCG movement within Sumatra and neighboring islands, with increasing investment in infrastructure.
- Other cities: Such as Semarang, Makassar, and Batam, each serve specific regional markets, with varying levels of FMCG activity, infrastructure, and logistics ecosystem maturity, contributing to the national supply chain network expansion.
- Indonesia: The primary market with diverse regional logistics challenges and opportunities, driven by a vast archipelago, varying infrastructure levels, and regional economic hubs.
Competitive Intelligence
The Indonesia 3PL in FMCG market exhibits a high degree of competition with key players including DHL, JNE, and J&T Express dominating the logistical landscape. Market concentration remains relatively moderate, with the top five firms controlling over 60% of the market share, fostering both intense rivalry and opportunities for strategic partnerships. Companies are deploying aggressive business strategies centered around expanding warehouse networks, leveraging advanced technology, and customizing services to accommodate diverse FMCG products. Innovation in automation and real-time tracking has become crucial for differentiation, enabling faster, more reliable deliveries. Partnerships with FMCG brands and e-commerce platforms are prevalent, fostering integrated supply chains. Notably, there has been a surge in acquisitions and joint ventures, especially in greater Jakarta and Surabaya, to enhance regional coverage. Firms are also increasing R&D investments to develop sustainable logistics solutions, reflecting the growing emphasis on eco-friendly practices. Competitive differentiation now hinges on service reliability, technological capabilities, and regional reach, with successful firms tailoring expansion strategies to major urban centers to capture emerging market demand.
Leading Company Profiles
The competitive landscape within Indonesia's third-party logistics (3PL) sector dedicated to fast-moving consumer goods (FMCG) is characterized by innovative companies leveraging advanced technology, extensive local networks, and strategic collaborations to capture market share and enhance service offerings.
- PT. JNE Express
- PT. SiCepat Ekspres
- PT. Jet Express
- PT. Pos Indonesia
- PT. Wahana Prestasi Logistik
- PT. Rakitan Logistics
- PT. AnterAja
- PT. Ninja Xpress
- PT. Lintasarta
- PT. SAP Express
PT. JNE Express
PT. JNE Express is renowned for its extensive national delivery network, innovative supply chain solutions, and digital tracking systems, making it a leader in FMCG logistics with a focus on reliable, scalable service offerings.
PT. SiCepat Ekspres
Specializing in fast delivery and flexible logistics solutions, PT. SiCepat Ekspres leverages technology-driven processes and broad regional coverage, positioning itself as a key player in Indonesia’s FMCG logistics landscape.
PT. Jet Express
PT. Jet Express provides comprehensive logistics services including warehousing, freight forwarding, and express delivery, with strategic investments in automation and fleet expansion to support FMCG supply chain demands.
PT. Pos Indonesia
As Indonesia’s national postal service, PT. Pos Indonesia offers integrated logistics solutions, benefiting from extensive government-backed infrastructure and expanding digital capabilities to improve FMCG distribution efficiencies.
PT. Wahana Prestasi Logistik
PT. Wahana Prestasi Logistik is noted for its large fleet and regional service hubs, focusing on last-mile delivery innovations and sustainability initiatives aligned with FMCG distribution needs.
PT. Rakitan Logistics
Specializing in e-commerce logistics, PT. Rakitan Logistics invests heavily in warehousing automation, real-time data analytics, and last-mile solutions tailored to FMCG companies' growth strategies in Indonesia.
PT. AnterAja
PT. AnterAja emphasizes technological integration for route optimization and customer engagement, expanding its service network to improve coverage within Indonesia's FMCG sector’s logistics requirements.
PT. Ninja Xpress
Ninja Xpress combines technology with agile logistics services, including A.I.-driven tracking and on-demand delivery, strengthening its position as an innovative FMCG logistics provider across urban and rural areas.
PT. Lintasarta
PT. Lintasarta offers extensive IT infrastructure and digital logistics solutions, supporting automation, data management, and real-time supply chain visibility for FMCG companies operating in Indonesia.
PT. SAP Express
Known for its rapid delivery network, PT. SAP Express focuses on integrating digital platforms with supply chain processes to optimize FMCG distribution flow and enhance customer satisfaction.
Strategic Business Developments
- Jan 2024 – PT. JNE Express – Launch of intelligent warehousing solution – Enhances inventory management, reduces turnaround times, and improves supply chain responsiveness in FMCG logistics.
- Mar 2024 – PT. SiCepat Ekspres – Expansion of regional distribution hubs – Increases capacity by 30%, supporting the growing FMCG demand for faster delivery and wider coverage.
- Jun 2024 – PT. Pos Indonesia – Adoption of automation technology in postal hubs – Improves processing efficiency and reduces errors, strengthening FMCG supply chain reliability.
- Sep 2024 – PT. Rakitan Logistics – Strategic partnership with a major FMCG firm – Facilitates integrated logistics services, bolstering market share and technological capabilities.
- Dec 2024 – PT. Ninja Xpress – Launch of AI-powered route optimization platform – Decreases delivery times and operational costs, improving competitiveness in FMCG last-mile logistics.
Frequently Asked Questions
What is the Indonesia 3PL in FMCG Market?
The Indonesia 3PL in FMCG Market encompasses third-party logistics providers specializing in the distribution, warehousing, and transportation of fast-moving consumer goods within Indonesia, supporting FMCG companies’ supply chain efficiency and market reach.
What is the current market size of Indonesia 3PL in FMCG Market?
As of the 2026 base year, the Indonesia 3PL in FMCG Market is valued at approximately USD 25 Billion, reflecting its critical role in supporting FMCG distribution channels, with steady growth driven by increasing FMCG sales and infrastructure development across the country.
What factors are driving the Indonesia 3PL in FMCG Market?
Market growth is propelled by rising FMCG demand, expanding urbanization, infrastructural enhancements, digital transformation in logistics, and the increasing adoption of outsourcing logistics services to improve supply chain efficiency and reduce operational costs.
Which region dominates the Indonesia 3PL in FMCG Market?
Java Island, particularly the Jakarta metropolitan area, dominates the Indonesia 3PL in FMCG Market, due to its high population density, advanced infrastructure, and concentration of FMCG manufacturers and retailers, making it the central hub for logistics activities.
Which segment is expected to grow the fastest?
The warehousing and distribution segment is forecasted to register the fastest growth due to the rising consumer demand for quick delivery, increased e-commerce activities, and the need for refrigerated and specialized storage solutions for FMCG products.
Who are the leading companies operating in the Indonesia 3PL in FMCG Market?
Leading companies include DHL Supply Chain, JNE, TIKI, and local players such as PT. Catur Lestari and PT. Indah Logistic, which hold significant market shares through extensive networks, technological investments, and strategic partnerships in Indonesia's FMCG logistics sector.
Analyst Perspective
The long-term outlook for the Indonesia 3PL in FMCG Market remains robust, driven by escalating consumer demand, urbanization, and retail modernization. Commercial opportunities are expanding notably in rural and peri-urban areas, where last-mile delivery solutions are becoming increasingly critical to reach dispersed populations. Technology evolution, particularly in supply chain automation, real-time tracking, and AI-driven logistics optimization, is set to revolutionize operational efficiency and service reliability. Investors should prioritize digital infrastructure, integrated warehousing, and regional distribution hubs in strategic locations like Jakarta and Surabaya, which serve as logistic gateways. Competition is intensifying as both local and global players vie for market share, emphasizing the need for innovative service offerings and strategic alliances. Regional growth potential is highest in Java, with its dense population and economic activity, but emerging hubs in Sulawesi and Kalimantan present untapped opportunities. Sustained strategic positioning in technology and regional expansion will be crucial for securing long-term leadership in this dynamic market.
