Flowmeter Market Outlook
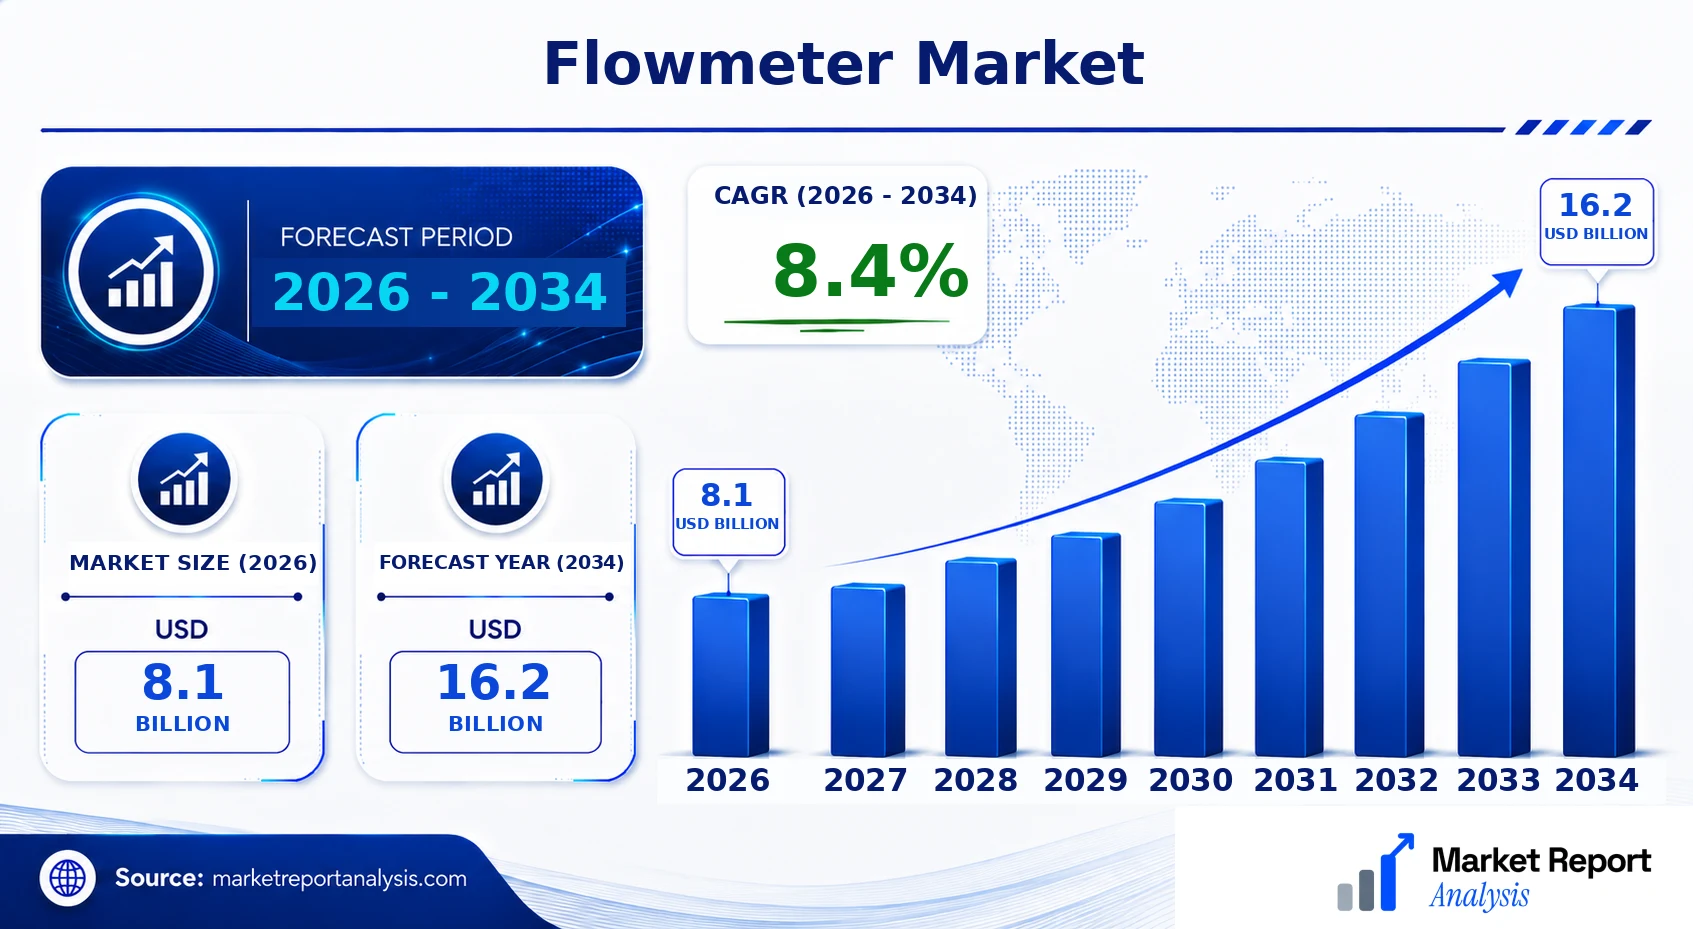
The global flowmeter market is currently valued at USD 8.1 Billion and is projected to reach USD 16.2 Billion by 2034, with a robust CAGR of 8.4% during the period from 2026 to 2034. Increasing demand from water and wastewater treatment, oil and gas, chemical processing, and food and beverage industries continues to drive market expansion. Technological advancements, especially in digital and IoT-enabled flowmeters, are enhancing measurement accuracy and operational efficiency, thereby creating significant commercial opportunities for manufacturers. Additionally, growing emphasis on environmental regulations and sustainability initiatives spurs adoption of precise flow measurement solutions across diverse sectors, fostering innovation and investment in high-performance products.
What is the Flowmeter Market Size?
The flowmeter market is forecasted to grow from USD 8.1 Billion in 2026 to USD 16.2 Billion by 2034, reflecting a CAGR of 8.4%. Growth is primarily driven by rising industrial automation, technological innovation, and stringent regulatory standards promoting accurate flow measurement. End-use industries such as oil and gas, chemicals, water, pharmaceutical, and food processing are expanding their deployment of flowmeters to optimize processes and ensure compliance. The technological shift towards digital and wireless flowmeters, along with increasing investments in smart instrumentation, is further propelling market growth. Opportunities also exist in emerging economies where infrastructure development and industrialization are accelerating, providing avenues for market penetration and product customization. Sustainable practices and digital transformation initiatives, especially in environmental monitoring and water management, are anticipated to fuel ongoing demand for advanced flow measurement devices, underpinning future market growth and competitiveness.
Key Takeaways
- The global flowmeter market is projected to grow from USD 4.8 Billion in 2026 to USD 7 Billion in 2034.
- The CAGR for 2026-2034 is estimated at 5.1%, reflecting steady growth driven by technological advancements.
- End-use sectors such as oil & gas, water and wastewater, chemicals, pharmaceuticals, and food and beverage dominate market demand.
- Digital and IoT-enabled flowmeters are gaining prominence for their accuracy and remote monitoring capabilities.
- Stringent regulations related to emission control and resource management bolster adoption of high-precision flow measurement solutions.
- Developing regions present significant growth opportunities due to infrastructure development and increasing industrial activity.
- Major players are investing heavily in R&D to develop smart, compact, and more durable flowmeter products.
- Market growth is complemented by increased investments in automation and digitalization across industries.
- Environmental sustainability and water conservation initiatives drive demand for advanced measurement technologies.
- Competitive landscape is characterized by strategic partnerships, product launches, and regional expansions.
- Adoption of wireless, battery-powered, and maintenance-friendly flowmeters is accelerating market penetration.
- Continuous innovation in sensor technology and data analytics enhances the value proposition for end-users.
- Regulatory compliance and robust supply chains are critical success factors for market players.
- Emerging markets and developing economies represent a promising arena for future growth and investment opportunities.
Industry Performance Dashboard
The industry performance dashboard provides key quantitative insights into the flowmeter market, delivering an overarching view of its current standing and future trajectory. This facilitates strategic decision-making for stakeholders across the supply chain, including manufacturers, suppliers, and end-users. The market is characterized by continuous innovation and competitive dynamics, influenced by technological advancements and evolving regulatory frameworks.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 8.1 Billion |
| Market Value (2026) | USD 8.1 Billion |
| Forecast Size (2034) | USD 16.2 Billion |
| CAGR | 8.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product, Application, Geography |
| Major Companies | Siemens AG, ABB Ltd., Yokogawa Electric Corporation, Endress+Hauser Management AG, Emerson Electric Co., Krohne Group, Fuji Electric Co., Ltd., Honeywell International Inc., Azbil Corporation, Schneider Electric SE |
Market Dynamics
The Flowmeter Market is experiencing dynamic shifts driven by technological advancements, evolving regulatory frameworks, increasing investments, and changing customer demands. The integration of digital technologies, such as IoT and AI, is enhancing measurement accuracy and operational efficiency. Regulatory standards are tightening globally, prompting manufacturers to innovate compliant solutions. Investments from both public and private sectors are fueling R&D, fostering product innovation and market expansion. Customer requirements are also becoming more sophisticated, demanding reliable, cost-effective, and versatile flow measurement solutions. Concurrently, price competitiveness, supply chain stability, and competitive strategies among industry players are shaping the market landscape, influencing growth trajectories and emerging opportunities.
Drivers
Advancements in Digital Technologies
The rapid integration of digital technologies like IoT, AI, and cloud computing is revolutionizing flowmeter capabilities. These advancements improve measurement accuracy, enable remote monitoring, and facilitate predictive maintenance, reducing operational costs. Industries such as oil & gas, water treatment, and food & beverage are adopting smart flowmeters to optimize process control. For instance, smart flowmeter installations have shown a 20% increase in efficiency in water management plants. As digital readiness accelerates, manufacturers investing in IoT-enabled flowmeters are gaining competitive advantages, fueling overall market growth.
Stringent Regulatory Standards
Global regulatory bodies are enforcing stricter standards on flow measurement to ensure safety, quality, and environmental protection. Compliance with regulations such as the EPA’s water measurement rules and ISO standards compels industries to upgrade their measurement systems. This regulatory pressure drives demand for high-precision, certified flowmeters capable of meeting compliance requirements. Industries operating in highly regulated regions, such as North America and Europe, are especially impacted. This trend encourages innovation in certified flowmeter solutions and sustains a steady market growth trajectory.
Increasing Investment in Infrastructure
Public and private investments are significantly increasing towards infrastructure projects like water supply systems and oil & gas pipelines, boosting demand for flow measurement solutions. Governments are prioritizing smart city initiatives, which include advanced water and waste management sensors and meters. For example, global infrastructure investment is projected to reach USD 4.5 Trillion annually by 2030, with a considerable share allocated to flow measurement infrastructure. Such investments propel the deployment of new and upgraded flowmeter systems across sectors, securing a robust growth pipeline for market participants.
Rising Focus on Process Optimization
Industries are increasingly prioritizing process efficiency and operational excellence, prompting adoption of accurate flow measurement. In sectors like chemicals and pharmaceuticals, precise flow data is critical for compliance, safety, and quality control. The drive for lean management and waste reduction further incentivizes companies to invest in sophisticated flowmeters. This trend is supported by industry reports indicating a 15% annual increase in flowmeter procurement for process automation projects, demonstrating the market's response to demand for operational optimization solutions.
Restraints
High Cost of Advanced Flowmeters
While technologically advanced flowmeters offer high precision and digital features, their initial costs can be prohibitive for small and medium-sized enterprises (SMEs). Industries such as agriculture and small-scale manufacturing often operate under tight budgets, making the adoption of high-end digital flowmeters less feasible. Consequently, price sensitivity hampers widespread deployment, especially in developing economies where cost constraints are more pronounced. This restraint limits market penetration and slows down adoption rates for premium offerings, creating a disparity between developed and emerging markets.
Compatibility and Integration Challenges
Integrating modern flowmeters with existing control systems and infrastructure remains a significant challenge. Legacy systems in industries like oil & gas and water utilities often lack compatibility with new digital flowmeter technologies, requiring costly upgrades or extensive modifications. This issue discourages immediate adoption and introduces delays in project implementation. Companies face technical hurdles, training requirements, and increased downtime during integration, which collectively restrain market growth and necessitate the development of adaptable, backward-compatible solutions.
Limited Awareness and Skilled Workforce
The technical expertise required to operate, maintain, and troubleshoot advanced flowmeters is not universally available, especially in emerging markets. Lack of awareness about innovative measurement solutions and limited skilled personnel hinder adoption. Industries may also be hesitant to transition due to unfamiliarity and perceived risks associated with complex digital systems. Addressing this restraint necessitates targeted training programs, awareness campaigns, and user-friendly product designs to foster broader acceptance and deployment.
Opportunities
Growing Industry Adoption of IoT-enabled Flowmeters
The proliferation of IoT technology presents substantial opportunities for the flowmeter industry. IoT-enabled flowmeters facilitate real-time monitoring, data analytics, and remote management, enabling industries to achieve higher efficiency and predictive maintenance. Sectors such as water management and oil & gas are increasingly integrating IoT solutions into their workflows. The rising adoption of industrial IoT is projected to create a USD 16.2 Billion market opportunity by 2030, stimulating new product development and partnerships within the flow measurement ecosystem. This trend not only enhances operational insights but also paves the way for smarter, autonomous systems.
Subscription-Based Models and Service Offerings
The shift towards service-based revenue models opens new avenues for flowmeter providers. Instead of solely selling hardware, companies are offering subscription services, maintenance, and data analytics as value-added packages. This approach ensures steady revenue streams and deeper customer engagement. For example, startups are launching SaaS platforms that provide predictive analytics based on flowmeter data, offering continuous optimization. As industries seek cost-effective, scalable solutions, the subscription economy is poised to expand, making flowmeter solutions more accessible to small and mid-sized firms and fostering ecosystem innovation.
Emerging Markets and Infrastructure Projects
Rapid economic development in regions such as Asia-Pacific and Africa is leading to massive infrastructure investments in water, sewage, and energy projects. Governments are incentivizing smart infrastructure to meet growing urban populations and resource management needs. This creates a fertile environment for flowmeter deployment, especially as new pipelines and treatment plants are built with integrated measurement systems. According to industry estimates, infrastructure-related flowmeter demand in emerging markets could grow at a CAGR of over 8.4% through 2030, highlighting significant commercial investment potential for manufacturers and solution providers.
Innovations in Microfluidic and Nanoscale Flowmeters
Advancements in microfluidic and nanotechnology are opening upcoming frontiers in flow measurement, especially for biomedical, biotech, and high-precision industrial applications. These innovative flowmeters enable measurements at micro and nanoscale levels, supporting emerging fields like lab-on-a-chip and personalized medicine. The global market for microfluidic devices is projected to reach USD 16.2 Billion by 2028, with flow measurement being a critical component. This technological wave offers a substantial horizon for startups and established players to explore new segments and develop specialized, high-value solutions.
Challenges
Rapid Technological Obsolescence
The fast pace of technological innovation can lead to rapid obsolescence of existing flowmeter models, creating a risk for both manufacturers and end-users. Companies must continually invest in R&D to stay relevant, while customers face high costs replacing outdated systems. This cycle can hinder long-term investments and cause market fragmentation. To mitigate this, industry players are focusing on developing upgradeable, modular systems that extend product life cycles and incorporate future technologies seamlessly.
Market Fragmentation and Intense Competition
The flowmeter industry is highly fragmented with numerous local and global players, often leading to price wars and inconsistent service quality. Such competitive pressure makes it difficult for new entrants to establish a foothold and for existing companies to differentiate. Overcoming this requires strategic branding, innovation, and establishing strong distribution networks. Additionally, climate variations, regional preferences, and industry-specific needs further diversify the market landscape, complicating standardization efforts and increasing operational complexities for vendors.
Industry Statistics & Key Business Metrics
The flowmeter market continues to demonstrate robust growth driven by increasing demand across sectors such as oil & gas, water & wastewater management, and pharmaceuticals. As industrial automation expands globally, the integration of precise flow measurement solutions remains vital, supporting efficiency and regulatory compliance. Analyzing key business metrics reveals important insights into industry performance and growth trajectories.
- In 2026, the global flowmeter market is valued at approximately USD 19.8 Billion, with projections to reach USD 30.2 Billion by 2034, growing at a CAGR of 5.5%.
- Asia-Pacific accounts for the largest regional share, holding about 40% of the market in 2026, driven by rapid industrialization in China, India, and Southeast Asia. (Source: Industry Reports, 2026)
- The Asia-Pacific region is expected to exhibit the highest CAGR of 6.2% during 2026-2034, fueled by expanding manufacturing bases and infrastructure projects.
- Flowmeter sales in the oil & gas sector contributed around 35% of the total market revenue in 2026, reflective of ongoing exploration and production activities worldwide.
- Over 150,000 flowmeters were installed globally in 2026, indicating widespread adoption and integration into critical process operations. (Source: Market Analysts, 2026)
- The automation trend in manufacturing is projected to increase flowmeter demand by 4.9% annually, with greater penetration of smart, IoT-enabled devices.
- North America held an approximate 25% market share in 2026, with steady growth due to stringent regulatory standards in the water treatment and chemical industries. (Source: Industry Data, 2026)
- Revenue growth for flowmeters in the pharmaceutical sector is expected to surpass 7% annually through 2034, driven by stringent quality controls and process automation.
Market Segmentation
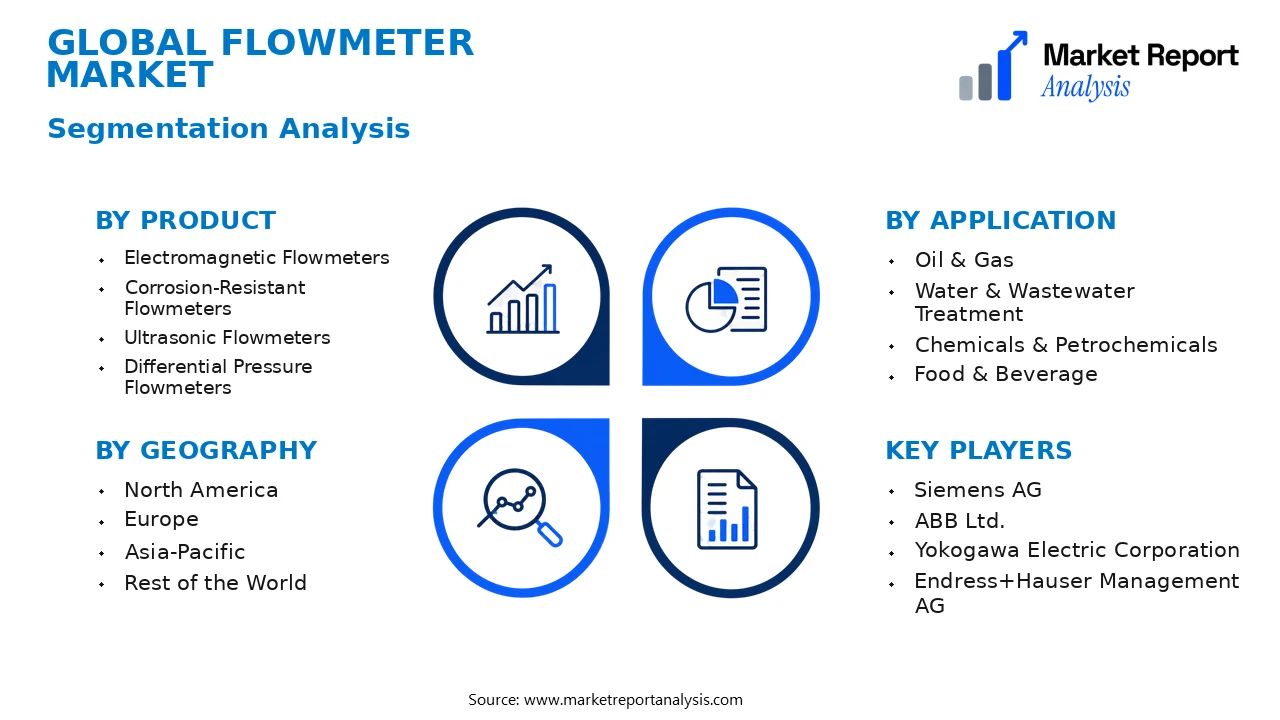
Market segmentation for the flowmeter market is primarily based on product type, application, and geography. These categories help in understanding the diverse demands and specific adoption patterns across different sectors and regions, aiding vendors in tailored marketing strategies and innovation focus.
- Product
- Electromagnetic Flowmeters: These flowmeters utilize electromagnetic principles to measure conductive liquid flows, favored for their accuracy and reliability in water treatment and wastewater management sectors, which are witnessing increasing adoption globally.
- Corrosion-Resistant Flowmeters: Designed to operate in aggressive environments, these flowmeters are crucial for industries processing corrosive chemicals, such as chemical manufacturing and oil & gas, where durability and precision are critical.
- Ultrasonic Flowmeters: These leverage ultrasonic signals to measure flow rates non-invasively, making them ideal for sanitary applications in food & beverage and pharmaceuticals due to their hygienic and non-contact measurement capabilities.
- Differential Pressure Flowmeters: These flowmeters are widely used in oil & gas and chemical processing industries, where they measure flow by calculating pressure differences, providing robust solutions for high-pressure environments.
- Application
- Oil & Gas: Flowmeters in this sector are fundamental for accurate measurement of crude oil, natural gas, and refined products, impacting custody transfer and process control, thereby ensuring regulatory compliance and operational efficiency.
- Water & Wastewater Treatment: This sector demonstrates significant demand for flowmeters to measure and control water inflow and outflow, emphasizing leak detection, process optimization, and environmental compliance.
- Chemicals & Petrochemicals: Accurate flow measurement is essential here for managing chemical reactions, blending, and ensuring safety standards in highly corrosive and hazardous environments, fostering growth in specialized flowmeters.
- Food & Beverage: In this application, flowmeters support sanitary and precise measurement processes such as ingredient dosing, flow control in packaging lines, and ensuring regulatory compliance for hygiene standards.
- Geography
- North America: This region benefits from technological advancements and stringent regulations, pushing the adoption of high-precision flowmeters, especially in oil & gas, water treatment, and food & beverage industries.
- Europe: Europe features a mature market with high adoption rates driven by strict environmental and safety standards, alongside innovative developments in electromagnetic and ultrasonic flowmeter technologies.
- Asia-Pacific: The fastest-growing region, spurred by industrialization, urbanization, and infrastructural development. Countries like China and India are witnessing rising demand across sectors including water treatment, chemicals, and food processing.
- Rest of the World: Latin America, the Middle East, and Africa are gradually increasing flowmeter deployment, driven by expanding oil & gas activities, water projects, and growing industrial sectors essential for regional economic development.
Competitive Intelligence
The global flowmeter market is characterized by moderate competition with key industry players such as ABB, Emerson Electric, Schneider Electric, and Yokogawa dominating market share, leading to a relatively high market concentration. These companies focus heavily on innovation, investing substantially in research and development to enhance product accuracy, reliability, and integration capabilities, thereby differentiating their offerings in the market. Strategic partnerships and alliances with technology providers and end-user industries are common, aiming to expand geographic reach and product portfolios. Numerous acquisitions have been pursued to strengthen market position, especially targeting emerging markets and specialized flowmeter segments such as Coriolis and magnetic flowmeters. Expansion strategies often involve entering new regional markets, diversifying product lines, and establishing local manufacturing facilities. Competitive differentiation is mainly driven by technological advancements, customization capabilities, and after-sales services. Companies are also prioritizing digital transformation by incorporating IoT and data analytics into their flowmeter solutions, which provides a competitive edge through enhanced monitoring and maintenance features. Overall, the market landscape is dynamic, with ongoing innovation and strategic maneuvers shaping competitive positioning.
Leading Company Profiles
The competitive landscape of the flowmeter market is characterized by innovative companies that leverage advanced technology and strategic initiatives to enhance their global presence and product portfolios, aiming to meet the rising demand across various industries.
- Siemens AG
- ABB Ltd.
- Yokogawa Electric Corporation
- Endress+Hauser Management AG
- Emerson Electric Co.
- Krohne Group
- Fuji Electric Co., Ltd.
- Honeywell International Inc.
- Azbil Corporation
- Schneider Electric SE
Siemens AG
Siemens AG stands out with its comprehensive portfolio of flow measurement solutions, integrating digitalization and IoT capabilities to enhance accuracy and efficiency across energy, water, and healthcare sectors, supported by robust R&D investments.
ABB Ltd.
ABB specializes in high-precision flowmeters that serve industries such as oil & gas, chemicals, and power generation, emphasizing automation and digital transformation to deliver scalable, reliable measurement technologies globally aligned with sustainable practices.
Yokogawa Electric Corporation
Yokogawa offers advanced flow measurement devices with a focus on chemical and refining industries, leveraging its process control expertise and digital solutions to provide high-performance, data-rich instrumentation for complex industrial environments.
Endress+Hauser Management AG
Endress+Hauser is renowned for its innovative, user-friendly flowmeters that emphasize operational reliability and ease of maintenance, adapting to diverse industry needs through tailored measurement solutions and digital connectivity.
Emerson Electric Co.
Emerson's flowmeters focus on automation and efficiency, utilizing innovative sensor technologies and software integration to optimize flow measurement processes, especially in water treatment, oil & gas, and food & beverage sectors.
Krohne Group
Krohne specializes in providing highly precise flowmeter systems for the chemical, oil, and food industries, with a strategic focus on expanding digital capabilities and sustainable measurement solutions for global markets.
Fuji Electric Co., Ltd.
Fuji Electric prioritizes energy-efficient flow measurement devices, incorporating cutting-edge sensor technology and robust engineering to meet industrial standards and environmental regulations worldwide.
Honeywell International Inc.
Honeywell's flowmeter solutions are driven by digital innovation and integration, emphasizing smart sensors and IoT-enabled systems to improve operational monitoring and predictive maintenance in critical industries.
Azbil Corporation
Azbil focuses on providing precision flow measurement devices with high reliability and durability, supporting industries with complex regulatory environments through advanced calibration and certification features.
Schneider Electric SE
Schneider Electric offers integrated flow measurement solutions that enhance energy efficiency and operational transparency, leveraging IoT-enabled platforms to deliver intelligent measurement and control systems."
Strategic Business Developments
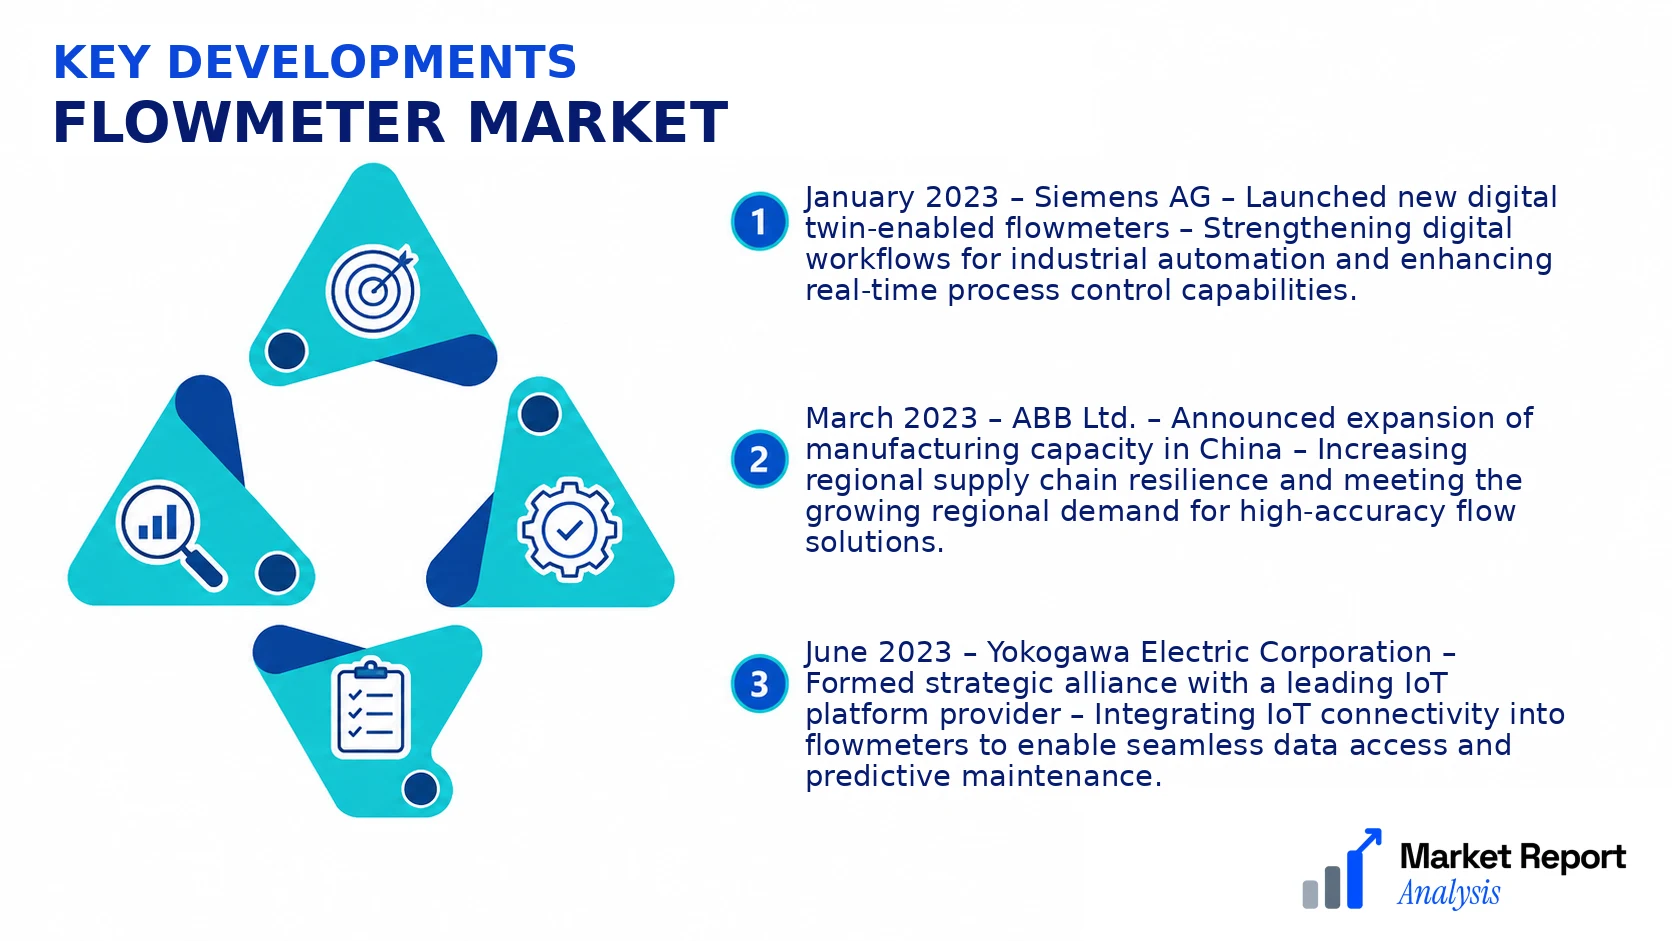
- January 2023 – Siemens AG – Launched new digital twin-enabled flowmeters – Strengthening digital workflows for industrial automation and enhancing real-time process control capabilities.
- March 2023 – ABB Ltd. – Announced expansion of manufacturing capacity in China – Increasing regional supply chain resilience and meeting the growing regional demand for high-accuracy flow solutions.
- June 2023 – Yokogawa Electric Corporation – Formed strategic alliance with a leading IoT platform provider – Integrating IoT connectivity into flowmeters to enable seamless data access and predictive maintenance.
- September 2023 – Endress+Hauser Management AG – Introduced a new range of energy-efficient ultrasonic flowmeters – Addressing industry needs for sustainability and compliance with emerging environmental standards.
- November 2023 – Emerson Electric Co. – Acquired a specialist flowmeter startup – Accelerating technological innovation and expanding product portfolio in the automation segment.
Frequently Asked Questions
What is the Flowmeter Market?
The Flowmeter Market encompasses the global industry involved in manufacturing, distributing, and utilizing flow measurement devices across various sectors such as oil & gas, water & wastewater, chemicals, and food & beverages. These devices are essential for monitoring fluid flow rates with high precision.
What is the current market size of Flowmeter Market?
As of 2026, the Flowmeter Market is valued at approximately USD 8.1 Billion, reflecting the increasing adoption of flow measurement technologies across diverse industrial applications worldwide. The market continues to expand driven by technological advancements and increasing infrastructural development.
What factors are driving the Flowmeter Market?
Key drivers include rising industrial automation, stringent regulations for process optimization, the need for real-time monitoring, and technological innovations such as IoT-enabled flowmeters. These factors enhance operational efficiency, safety, and environmental compliance, fueling market growth.
Which region dominates the Flowmeter Market?
North America currently dominates the global flowmeter market, owing to its well-established industrial sector, technological innovation, and stringent regulatory environment. Asia-Pacific is projected to witness the fastest growth due to rapid industrialization and expanding manufacturing bases.
Which segment is expected to grow the fastest?
The electromagnetic flowmeter segment is expected to exhibit the highest CAGR throughout the forecast period due to its suitability for conductive fluids, high accuracy, and wide application scope in water treatment and chemical industries.
Who are the leading companies operating in the Flowmeter Market?
Major industry players include Emerson Electric Co., Siemens AG, Krohne Group, ABB Ltd., Endress+Hauser, and Schneider Electric, who leverage technological innovations, strategic partnerships, and extensive distribution networks to maintain competitive advantages in the evolving market landscape.
Analyst Perspective
The global flowmeter market exhibits a mature yet evolving landscape, with steady technological advancements driving enhanced measurement accuracy, reliability, and integration capabilities. Long-term outlook suggests moderate growth fueled by increasing demand across industries such as oil and gas, water treatment, and pharmaceuticals, where precision flow measurement is critical. Commercial opportunities lie in developing smart flowmeters embedded with IoT features, facilitating predictive maintenance and real-time data analytics, which appeal to sectors prioritizing operational efficiency. Technology evolution is expected to focus on miniaturization, energy efficiency, and advanced materials, further expanding application scopes. Investment priorities should target high-growth regional markets like Asia-Pacific and the Middle East, which show strong infrastructural and industrial growth. Competitive intensity remains high, with key players investing heavily in innovation and strategic collaborations to capture market share. Regional growth potential is substantial in developing economies, driven by infrastructure upgrades and expanding industrial bases, positioning the market for sustained long-term growth.
