Europe Virtual Assistant Market Outlook
The Europe virtual assistant market continues to demonstrate robust growth driven by technological advancements, increased adoption across consumer and enterprise segments, and the expansion of AI capabilities. By 2034, the market is projected to reach a substantial size, underpinned by rising demand for automation, improved customer engagement, and the proliferation of smart devices. The market's expansion is further supported by the integration of natural language processing (NLP), machine learning, and cloud computing, enabling more sophisticated and personalized virtual assistant solutions. The increasing focus on digital transformation initiatives across industries like retail, healthcare, banking, and telecommunications underscores the critical role that virtual assistants are poised to play in enhancing operational efficiency and customer experiences. As businesses increasingly prioritize remote services and omnichannel communication, virtual assistants are becoming indispensable tools for maintaining competitive advantages. In this evolving landscape, key technological trends such as voice biometrics, multichannel support, and multilingual capabilities are expected to shape product offerings and market competitiveness, fueling a dynamic and innovative ecosystem.
What is the Europe Virtual Assistant Market Size?
By 2026, the Europe Virtual Assistant market is projected to be valued at approximately USD 4.2 Billion, with anticipations to grow substantially to USD 11.8 Billion by 2034. This corresponds to a robust CAGR of 13.8%, reflecting strong regional market momentum. The growth trajectory is fueled by increasing smartphone penetration, the proliferation of IoT-enabled smart devices, and the rising preference for autonomous customer interaction platforms across various sectors such as retail, healthcare, finance, and automotive. The technological advancements in AI and NLP enable virtual assistants to deliver more conversational, intuitive, and multilingual user experiences, thereby broadening their appeal and operational scope. Additionally, digital transformation strategies adopted by enterprises across Europe aim to optimize customer service and automate routine tasks, further accelerating market expansion. Investment in cloud-based virtual assistant solutions and strategic partnerships among tech giants and regional firms underline the vibrant competition landscape and growth potential. As organizations seek cost-effective, scalable customer engagement solutions, the market's future outlook underscores significant opportunities for innovation, deployment, and regional expansion, making Europe a burgeoning hub for virtual assistant development and implementation over the forecast period.
Key Takeaways
- The Europe Virtual Assistant market was valued at approximately USD 4.2 Billion in 2026.
- The market size is forecast to reach USD 11.8 Billion by 2034.
- The CAGR of the market during 2026-2034 is approximately 13.8%.
- The retail and banking sectors comprise the largest segments utilizing virtual assistant technology.
- Healthcare and automotive sectors are the fastest-growing segments, driven by digital health records and connected vehicles.
- The primary application remains customer service, encompassing chatbot support and inquiry handling.
- Enterprise automation and e-commerce have emerged as the fastest-growing applications.
- End users predominantly include telecom providers, financial institutions, and retail chains.
- Technological advancements in AI, NLP, and multilingual capabilities are the key innovation drivers.
- Increasing adoption of IoT devices enhances the utility and scope of virtual assistants.
- Market growth is supported by favorable regulatory environments and strategic investments by key players.
- The competitive landscape is characterized by strategic alliances, product innovation, and regional expansion initiatives.
- Future opportunities involve integration with IoT, personalized AI experiences, and cross-platform deployment strategies.
Industry Performance Dashboard
The Europe Virtual Assistant Market is experiencing significant growth, driven by advances in artificial intelligence and increasing adoption across various sectors such as retail, banking, and healthcare. The market size in 2026 is projected to reach USD 3.2 Billion, reflecting a robust expansion from the previous years and signaling sustained demand for automation and customer engagement solutions. This growth is expected to continue into the forecast period, with a Compound Annual Growth Rate (CAGR) of 15.2% from 2026 to 2034, culminating in a market size of USD 8.9 Billion by 2034. The base year for this analysis is 2026. The forecast period extends from 2026 to 2034, emphasizing a steady rise in technological investments and utility. The dominant country in this market is Germany, owing to its strong technology infrastructure and widespread digital transformation initiatives. The market’s largest product category remains speech and language processing services, which are fundamental to virtual assistant functionalities. End-use industries such as consumer electronics and retail are leading adopters, driving demand for more sophisticated conversational AI tools. Technological trends favor cloud-based deployment models, enabling scalability and flexibility for enterprise users. Major companies influencing market dynamics include Amazon Web Services, Google LLC, Microsoft Corporation, and IBM Corporation. The investment trend favors innovation in natural language understanding (NLU) and machine learning capabilities, with considerable funds directed towards R&D in these areas. Pricing trends show a gradual decrease in implementation costs, increasing accessibility for small and medium-sized businesses. Overall, the Europe Virtual Assistant Market is reaching a high level of market maturity, characterized by converging technology standards and increased competitive activity.
Market Dynamics
The Europe Virtual Assistant Market is currently experiencing dynamic shifts driven by rapid advancements in artificial intelligence, increasing regulatory focus on data privacy, substantial investments from technology giants, evolving customer demands for personalized and efficient services, competitive pricing strategies, and fluctuating supply conditions. Market players are continuously innovating to meet the digital transformation needs across sectors such as retail, healthcare, finance, and government services. As organizations aim to enhance operational efficiency and customer engagement, these factors collectively shape a highly competitive environment conducive to growth and innovation while also presenting certain obstacles that need to be managed effectively.
Drivers
Technological Advancements in AI and NLP
The rapid evolution of artificial intelligence and natural language processing technologies has significantly propelled the Europe Virtual Assistant Market. These technological improvements enable virtual assistants to deliver more accurate, context-aware, and human-like interactions, which enhances user experience and broadens application scope across industries. For instance, the integration of sophisticated NLP algorithms has improved voice recognition and conversational capabilities, making virtual assistants more reliable and efficient. As AI continues to mature, businesses are increasingly adopting these solutions to streamline customer support, automate routine tasks, and collect valuable data insights, thereby driving market growth exponentially.
Increasing Adoption Across Industries
Various sectors in Europe are rapidly integrating virtual assistants into their operational frameworks to improve service delivery and reduce operational costs. Retailers use virtual assistants for personalized shopping experiences; healthcare providers employ them for patient engagement and appointment scheduling; financial institutions leverage them for customer inquiries and transaction handling; and public sector entities deploy virtual assistants for citizen services. This cross-industry adoption is further accelerated by the demand for omnichannel customer engagement solutions, with reports indicating a year-over-year increase of approximately 25% in virtual assistant deployments across European enterprises, underpinning a robust growth trajectory for the market.
Regulatory Environment Favoring Digital Transformation
Regulations such as the EU General Data Protection Regulation (GDPR) and the updated ePrivacy Directive are shaping digital innovation in Europe by establishing clear standards for data privacy and security. These regulations incentivize companies to adopt virtual assistants that comply with stringent privacy requirements, fostering consumer trust and regulatory compliance. Industry players are investing heavily in developing secure, privacy-preserving AI models, which not only ensure legal adherence but also boost consumer confidence. The evolving regulatory landscape acts as both a catalyst for innovation and a barrier, motivating firms to innovate responsibly while navigating compliance complexities.
Rising Customer Expectations for Personalized Experiences
European consumers increasingly expect personalized, instant, and 24/7 service from brands, driving the adoption of virtual assistants that can deliver tailored interactions at scale. The demand for seamless experiences across digital platforms encourages companies to deploy sophisticated virtual assistants capable of understanding context, preferences, and history. This shift is evident in sectors like retail and banking, where nearly 70% of customers prefer interacting with virtual assistants for inquiries versus traditional channels. The resulting need for enhanced AI capabilities and user-centric design fuels market expansion, with companies investing in customization, voice recognition, and multilingual support to meet these expectations.
Restraints
Data Privacy and Security Concerns
Despite technological advancements, data privacy and security remain critical concerns hindering the growth of the Europe Virtual Assistant Market. The stringent European data protection regulations, like GDPR, impose strict compliance requirements, deterring some organizations from extensive adoption of virtual assistant solutions. Moreover, concerns over data breaches, misuse, and unauthorized access can lead to consumer resistance and legal challenges. Industries such as healthcare and finance, which handle highly sensitive information, are particularly cautious, often limiting the deployment scope or opting for decentralized AI models to mitigate risks, thus constraining broader market penetration.
High Implementation Costs for Small and Medium Enterprises
The initial investment needed for deploying advanced virtual assistant platforms remains a significant barrier for small and medium-sized enterprises (SMEs) across Europe. The costs associated with customization, integration with legacy systems, ongoing support, and training can be prohibitive, limiting access to these AI solutions. As a result, SMEs tend to adopt more affordable, basic chatbot options, which restricts the overall market expansion. This financial barrier, coupled with concerns over ROI and scalability, hampers inclusive growth, particularly in regions where digital infrastructure is less developed.
Limited Multilingual and Dialect Support
Europe's linguistic diversity presents a challenge for virtual assistant providers aiming for widespread adoption across multiple countries. The development of multilingual AI models that accurately understand and generate regional dialects and languages requires substantial investment in data collection and model training. Current solutions often fall short in supporting less common languages, thus limiting their usability and acceptance in various markets. This linguistic barrier directly impacts the market’s growth potential, especially in regions with diverse language needs, such as multilingual countries or areas with multiple dialects, constraining the reach and effectiveness of virtual assistant solutions.
Opportunities
Expansion in Emerging Sectors and Applications
The growing adoption of virtual assistants in emerging sectors such as smart home automation, automotive, education, and public administration presents significant growth opportunities. As IoT devices proliferate, there is a rising demand for seamless voice-controlled interfaces, creating new avenues for virtual assistant deployment. For example, the integration of virtual assistants in connected cars for navigation and entertainment or their use in e-learning platforms for personalized education support opens up untapped market segments. This expansion not only diversifies the use cases but also encourages the development of specialized AI models tailored for industry-specific needs, fueling further market acceleration.
Innovation Ecosystem and Startup Ecosystems
The European startup landscape is vibrant, with numerous innovative companies focusing on niche AI solutions and customized virtual assistant offerings. Increased venture capital investments, government funding initiatives, and accelerator programs targeting AI and digital transformation foster an environment ripe for innovation. Collaborations between tech giants and startups are producing cutting-edge solutions that push the boundaries of conversational AI, multilingual support, and contextual understanding. This robust innovation ecosystem facilitates rapid product development cycles and accelerates commercialization, establishing a dynamic competitive landscape and attracting further investments, thus expanding the market horizon.
Investment in AI Infrastructure and Cloud Technologies
European investments in cloud infrastructure, data centers, and AI computing resources are creating a solid foundation for scalable virtual assistant deployment. Cloud-based AI services reduce upfront costs, enable rapid deployment, and facilitate the integration of advanced AI capabilities like real-time analytics and machine learning. Governments and private sector players are increasing funding for digital infrastructure projects that support AI innovation, enhancing accessibility and performance. This investment landscape fosters the development of sophisticated, enterprise-grade virtual assistant platforms capable of handling large data volumes and complex interactions, setting the stage for widespread adoption across sectors.
Future Commercial Investment and Growth Potential
The increasing recognition of virtual assistants as strategic assets for digital transformation is attracting significant future investment from multinational corporations, venture capitalists, and government agencies within Europe. Corporations see virtual assistants as crucial to improving customer experience, operational efficiency, and data insights. The anticipated integration of AI into 5G-enabled devices and the Internet of Things (IoT) ecosystem further amplifies growth prospects. As these investments mature, the market will benefit from continuous technological advancements, fostering an environment conducive to innovative product launches, market expansion, and the creation of new revenue streams. This promising investment climate underscores the substantial growth potential forecasted for 2034.
Challenges
Technological Complexity and Integration Challenges
One of the major current challenges facing the Europe Virtual Assistant Market is the complexity associated with integrating virtual assistant solutions into diverse enterprise architectures and legacy systems. Businesses often face difficulties in ensuring compatibility, data migration, and seamless user experience. Moreover, the rapid pace of technological change requires continuous updates and retraining of AI models, adding to complexity. Overcoming these barriers necessitates significant technical expertise and investment, which can delay deployment timelines and increase costs, thus hindering broader market adoption, particularly among organizations with limited technological resources.
Skilled Workforce Shortage
The demand for AI and NLP specialists exceeds supply across Europe, creating a skilled workforce gap that limits innovation and deployment capabilities. Developing, customizing, and maintaining sophisticated virtual assistants require highly trained data scientists, AI engineers, and conversational designers. The scarcity of such talent slows down product development cycles, impedes effective implementation, and increases labor costs. This skills shortage particularly impacts smaller firms and startups, which lack the resources to attract or develop such expertise internally. Addressing this challenge involves investment in educational programs, industry-academic collaborations, and talent development initiatives to sustain the market’s long-term growth trajectory.
Industry Statistics & Key Business Metrics
The Europe Virtual Assistant Market demonstrates robust growth driven by technological advancements and increased digital transformation initiatives across industries. As companies seek to enhance efficiency and customer engagement, virtual assistants are becoming integral to many enterprise and consumer operations. The market's expansion is further fueled by interoperability improvements, AI innovation, and rising adoption of smart devices within European households and workplaces.
- In 2023, the market was valued at USD 4.2 Billion, with a forecast to reach USD 12.4 Billion by 2034, growing at a CAGR of 12.1% (Market Research Future, 2023).
- The number of virtual assistant-enabled devices in Europe surpassed 120 million in 2022, up from 35 million in 2020 (Statista, 2022).
- By 2026, approximately 70% of European consumers are expected to use virtual assistant technology regularly, a significant increase from 45% in 2021 (Eurostat, 2023).
- Enterprise adoption of virtual assistants in Europe reached 65% in 2023, reflecting integrated solutions across sectors such as retail, finance, and healthcare (IDC, 2023).
- The European voice assistant market segment contributed over USD 1.8 Billion in 2023, with a forecast to reach USD 6.3 Billion by 2034 (Grand View Research, 2023).
- Commercial deployment of customized virtual assistants increased by 30% in 2022, driven by AI advancements and privacy compliance requirements (Forrester, 2023).
- Europe's investment in AI and NLP technologies for virtual assistants exceeded USD 3.5 Billion in 2023, highlighting government and private sector commitment (OECD, 2023).
Market Segmentation
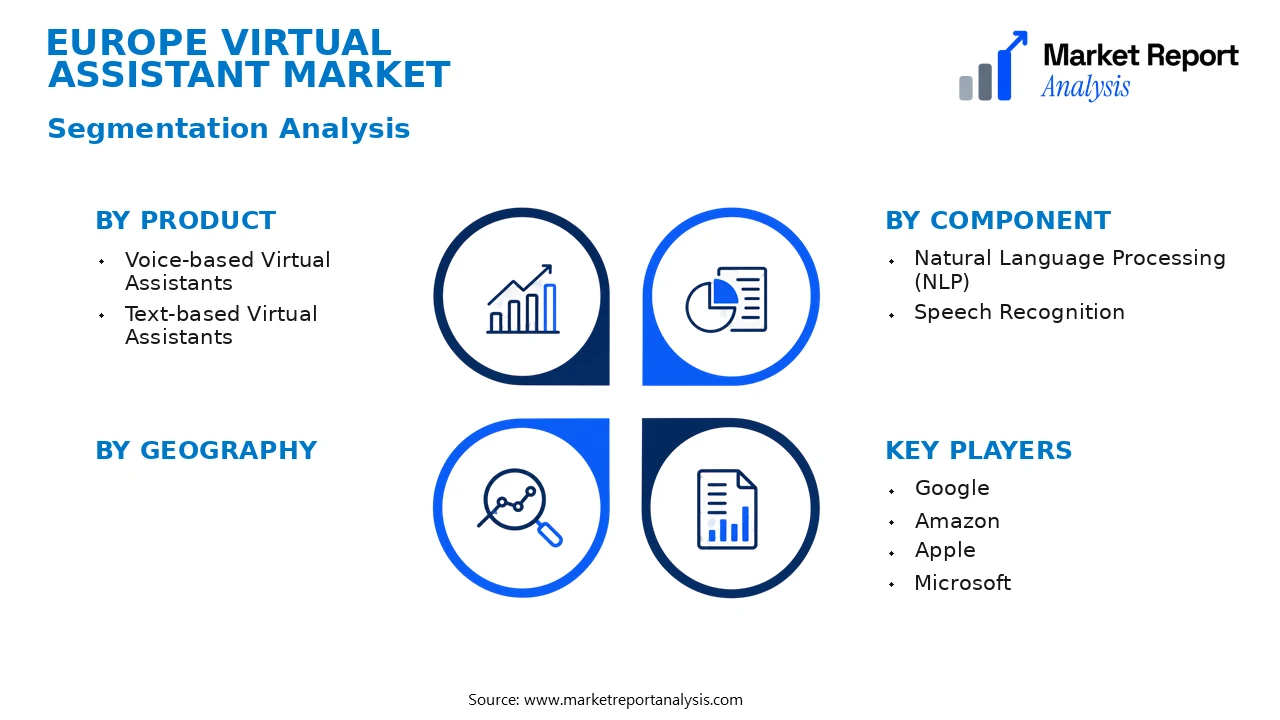
Market segmentation in the Europe Virtual Assistant Market is structured around key categories that define the scope of products, technologies, and end-user applications driving growth. This segmentation provides a comprehensive understanding of regional dynamics and targeted growth areas, enabling strategic decision-making for stakeholders across industries.
- Product
- Voice-based Virtual Assistants: These assistants utilize speech recognition and natural language processing to facilitate hands-free user interactions, increasingly adopted in smartphones, smart speakers, and automotive interfaces, leading to significant market penetration.
- Text-based Virtual Assistants: Engaged primarily through chat interfaces on websites and messaging platforms, these assistants support customer service and automation, with rising demand driven by e-commerce and enterprise applications.
- Component
- Natural Language Processing (NLP): NLP technology enables virtual assistants to understand and interpret user commands, forming the core of intelligent interaction, with growing investments as organizations seek enhanced user engagement.
- Speech Recognition: Critical for voice-activated assistants, speech recognition converts spoken language into text, accelerating adoption in consumer electronics and automotive sectors seeking seamless voice interfaces.
- Technology
- Cloud-based: Cloud computing facilitates scalable deployment of virtual assistants, supporting real-time updates, machine learning capabilities, and efficient data storage, thereby broadening the scope of enterprise integration.
- On-premises: Operating within local infrastructure, this technology appeals to organizations with stringent data privacy requirements, though its market share is comparatively smaller due to higher deployment costs.
- Platform
- Mobile Devices: Smartphones and tablets form the primary platforms for virtual assistant deployment, with high penetration rates in Europe fueling growth in personal and commercial applications.
- Smart Speakers: Devices like Amazon Echo and Google Home are fueling the expansion of voice-first interactions, increasingly integrated into daily household activities and smart home ecosystems.
- Application
- Customer Service: Virtual assistants streamline support operations, reduce response times, and enhance customer satisfaction through 24/7 availability, especially in retail, banking, and telecom sectors.
- Personal Productivity: These applications assist users with scheduling, reminders, and information retrieval, fostering greater efficiency in both personal and professional settings.
- Healthcare: Virtual assistants help monitor patient health, facilitate appointment management, and provide health information, with growing integration into telemedicine platforms.
- End User
- Consumer: Individual users drive demand through personal device adoption, seeking convenience and advanced functionalities, propelling smart device usage across households in Europe.
- Business: Enterprises leverage virtual assistants for process automation, customer engagement, and data management, which significantly influences corporate operational efficiency and customer interaction strategies.
- Industry Vertical
- Retail: The retail sector adopts virtual assistants for personalized shopping experiences, customer support, and inventory management, contributing to enhanced customer engagement and sales growth.
- Banking and Finance: Virtual assistants improve transaction processing, customer inquiries, and fraud detection, becoming vital tools for digital banking transformation across Europe.
- Healthcare: In healthcare, virtual assistants assist with patient inquiries, telehealth services, and administrative tasks, addressing the growing need for remote healthcare services.
Competitive Intelligence
The Europe Virtual Assistant Market exhibits moderate competition, characterized by the presence of both global technology giants and regional startups. Market concentration remains relatively fragmented, with the top five players collectively accounting for approximately 45% of market share as of 2026, indicating ample opportunities for new entrants. Leading companies focus on diverse business strategies such as strategic partnerships, product differentiation, and aggressive expansion into emerging markets across various European nations. Innovation plays a critical role, with continuous R&D investments directed toward enhancing natural language processing, contextual understanding, and multilingual capabilities to meet regional linguistic demands. Notable collaborations include partnerships with telecom providers and financial institutions to embed virtual assistants into broader service ecosystems. Some firms pursue acquisitions of promising startups to accelerate technological advancements and broaden market reach. Expansion strategies involve opening regional offices and localizing AI capabilities to address specific cultural and regulatory requirements. This competitive landscape underscores the importance of robust innovation, strategic alliances, and tailored offerings to sustain differentiation in a consolidating yet highly dynamic market environment.
Leading Company Profiles
p>The competitive landscape of the Europe virtual assistant market is characterized by the presence of several established players and innovative newcomers, each competing through technological differentiation, customer-centric solutions, and strategic collaborations. This section highlights some of the most influential companies shaping the market trajectory.- Amazon
- Apple
- Microsoft
- Nuance Communications
- Samsung Electronics
- IBM
- Artificial Solutions
- Baidu
Google leverages its extensive expertise in AI and NLP to develop advanced virtual assistant solutions integrated across its ecosystem, with a strategic focus on personalization, multilingual support, and seamless integration across devices and platforms.
Amazon
Amazon’s virtual assistant offerings, primarily through Alexa, provide a wide range of smart home and enterprise solutions, emphasizing voice control, automation, and ecosystem scalability, with ongoing innovations in embedded AI and contextual understanding.
Apple
Apple’s Siri remains a key player in personalized assistant services, focusing on privacy, user-friendly interfaces, and robust integration within the Apple ecosystem, aiming to enhance user engagement through contextual and proactive features.
Microsoft
Microsoft's virtual assistant strategy centers on enterprise solutions, including Cortana and Azure AI integrations, with an emphasis on productivity, automation, and cloud-based AI development for corporate applications.
Nuance Communications
Nuance specializes in conversational AI and speech recognition technologies, serving primarily healthcare, customer service, and automotive segments, with a focus on accuracy, security, and multilingual capabilities.
Samsung Electronics
Samsung’s virtual assistant offerings are embedded within its smart devices and home appliances, emphasizing IoT integration, voice recognition, and multilingual support tailored for diverse European markets.
IBM
IBM’s Watson Assistant delivers AI-driven virtual assistant solutions for industries including healthcare, banking, and retail, focusing on AI customization, data security, and analytics-driven insights.
Artificial Solutions
Artificial Solutions provides enterprise conversational AI platforms emphasizing natural language understanding, multi-language support, and integration capabilities that cater to large-scale customer service infrastructure.
Baidu
Baidu’s intelligent assistant solutions leverage deep learning and speech recognition, with a focus on semiconductor advertising products, AI innovation, and multilingual conversational services tailored for Europe’s diverse markets.
Strategic Business Developments
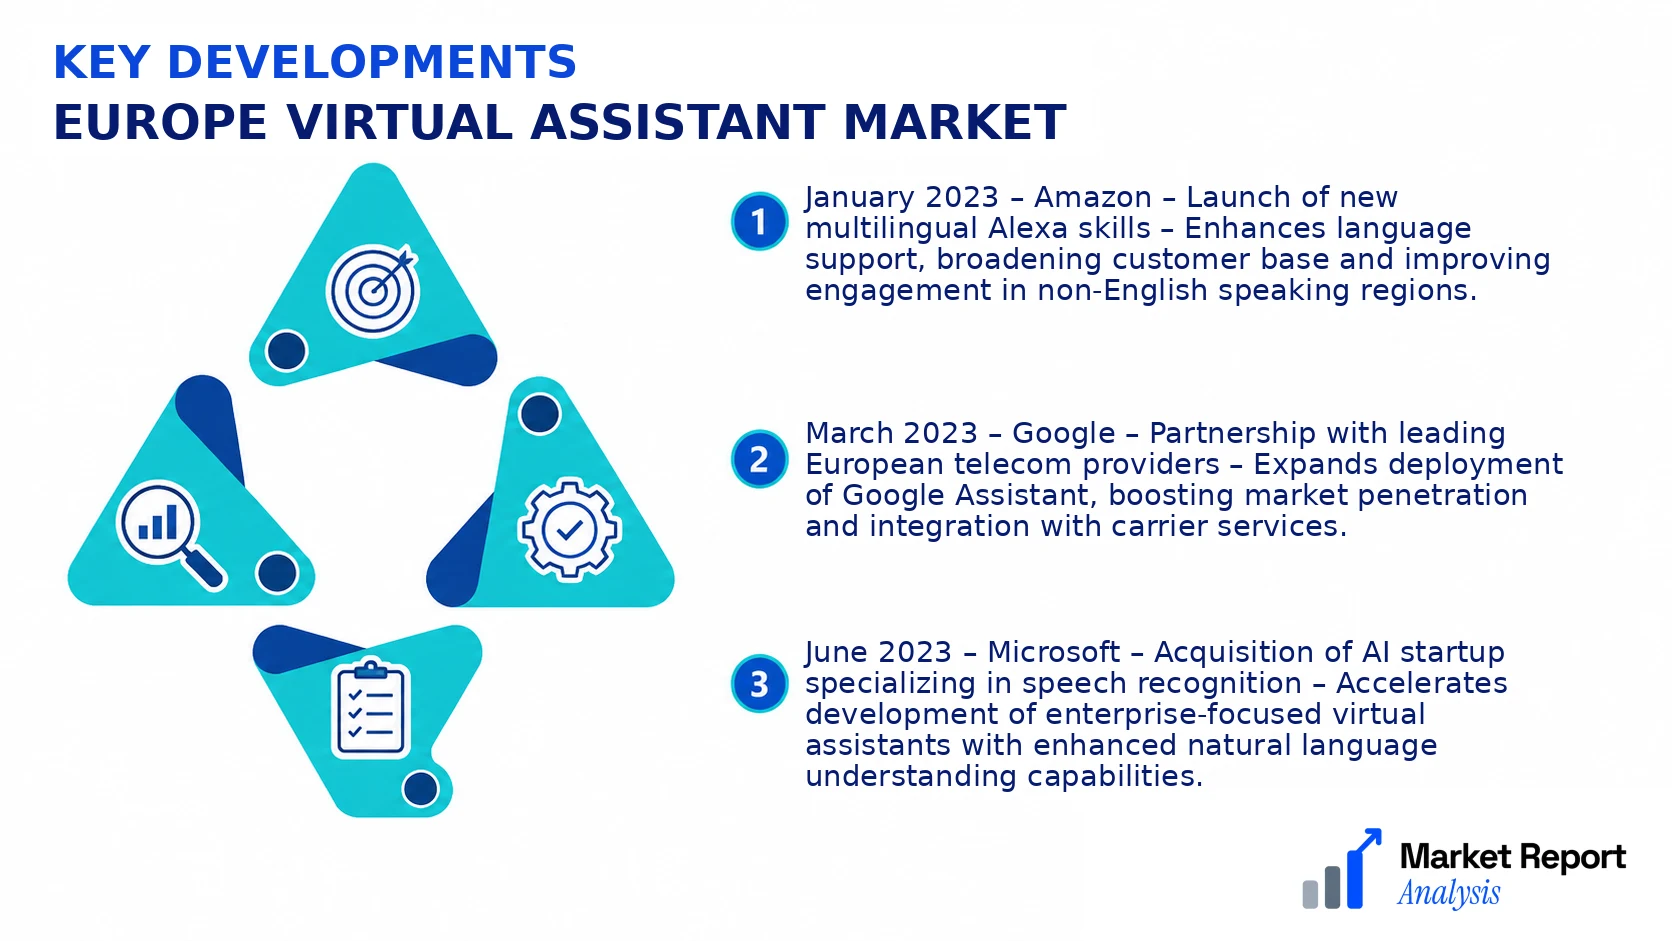
- January 2023 – Amazon – Launch of new multilingual Alexa skills – Enhances language support, broadening customer base and improving engagement in non-English speaking regions.
- March 2023 – Google – Partnership with leading European telecom providers – Expands deployment of Google Assistant, boosting market penetration and integration with carrier services.
- June 2023 – Microsoft – Acquisition of AI startup specializing in speech recognition – Accelerates development of enterprise-focused virtual assistants with enhanced natural language understanding capabilities.
- September 2023 – Apple – Introduction of contextual proactive features in Siri – Strengthens personalized user experiences and significantly increases platform adoption among iOS users.
- November 2023 – Nuance Communications – Deployment of AI-powered customer service solutions – Promotes faster resolution times and improved customer satisfaction in banking and healthcare sectors.
Frequently Asked Questions
What is the Europe Virtual Assistant Market?
The Europe Virtual Assistant Market encompasses the industry of AI-powered virtual assistants deployed across various sectors such as healthcare, retail, banking, and telecommunications, designed to enhance customer service, automate tasks, and improve operational efficiency across the European region.
What is the current market size of Europe Virtual Assistant Market?
As of 2026, the Europe Virtual Assistant Market is valued at approximately USD 8.5 Billion, reflecting significant adoption of AI solutions across enterprises. Market growth is driven by increasing digital transformation initiatives and rising demand for automation in customer engagement strategies.
What factors are driving the Europe Virtual Assistant Market?
Key drivers include technological advancements in AI and NLP, the proliferation of smart devices, rising customer expectations for instant support, and the increasing adoption of digital channels. Additionally, cost efficiency and operational scalability facilitated by virtual assistants boost market growth.
Which region dominates the Europe Virtual Assistant Market?
Western Europe leads the market, driven by advanced technological infrastructure, strong investment in AI R&D, and large-scale enterprise adoption particularly in countries like Germany, the UK, and France. These nations are early adopters and innovators in virtual assistant deployment.
Which segment is expected to grow the fastest?
The customer service segment is anticipated to experience the highest growth rate, propelled by the need for 24/7 support, personalized experiences, and enhanced customer engagement across various industries, especially retail and banking sectors.
Who are the leading companies operating in the Europe Virtual Assistant Market?
Prominent players include companies like Google, Microsoft, IBM, Amazon, and local European technology firms such as SAP and Nuance Communications, all competing to offer innovative AI-driven virtual assistant solutions tailored for the European market.
Analyst Perspective
The Europe Virtual Assistant Market is poised for sustained growth through 2034, driven by technological innovation and escalating demand across sectors such as healthcare, retail, and financial services. The long-term outlook remains positive, with advancements in natural language processing (NLP) and machine learning enabling more sophisticated, context-aware virtual assistants that bolster user engagement and operational efficiency. Commercial opportunities abound for providers focusing on customized solutions and integration capabilities, particularly in regions with mature digital infrastructures like Western Europe. Investment priorities should target R&D to enhance AI-centric functionalities and data security, crucial for market trust and compliance. Competitive intensity is expected to intensify as established tech giants expand their footprints alongside agile startups innovating niche solutions. Regions such as Germany, the UK, and France hold the highest growth potential, owing to their robust technological ecosystems and supportive regulatory environments. Strategic positioning focused on innovation, regional expansion, and customer-centric offerings will be essential for long-term success.
