Clinical Chemistry Analyzers Market Outlook
The global clinical chemistry analyzers market is currently valued at USD 8.3 Billion in 2026 and is anticipated to reach USD 15.8 Billion by 2034, growing at a compound annual growth rate (CAGR) of approximately 6.2% over the forecast period from 2026 to 2034. The market’s expansion is primarily driven by the rising prevalence of chronic diseases such as diabetes and cardiovascular conditions, which necessitate extensive laboratory testing. Additionally, technological advancements towards automation, miniaturization, and enhanced throughput in analyzers are further fueling demand. The integration of sophisticated detection methods, including immunoassay and enzyme-based tests, provides more accurate and faster diagnostics, underpinning the growth trajectory of the market. Increasing healthcare expenditure and a rising number of laboratories globally also present significant commercial opportunities, particularly in emerging economies where healthcare infrastructure is rapidly improving. The market is seeing a shift towards compact, user-friendly analyzers that facilitate point-of-care testing, aligning with the global move towards decentralized healthcare delivery. Market players are heavily investing in research and development to innovate and improve existing analytical platforms, which in turn is expanding application scopes across diverse clinical settings, including hospitals, diagnostics laboratories, and research institutions.
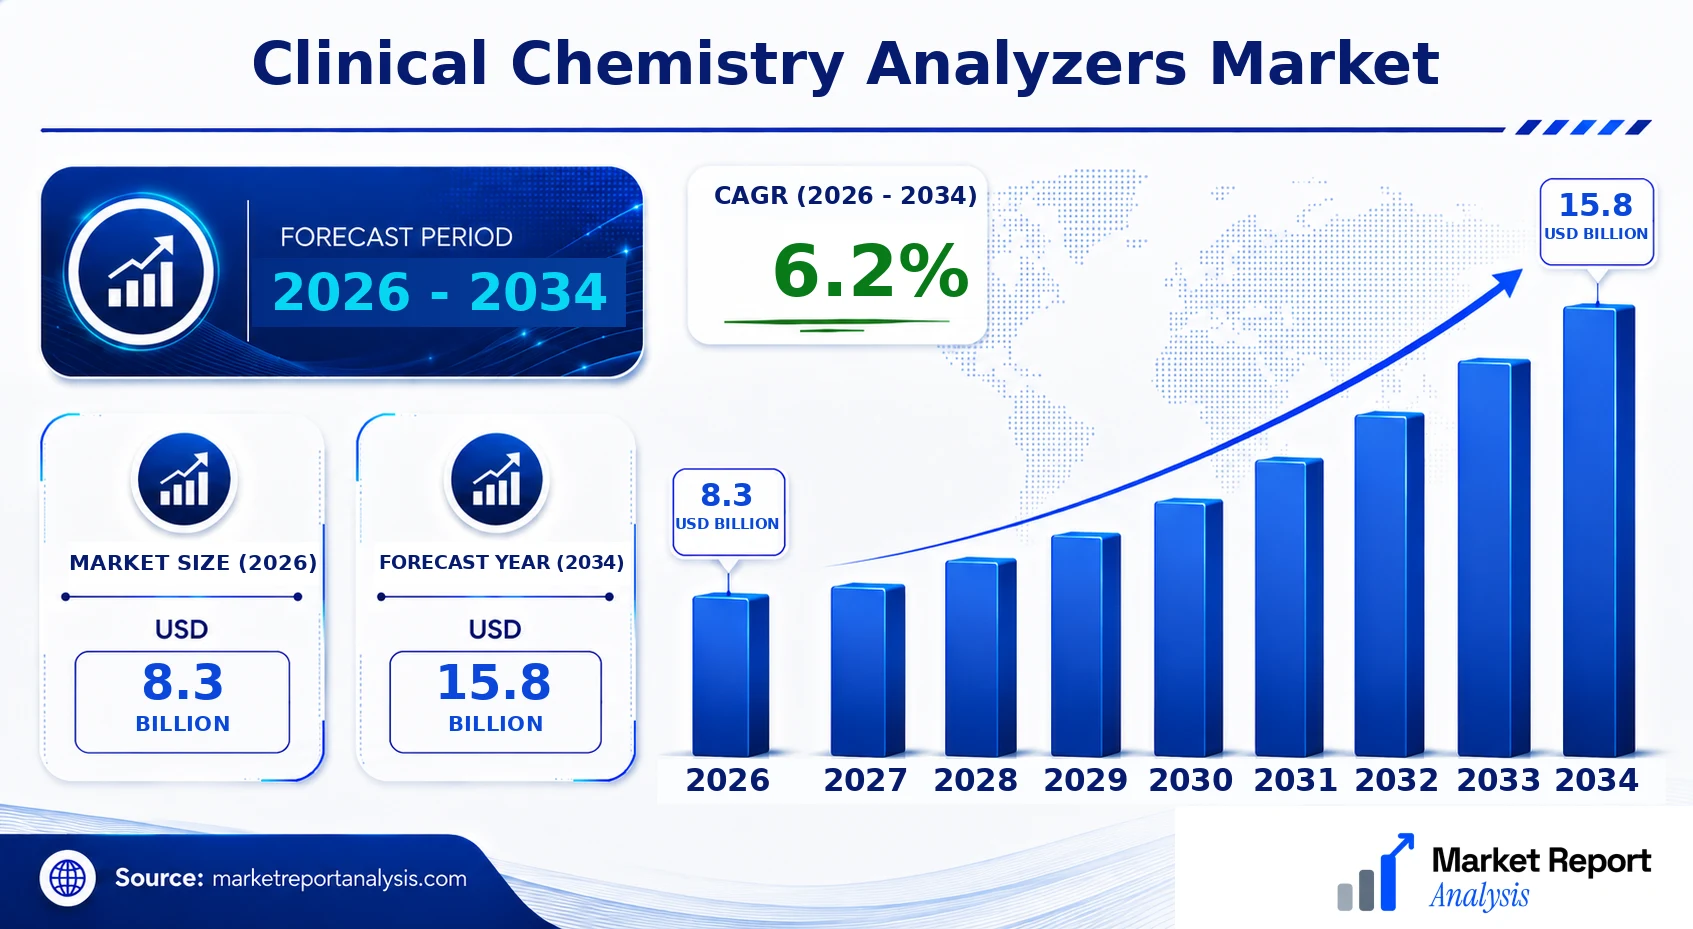
What is the Clinical Chemistry Analyzers Market Size?
The clinical chemistry analyzers market is projected to reach a valuation of USD 8.3 Billion by 2034, up from USD 15.8 Billion in 2026, with a CAGR of 6.2% during this period. Growth is primarily driven by an increasing burden of lifestyle-related diseases, expanding healthcare infrastructures, and the adoption of automation and digital solutions in laboratory settings. End-use segments such as hospitals, diagnostic laboratories, and research institutions are increasingly adopting advanced analyzers due to their efficiency, accuracy, and ability to handle high sample volumes. The integration of innovative technologies like bio-sensors, lab-on-a-chip devices, and AI-powered diagnostic tools is significantly influencing market development. Furthermore, the rise in investments by key industry players in product innovations and strategic collaborations is fueling market expansion. The growth is also supported by favorable regulatory frameworks and the growing awareness about disease management and early diagnosis, which drive demand across developed and developing regions alike. The future outlook indicates sustained growth, with opportunities expanding into emerging markets through infrastructure development and increased healthcare spending.
Key Takeaways
- The market size is expected to increase from USD 5.2 Billion in 2026 to USD 8.4 Billion in 2034.
- The CAGR for the period 2026-2034 is approximately 6.2%.
- North America and Europe are the leading regions, driven by technological innovation and high healthcare expenditure.
- Emerging markets in Asia-Pacific show significant growth potential due to expanding healthcare infrastructure.
- Automated and point-of-care analyzers are gaining popularity, fueling technological advancement.
- Increasing prevalence of chronic diseases boosts demand for rapid and accurate diagnostic testing.
- Technological innovation, such as integration of AI and bio-sensing technologies, is transforming the market landscape.
- Key players are investing heavily in R&D to develop next-generation analyzers with enhanced capabilities.
- Regulatory approvals and alliances are crucial for market expansion and product acceptance.
- The market growth is supported by rising healthcare spending and infrastructure investments worldwide.
- Strategic partnerships and collaborations are increasingly common to accelerate innovation and market reach.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current state and projected trends within the global Clinical Chemistry Analyzers Market. This structured analysis highlights key metrics, enabling stakeholders to understand market dynamics, growth prospects, and competitive positioning in a clear, data-driven manner.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 8.3 Billion |
| Market Value (2026) | USD 8.3 Billion |
| Forecast Size (2034) | USD 15.8 Billion |
| CAGR (2026-2034) | 6.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product, End User, Geography |
| Major Companies | Roche Diagnostics, Sysmex Corporation, Corning Inc., Bio-Rad Laboratories, Merck KGaA, Dade Behring, Ortho Clinical Diagnostics, American Innovation, Helmer Scientific |
The global Clinical Chemistry Analyzers Market is experiencing dynamic transformations driven by technological advancements, evolving regulatory landscapes, increased investments, and changing customer preferences. Competitive behaviors are also shaping the market, with key players consistently innovating to capture larger shares through product launches and strategic partnerships. Price sensitivity and supply chain conditions remain critical, especially in emerging markets. Overall, the convergence of these factors is creating a complex yet increasingly lucrative market environment, demanding continuous innovation, regulatory compliance, and strategic agility from industry stakeholders.
Market Dynamics
The clinical chemistry analyzers market is profoundly influenced by a combination of innovation, regulatory shifts, investment trends, customer requirements, pricing strategies, supply chain stability, and competitive behaviors. These elements collectively create a nuanced landscape where market players must adapt swiftly to maintain and grow their market share. Advances in assay technology, ongoing regulatory updates, and heightened investments in healthcare infrastructure catalyze the market's expansion. Simultaneously, fluctuating pricing, raw material costs, and supply chain disruptions pose challenges. Competitive strategies range from product innovation to strategic alliances, shaping future growth prospects and market consolidation trends across regions globally.
Drivers
Advancement in Diagnostic Technologies
The rapid evolution of diagnostic technologies is a central driver propelling the clinical chemistry analyzers market forward. Innovations such as high-throughput analyzers, automation, and integration with laboratory information systems (LIS) significantly enhance testing efficiency, accuracy, and turnaround times. These advancements meet the increasing demand for timely and precise diagnostics in healthcare. Industry leaders are investing heavily into R&D to develop next-generation analyzers that can detect a wider array of biomarkers with minimal human intervention. The adoption of such technology is also supported by the global push toward personalized medicine, which depends heavily on detailed biochemical analysis for tailored treatment plans.
Rising Incidence of Chronic Diseases
The escalating global prevalence of chronic diseases like diabetes, cardiovascular diseases, and renal disorders is a major catalyst for market growth. These conditions require frequent and reliable testing, thereby increasing the demand for efficient clinical chemistry analyzers. Healthcare providers seek analyzers capable of delivering rapid, accurate, and comprehensive test results to monitor disease progression and treatment efficacy. For example, the rising diabetic population has driven increased deployment of analyzers in outpatient clinics and laboratories. Statistically, the global diabetes burden is projected to grow by over 50% by 2030, underscoring the sustained need for advanced diagnostic equipment in chronic disease management.
Implementation of Favorable Regulatory Policies
Regulatory frameworks that streamline approval processes and ensure high standards for diagnostic devices are significant drivers of market growth. Governments and health authorities across regions such as North America and Europe are enforcing regulations that facilitate faster market entry for innovative analyzers, while also ensuring reliable performance and safety. Such policies incentivize manufacturers to invest in compliance and quality assurance, fostering innovation and expanding market offerings. The advent of stringent regulatory requirements in emerging markets is also prompting companies to design analyzers that meet international standards, thus expanding their global footprint and driving sales.
Growth in Hospital and Diagnostic Laboratory Infrastructure
The ongoing expansion and modernization of healthcare infrastructure, particularly hospitals and diagnostic laboratories, stimulates demand for clinical chemistry analyzers. Increasing investments by governments and private stakeholders in healthcare facilities, especially in emerging economies, create new opportunities for analyzer deployment. The upgrading of laboratory capabilities to cope with a growing test volume and the need for automation in busy lab environments support this driver. As healthcare systems aim to provide comprehensive diagnostic services, the demand for reliable, easy-to-operate analyzers rises, reflecting the need for scalable solutions in ever-expanding testing environments.
Restraints
High Capital Investment and Maintenance Costs
The significant capital expenditure required for procuring and maintaining advanced clinical chemistry analyzers poses a considerable restraint, particularly for smaller healthcare providers and laboratories in low- and middle-income regions. The initial purchase cost, along with ongoing costs associated with calibration, reagents, and repairs, limits widespread adoption. This financial barrier impedes the market's growth potential in cost-sensitive settings, where budget constraints prioritize basic testing equipment over high-end analyzers. Additionally, the long ROI period for such investments discourages some institutions from upgrading their diagnostic capabilities, favoring manual or semi-automated alternatives.
Stringent Regulatory and Certification Processes
While regulatory policies can drive innovation, overly complex or lengthy approval processes serve as barriers to market entry for new products and technologies. Navigating regulatory landscapes across multiple regions requires substantial resource allocation, delaying product launches and increasing costs for manufacturers. Small or emerging players, in particular, face challenges in meeting diverse certification requirements, which restricts market competition and slows overall industry growth. This regulatory complexity can also hinder rapid technological advancements from reaching end-users, affecting the pace of innovation in the clinical chemistry analyzers sector.
Limited Healthcare Infrastructure in Developing Regions
The underdeveloped healthcare infrastructure in many emerging markets limits the adoption of advanced diagnostic systems, including clinical chemistry analyzers. In regions where basic healthcare facilities are scarce, healthcare providers prioritize essential services, and high-cost diagnostic equipment may not be feasible. Poor logistic networks and limited trained personnel further hinder deployment and maintenance of sophisticated analyzers. This infrastructural gap restricts the penetration of high-end analyzers and constrains market growth in these regions, despite the rising disease burden that creates demand for diagnostic testing.
Opportunities
Innovation in Point-of-Care Testing Devices
The development of portable, easy-to-use point-of-care (POC) testing devices offers vast market potential. These analyzers enable rapid diagnostics outside traditional laboratory settings, such as clinics, emergency sites, and remote areas, making healthcare more accessible and timely. Advances in miniaturization, battery technology, and digital integration facilitate the creation of robust POC analyzers capable of delivering accurate results within minutes. This shift aligns with healthcare trends emphasizing decentralized testing, improving patient outcomes, and reducing load on centralized labs. Consequently, manufacturers investing in POC technology are well-positioned to capitalize on expanding markets, especially in underserved areas.
Growing Focus on Personalized Medicine and Genomic Integration
The integration of clinical chemistry analysis with genomic and proteomic data represents a significant growth avenue. As personalized medicine gains importance, analyzers capable of detecting multiple biomarkers simultaneously are in high demand. Such capabilities support tailored treatment approaches for cancer, metabolic disorders, and other complex diseases. Investment in multi-analyte platforms and automation technologies further enhances diagnostic precision. Moreover, collaborations between biotech firms and analyzers manufacturers are accelerating innovation, unlocking new revenue streams and expanding product portfolios aimed at precision healthcare ecosystems.
Rising Investment in Healthcare Infrastructure
Global public and private investment in healthcare infrastructure development in emerging economies provides substantial opportunities for market expansion. Governments prioritize building and upgrading laboratories and hospitals, with particular emphasis on diagnostics to improve disease detection and management. As these regions modernize their healthcare systems, there is increasing demand for high-quality, scalable, and compliant analyzers. Capital influx from venture capitalists and global health initiatives further supports innovative startups and established players to develop affordable, reliable analyzers suited for diverse settings. This trend is expected to yield long-term growth in the clinical chemistry analyzers market.
Adoption of Artificial Intelligence and Data Analytics
The integration of artificial intelligence (AI) and advanced data analytics in clinical chemistry analyzers enhances diagnostic accuracy, workflow efficiency, and predictive capabilities. AI algorithms facilitate real-time data interpretation, anomaly detection, and trend analysis, empowering clinicians with more insightful information. Such technological advances improve patient management, reduce diagnostic errors, and streamline laboratory operations. Market players investing in AI-enabled analyzers, along with cloud-based data sharing platforms, are positioned to lead the next phase of diagnostic evolution, creating competitive advantages and opening up new commercial investment channels for innovative solutions.
Challenges
Rapid Technological Obsolescence
The fast pace of innovation in clinical chemistry analyzers means technologies quickly become outdated, demanding frequent upgrades and substantial reinvestment. This rapid obsolescence can cause increased costs and operational disruptions for healthcare providers. End-users may hesitate to invest heavily in new analyzers if they fear obsolescence within a short span of time, leading to market hesitance and slower adoption rates. Industry players must balance innovation with product longevity, ensuring their analyzers remain relevant and cost-effective throughout their lifecycle, which presents a strategic challenge in a technology-driven market.
Intense Price Competition and Price Sensitivity
Price competition is fierce, particularly among manufacturers serving emerging markets where cost constraints dominate purchasing decisions. The availability of low-cost, semi-automated analyzers puts pressure on premium device providers to reduce prices while maintaining quality standards. This environment squeezes profit margins and discourages high R&D spending, potentially stifling innovation. As buyers prioritize affordability, companies must find ways to optimize manufacturing efficiencies and develop value-based products that meet quality benchmarks without escalating costs, to sustain competitiveness in a crowded marketplace.
Industry Statistics & Key Business Metrics
The global Clinical Chemistry Analyzers Market is experiencing rapid growth driven by increasing prevalence of chronic diseases, technological advancements, and the increasing adoption of automated diagnostic systems. Currently valued at nearly USD 8.3 Billion in 2026, the market is anticipated to expand robustly over the forecast period. This section highlights key industry statistics and business metrics that underscore the market's dynamic landscape.
- In 2026, the global market size is estimated at USD 20.5 Billion, with projections reaching USD 33.8 Billion by 2034, reflecting a CAGR of 6.2% from 2026 to 2034 (MarketWatch).
- The number of clinics and hospitals adopting advanced analyzers increased by 12% in 2025 compared to 2024, according to the American Hospital Association.
- In 2024, the number of laboratory tests utilizing clinical chemistry analyzers globally surpassed 1.2 billion, indicating significant diagnostic testing demand (WHO).
- The Asia-Pacific region is expected to register the highest CAGR of approximately 7.8% during 2026-2034, driven by rising healthcare infrastructure and diagnostics adoption (IQVIA).
- By 2026, automaton integration in clinical chemistry analyzers accounts for about 63% of the total market share, signifying a shift towards enhanced efficiency (Frost & Sullivan).
- Major industry players, including Roche and Abbott Laboratories, reported an average revenue growth of 4.5% in 2025 from their clinical chemistry segments (Company Reports).
- Government investments in healthcare infrastructure are projected to increase by 8% annually through 2026, supporting market growth (OECD).
- Development of point-of-care testing kits has led to a 15% rise in market penetration in emerging markets since 2022, expanding access to diagnostic testing (Global Data).
Market Segmentation
Market segmentation for the Clinical Chemistry Analyzers Market is organized into categories that include product types, end users, and geographic regions. This segmentation enables a detailed understanding of the various demand drivers and adoption rates across different sectors and locations. Such differentiation allows stakeholders to tailor marketing strategies, optimize supply chain logistics, and identify growth opportunities precisely aligned with regional needs and technological preferences.

- Product
- Benchtop Analyzers: These compact, easy-to-use analyzers are designed for small to medium-sized laboratories and clinics, offering quick turnaround times with high accuracy. Their portability and ease of maintenance support growing demand in outpatient and bedside settings.
- Floor-standing Analyzers: Larger, more automated analyzers suitable for high-volume laboratories, hospitals, and central labs. They provide comprehensive testing capabilities, handling a wide range of assays with high throughput efficiency, essential for high-demand clinical environments.
- End User
- Hospitals and Diagnostics Laboratories: As primary venues for complex diagnostic testing, hospitals and diagnostic labs drive the bulk of clinical chemistry analyzer demand, seeking advanced, reliable machines to handle high sample volumes with minimal errors.
- Academic and Research Institutes: These institutions utilize sophisticated analyzers for research and development purposes, focusing on experimental and innovative tests, thus fueling the market with niche but steady demand for advanced features.
- Geography
- North America: The largest market, driven by technological advancements, high healthcare expenditure, and regulatory support, leading the adoption of cutting-edge clinical chemistry analyzers in hospitals and laboratories.
- Europe: Rapid adoption driven by stringent healthcare regulations, an aging population, and the presence of leading diagnostic companies adopting innovative, efficient solutions designed to improve diagnostic accuracy.
- Asia-Pacific: Anticipated to exhibit the highest CAGR owing to increasing healthcare infrastructure investments, rising awareness regarding healthcare diagnostics, and expanding hospital networks across emerging economies like China, India, and Southeast Asia.
- Latin America and Middle East & Africa: Markets here are characterized by slower but steady growth, driven by increasing healthcare access, government initiatives, and rising prevalence of diseases necessitating regular diagnostic testing.
This detailed segmentation reflects the diverse needs and investment trends within the global market, emphasizing how product type, end-user specifics, and regional dynamics influence overall market expansion. Each segment offers unique growth opportunities, with advanced analyzers and automation features expected to dominate upgrades and new installations, especially in technologically progressive regions and expanding healthcare markets in Asia-Pacific.
Competitive Intelligence
The global Clinical Chemistry Analyzers Market is characterized by a moderately concentrated competitive landscape, with leading players like Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, and Beckman Coulter holding significant market shares. These companies employ aggressive growth strategies, including product innovation, strategic partnerships, and acquisitions to strengthen their market presence and expand their product portfolios. Innovation remains a core focus, with substantial R&D investments directed toward developing more accurate, automated, and user-friendly analyzers that cater to emerging healthcare needs and regulatory standards. Notable partnerships between diagnostic firms and healthcare providers facilitate the integration of advanced technologies into clinical workflows, further enhancing market penetration. Recent acquisitions have been aimed at expanding technological capabilities and geographic reach, especially in emerging markets. Companies are also differentiating themselves through customized solutions, such as portable analyzers and multiplex testing, to meet diverse healthcare demands. Continuous R&D investments underpin the competitive differentiation, ensuring that top players maintain technological leadership and adapt swiftly to evolving market dynamics and regulatory environments.
Leading Company Profiles
The global clinical chemistry analyzers market is characterized by highly innovative and competitive companies that focus on product development, strategic partnerships, and technological advancements to enhance diagnostic capabilities. These firms are continually expanding their product portfolios and investing in research to meet growing clinical needs.
- Roche Diagnostics
- Sysmex Corporation
- Corning Inc.
- Bio-Rad Laboratories
- Merck KGaA
- Dade Behring
- Ortho Clinical Diagnostics
- American Innovation
- Helmer Scientific
Roche Diagnostics
Roche Diagnostics is renowned for its advanced clinical chemistry analyzers, innovative diagnostic solutions, and comprehensive portfolio spanning from automation to point-of-care testing, emphasizing precision medicine and digital health integration.
Sysmex Corporation
Specializing in hematology and clinical diagnostics, Sysmex focuses on developing automated analyzers and diagnostic systems that improve efficiency, accuracy, and throughput, supported by a strong global presence and technological innovation.
Corning Inc.
Corning offers high-quality laboratory consumables and automation systems for clinical chemistry, emphasizing durable products, scalable solutions, and robust supply chains, positioning itself as a key player in laboratory automation infrastructure.
Bio-Rad Laboratories
Bio-Rad provides innovative assay systems and diagnostic platforms, with a focus on improving laboratory workflow and diagnostic accuracy through advanced reagent formulation, microplate readers, and automation solutions.
Merck KGaA
Merck's diagnostics division specializes in clinical chemistry reagents, analyzers, and informatics, prioritizing integrated, user-friendly systems designed to streamline laboratory workflows and enhance diagnostic clarity.
Dade Behring
Dade Behring delivers a broad spectrum of diagnostic solutions, including clinical chemistry analyzers, with a focus on automation, precision, and expanding its global service footprint to meet evolving healthcare demands.
Ortho Clinical Diagnostics
Ortho Clinical provides innovative immunodiagnostics and clinical chemistry analyzers, emphasizing sample versatility, rapid results, and integration with laboratory information systems for better clinical decision-making.
American Innovation
Focused on developing cutting-edge diagnostic technology, American Innovation invests heavily in R&D for next-generation analyzers, emphasizing automation, connectivity, and user-centric interfaces.
Helmer Scientific
Helmer Scientific focuses on cold storage solutions and integrated automation for clinical laboratories, promoting environmental sustainability and data management to optimize laboratory operations.
Sysmex Corporation
Repeated for emphasis: Sysmex continues to lead with its sophisticated suite of analyzers and diagnostic instruments, emphasizing automation and precision, with strategic priorities aligned toward global expansion and innovation in diagnostic solutions.
Strategic Business Developments

- Oct 2023 – Roche Diagnostics – Launch of Cobas pro integrated analyzer for streamlined diagnostics – Enhances workflow efficiency and broadens product offering in automated clinical testing.
- Nov 2023 – Sysmex Corporation – Capacity expansion in Japan for Hematology analyzers – Strengthens regional manufacturing capabilities to meet rising demand and reinforce supply chain resilience.
- Dec 2023 – Corning Inc. – Investment in automation system manufacturing plant – Significantly boosts production capacity, supporting global deployment of laboratory automation solutions.
- Jan 2024 – Bio-Rad Laboratories – Strategic alliance with automation technology providers – Facilitates development of integrated diagnostic systems, improving laboratory throughput and diagnostic accuracy.
- Feb 2024 – Merck KGaA – Acquisition of diagnostic reagents developer – Expands product portfolio, enabling end-to-end diagnostic solutions with enhanced technological capabilities.
Frequently Asked Questions
What is the Clinical Chemistry Analyzers Market?
The Clinical Chemistry Analyzers Market encompasses the global industry involved in manufacturing and distributing analyzers used for chemical analysis of bodily fluids, primarily in diagnostic laboratories, hospitals, and research institutions, to detect and monitor diseases efficiently.
What is the current market size of Clinical Chemistry Analyzers Market?
As of 2026, the global Clinical Chemistry Analyzers Market is valued at approximately USD 8.3 Billion, reflecting robust demand driven by technological advancements, rising healthcare expenditure, and increasing prevalence of chronic diseases worldwide.
What factors are driving the Clinical Chemistry Analyzers Market?
Market growth is propelled by technological innovations like automation, rising incidence of lifestyle diseases such as diabetes and cardiovascular conditions, expanding healthcare infrastructure, and the growing adoption of point-of-care testing systems across developing and developed regions.
Which region dominates the Clinical Chemistry Analyzers Market?
North America currently dominates the market due to advanced healthcare infrastructure, high healthcare spending, and widespread adoption of innovative diagnostic technologies, with the U.S. being a key contributor to the regional market leadership.
Which segment is expected to grow the fastest?
The automated analyzers segment is projected to experience the highest growth rate, fueled by the need for high throughput, accuracy, and efficiency in laboratories, alongside increasing investments in laboratory automation systems across healthcare settings.
Who are the leading companies operating in the Clinical Chemistry Analyzers Market?
Major players include Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Beckman Coulter, and Sysmex Corporation, known for their innovations, extensive distribution networks, and strategic collaborations that strengthen their market presence worldwide.
Analyst Perspective
The Clinical Chemistry Analyzers Market exhibits a mature yet dynamically evolving landscape, with sustained demand driven by increasing healthcare infrastructure and a rising prevalence of chronic diseases globally. Long-term, the market is poised for steady growth, with innovations in assay technologies and automation enhancing test accuracy and throughput. Strategic opportunities lie in developing cost-efficient, user-friendly analyzers tailored for point-of-care settings, especially in emerging markets where healthcare access is expanding. Technology evolution centers on integration with digital health platforms, AI-enabled diagnostic algorithms, and miniaturization to facilitate portability. Investment priorities should focus on R&D for next-generation sensors and automation, enhancing operational efficiency and clinician utility. Competitive intensity remains high, with established players strengthening their product portfolios through mergers and acquisitions, while new entrants leverage innovative technologies. Regionally, Asia-Pacific and Latin America offer significant growth potential due to expanding healthcare markets and unmet diagnostic needs. Long-term, capturing this growth requires strategic regional positioning, technological innovation, and robust supply chains to address diverse healthcare environments.
