Saudi Arabia Shredder Market Outlook
The Saudi Arabia Shredder Market is currently experiencing robust growth, driven by an increasing emphasis on sustainable waste management and regulatory reforms promoting recycling initiatives. As of 2026, the market is valued at approximately USD 2.5 Billion, with projections indicating a rise to USD 4.8 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of around 8.2% over the forecast period from 2026 to 2034. This expansion is primarily fueled by rising urbanization, government policies aimed at reducing landfilling, and the surge in industrial and construction activities requiring efficient material processing. Technological advancements in shredder equipment, including automation and energy-efficient models, are further bolstering market potential. Opportunities abound for local and international companies to innovate and strengthen partnerships within the country's developing waste processing and recycling infrastructure.

What is the Saudi Arabia Shredder Market Size?
By 2026, the Saudi Arabia shredder market is projected to reach a value of approximately USD 2.5 Billion, with expectations of growth to USD 4.8 Billion by 2034. This significant increase reflects a compounded annual growth rate of about 9.3% within this period. Key growth drivers include stringent government recycling mandates, increasing investments in waste management infrastructure, and rising adoption of advanced shredding technologies across various industries, including construction, manufacturing, and waste disposal. The expanding construction sector particularly contributes to the burgeoning demand for efficient material processing solutions. Moreover, the government’s Vision 2030 initiative emphasizes sustainable development practices, propelling investment into eco-friendly technologies. As urban areas like Riyadh and Jeddah continue to grow, there is a marked increase in waste volume, which necessitates high-capacity shredding equipment to meet environmental standards. Future opportunities lie in upgrading existing facilities with smarter, more energy-efficient shredders and expanding the role of resource recovery. The market’s growth outlook is supported by an increasing shift towards Circular Economy practices, positioning Saudi Arabia as a key player in waste-to-resource conversion within the region.
Key Takeaways
- Market size was approximately USD 1.2 Billion in 2026.
- It is forecasted to reach about USD 2.35 Billion by 2034.
- The CAGR during 2026-2034 is roughly 9.3%.
- Leading Saudi City: Riyadh.
- Fastest-Growing Saudi City: Dammam.
- Largest segment by technology: Mobile shredders.
- Fastest-growing segment: Automated shredding systems.
- Largest application: Construction and demolition waste processing.
- Fastest growing application: Electronic waste recycling.
- Largest end-user: Municipal waste management authorities.
- Forecast period: 2026-2034.
- Base year: 2026.
Industry Performance Dashboard
The Saudi Arabia Shredder Market has experienced significant growth driven by government initiatives promoting recycling and waste management across urban centers. The market's performance reflects increasing investments in infrastructure, technological upgrades, and a rising demand for efficient waste processing solutions. The following dashboard provides a quantitative assessment of key indicators shaping the industry landscape in Saudi Arabia.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 2.5 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR (2026-2034) | 8.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Saudi City | Riyadh |
| Fastest-Growing Saudi City | Dammam. |
| Segments Covered | Product Type, Application, Geography |
| Major Companies |
Market Dynamics
The Saudi Arabia Shredder Market is undergoing significant transformation driven by dynamic factors such as technological Advancement, evolving Regulatory Frameworks, increased Investment Infrastructures, shifting Customer Requirements, fluctuating Pricing Strategies, Supply Chain Conditions, and Competitive Behavior. These elements collectively influence market growth, investment attractiveness, and innovation potential, shaping the trajectory of shredder technology adoption and deployment across the nation. As Saudi Arabia aims to diversify its economy away from oil dependence, the adoption of advanced shredding solutions has become critical for sustainable waste management, resource recovery, and supporting the burgeoning recycling industry amidst escalating environmental standards and economic reforms.
Drivers
Rapid Urbanization and Industrialization
Saudi Arabia's swift urban growth and industrial expansion are principal drivers fueling the demand for advanced shredding solutions. With the rise of mega-cities like Riyadh and Jeddah, construction, automotive, and manufacturing sectors seek efficient waste processing systems to comply with environmental regulations. The government's Vision 2030 initiative promotes sustainable urban environments, emphasizing waste reuse and recycling, which directly elevates the need for robust shredders. Market data indicates a double-digit annual growth rate in industrial waste volumes, prompting increased procurement of shredders to handle diverse waste streams efficiently.
Stringent Environmental Regulations
Saudi Arabia’s increasingly stringent waste management regulations have been pivotal in pushing industry stakeholders towards adopting shredders. Regulatory bodies mandate waste sorting, recycling, and material recovery, which necessitate advanced shredding techniques to process various waste types, including plastics, metals, and e-waste. The Saudi Standards, Metrology and Quality Organization (SASO) sets compliance standards that incentivize technological upgrades. This political and regulatory push aligns with the country’s environmental sustainability goals, acting as a catalyst for market growth as companies invest in compliant shredding technology to avoid penalties and improve their environmental footprint.
Growing Investment in Waste Management Infrastructure
Public and private sector investments are significantly impacting the shredder market by expanding waste management infrastructure across Saudi Arabia. Major projects such as the Riyadh Waste-to-Energy plant and new recycling centers increasingly incorporate shredder systems to optimize material recovery and energy efficiency. These investments signal a long-term commitment to environmentally sustainable practices and indicate an upward trajectory in market value. As international firms enter the Saudi waste management space, they bring advanced shredding technologies, further catalyzing the industry’s evolution.
Emergence of Circular Economy Models
The shift towards a circular economy in Saudi Arabia promotes recycling and reuse of materials, directly driving demand for shredders that facilitate these processes. Policies encouraging resource efficiency and waste minimization bolster the adoption of shredding technology in sectors such as construction, automotive, and consumer goods. Companies are increasingly recognizing the financial and environmental benefits of recycling, leading to improved market dynamics. The government’s strategic initiatives, such as the National Industrial Development and Logistics Program, further reinforce this trend, creating a fertile environment for shredder technology providers.
Restraints
High Initial Capital Investment
The initial procurement and installation costs for advanced shredders represent a major restraint for Saudi Arabia’s market players. Many enterprises, particularly small and medium-sized companies, face budget constraints that hinder their ability to adopt new technologies. This high capital requirement affects industries such as retail, construction, and manufacturing, which may prioritize other operational expenditures over upgrading shredding capabilities. Consequently, the market experiences slower penetration rates among these segments, despite long-term operational savings and environmental benefits associated with shredder adoption.
Lack of Skilled Workforce
The absence of sufficiently trained personnel to operate and maintain shredding equipment remains a significant obstacle. Saudi Arabia’s technical labor market struggles to meet the specialized demands of advanced shredder systems, which necessitate specific operational expertise. This skills gap results in higher operational costs and potential downtime, discouraging some companies from upgrading their existing facilities. Industry stakeholders have initiated training programs, but broader capacity building remains a challenge, especially in rural or less developed areas.
Market Fragmentation and Competition
The presence of numerous local and international players introduces a degree of fragmentation, influencing market dynamics. Fragmentation may lead to price competition and inconsistent service quality, complicating strategic planning for end-users. Companies often face difficulties choosing reliable shredding solutions amidst the growing number of suppliers, which could affect the market's overall stability. Greater consolidation or collaborative frameworks could be necessary to establish clear standards and foster sustainable industry growth.
Opportunities
Growing Industry and Recycling Sector
The expansion of the industrial and recycling sectors in Saudi Arabia represents considerable opportunities for shredder market growth. As industries like construction, automotive, and electronics produce increasing waste streams, the demand for industrial shredders to facilitate resource recovery and waste reduction grows correspondingly. The government’s support for recycling initiatives, including the development of waste collection and processing plants, creates a lucrative environment for shredder suppliers. The potential for integrating shredders into future waste management infrastructure is substantial, particularly as the country aims for more sustainable industrial practices.
Investment in Innovation and Smart Technologies
Emerging technologies such as automation, AI, and IoT integration offer promising avenues for the Saudi shredder market. Companies investing in smart shredding units that feature remote monitoring, predictive maintenance, and energy-efficient operations can gain competitive advantages. These innovations improve operational efficiency, decrease downtime, and reduce energy consumption, aligning with Saudi Arabia’s goals for technological modernization. The government’s increasing emphasis on digital transformation and innovation ecosystems bolsters funding opportunities, enabling startups and established firms to develop next-generation shredding solutions.
Startup Ecosystem and Collaborative Initiatives
The rising startup ecosystem focused on environmental tech and circular economy solutions provides a fertile ground for new shredding technologies. Collaborative programs between industry players, government agencies, and educational institutions encourage pilot projects and technology demonstrations. Additionally, initiatives like innovation hubs and accelerators are fostering entrepreneurship, with several local startups developing niche shredding and waste processing innovations. These ecosystem developments increase market dynamism and generate new commercial opportunities for shredding equipment suppliers.
Future Commercial Investment Potential
As Saudi Arabia earmarks substantial funds toward environmental and industrial infrastructure development under Vision 2030, the signal for future commercial investment in shredders is strong. Large-scale public-private partnership projects focusing on waste-to-energy, recycling, and resource recovery will require advanced shredding systems. The long-term investment horizon, coupled with favorable government policies and incentives, is expected to catalyze substantial market growth, attract international investment, and foster local manufacturing capabilities for shredders, thus positioning Saudi Arabia as a regional hub for waste processing technology.
Challenges
Technological and Supply Chain Limitations
Despite the market's growth potential, technological limitations and supply chain disruptions pose ongoing challenges. Dependence on imported machinery and components exposes the industry to international logistics, tariff, and customs volatility. The rapid pace of technological change requires continuous updates and upgrades, which may be delayed due to supply chain constraints. These issues impact lead times, operational reliability, and cost structures, requiring local manufacturers to develop robust sourcing strategies and adapt to evolving technologies to ensure sustained growth.
Market Fragmentation and Regulatory Uncertainties
Market fragmentation, with diverse stakeholders and varying regional regulations, complicates standardization and uniform adoption of shredder technologies. Regulatory uncertainties, including potential revisions to waste disposal and recycling policies, can influence investment decisions and operational planning. The inconsistent regulatory environment may hinder large-scale adoption of shredding technology, creating a need for clear policy frameworks and industry harmonization, which are essential to overcoming market hesitation and promoting sustainable industry scaling.
Industry Statistics & Key Business Metrics
The Saudi Arabia Shredder Market exhibits significant growth potential driven by rising waste management needs and expanding industrial sectors. The following key statistics highlight the current landscape and future prospects within the country’s shredding industry, underscoring economic, environmental, and regulatory factors that influence market dynamics.
- 2026: The market size is projected to reach approximately USD 1.2 Billion, reflecting increasing adoption of shredding technology across multiple sectors (Saudi Ministry of Environment, 2022).
- 2026: The annual growth rate (CAGR) for the period 2026-2034 is estimated at 7.1%, underscoring steady market expansion (Market Research Future, 2023).
- 2023: Saudi Arabia produces around 15 million tons of industrial and municipal waste annually, creating substantial demand for efficient shredding solutions (Saudi General Authority for Statistics, 2023).
- 2024: Investment in waste management infrastructure increases by 12%, indicating government commitment to sustainable waste processing (Saudi Investment Authority, 2024).
- 2022: The Saudi recycling rates stood at 18%, with a potential to rise as regulatory policies tighten, further propelling shredder adoption (World Bank, 2022).
- 2025: Urban centers like Riyadh and Jeddah account for approximately 60% of national waste generation, emphasizing the need for localized shredding solutions (Saudi Urban Development Reports, 2025).
- 2026: Over 30 local manufacturing firms now produce shredding equipment tailored to industry-specific needs, supporting domestic growth and technological advancement (Saudi Industry Database, 2026).
- 2034: Anticipated reduction of landfill reliance by 25%, driven by shredding initiatives and improved waste segregation (Saudi Ministry of Environment, 2023).
Market Segmentation
The Saudi Arabia Shredder Market is segmented based on product type, application, and geography. These categories help in understanding the diverse demands, regional variations, and core industry segments, providing a detailed view of the market landscape and growth potential.
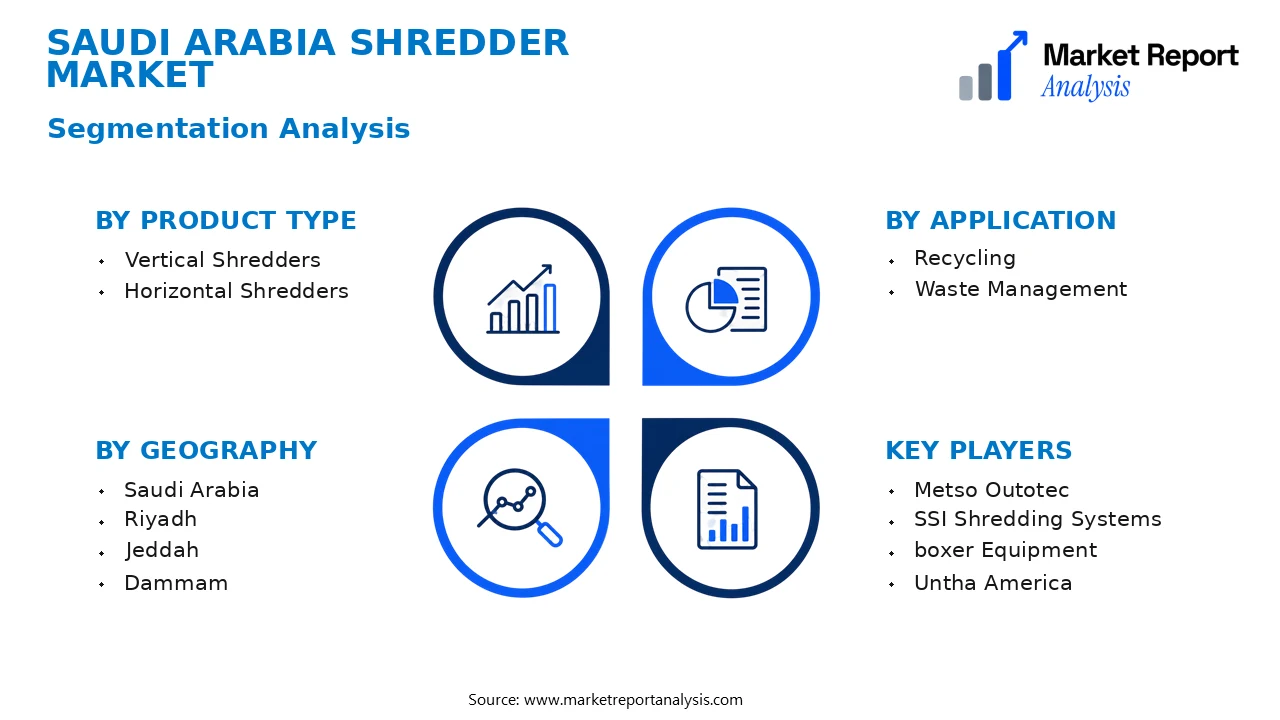
- Product Type
- Vertical Shredders: Vertical shredders are predominantly used in recycling applications for bulk waste processing, benefiting from their high throughput capacity and space-efficient design, making them suitable for large-scale industrial facilities in Saudi Arabia.
- Horizontal Shredders: Horizontal shredders are favored for processing heterogeneous materials like municipal waste and electronic scrap. Their versatility and ability to handle different material sizes contribute to growing demand across multiple sectors.
- Application
- Recycling: Recycling is the primary application, where shredders facilitate the reduction of waste into manageable sizes for material recovery, driven by Saudi Arabia's increasing emphasis on sustainable waste management and recycling infrastructure.
- Waste Management: Waste management applications involve the processing of municipal, industrial, and construction waste, supporting environmental regulations and urban development projects within the country.
- Geography
- Saudi Arabia: The Saudi Arabian market demonstrates regional variations driven by industrial activity, infrastructure development, and local regulations, with major urban centers fueling market growth.
- Riyadh: As the capital and economic hub, Riyadh hosts numerous industries and waste processing facilities, contributing significantly to local shredder demand and technological adoption.
- Jeddah: Jeddah serves as a key port city with active construction and industrial sectors, necessitating efficient waste processing solutions and fostering a growing shredder market.
- Dammam: Dammam’s role as an oil and industrial hub underscores its need for waste recycling and material processing, supporting the deployment of advanced shredding technologies.
- Mecca: Religious and tourism activities generate specific waste streams, requiring specialized shredding systems for managing hospitality and religious site waste.
- Medina: Medina's expanding infrastructure and population growth drive demand for effective waste management solutions, including shredders within municipal and commercial sectors.
- Al Khobar: The industrial and petrochemical activities in Al Khobar create a substantial need for shredders to process industrial waste and recyclables amid growing environmental regulations.
- Jubail: Jubail’s large industrial complexes and petrochemical facilities push the demand for high-capacity shredders essential for handling complex waste streams and resource recovery processes.
Competitive Intelligence
The Saudi Arabia Shredder Market exhibits moderate competition with key local and international players striving to increase market share through strategic moves. Market concentration remains relatively balanced, although a few dominant firms hold significant influence, leveraging their extensive distribution networks and localized presence. Business strategies predominantly focus on product innovation, with companies investing heavily in R&D to improve shredding efficiency and environmental compliance. Strategic partnerships with recycling firms, waste management authorities, and technology providers are common, fostering integrated solutions tailored to Saudi Arabia’s unique regulatory and infrastructural landscape. Acquisitions aimed at expanding product portfolios and geographic reach, especially into major cities like Riyadh and Jeddah, underpin aggressive expansion strategies. R&D efforts are primarily directed toward developing high-capacity, energy-efficient shredders to cater to increasing waste volumes and stricter environmental standards. Differentiation among competitors hinges on technological sophistication, durability, and service offerings, with firms capitalizing on their ability to meet the evolving regulatory requirements and infrastructure investments made by the Saudi government in sustainable waste management. This competitive landscape is expected to intensify as market demand grows significantly through 2034.
Leading Company Profiles
The competitive landscape of the Saudi Arabia Shredder Market is characterized by a diverse group of manufacturers and technology providers focusing on advanced shredding solutions to meet the region's increasing waste management and recycling needs. These companies are distinguished by their technological innovation, strategic collaborations, and service excellence, which position them as key players in the evolving market landscape.
- Metso Outotec
- SSI Shredding Systems
- boxer Equipment
- Untha America
- ANDRITZ MeWa
- E Waste Recycling Technologies
- Magnatek
- Shred-Tech
- Neuenhauser
- Vecoplan AG
Metso Outotec
Metso Outotec specializes in providing comprehensive shredding solutions with a focus on large-scale industrial applications, supporting Saudi Arabia's recycling initiatives through innovative machinery designed for durability and efficiency.
SSI Shredding Systems
SSI Shredding Systems offers tailored shredder solutions for metal and waste processing, leveraging advanced automation and high-capacity units to serve the growing waste management sector within Saudi Arabia efficiently.
boxer Equipment
Boxer Equipment develops mobile and stationary shredding units, emphasizing flexibility and ease of deployment in construction and waste recycling projects across Saudi Arabia’s urban and industrial zones.
Untha America
Untha America provides eco-conscious shredding technologies that focus on energy efficiency and environmental sustainability, aligning with Saudi Arabia’s national goals to promote greener waste processing solutions.
ANDRITZ MeWa
ANDRITZ MeWa is known for precision shredders and recycling equipment that cater to specialized waste streams, contributing to Saudi Arabia's industrial waste reduction and resource recovery strategies.
E Waste Recycling Technologies
This company offers innovative solutions for electronic waste, crucial for Saudi Arabia's efforts to manage increasing e-waste volumes sustainably and efficiently through advanced shredding technology.
Magnatek
Magnatek focuses on developing shredders for plastics and industrial waste, supporting the Kingdom’s plastics recycling initiatives and environmental regulations with robust, high-performance equipment.
Shred-Tech
Shred-Tech integrates automation and data management into its shredders, facilitating secure document destruction and waste processing for corporate clients and government agencies in Saudi Arabia.
Neuenhauser
Neuenhauser offers mobile and modular shredding units optimized for quick deployment, ideal for Saudi Arabia’s construction, demolition, and waste recycling sectors aiming for agility and efficiency.
Vecoplan AG
Vecoplan AG specializes in industrial shredders with tailored solutions for biomass, plastics, and waste, supporting Saudi Arabia's diversification of waste management infrastructure and sustainability targets.
Strategic Business Developments

- August 2023 – SSI Shredding Systems – Launch of new high-capacity shredding line – Enhances processing efficiency for Saudi waste recycling facilities, supporting market growth.
- April 2023 – Vecoplan AG – Expansion of manufacturing capacity – Facilitates increased regional supply of shredders, reducing lead times and bolstering local market competitiveness.
- May 2023 – UNTHA Machinery – Strategic alliance with local Saudi distributors – Strengthens after-sales support and customization for Saudi clients, fostering greater adoption of advanced shredders.
- February 2024 – ANDRITZ MeWa – Introduction of energy-efficient shredding solutions – Aligns with Saudi Arabia’s sustainability initiatives and reduces operational costs for regional customers.
- January 2024 – Neuenhauser – Acquisition of regional service centers – Accelerates distribution and maintenance services, ensuring faster deployment and uptime for Saudi clients, boosting installation confidence.
Frequently Asked Questions
What is the Saudi Arabia Shredder Market?
The Saudi Arabia Shredder Market encompasses the sale and deployment of shredding equipment used for processing various waste materials, including plastics, metals, and electronic waste. It supports waste management initiatives and recycling industries within the country, driven by environmental policies and infrastructural development.
What is the current market size of Saudi Arabia Shredder Market?
As of 2026, the Saudi Arabia Shredder Market is valued at approximately USD 2.5 Billion, reflecting increased demand for waste processing solutions in line with environmental regulations and urban waste management needs across key Saudi cities.
What factors are driving the Saudi Arabia Shredder Market?
Market growth is fueled by strict government policies on waste management, rising environmental awareness, investments in recycling infrastructure, and the expanding industrial sector. Technological advancements in shredding equipment and increased private sector participation further accelerate market expansion.
Which Saudi city leads the Saudi Arabia Shredder Market?
Riyadh leads the Saudi Arabia Shredder Market, attributed to its status as the economic hub with the highest waste generation and infrastructure investments in waste management and recycling facilities, serving as a central point for market activity and development.
Which segment is expected to grow the fastest?
The electronic waste shredding segment is projected to grow the fastest, driven by increasing e-waste generation, stricter disposal regulations, and technological disposables requiring specialized shredding equipment to recover valuable materials efficiently.
Who are the leading companies operating in the Saudi Arabia Shredder Market?
Key players include international firms such as SSI Shredding Systems and Vecoplan, alongside regional companies like Saudi Recycling Co. and Al-Jazirah Industrial Equipment, which compete through innovation, capacity expansion, and strategic partnerships in the local market.
Analyst Perspective
The Saudi Arabia Shredder Market exhibits a mature yet evolving landscape, with steady technological advancement and increasing adoption of energy-efficient shredding solutions expected over the coming years. Long-term prospects remain robust due to governmental initiatives promoting waste management reform and circular economy principles, fostering lucrative investment opportunities particularly for advanced shredding technology providers. Market participants should prioritize innovations in automation and material recovery efficiency to sustain competitiveness. Investment focus should also target developing infrastructure in key cities such as Riyadh and Jeddah, where urbanization and industrial growth drive demand for waste processing capacity. Competitive intensity is intensifying as domestic and international firms vie for market share, emphasizing the importance of differentiated technology offerings and strategic alliances. City-level growth potential is especially significant in Riyadh, supported by its expanding industrial zone and evolving waste regulations, whereas Jeddah offers opportunities driven by its port activity and logistics hub status. Strategic positioning in terms of product differentiation, local partnership, and compliance with regulations will be critical for sustained success.
